
 Chiplet Technology Market | 2026-2036
Chiplet Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Chiplet Technology Market Insights
Platform licensing revenue is narrowing as a margin pool as semiconductor firms shift value capture toward in-house heterogeneous integration capabilities. Intel Corporation leverages its Foveros 3D stacking technology to control advanced packaging architectures internally. AMD anchors its competitive stance through chiplet-centric CPU and GPU designs that reduce silicon waste. TSMC dominates outsourced chiplet assembly with its CoWoS and InFO interconnect platforms serving fabless customers.
Chiplet technology refers to the disaggregation of monolithic system-on-chip designs into smaller, functionally specialized die that communicate through standardized interconnects such as the Universal Chiplet Interconnect Express protocol, enabling heterogeneous integration of dies from different process nodes onto a single package. Processor chiplets occupy the dominant revenue position as CPU and GPU vendors decompose compute engines into modular tiles. Memory chiplets represent the fastest-expanding segment as high-bandwidth memory stacks integrate directly beside logic dies in AI accelerators. Interconnect platforms concentrate margin pools through proprietary standards and packaging IP licensing.
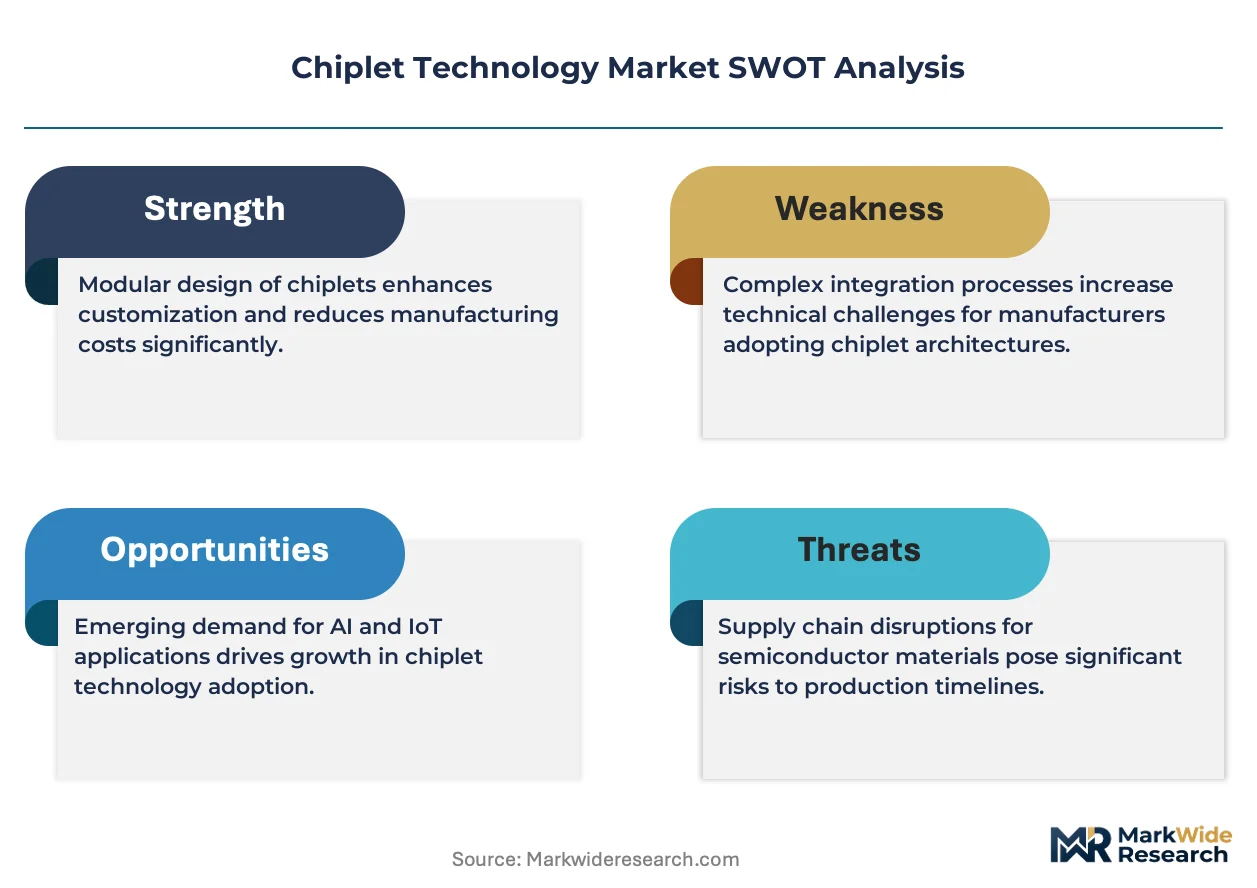
The U.S. CHIPS and Science Act directs EPA and Department of Commerce oversight toward domestic advanced packaging facility permitting, reshaping where chiplet assembly capacity locates. The EU Chips Act imposes REACH chemical compliance and CE marking requirements on European-based packaging materials and processes, affecting substrate and die-attach supply chains. China's GB standards and MIIT dual carbon goals constrain imported packaging equipment while promoting local heterogeneous integration capabilities. Stakeholders must monitor which interconnect standards achieve ecosystem lock-in versus open consortium adoption.
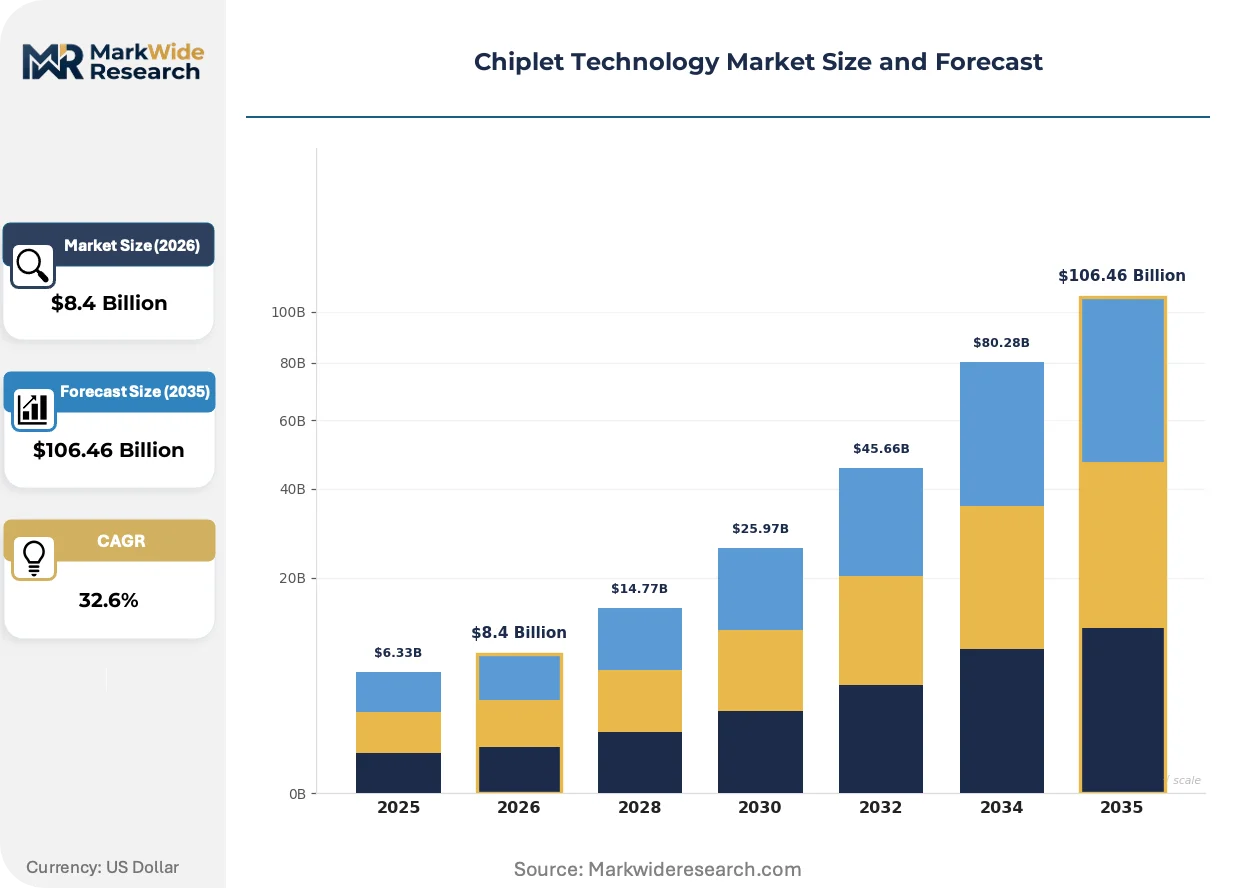
Market Dynamics
Heterogeneous integration architectures are forcing a structural reconfiguration of semiconductor value chains, as disaggregated die assembly displaces monolithic fabrication economics and reskills capital deployment toward advanced packaging capacity.
Growth Catalysts
- AI Inference Workloads:Data center operators deploy chiplet-based accelerators to optimize thermal performance and yield economics at advanced nodes.
- U.S. CHIPS and Science Act:EPA and Department of Commerce permitting reforms accelerate domestic advanced packaging facility construction timelines.
- Universal Chiplet Interconnect Express:Standardized die-to-die protocols reduce ecosystem fragmentation and lower barrier-to-entry for fabless designers.
Market Restraints
- Substrate Supply Concentration:ABF substrate fabrication clusters in Taiwan and Japan, creating single-source vulnerability for high-layer-count packages.
- Die-Attach Material Costs:Silver sinter paste and thermal interface materials face price volatility tied to precious metal commodity markets.
- Interconnect IP Licensing:Proprietary packaging standards from dominant foundries extract recurring royalties that compress fabless margins.
Strategic Opportunities
- Automotive Functional Safety:ISO 26262-certified chiplets enable zonal architecture adoption in electric vehicle compute platforms.
- European Packaging Sovereignty:EU Chips Act subsidies attract heterogeneous integration investment to Dresden and Grenoble clusters.
- Photonics-Electronics Convergence:Co-packaged optics chiplets address bandwidth-density constraints in AI training clusters.
Industry Challenges
- Multiphysics Simulation Talent:Chiplet design requires concurrent thermal-electrical-mechanical modeling expertise that remains scarce across the workforce.
- Known-Good-Die Testing:Pre-assembly die validation protocols extend qualification timelines and raise capital intensity for test equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chiplet Technology Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $106.46 Billion |
| CAGR (2026 – 2036) | 32.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processor Chiplets, Memory Chiplets, I/O Chiplets, Application-Specific Chiplets End User: Consumer Electronics, Telecommunications, Automotive, Data Centers Technology: 3D Stacking, Heterogeneous Integration, Modular Design, Interconnect Platforms Application: AI Inference, High-Performance Computing, Edge Computing, Cloud Services |
| Companies Covered | Intel Corporation, Advanced Micro Devices, Inc. (AMD), TSMC (Taiwan Semiconductor Manufacturing Company), NVIDIA Corporation, Samsung Electronics Co., Ltd., Marvell Technology, Inc., IBM Corporation, Apple Inc., MediaTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chiplet Technology Market Trends and Innovations
Active developments across interconnect protocols, sovereign capacity buildout, and procurement restructuring are compressing traditional competitive moats while opening asymmetric entry points for specialized packaging houses.
Hybrid bonding technology is collapsing the pitch limitations of conventional microbump interconnects, enabling sub-10 micron die-to-die spacing that preserves signal integrity at reduced power. Memory vendors and AI accelerator designers are accelerating adoption for high-bandwidth memory integration. The structural consequence is collapsing the historical separation between logic and memory process nodes, allowing optimal-node selection per function.
REACH chemical compliance and CE marking requirements under the EU Chips Act are reshaping substrate material qualification protocols for European-based packaging facilities. ECHA oversight of die-attach chemistries and molding compounds is extending supplier certification cycles. Advanced substrate vendors are responding by regionalizing formulation development to avoid cross-border regulatory friction.
Buyer concentration among hyperscale cloud operators is compressing procurement cycles and forcing packaging houses to absorb inventory risk through consignment die models. Traditional fabless-vendor relationships are giving way to direct foundry-packaging partnerships negotiated by cloud hardware teams. This restructuring is most visible in Taiwan's Hsinchu corridor, where TSMC CoWoS capacity allocation now hinges on direct cloud provider commitments rather than traditional semiconductor distributor channels.
Chiplet Technology Market Segmentation
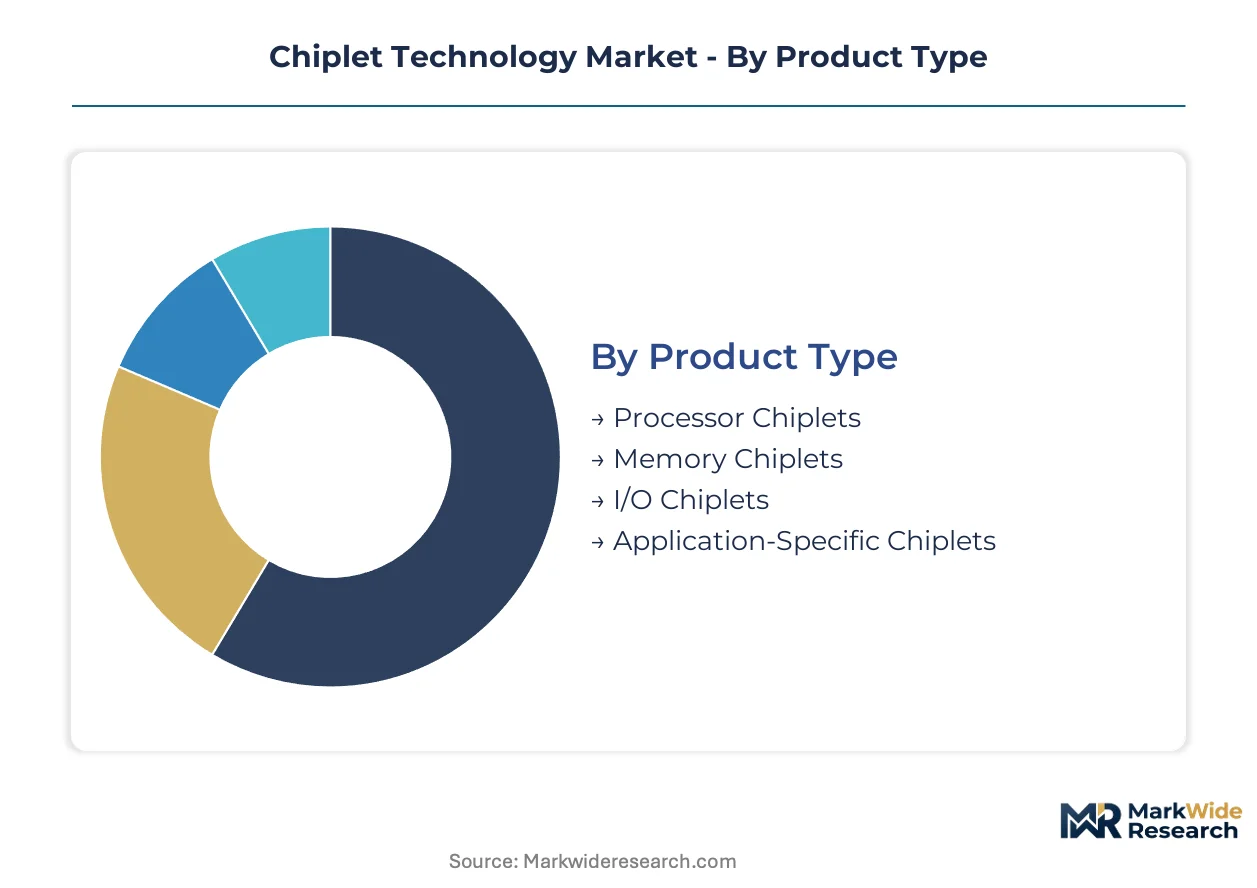
Chiplet disaggregation fragments monolithic silicon economics across multiple technical and commercial dimensions. Each segmentation axis reveals distinct margin pools, capacity constraints, and ecosystem dependencies that reshape procurement and partnership structures.
Product Type:
Cost tier differentiation across die functions determines where heterogeneous integration delivers yield economics versus where monolithic alternatives retain advantage.
- Processor Chiplets:Modular CPU and GPU tiles fabricated at leading-edge nodes enable node-specific optimization per compute function. Data center AI accelerators concentrate demand as hyperscalers decompose training and inference engines into specialized tiles to improve defect-limited yields at 3nm-class geometries.
- Memory Chiplets:High-bandwidth memory stacks integrate through silicon vias adjacent to logic dies, collapsing the historical physical separation between DRAM and processor packages. AI training clusters in Taiwan's Hsinchu corridor anchor demand as bandwidth-per-watt constraints dominate accelerator architecture decisions.
- I/O Chiplets:Peripheral interface dies fabricated at mature nodes handle SerDes, PCIe, and networking protocols.
- Application-Specific Chiplets:Custom accelerators for cryptography, signal processing, or sensor fusion target defense and aerospace qualification requirements.
Processor chiplets hold installed capacity. Memory chiplets are rotating up the share rankings.
End User:
Application-specific reliability and thermal requirements segment the customer base across divergent certification and procurement protocols.
- Data Centers:Hyperscale operators drive CoWoS capacity allocation through direct foundry negotiations rather than traditional semiconductor distribution. Thermal design power constraints above 700W per accelerator package force liquid cooling integration and substrate material selection tradeoffs.
- Automotive:ISO 26262 functional safety certification and AEC-Q100 temperature grading impose qualification timelines that stretch 18-24 months for zonal compute chiplets. Electric vehicle platforms in Germany's Baden-Württemberg cluster anchor initial deployment as zonal E/E architectures displace distributed ECU designs.
- Telecommunications:Baseband processing and radio frequency front-end disaggregation targets Open RAN interoperability requirements.
- Consumer Electronics:Smartphone application processors and wearable compute modules prioritize package thickness and power efficiency over raw interconnect bandwidth.
Data centers command volume premiums. Automotive is climbing the fastest on qualification-driven contract structures.
Technology:
Interconnect pitch and bonding methodology segment the technical landscape across thermal, electrical, and mechanical performance thresholds.
- 3D Stacking:Hybrid bonding and microbump architectures collapse die-to-die spacing below 10 microns, preserving signal integrity at reduced power consumption. Memory-logic integration for AI accelerators concentrates adoption as HBM3E stack heights test package warpage limits.
- Heterogeneous Integration:Multi-die assembly combining logic, memory, and analog functions from divergent process nodes onto single substrates. U.S. CHIPS Act subsidies for domestic advanced packaging facilities redirect capacity investment toward Arizona and New York heterogeneous integration clusters.
- Modular Design:Standardized die footprints and interconnect protocols enable second-source supply and inventory risk distribution.
- Interconnect Platforms:Proprietary CoWoS, InFO, and EMIB standards versus emerging UCIe open consortium specifications.
3D stacking holds installed capacity. Heterogeneous integration is gaining share fastest on sovereign capacity buildout.
Application:
Compute intensity and latency tolerance segment deployment architectures across cloud, edge, and device-local processing tiers.
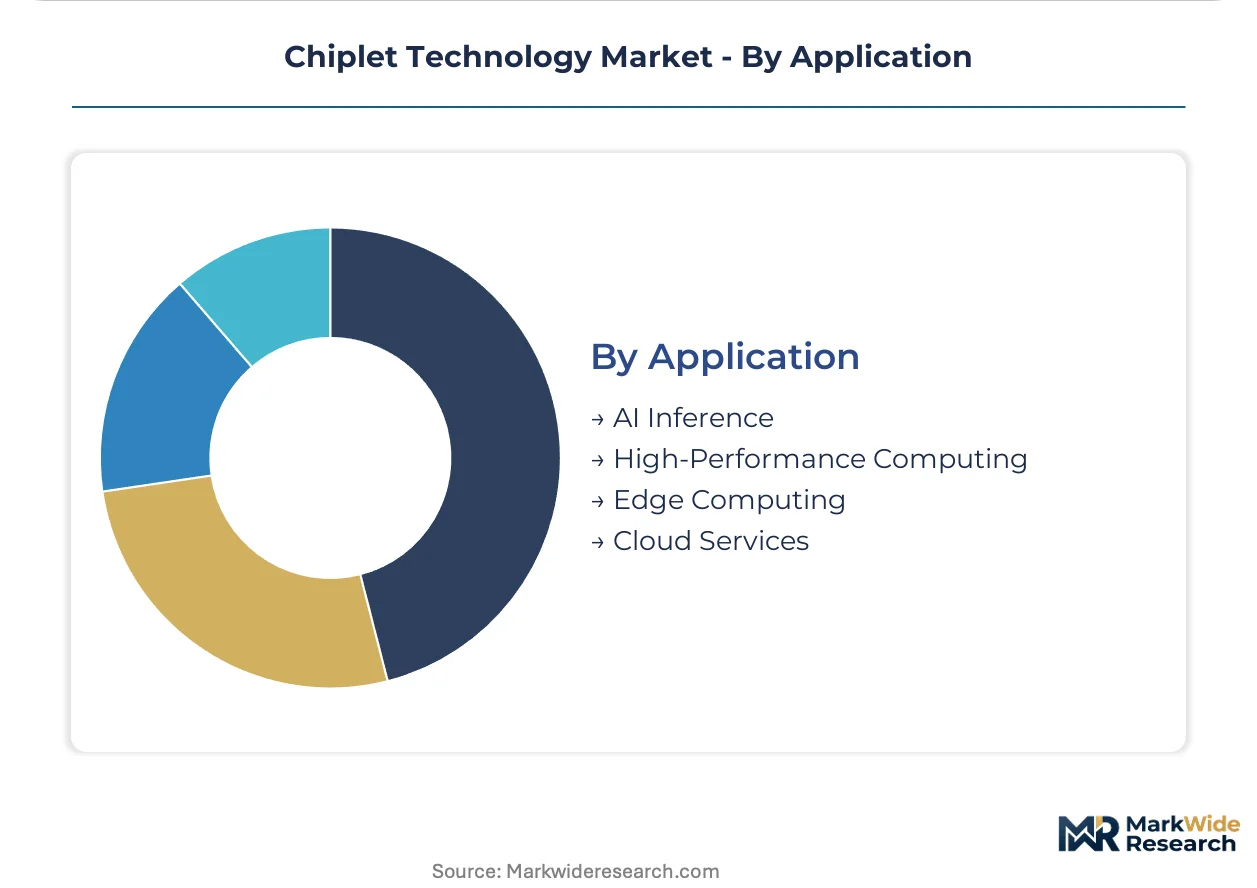
- AI Inference:Low-latency, high-throughput acceleration for production model serving dominates CoWoS capacity allocation. Batch size optimization and KV-cache memory bandwidth requirements drive HBM3 integration decisions in Taiwan and South Korea packaging facilities.
- High-Performance Computing:Exascale system interconnect bandwidth and MPI collective operation latency constraints favor 3D stacking for CPU-GPU memory coherence. U.S. Department of Energy procurement timelines anchor demand through Aurora and El Capitan system deployments.
- Edge Computing:Factory automation and retail vision systems balance inference throughput against 15-75W thermal envelopes.
- Cloud Services:General-purpose compute and storage disaggregation targets total cost of ownership optimization through yield recovery.
AI inference holds installed capacity. High-performance computing is rotating up the share rankings on exascale procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Data center operators in the United States prioritize AI inference throughput and liquid-cooled packaging, while East Asian manufacturing clusters emphasize heterogeneous integration yield economics and sovereign capacity security.
United States
Hyperscale cloud operators drive CoWoS demand through direct foundry negotiations. EPA and Department of Commerce permitting reforms under the CHIPS Act accelerate domestic advanced packaging facility construction timelines. Arizona's Phoenix metro anchors heterogeneous integration investment as Intel and TSMC expand substrate-level assembly capacity.
Taiwan
TSMC's CoWoS and InFO platforms dominate outsourced chiplet assembly for fabless AI accelerator designers. MIIT dual carbon goals in neighboring China indirectly concentrate premium packaging demand in Hsinchu Science Park. The Hsinchu corridor now allocates capacity based on direct cloud provider commitments rather than traditional semiconductor distribution channels.
South Korea
Memory vendors accelerate HBM3E stack integration beside logic dies for AI training clusters. MFDS semiconductor material regulations shape die-attach chemistry qualification protocols. Seoul's Pangyo Techno Valley anchors memory-logic convergence R&D as Samsung Electronics expands hybrid bonding pilot lines.
Japan
ABF substrate fabrication concentrates in Nagoya and Tokyo industrial corridors, creating supply vulnerability for high-layer-count packages. METI semiconductor revitalization subsidies redirect capital toward advanced packaging equipment localization. Yokohama's Kanagawa cluster hosts substrate material formulation development to avoid cross-border regulatory friction.
Germany
Automotive zonal compute architectures drive ISO 26262-certified chiplet qualification demand. ECHA REACH compliance and CE marking requirements reshape substrate material protocols for Dresden packaging facilities. Baden-Württemberg's Stuttgart region anchors electric vehicle platform deployment as Bosch and Infineon expand heterogeneous integration partnerships.
Chiplet Technology Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player categories: integrated device manufacturers controlling proprietary packaging architectures, pure-play foundries dominating outsourced assembly, and fabless designers capturing value through chiplet-centric product roadmaps. Strategic moves center on backward integration into substrate fabrication and capacity reservation agreements with cloud hardware procurement teams.
Within the integrated-manufacturer tier, Intel Corporation and Samsung Electronics Co., Ltd. exemplify captive packaging strategies that internalize heterogeneous integration margins. TSMC (Taiwan Semiconductor Manufacturing Company) anchors the foundry-centric archetype through CoWoS capacity allocation dominance. Advanced Micro Devices, Inc. (AMD) occupies a position as the fabless reference point for chiplet-native CPU and GPU architectures that reduce silicon waste through modular tile designs.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices, Inc. (AMD) |
| TSMC (Taiwan Semiconductor Manufacturing Company) |
| NVIDIA Corporation |
| Samsung Electronics Co., Ltd. |
| Marvell Technology, Inc. |
| IBM Corporation |
| Apple Inc. |
| MediaTek Inc. |
| Others |
Pricing and Supply Chain Analysis
The Kaohsiung-to-Long Beach transpacific container corridor anchors chiplet logistics cost dynamics, where freight rate volatility amplifies pricing power for Taiwan-based packaging houses while compressing margins for fabless designers sourcing CoWoS capacity through spot allocation mechanisms.
Pricing Analysis
Long-term offtake agreements dominate high-volume procurement as hyperscale cloud operators secure CoWoS slots through multi-year capacity reservations with TSMC. Price differentiation rests on interconnect complexity tier and thermal performance grade, with liquid-cooled packages commanding premiums over air-cooled alternatives. Cost compression in standard-tier packaging intensifies as second-source substrate vendors enter qualification cycles. Automotive OEMs exhibit highest price sensitivity due to extended ISO 26262 certification timelines, while AI accelerator designers prioritize performance over unit economics.
Supply Chain Analysis
TSMC, Intel, and Samsung Electronics hold captive advanced packaging capacity that shapes global supply availability. Raw material flows concentrate in Taiwan for ABF substrates, Japan for die-attach chemistries, and South Korea for HBM3E stacks. Single-source vulnerability in high-layer-count substrate fabrication exposes the supply chain to geographic concentration risk. Distribution runs through direct foundry-packaging partnerships negotiated by cloud hardware procurement teams, displacing traditional semiconductor distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chiplet technology markets are approaching a platform-economics inflection as UCIe standardization erodes proprietary interconnect lock-in and redistributes value capture toward ecosystem orchestrators.
For Market Incumbents: Build captive substrate fabrication capabilities to secure margin pools threatened by ABF supply concentration in Taiwan and Japan. Intel and TSMC should accelerate Arizona and Dresden heterogeneous integration capacity to capture U.S. CHIPS Act subsidies before qualification timelines extend. Defensive positioning requires backward integration into die-attach material formulation to offset silver sinter paste commodity volatility. For New Entrants and Emerging Players: Establish a beachhead in automotive zonal compute architectures where ISO 26262 certification barriers extend incumbent lead times and create entry windows. Photonics-electronics convergence for co-packaged optics in AI training clusters represents underpenetrated white space with asymmetric technical requirements. Go-to-market execution should target direct partnerships with European automotive Tier 1s in Baden-Württemberg bypassing traditional foundry channels. For Investors and Strategic Acquirers: Specialized packaging houses with hybrid bonding pilot lines and MIIT-compliant China capacity represent priority acquisition archetypes as sovereign packaging mandates proliferate. Long-term viability hinges on interoperability standard adoption curves rather than proprietary IP depth. Monitor UCIe consortium membership expansion rates as the signal indicating ecosystem lock-in versus open architecture inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Sub-10 micron pitch capability secures HBM3E integration slots for AI accelerators. |
| UCIe Standard Certification | Open interconnect protocol adoption reduces ecosystem fragmentation for fabless designers. |
| Domestic Packaging Facility Buildout | U.S. CHIPS Act subsidies redirect assembly capacity toward Arizona and New York clusters. |
| Automotive Functional Safety Qualification | ISO 26262 certification enables zonal E/E architecture penetration in electric vehicles. |
| Co-Packaged Optics Integration | Photonics-electronics convergence addresses bandwidth-density constraints in exascale systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging process engineers, fabless semiconductor procurement directors, cloud hardware platform architects, and substrate material formulation specialists. Secondary validation drew from SEC 10-K filings, EPA permitting databases, ECHA REACH substance registrations, and TSMC technology symposium disclosures. Bottom-up capacity modeling triangulated against top-down semiconductor capital expenditure tracking.
Calibration against historical CoWoS capacity allocation cycles and HBM3E stack yield learning curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include interconnect platform type, end-use application tier, thermal design power envelope, and regional regulatory cluster. CAGRs were derived from supply-demand balance modeling incorporating foundry expansion timelines and hyperscaler procurement cycle phasing.
Stress conditions across substrate supply disruption, UCIe adoption velocity, and automotive qualification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of foundry capacity allocation announcements and consortium standard ratification milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Car Chip Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Airbag Chip Market