
 Integrated Graphics Chipset Market | 2026-2036
Integrated Graphics Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Graphics Chipset Market Foresight
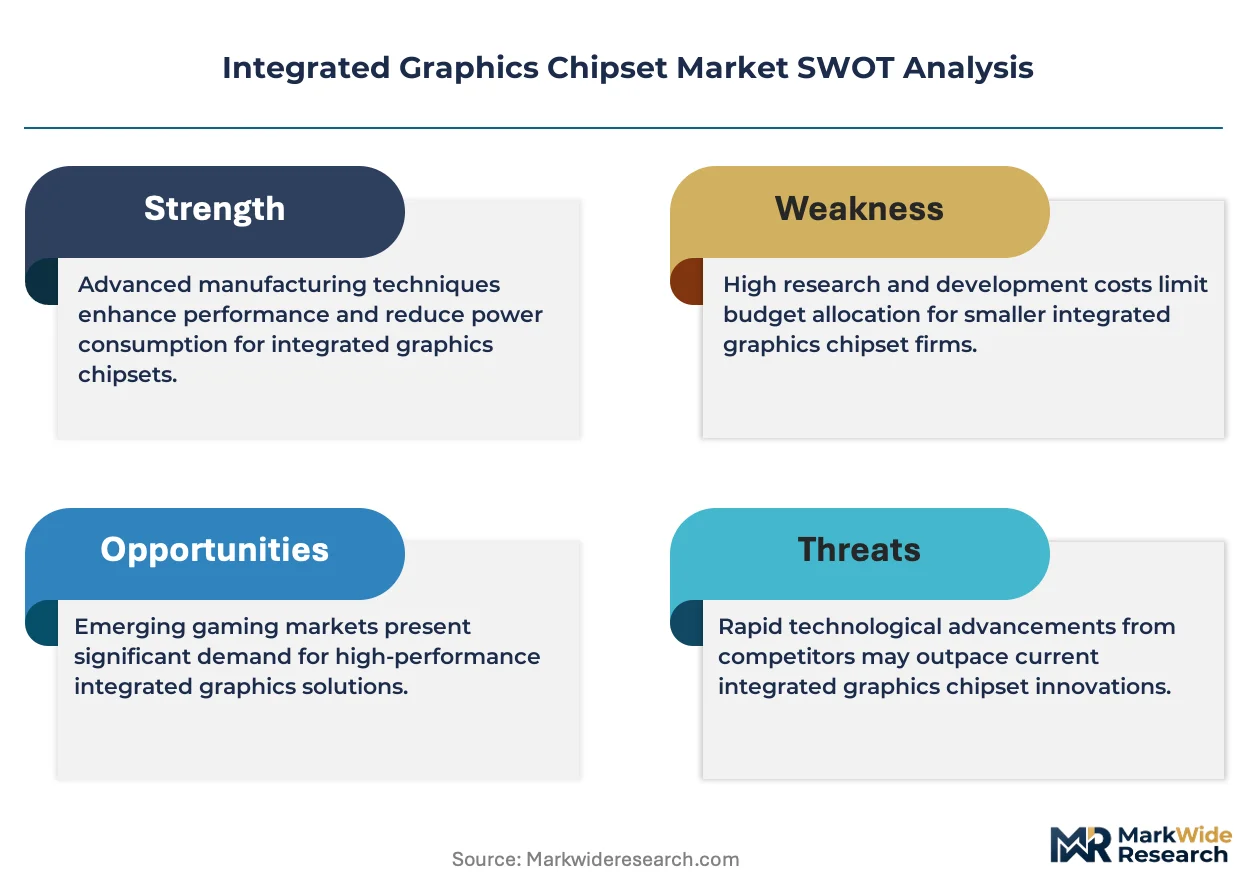
Foundry capacity expansion in Taiwan is realigning supply availability for integrated graphics die production. Intel Corporation leverages its IDM 2.0 strategy to sustain captive wafer supply for Core processor-integrated GPUs. Advanced Micro Devices anchors its Ryzen APU portfolio with Zen CPU and RDNA graphics convergence on a single monolithic die. NVIDIA Corporation competes primarily in the discrete segment but extends licensing architectures into ARM-based integrated solutions for automotive and data center adjacencies.
An integrated graphics chipset combines a graphics processing unit with the central processor or system chipset on a shared silicon die, typically manufactured at 7nm to 4nm process nodes with shared memory architecture drawing from system DRAM rather than dedicated GDDR. This integration reduces bill-of-materials cost and power consumption for volume PC, mobile, and embedded applications where visual output suffices without discrete GPU expenditure. The integrated graphics segment retains dominant shipment volumes across consumer laptops and entry-level desktops, while hybrid graphics architectures capture premium mobile workstation transitions where software dynamically switches between integrated and discrete engines. GPU technology as a category commands the largest installed base, though APU configurations represent the fastest-growing silicon category as AMD and Intel converge compute and graphics on unified dies.
The US FCC governs electromagnetic emissions standards that constrain PCB layout and thermal design for integrated graphics implementations in consumer electronics. The EU REACH regulation and RoHS directive restrict hazardous substances in semiconductor packaging materials, directly affecting substrate and solder bump compositions for graphics die attach. China's MIIT enforces domestic cybersecurity review protocols for processors deployed in government and critical infrastructure procurement. Stakeholders must monitor how divergent efficiency mandates and silicon sovereignty programs reshape foundry allocation and certification requirements across major demand jurisdictions.
Market Dynamics
Foundry allocation for integrated graphics die production is compressing as Taiwan Semiconductor Manufacturing Company prioritizes advanced AI accelerator wafers over mature-node APU contracts, forcing Intel and AMD to recalibrate captive fab utilization and external foundry commitments.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandated standby power ceilings below 0.5 watts for computing equipment are accelerating low-power integrated graphics adoption in corporate thin-client refresh cycles across Germany and France.
- Edge AI inference workloads:Computer vision applications in retail self-checkout and industrial quality inspection are displacing discrete GPUs with RDNA3-integrated APUs that deliver sufficient INT8 throughput at fractionally lower thermal design power.
- China's MIIT domestic procurement mandates:Government and state-owned enterprise PC tenders now require processors with indigenous integrated graphics, channeling motherboard ecosystem demand toward Loongson and Zhaoxin x86-compatible designs.
Market Restraints
- Memory bandwidth ceiling:Shared DDR5 system memory architectures cap integrated graphics performance below 100 GB/s, constraining 4K gaming and professional visualization workloads that GDDR6-equipped discrete GPUs serve without contention.
- TSMC N6 and N4 node allocation:Leading-edge foundry capacity concentration in Hsinchu and Taichung creates supply vulnerability for AMD Ryzen APU ramp schedules when AI training chip orders absorb available 5nm-class wafer starts.
- US BIS advanced packaging restrictions:Export controls on high-bandwidth memory interposers complicate integrated graphics evolution toward chiplet-based designs that would otherwise merge logic and memory stacks for bandwidth expansion.
Strategic Opportunities
- Automotive digital cockpit consolidation:ARM-based SoC designs licensed from Imagination Technologies and ARM Mali are electrifying integrated graphics penetration into tier-one supplier programs for Mercedes-Benz and BMW instrument cluster integration.
- India's PLI scheme for semiconductor assembly:Modified incentive structures covering display driver and integrated die packaging are attracting OSAT investment in Gujarat and Tamil Nadu for cost-optimized APU module production serving domestic laptop brands.
- Hybrid graphics firmware optimization:Microsoft DirectX 12 Ultimate Variable Rate Shading APIs are enabling software-defined switching between Intel Xe integrated and discrete Arc GPUs, creating premium laptop configurations without full discrete GPU bill-of-materials burden.
Industry Challenges
- Physical design talent scarcity:Deep-submicron GPU floorplanning expertise concentrates among senior engineers at Intel Hillsboro and AMD Austin, constraining fabless entrants from achieving competitive power-performance-area metrics on contracted foundry processes.
- Cross-vendor driver certification timelines:ISV validation for Autodesk Maya and Siemens NX professional visualization suites extends 18-24 months for new integrated graphics architectures, delaying enterprise workstation adoption despite silicon readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Graphics Chipset Market |
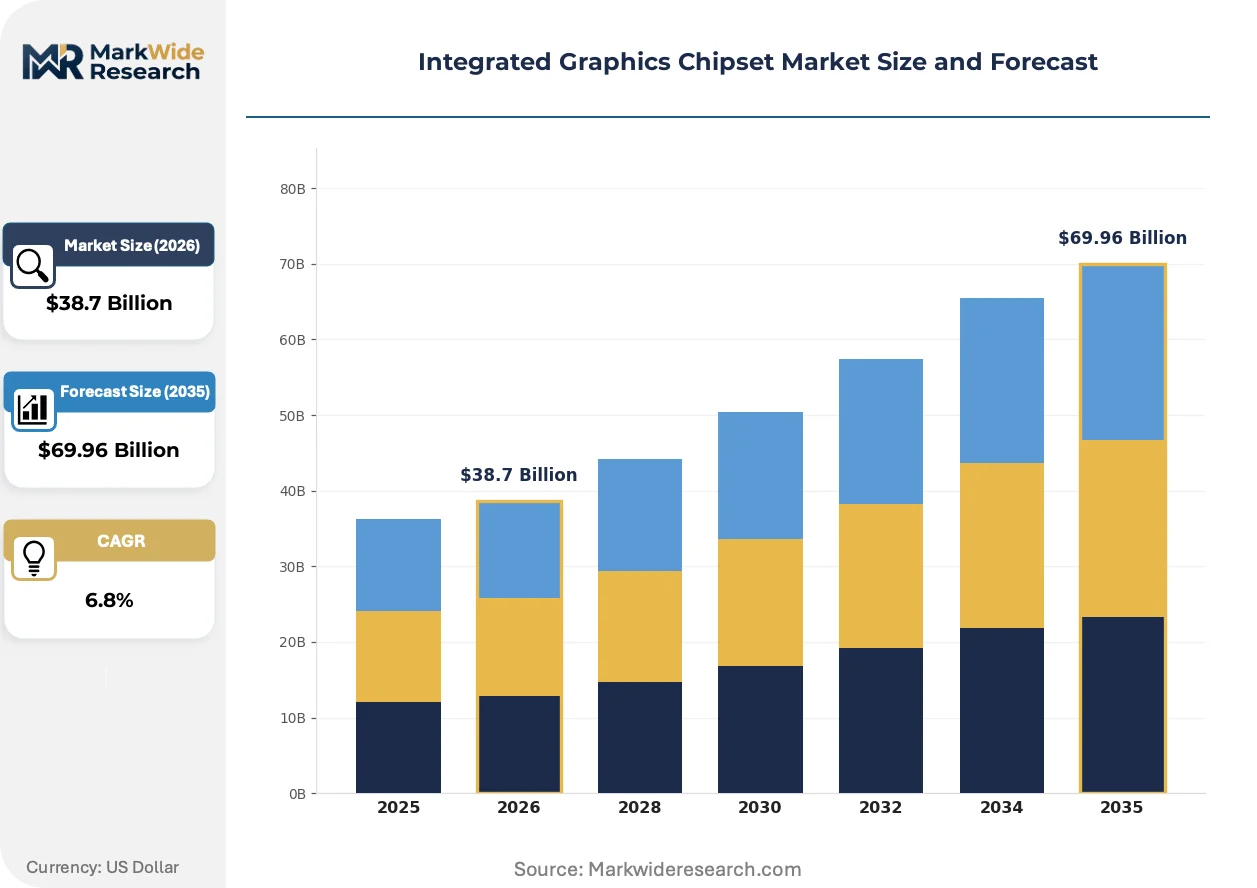
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Graphics, Integrated Graphics, Hybrid Graphics, Mobile Graphics End User: Gaming, Professional Workstations, Consumer Electronics, Automotive Technology: GPUs, APUs, Ray Tracing, Virtual Reality Application: Machine Learning, Video Editing, CAD, Gaming Consoles |
| Companies Covered | Intel Corporation, Advanced Micro Devices, Apple Inc., NVIDIA Corporation, Qualcomm, MediaTek, Samsung, Imagination Technologies, VIA Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Graphics Chipset Market Shifts & Advancements
Chiplet disaggregation is fragmenting monolithic APU architectures into separate compute and graphics tiles interconnected through proprietary die-to-die interfaces, enabling process-node optimization and yield recovery while complicating thermal and power delivery design.
Unified memory architectures that pool system DRAM between CPU and GPU through hardware-managed cache coherency are electrifying integrated graphics responsiveness for browser-based 3D rendering and light content creation. Chromebook and entry-level Windows laptop OEMs in Taiwan and Vietnam are adopting AMD Phoenix and Intel Meteor Lake designs that expose 16GB+ shared memory pools to graphics workloads. This convergence is compressing the performance gap against low-end discrete GPUs in the $100-150 segment, forcing NVIDIA to reposition GeForce MX series products toward thin-margin clearance channels.
China's GB 4943.1-2022 cybersecurity certification for information technology equipment is mandating domestic cryptographic module integration within processor graphics firmware, creating compliance friction for Intel and AMD shipments into government and financial services procurement. MIIT testing laboratory queues in Beijing and Shanghai currently extend 8-12 months for new silicon submissions. Domestic alternatives from Hygon and Zhaoxin are accelerating certification completion by 40-60 days, capturing share in provincial datacenter and surveillance system deployments where integrated graphics handle video decode and light inference.
Enterprise IT procurement teams are consolidating laptop fleet specifications around 16-inch form factors with 2560x1600 displays, prioritizing integrated graphics solutions that drive these panels without external GPU cost. Dell, HP, and Lenovo commercial sales organizations report 70% plus attach rates for AMD Ryzen Pro and Intel vPro configurations with integrated graphics in North American corporate tenders. This specification compression is displacing discrete GPU upsell opportunities in the $800-1200 enterprise price band, redirecting vendor margin capture toward memory and storage configuration tiers.
Integrated Graphics Chipset Market Segmentation
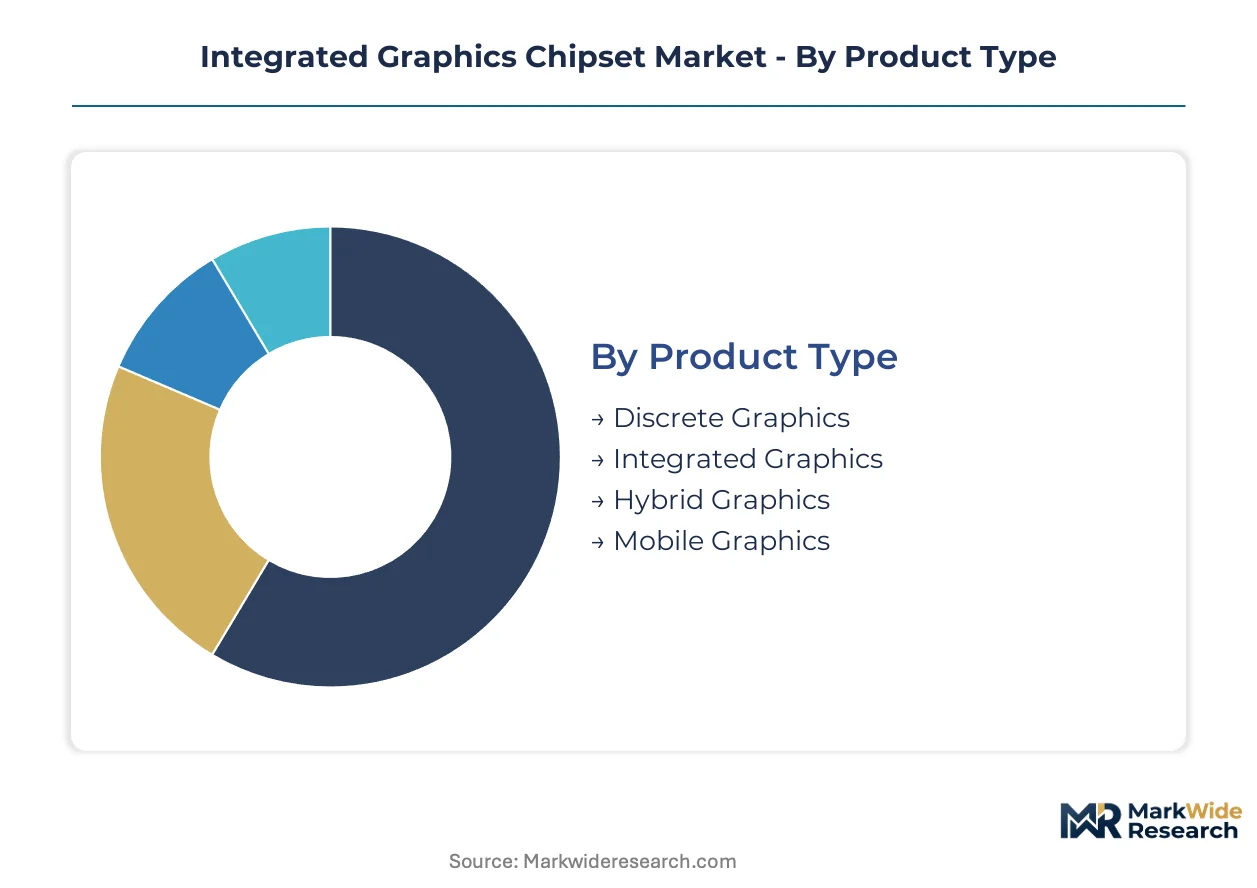
Integrated graphics chipset procurement hinges on thermal constraints, memory bandwidth requirements, and software certification timelines that vary sharply across deployment contexts. Segmentation reveals how AMD, Intel, and ARM-based suppliers calibrate die configurations, process nodes, and driver stacks to match distinct buyer workflows and power envelopes.
Product Type:
Buyer selection pivots on bill-of-materials tradeoffs between silicon cost, board complexity, and upgrade flexibility.
- Discrete Graphics:Dedicated GPU dies with local GDDR6 or GDDR6X memory deliver bandwidth exceeding 500 GB/s for 4K gaming and AI training workloads. Dell and HP workstation divisions specify NVIDIA RTX Ada or AMD Radeon Pro boards for Autodesk Revit and SolidWorks certification requirements.
- Integrated Graphics:CPU-die graphics engines manufactured at 4nm to 7nm nodes share DDR5 system memory pools below 100 GB/s bandwidth. Corporate IT refresh cycles across Germany and France specify Intel Core and AMD Ryzen Pro APUs for thin-client deployments under EU Ecodesign standby power mandates.
- Hybrid Graphics:Dynamic switching firmware routes display output between integrated and discrete engines based on workload detection. Microsoft Surface Laptop Studio and Lenovo ThinkPad P-series mobile workstations leverage this architecture to preserve battery endurance during document editing.
- Mobile Graphics:Thermally constrained GPU implementations for tablets and handheld gaming devices operate within 5-15W TDP envelopes. Valve Steam Deck and ASUS ROG Ally incorporate AMD RDNA2-based custom APUs for portable AAA gaming.
Volume sits with Integrated Graphics; growth tilts toward Hybrid Graphics.
End User:
Application-specific certification requirements and thermal design power budgets reshape vendor prioritization across customer categories.
- Gaming:Frame rate consistency at 1080p and 1440p resolutions drives APU selection for entry-level laptop configurations. Vietnamese and Indonesian OEMs specify AMD Phoenix and Intel Meteor Lake silicon for sub-$800 consumer notebooks where discrete GPU cost proves prohibitive.
- Professional Workstations:ISV-validated drivers for Dassault Systèmes CATIA and Siemens NX demand extended qualification timelines. HP ZBook and Dell Precision mobile workstation divisions maintain 18-month certification backlogs for new integrated graphics architectures.
- Consumer Electronics:Smart displays and streaming set-top boxes require H.265 and AV1 decode acceleration without active cooling. Amazon Fire TV and Google Chromecast product lines license ARM Mali and Imagination PowerVR cores for cost-optimized 4K video playback.
- Automotive:Digital instrument clusters and infotainment head units consolidate multiple displays through single SoC graphics pipelines. Mercedes-Benz and BMW tier-one suppliers specify Renesas and Qualcomm Snapdragon cockpit platforms with integrated Adreno and Mali GPU blocks.
Workstation margins concentrate in Professional Workstations; unit expansion accelerates fastest in Automotive.
Technology:
Silicon convergence trends and rendering pipeline architectures determine competitive positioning across implementation approaches.
- GPUs:Dedicated graphics execution units with programmable shader arrays remain the dominant installed base category. NVIDIA GeForce and AMD Radeon discrete products command premium positioning for real-time ray tracing and DLSS upscaling implementations.
- APUs:Unified CPU-GPU dies manufactured on single monolithic or chiplet interconnects represent the steepest expansion trajectory. AMD Ryzen 7040-series Phoenix designs combine Zen 4 compute cores with RDNA3 graphics on TSMC 4nm process for 15-54W configurable TDP envelopes.
- Ray Tracing:Hardware-accelerated bounding volume hierarchy traversal for realistic lighting simulation requires dedicated RT cores. Intel Arc Alchemist and AMD RDNA3 integrated implementations enable entry-level ray tracing for ChromeOS and Windows laptops.
- Virtual Reality:Stereoscopic rendering pipelines with sub-20ms motion-to-photon latency demand sustained frame delivery. Meta Quest standalone headsets incorporate Qualcomm Snapdragon XR2+ platforms with integrated Adreno graphics for untethered VR applications.
GPU shipments dominate current volume; APU configurations climb the fastest.
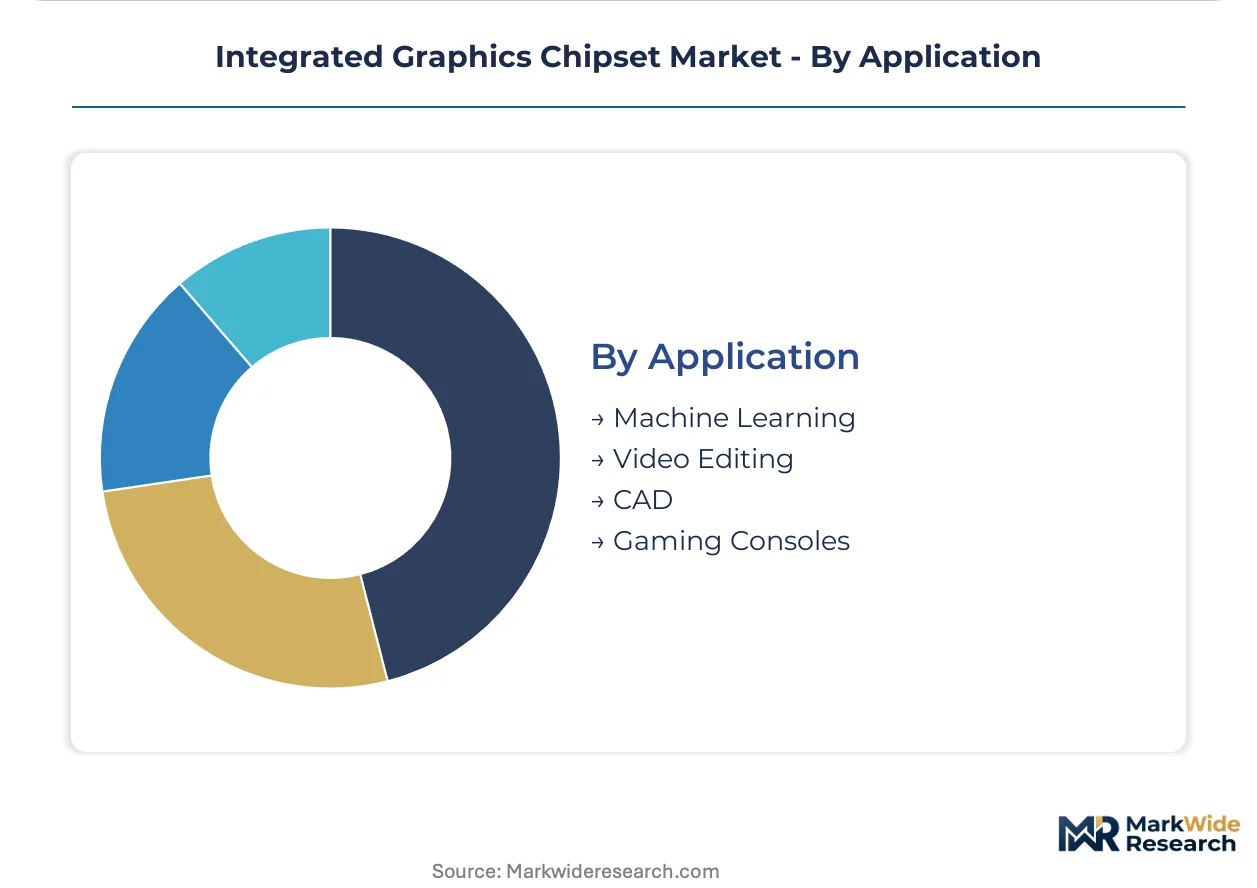
Application:
Compute intensity and memory access patterns differentiate workload requirements across software categories.
- Machine Learning:INT8 and FP16 inference acceleration for edge deployment favors integrated graphics with matrix multiply engines. Retail self-checkout systems in Walmart and Target deployments utilize AMD Ryzen Embedded APUs for computer vision barcode scanning.
- Video Editing:Timeline scrubbing and effects rendering demand sustained memory bandwidth and codec hardware acceleration. Adobe Premiere Pro and DaVinci Resolve software stacks optimize for Intel Quick Sync and AMD VCE encode blocks in integrated configurations.
- CAD:Large assembly manipulation and real-time shaded viewport performance require certified OpenGL and DirectX implementations. Siemens NX and PTC Creo engineering software maintain validation matrices for Intel UHD, Iris Xe, and AMD Radeon Graphics driver branches.
- Gaming Consoles:Custom APU designs with unified memory architectures optimize for console form factor and thermal constraints. Sony PlayStation 5 and Microsoft Xbox Series X incorporate AMD RDNA2-based semi-custom silicon with 16GB GDDR6 memory pools.
CAD maintains the largest professional installed base; Machine Learning gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan anchors integrated graphics supply chains, while end-demand concentrates in corporate IT refresh cycles across Germany, government procurement in China, thin-client deployments in the United States, automotive cockpit programs in Japan, and domestic motherboard manufacturing in India.
United States
Corporate thin-client refresh cycles and edge AI inference workloads drive APU procurement from Intel and AMD. The FCC governs electromagnetic emissions standards that constrain PCB layout and thermal design for integrated graphics implementations in consumer electronics. Dell and HP workstation divisions in Austin and Houston specify Intel vPro and AMD Ryzen Pro configurations for enterprise fleet tenders.
Germany
EU Ecodesign standby power mandates below 0.5 watts accelerate low-power integrated graphics adoption in corporate thin-client deployments. The EU REACH regulation and RoHS directive restrict hazardous substances in semiconductor packaging materials, directly affecting substrate and solder bump compositions. Siemens and BMW procurement teams in Munich and Stuttgart prioritize certified driver stacks for professional visualization workloads.
China
Government and state-owned enterprise PC tenders require processors with indigenous integrated graphics, channeling motherboard ecosystem demand toward Loongson and Zhaoxin designs. MIIT enforces domestic cybersecurity review protocols through GB 4943.1-2022 certification with testing laboratory queues in Beijing and Shanghai extending 8-12 months. Domestic alternatives from Hygon accelerate certification completion by 40-60 days, capturing share in provincial datacenter deployments.
Japan
Automotive digital cockpit consolidation electrifies integrated graphics penetration into tier-one supplier programs for instrument cluster integration. METI oversees industrial standards coordination for semiconductor packaging and thermal management specifications. Renesas and tier-one suppliers in Nagoya and Tokyo specify ARM-based SoC designs with Mali and Imagination GPU cores for Mercedes-Benz and BMW programs.
India
The PLI scheme for semiconductor assembly attracts OSAT investment for cost-optimized APU module production serving domestic laptop brands. Modified incentive structures covering display driver and integrated die packaging concentrate activity in Gujarat and Tamil Nadu. Dell and HP commercial sales organizations report 70% plus attach rates for integrated graphics configurations in corporate tenders across Bangalore and Mumbai IT corridors.
Integrated Graphics Chipset Market Competitive Landscape
Global majors compete with regional champions across process node access and captive foundry utilization. The integrated graphics chipset market structures around IDM incumbents with captive wafer supply, fabless designers dependent on external foundry allocation, and ARM-based IP licensors serving automotive and mobile adjacencies. Three archetypes dominate: integrated device manufacturers sustaining vertical silicon control, fabless APU specialists leveraging external foundry partnerships, and GPU architecture licensors extending into ARM-based integrated solutions. Competitive moves concentrate on foundry capacity reservation and strategic IP licensing for automotive cockpit consolidation.
Within the IDM archetype, Intel Corporation and Advanced Micro Devices exemplify divergent supply strategies—Intel leverages captive fab utilization through its IDM 2.0 framework while AMD anchors external foundry commitments at TSMC for RDNA-integrated APU production. NVIDIA Corporation occupies a position bridging discrete GPU dominance with architecture licensing into ARM-based integrated solutions for automotive and data center adjacencies. These three represent the competitive tension between silicon sovereignty and foundry-dependent scaling.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices |
| Apple Inc. |
| NVIDIA Corporation |
| Qualcomm |
| MediaTek |
| Samsung |
| Imagination Technologies |
| VIA Technologies |
| Others |
Supply & Pricing Matrix
Corporate IT fleet consolidation around 16-inch 2560x1600 display specifications is compressing discrete GPU upsell opportunities and forcing Intel and AMD to recalibrate APU pricing tiers around memory and storage configuration bundles rather than silicon premiums. This procurement compression channels margin capture toward DRAM and NAND tiering while eroding standalone graphics chipset pricing power.
Pricing Analysis
Extended ISV driver certification warranties for Autodesk and Siemens NX validation tiers anchor premium pricing for workstation-bound APUs, while unbundled consumer laptop SKUs compete on raw silicon cost. Three-tier pricing structure across premium ISV-certified, standard commercial, and economy Chromebook levels differentiates AMD Ryzen Pro, Intel vPro, and baseline Celeron configurations. Cost compression in entry-level consumer tiers is intensifying because Vietnamese and Indonesian OEMs prioritize sub-$800 bill-of-materials targets. Corporate procurement teams exhibit lowest price sensitivity due to fleet standardization mandates, while education sector tenders show highest elasticity.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers including JSR and Tokyo Ohka Kogyo, while EUV scanner availability draws from ASML's Veldhoven fabrication facilities. Silicon wafer supply concentrates in Taiwan, South Korea, and Japan, with TSMC Hsinchu and Taichung fabs anchoring leading-edge APU production. Raw material dependencies span 300mm silicon wafers, high-purity photoresists, and palladium-based solder bump compositions. Single-source vulnerability around EUV lithography equipment creates supply chain risk for sub-5nm APU ramps. Distribution runs through Taiwan-based ODMs including Quanta and Compal for laptop module integration, then onward to Dell, HP, and Lenovo assembly facilities in China and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity allocation compression at TSMC N6 and N4 nodes is propping APU pricing power by constraining AMD and Intel supply elasticity, creating a supply-constrained market structure where procurement teams face extended lead times for volume commitments.
For Market Incumbents: Acquire physical design talent pools concentrated at Intel Hillsboro and AMD Austin to offset GPU floorplanning expertise scarcity constraining fabless entrants. Secure captive wafer supply through IDM 2.0 fab utilization or long-term TSMC capacity reservations to defend against AI accelerator wafer priority shifts. Prioritize ISV certification pipeline acceleration for Autodesk Maya and Siemens NX validation matrices to capture enterprise workstation margin pools before ARM-based alternatives mature. For New Entrants and Emerging Players: Launch via domestic Chinese motherboard ecosystem partnerships targeting MIIT procurement mandates for indigenous integrated graphics in government and state-owned enterprise tenders. Penetrate India's PLI scheme incentive structures for semiconductor assembly in Gujarat and Tamil Nadu, where modified display driver and integrated die packaging coverage attracts OSAT investment. Target automotive digital cockpit consolidation as the most penetrable segment, licensing ARM Mali or Imagination PowerVR cores for tier-one supplier programs at Mercedes-Benz and BMW. For Investors and Strategic Acquirers: The window for entry favors fabless APU specialists with secured TSMC N6 allocation and automotive SoC licensing pipelines. Long-term viability hinges on chiplet disaggregation capabilities and unified memory architecture IP spanning 5-10 year technology roadmaps. Watch for MIIT certification queue compression as the inflection signal indicating domestic Chinese alternatives are accelerating market access timelines against Intel and AMD.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | TSMC N6 and N4 node commitments secure APU wafer supply against AI accelerator absorption. |
| ISV Certification Pipeline Investment | Autodesk and Siemens NX validation matrices unlock enterprise workstation procurement channels. |
| Automotive SoC Licensing Expansion | ARM Mali and Imagination PowerVR core agreements penetrate Mercedes-Benz and BMW tier-one programs. |
| Domestic China Certification Acceleration | MIIT GB 4943.1-2022 compliance captures government and state-owned enterprise motherboard demand. |
| Chiplet Disaggregation R&D | Proprietary die-to-die interfaces enable process-node optimization and yield recovery for unified CPU-GPU tiles. |
Research Methodology
Independent corroboration across semiconductor foundry utilization reports, OEM procurement disclosures, and regulatory filing databases underwrites the qualitative findings in this study. Primary interviews with GPU architecture leads at Intel and AMD, procurement directors at Dell and HP commercial divisions, and regulatory affairs specialists navigating MIIT certification queues provided ground-truth validation. Secondary sources include TSMC investor materials, EU Ecodesign directive implementation guidance, and China MIIT GB standard documentation. Bottom-up APU shipment estimates from Taiwan ODMs triangulate against top-down motherboard ecosystem demand models.
Comparable historical periods spanning corporate IT refresh cycles and foundry allocation shifts anchor the forecast window to observed supply-demand imbalances. The analytical framework segments by product type, end user, technology, and application dimensions across the projection horizon. CAGRs derive from installed base replacement rates and penetration curve modeling for edge AI inference workloads. Forecast inputs incorporate EU standby power mandate compliance timelines and China domestic procurement mandate enforcement intensity.
TSMC node allocation priority shifts, MIIT certification queue duration volatility, and ISV driver validation timeline extensions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions around sustained corporate laptop fleet standardization and automotive cockpit consolidation trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Edge AI Processor Market