
 Protein Chip Market | 2026-2036
Protein Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Chip Market Outlook
Germany is reconfiguring European protein chip supply dynamics through dedicated microarray manufacturing hubs near Heidelberg and Munich. Thermo Fisher Scientific Inc. leverages its mass spectrometry instrumentation base to cross-sell integrated protein analysis workflows. Agilent Technologies, Inc. sustains R&D intensity in label-free detection platforms for pharmaceutical quality control. Bio-Rad Laboratories Inc. anchors its position through analytical chips optimized for clinical laboratory throughput requirements.
Protein chips are solid-phase assay devices that immobilize capture molecules—typically antibodies, antigens, or peptide probes—onto glass, silicon, or polymer substrates at densities exceeding 1,000 spots per square centimeter, enabling parallel quantification of protein interactions for diagnostics and drug discovery. Microarray chips dominate current revenue owing to established protocols in academic proteomics, while label-free detection platforms represent the fastest-expanding technology segment as pharmaceutical companies seek real-time binding kinetics without fluorescent tags. Pharmaceutical companies command the largest end-user share due to internal biomarker programs, though clinical laboratories are emerging as a concentrated margin pool where regulatory-cleared protein assays command premium pricing.
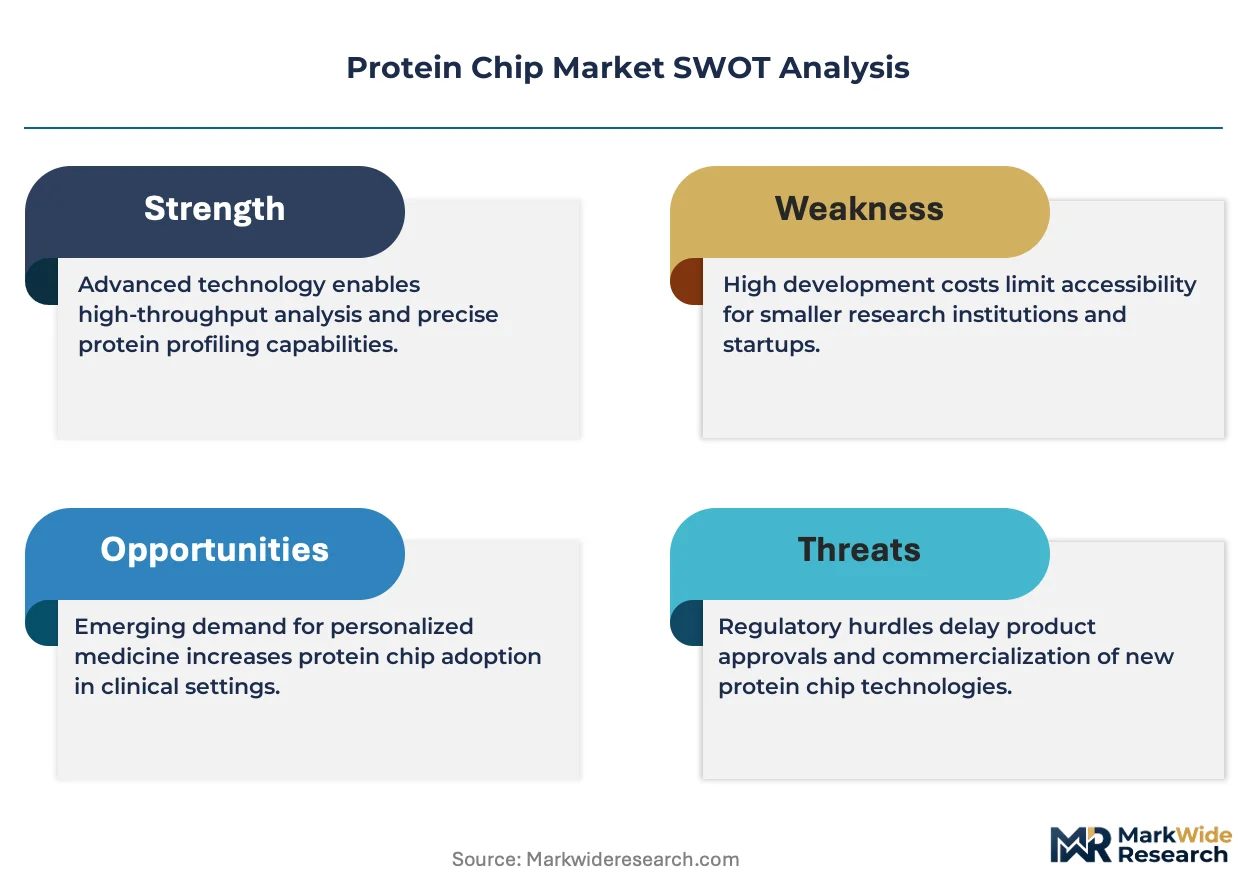
FDA premarket review pathways for multiplex in vitro diagnostics directly shape protein chip commercialization timelines and clinical adoption thresholds. EMA's In Vitro Diagnostic Regulation and ISO 13485 quality management standards impose design-control burdens that filter out smaller substrate suppliers. REACH compliance for surface chemistries and coating reagents adds material qualification costs for European market access. Stakeholders must monitor evolving FDA guidance on artificial intelligence-assisted protein assay interpretation, as algorithm-enabled readout systems will reshape competitive differentiation in high-complexity testing environments.
Market Dynamics
Multiplex assay miniaturization is compressing reagent consumption per test while expanding biomarker panel density, forcing substrate manufacturers to invest in nanoscale surface engineering capabilities to retain pharmaceutical procurement contracts.
Growth Catalysts
- NIH proteomics consortia:Sustained federal funding for high-density protein screening infrastructure maintains instrument replacement cycles at academic medical centers across the United States.
- Companion diagnostic mandates:FDA premarket review pathways for multiplex protein assays accelerate biomarker validation timelines, compressing pharmaceutical development cycles.
- Label-free detection platforms:Real-time binding kinetics without fluorescent tags reduces assay preparation labor, attracting quality control departments at biologics manufacturers.
Market Restraints
- Surface chemistry input costs:Specialized silane and polymer coating reagents face REACH compliance qualification burdens, inflating European substrate manufacturing expenses.
- Silicon wafer supply concentration:German microarray manufacturing hubs near Heidelberg depend on concentrated semiconductor foundry capacity, exposing production schedules to fab allocation constraints.
- Cross-reactivity technical limitations:High-density spotting of antibody capture molecules produces signal interference at densities exceeding 2,000 spots per square centimeter, capping assay multiplexing for complex samples.
Strategic Opportunities
- Clinical laboratory channel expansion:Regulatory-cleared protein assays command premium pricing in hospital-based reference laboratories, creating margin pools distinct from research-use-only sales.
- ISO 13485 certification acceleration:Quality management standard adoption filters out smaller substrate suppliers, opening procurement opportunities for compliant manufacturers in European diagnostic markets.
- Artificial intelligence-assisted interpretation:Algorithm-enabled readout systems reshape competitive differentiation in high-complexity testing environments, enabling automated biomarker scoring.
Industry Challenges
- Bioinformatics talent scarcity:Multiplex protein data analysis requires computational biologists trained in both mass spectrometry workflows and machine learning, creating recruitment bottlenecks.
- EMA In Vitro Diagnostic Regulation compliance timelines:Design-control documentation burdens extend product registration cycles, delaying revenue recognition for new assay launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Chip Market |
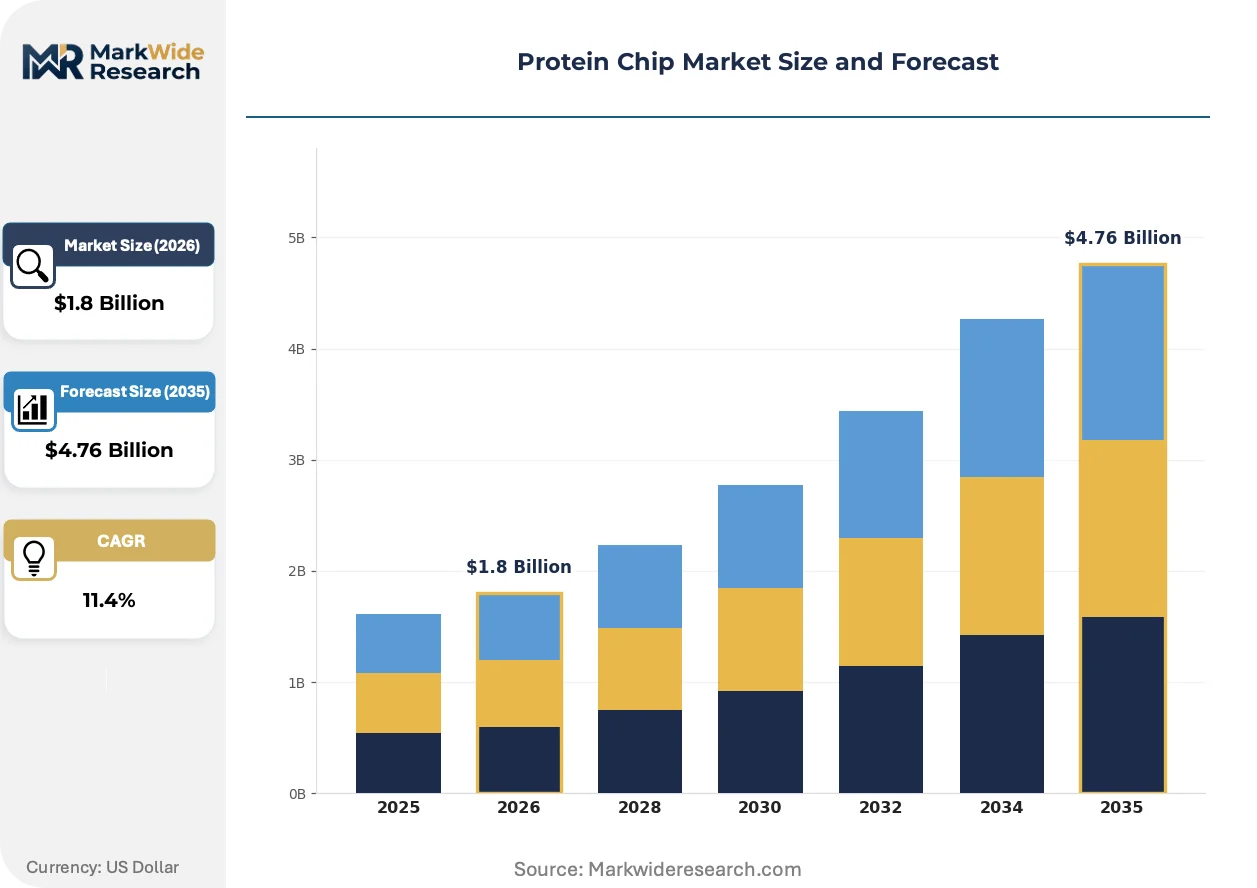
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarray Chips, Arrayed Primer Extension, Protein Microarrays, Analytical Chips Technology: Affinity-based, Label-free Detection, Mass Spectrometry, Surface Plasmon Resonance End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Biotech Firms Application: Diagnostics, Drug Discovery, Biomarker Discovery, Environmental Monitoring |
| Companies Covered | Agilent Technologies, Inc., Thermo Fisher Scientific Inc., PerkinElmer Inc., Bio-Rad Laboratories Inc., Illumina Inc., Roche Diagnostics, Shimadzu Corporation, Merck KGaA, RayBiotech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Chip Market Strategic Shifts
Protein chip architectures are converging with semiconductor manufacturing methods and computational analytics, producing assay platforms that generate machine-readable binding data at throughputs impossible with conventional ELISA workflows.
Surface plasmon resonance imaging is digitizing protein interaction data capture, converting real-time binding curves into quantitative kinetic parameters without endpoint staining. Pharmaceutical quality control departments are adopting these platforms for batch release testing of therapeutic antibodies. The technology is digitizing assay documentation, enabling direct electronic submission of binding data to regulatory filing systems.
EMA's In Vitro Diagnostic Regulation imposes post-market surveillance obligations on protein assay manufacturers, requiring systematic performance monitoring across distributed clinical installations. Diagnostic companies must maintain vigilance systems tracking analytical accuracy in diverse laboratory environments. European notified bodies are expanding technical documentation review scope, extending clearance timelines for multiplex protein panels.
Consolidated procurement by hospital network central laboratories is displacing decentralized purchasing of protein screening platforms. Integrated delivery networks in the United States are standardizing on single-vendor ecosystems to reduce training and maintenance complexity. This concentration is visible most acutely in Boston and San Diego biotech clusters, where anchor institutions dictate substrate specifications for affiliated research programs.
Protein Chip Market Segmentation
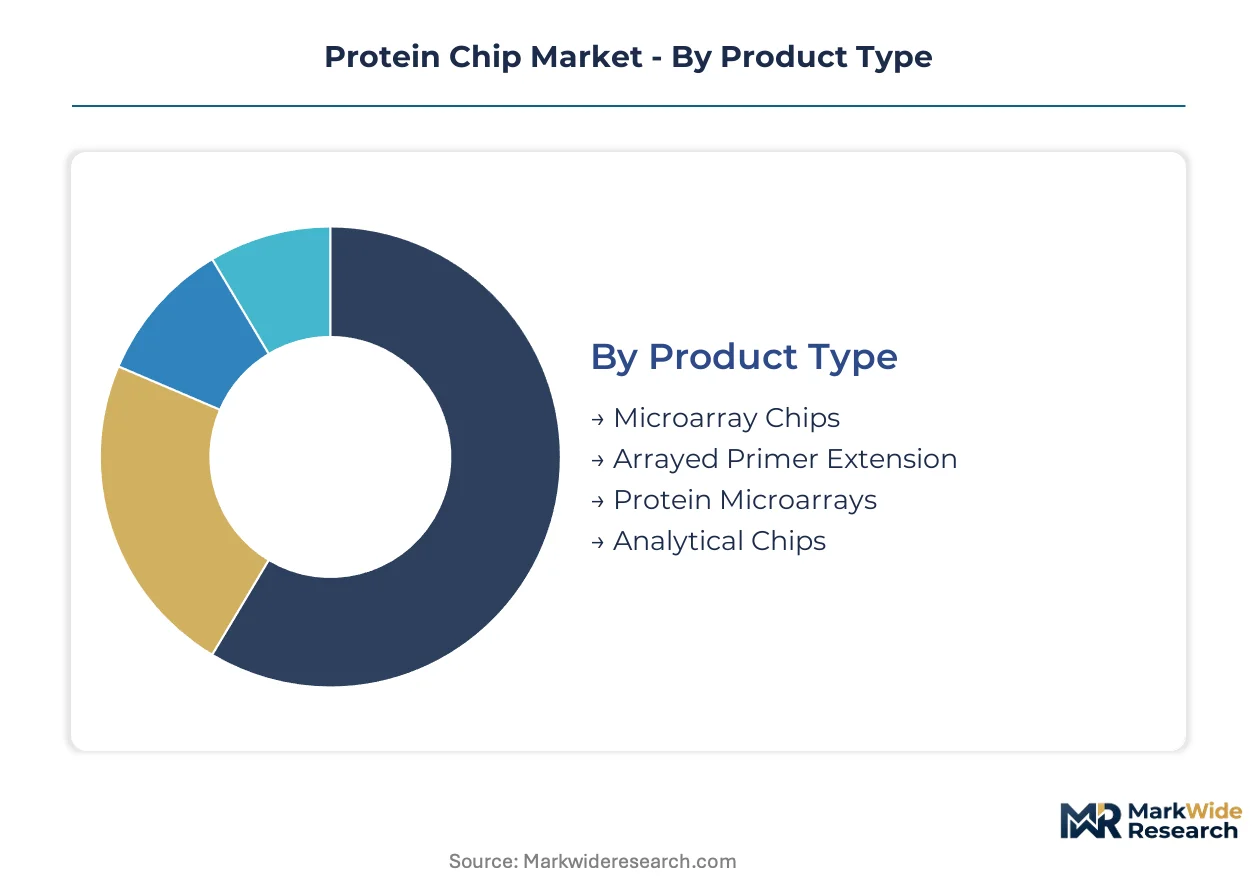
Protein chip market segmentation reveals distinct procurement cycles across substrate formats, detection modalities, and end-use environments. Each dimension carries implications for regulatory pathway selection, manufacturing scale economics, and customer retention strategies.
Product Type:
Microarray chips turn over on 18-24 month replacement cycles driven by surface chemistry degradation, while analytical chips installed in clinical laboratories persist 5-7 years under ISO 13485 maintenance protocols.
- Microarray Chips:Glass or silicon substrates with spotted antibody arrays at densities exceeding 1,000 spots per square centimeter. Academic medical centers in Boston and San Diego sustain replacement demand through NIH-funded proteomics consortia infrastructure grants.
- Analytical Chips:Polymer-based cartridges engineered for clinical laboratory throughput requirements with integrated fluidics. Hospital network central laboratories in the United States concentrate procurement volume as integrated delivery networks standardize on single-vendor ecosystems.
- Arrayed Primer Extension:Nucleic acid-protein hybrid substrates enabling genotype-phenotype correlation studies. Research institutions deploy these for biomarker validation cohorts.
- Protein Microarrays:Functional protein spotted arrays for interaction mapping. Biotech firms utilize these for therapeutic target characterization.
Microarray chips anchor the volume base while analytical chips gains share at the steepest rate.
Technology:
Cost tiers separate affinity-based platforms accessible to academic budgets from capital-intensive label-free systems requiring dedicated technical specialists.
- Label-free Detection:Real-time binding kinetics measurement without fluorescent tag preparation. Pharmaceutical quality control departments at biologics manufacturers adopt these platforms for batch release testing to reduce assay preparation labor.
- Surface Plasmon Resonance:Optical biosensors converting binding events into refractive index shifts. FDA premarket review pathways for multiplex protein assays accelerate adoption timelines for companion diagnostic development.
- Affinity-based:Conventional antibody-antigen capture with fluorescent or chemiluminescent readout. Clinical laboratories favor these for regulatory-cleared assay compatibility.
- Mass Spectrometry:Ionization-based protein identification coupled to chip-based sample preparation. Thermo Fisher Scientific cross-sells these workflows from its installed instrumentation base.
Affinity-based platforms dominate installed base economics while label-free detection climbs the fastest.
End User:
Customer type determines margin structure, with research institutions demanding volume discounts and clinical laboratories accepting premium pricing for regulatory-cleared assays.
- Pharmaceutical Companies:Internal biomarker programs and companion diagnostic mandates drive multiplex panel procurement. EMA In Vitro Diagnostic Regulation compliance timelines extend product registration cycles for European market access.
- Clinical Laboratories:Hospital-based reference laboratories command premium pricing for FDA-cleared protein assays. Consolidated procurement by United States integrated delivery networks concentrates purchasing power.
- Biotech Firms:Venture-funded discovery programs with rapid platform turnover. Boston and San Diego clusters sustain instrument placement rates through anchor institution specifications.
- Research Institutions:NIH-funded academic medical centers with cyclical grant-dependent procurement. Federal funding for high-density protein screening infrastructure maintains replacement cycles.
Pharmaceutical companies anchor the volume base while clinical laboratories gains share at the steepest rate.
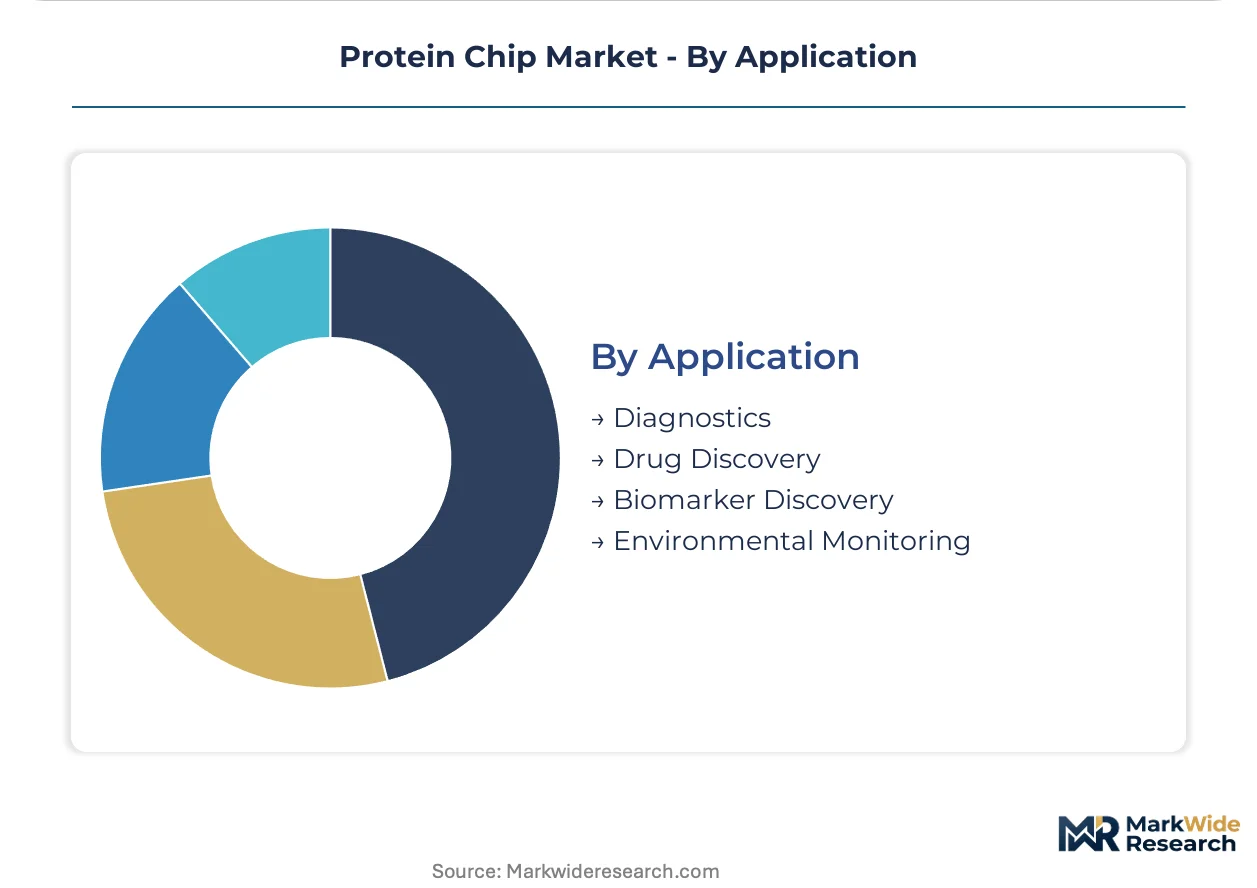
Application:
Maturity gradients separate established diagnostics workflows from emerging environmental monitoring deployments with unstandardized protocols.
- Diagnostics:Multiplex in vitro diagnostic assays for disease state classification. FDA premarket review pathways directly shape commercialization timelines and clinical adoption thresholds.
- Drug Discovery:Target validation and lead optimization screening. REACH compliance for surface chemistries adds material qualification costs for European substrate manufacturing.
- Biomarker Discovery:Exploratory protein profiling for therapeutic stratification. Cross-reactivity technical limitations cap assay multiplexing at densities exceeding 2,000 spots per square centimeter.
- Environmental Monitoring:Protein-based biosensors for toxin and pathogen detection. ISO 13485 quality management standard adoption filters substrate supplier participation.
Drug discovery anchors the volume base while diagnostics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket review pathways for multiplex protein assays anchor commercialization timelines in the United States, while EMA's In Vitro Diagnostic Regulation shapes European market access. NIH-funded proteomics consortia sustain instrument placement cycles at academic medical centers.
United States
NIH proteomics consortia maintain high-density protein screening infrastructure grants at academic medical centers. FDA clearance pathways for multiplex in vitro diagnostics compress time-to-market for new assay entrants. Boston and San Diego biotech clusters sustain instrument replacement rates through anchor institution procurement specifications.
Germany
Microarray manufacturing hubs near Heidelberg and Munich reconfigure European supply dynamics through concentrated semiconductor foundry partnerships. EMA In Vitro Diagnostic Regulation and ISO 13485 quality management standards impose design-control documentation burdens. REACH compliance for surface chemistries inflates substrate manufacturing expenses for domestic producers.
China
NMPA regulatory frameworks for in vitro diagnostics reshape protein assay registration timelines for multinational manufacturers. Domestic biopharmaceutical quality control departments drive label-free detection platform procurement. Yangtze River Delta research institutions deploy functional protein spotted arrays for therapeutic target characterization.
Japan
PMDA review pathways for companion diagnostics accelerate biomarker validation partnerships between domestic pharmaceutical companies and substrate suppliers. METI industrial policy supports proteomics infrastructure at national research institutes. Kanto region analytical laboratories concentrate procurement of regulatory-cleared protein assays.
United Kingdom
MHRA post-Brexit regulatory autonomy creates distinct clearance pathways for multiplex protein panels entering the British market. NHS England consolidated procurement by hospital network central laboratories standardizes on single-vendor ecosystems. London and Cambridge life sciences clusters sustain demand for high-throughput clinical laboratory platforms.
Protein Chip Market Competitive Environment
Capability concentration sits with specialized substrate manufacturers possessing nanoscale surface engineering expertise; scale advantage sits with diversified life sciences conglomerates leveraging cross-selling from installed analytical instrumentation bases. The market structures around three tiers: premium integrated workflow providers, mid-scale substrate specialists, and regional assay service laboratories. Strategic moves center on ISO 13485 certification acceleration for European diagnostic market access and artificial intelligence-assisted readout system development for high-complexity testing environments.
Among diversified analytical instrumentation conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies, Inc. occupy positions representing integrated workflow scale advantages. Bio-Rad Laboratories Inc. exemplifies the clinical laboratory-focused archetype with analytical chips engineered for throughput requirements. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc. |
| Bio-Rad Laboratories Inc. |
| Illumina Inc. |
| Roche Diagnostics |
| Shimadzu Corporation |
| Merck KGaA |
| RayBiotech Inc. |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer foundry concentration in Taiwan and Germany directly determines where margin pools accumulate downstream, with substrate manufacturers facing cost pass-through pressure from semiconductor-grade silicon suppliers while clinical laboratories capture premium pricing for regulatory-cleared assays.
Pricing Analysis
Geographic price spreads of 15-25% separate United States clinical laboratory procurement from European research-use-only volumes, reflecting FDA clearance premiums against REACH compliance cost burdens. Pricing stratifies across ISO 13485-certified diagnostic tiers, research-grade microarray substrates, and unvalidated exploratory formats. Cost compression in research-grade substrates intensifies as NIH grant cycles tighten instrument replacement budgets. Academic medical centers exhibit highest price sensitivity, while hospital network central laboratories accept premium positioning for regulatory-cleared companion diagnostic panels.
Supply Chain Analysis
Export control regimes limiting semiconductor manufacturing equipment flows to Chinese foundries constrain substrate surface engineering capacity expansion in Asia-Pacific markets. Supply concentrates in Germany, Taiwan, and the United States for silicon and glass substrate fabrication, with specialized silane coating reagents drawing from concentrated European chemical suppliers. Single-source vulnerability sits with photolithography equipment for high-density spotting above 2,000 spots per square centimeter. Distribution runs through life sciences distribution conglomerates with cold-chain logistics for reagent stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from assay interpretation software and ISO 13485 maintenance contracts expands faster than hardware placement, creating recurring revenue layers that pharmaceutical quality control departments lock in through multi-year service agreements.
For Market Incumbents: Insulate installed base positions through captive supply of surface chemistry reagents and accelerated ISO 13485 certification for European diagnostic market access. Consolidate procurement relationships with Boston and San Diego biotech clusters through anchor institution specifications. Vertical integration into nanoscale surface engineering filters out mid-scale substrate competitors. For New Entrants and Emerging Players: Establish a beachhead in environmental monitoring applications where regulatory-cleared assay protocols remain unstandardized and incumbent certification burdens are absent. Target biotech firm segments in Yangtze River Delta research corridors with functional protein spotted arrays for therapeutic target characterization. Lead with label-free detection platforms that reduce assay preparation labor for quality control departments. For Investors and Strategic Acquirers: Capital is best deployed toward substrate specialists possessing nanoscale surface engineering capabilities and existing FDA premarket submission experience. Long-term viability over the analysis window hinges on algorithm-enabled readout system development. Monitor NIH proteomics consortium funding allocations as inflection signal for academic instrument replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | EMA In Vitro Diagnostic Regulation compliance filters smaller substrate suppliers from European diagnostic procurement. |
| AI-Assisted Assay Interpretation Development | FDA guidance evolution on algorithm-enabled readout systems reshapes competitive differentiation in high-complexity testing. |
| Clinical Laboratory Channel Expansion | Hospital network central laboratories in United States integrated delivery networks concentrate procurement volume. |
| Surface Chemistry Reagent Captive Supply | REACH compliance qualification burdens inflate European substrate manufacturing expenses for non-integrated producers. |
| Label-Free Detection Platform Launch | Pharmaceutical quality control departments adopt real-time binding kinetics platforms for biologics batch release testing. |
Study Parameters
Operator-level perspectives from proteomics platform directors, clinical laboratory managers, regulatory affairs specialists at diagnostic manufacturers, and biomedical procurement officers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA In Vitro Diagnostic Regulation technical documentation, NIH RePORTER grant databases, and ISO 13485 certification registries. Bottom-up instrument placement modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing around NIH funding continuity, EMA compliance timeline compression, and semiconductor foundry capacity allocation framed the analytical approach across the projection horizon. Segmentation dimensions spanned substrate format, detection modality, end-user archetype, and regional regulatory cluster. CAGRs derived from instrument replacement cycle analysis and assay panel expansion rates, with inputs from proteomics infrastructure grant trajectories and companion diagnostic mandate adoption curves.
Macroeconomic conditions sit as an overlay; deviation in federal research funding levels, semiconductor capital expenditure cycles, or biopharmaceutical merger activity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance pathway efficiency and surface chemistry supply stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Application Processor Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Quantum Processing Units (QPU) Market