
 Car Chip Market | 2026-2036
Car Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Car Chip Market Insights
Autonomous driving platforms are repositioning tier-1 procurement budgets toward sensor fusion and real-time processing modules. Infineon Technologies AG dominates automotive power semiconductors through in-house production of silicon carbide substrates. NXP Semiconductors anchors vehicle networking portfolios with domain controller expertise. Texas Instruments competes in battery management integrated circuits for electrified architectures.
Car chips are semiconductor devices engineered to operate across temperature extremes from minus 40 to 150 degrees Celsius, fabricated on automotive-grade nodes with zero defect targets measured in parts per billion. Their primary commercial purpose is to execute control, sensing, and communication functions under sustained mechanical stress and electrical noise. Microcontroller units lead unit shipments due to pervasive deployment in engine control, braking, and body electronics. Power management integrated circuits represent the fastest-growing technology segment as 800-volt battery architectures multiply. Analog front-ends retain mature margin pools in safety-critical signal conditioning for airbag and antilock brake systems.
NHTSA in the United States mandates functional safety compliance through ISO 26262, while the EU Green Deal drives semiconductor efficiency standards for electrified fleets. China's MIIT enforces domestic chip content ratios through GB standards and dual carbon goals. Stakeholders must monitor how REACH substance restrictions and evolving FCC electromagnetic rules reshape substrate material qualifications and foundry location decisions.
Market Dynamics
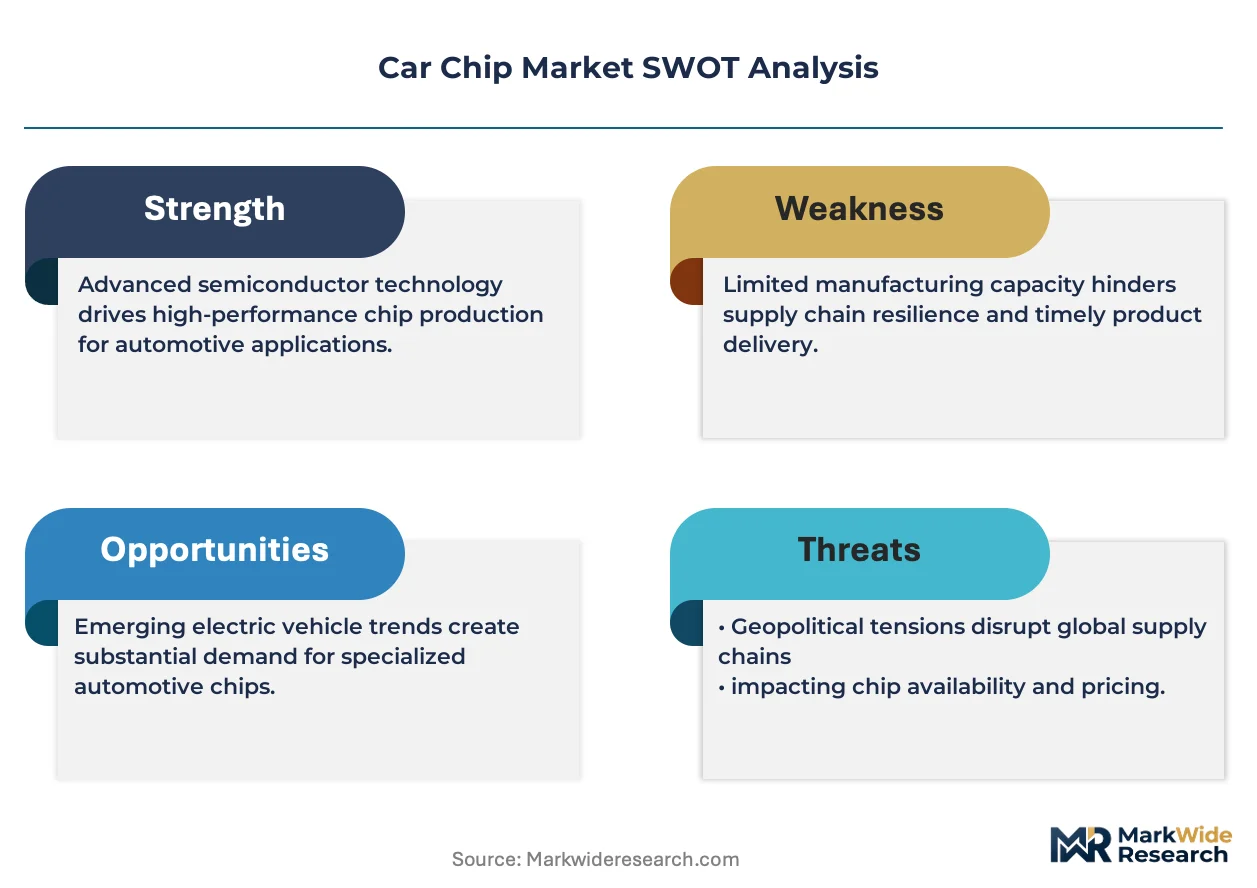
Electrified powertrains are compressing procurement timelines across vehicle assemblers as 800-volt architectures demand silicon carbide substrates with automotive-grade defect tolerances measured in parts per billion.
Growth Catalysts
- NHTSA Functional Safety Mandates:ISO 26262 compliance requirements in the United States are accelerating validation cycles for microcontrollers deployed in braking and steering systems.
- Silicon Carbide Substrate Adoption:Wide-bandgap materials are displacing silicon IGBTs in traction inverters as battery-electric platforms multiply across German and Chinese production lines.
- Sensor Fusion Architectures:Autonomous driving platforms are pulling real-time processing modules into domain controllers, concentrating semiconductor value in lidar-radar-camera integration stacks.
Market Restraints
- Substrate Cost Volatility:Silicon carbide wafer prices fluctuate with energy-intensive crystal growth capacity concentrated in limited foundry locations.
- Foundry Geographic Concentration:Advanced automotive node production clusters in Taiwan and South Korea create single-source vulnerability for 28nm and below process technologies.
- REACH Substance Restrictions:ECHA candidate list updates are forcing substrate material reformulations that extend qualification timelines for epoxy molding compounds.
Strategic Opportunities
- India PLI Scheme Incentives:Production-linked incentives for semiconductor packaging are attracting assembly and test investments in Gujarat and Tamil Nadu.
- Battery Management System Integration:Analog front-end consolidation with wireless cell monitoring is opening white space in electrified commercial vehicle architectures.
- EU Green Deal Carbon Targets:Fleet electrification mandates are tightening efficiency standards for power semiconductors in onboard chargers and DC-DC converters.
Industry Challenges
- Automotive Functional Safety Expertise Gap:Shortages of ISO 26262-certified systems engineers are extending development cycles for ASIL-D rated components.
- Legacy ECU Integration Complexity:Domain controller consolidation requires backward compatibility with millions of deployed engine control modules using heterogeneous communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Chip Market |
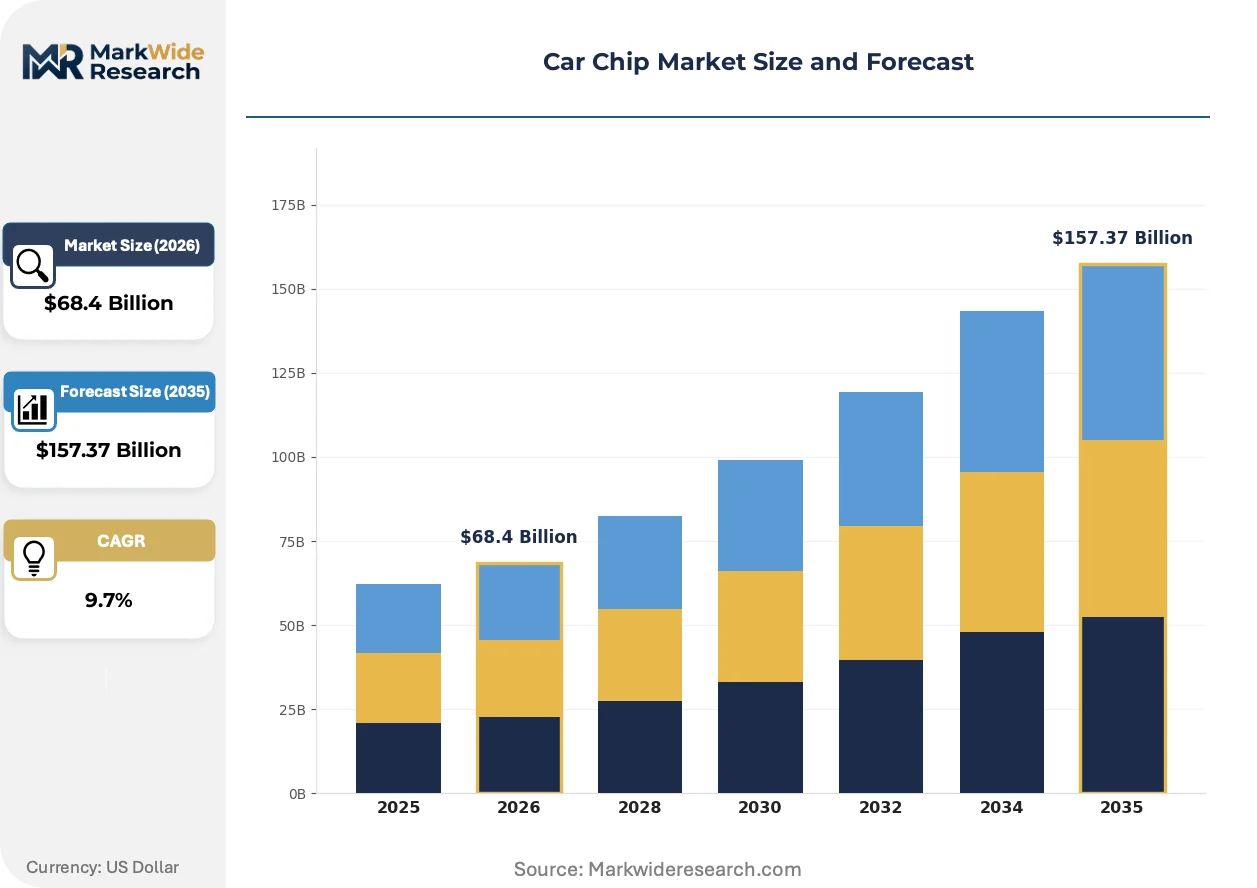
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontroller, Processor, Sensor, Transceiver Technology: Embedded, Analog, Digital, Power Management Application: Infotainment, Safety, Connectivity, Automation End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, Renesas Electronics Corp., Texas Instruments, onsemi, Analog Devices, Microchip Technology, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Chip Market Trends and Innovations
Real-time processing demands are compressing semiconductor development cycles as vehicle architectures shift from distributed ECUs to centralized compute platforms with zonal gateways.
Silicon carbide MOSFETs are automating thermal management decisions in traction inverters by enabling faster switching frequencies than silicon IGBTs. Tier-1 suppliers in Germany and Japan are qualifying 750-volt and 1200-volt devices for 800-volt battery platforms. This substrate transition is automating the displacement of liquid cooling systems in favor of lighter air-cooled designs.
EU Green Deal carbon targets are tightening semiconductor efficiency standards for electrified fleets through binding CO2 reduction mandates. The regulation is compressing supplier qualification timelines for wide-bandgap devices in onboard chargers. Power module manufacturers in France and Italy are accelerating silicon carbide substrate sourcing to meet 2035 fleet electrification deadlines.
Buyer concentration among German vehicle assemblers is compressing component pricing cycles as Volkswagen Group and BMW consolidate semiconductor procurement through direct foundry relationships. Long-term offtake agreements are displacing spot-market purchasing for microcontroller units and power management ICs. This consolidation is most visible in Stuttgart and Munich supplier ecosystems where tier-1 margins face sustained pressure.
Car Chip Market Segmentation
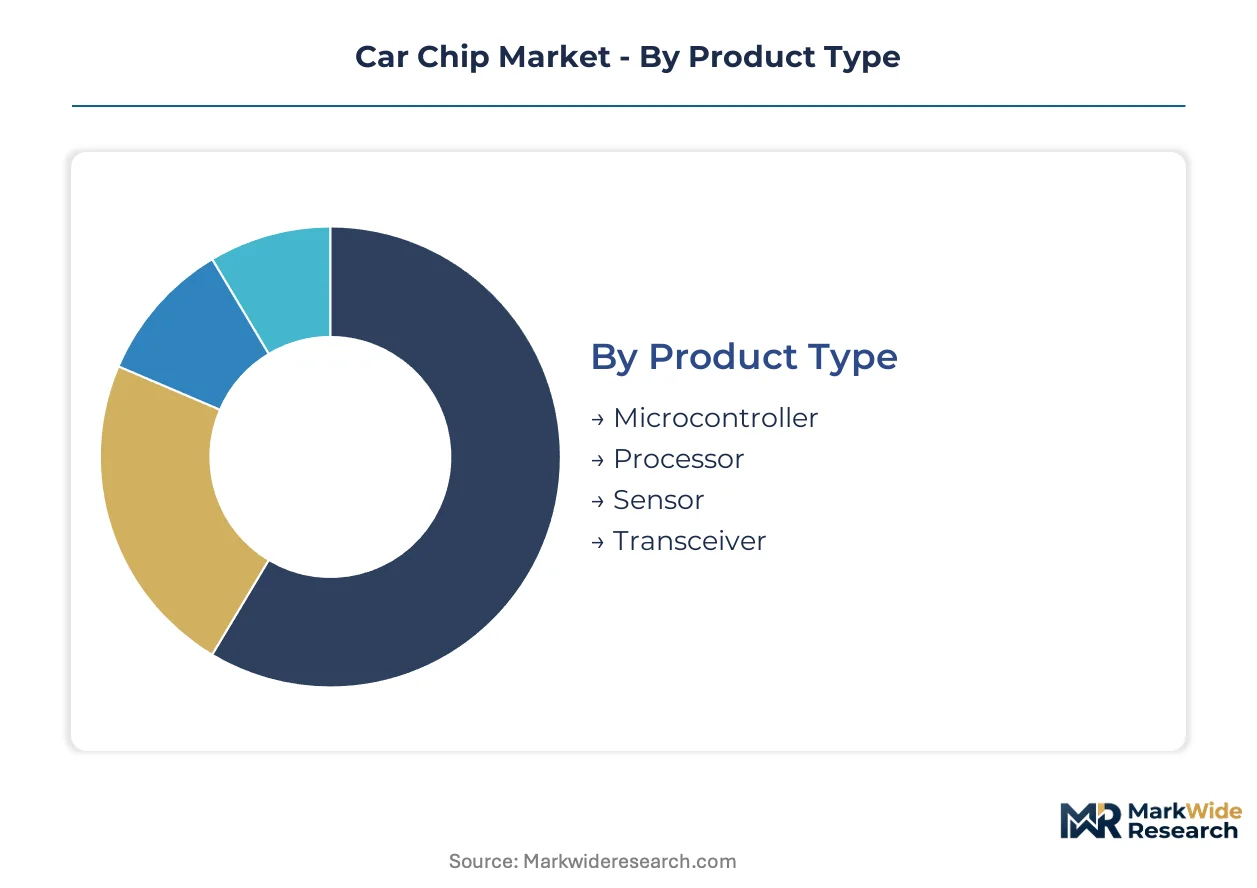
Car chip procurement patterns diverge sharply between high-volume commodity controllers and premium-priced wide-bandgap power devices. Semiconductor suppliers calibrate fab capacity and automotive qualification timelines differently across these tiers. Understanding volume-premium splits within each segmentation dimension reveals where margin pools concentrate versus where scale economies dominate.
Product Type:
Microcontroller units dominate unit shipments while processors command premium pricing per wafer.
- Microcontroller:These 8-bit to 32-bit devices execute real-time control functions across engine management, braking, and body electronics. Demand concentrates in Germany where Bosch and Continental anchor procurement for Volkswagen Group and BMW platforms, driven by NHTSA-mandated ISO 26262 functional safety requirements extending validation cycles.
- Processor:Multi-core SoCs handle sensor fusion and cockpit visualization workloads with automotive-grade reliability targets. Adoption concentrates in autonomous driving domain controllers across Chinese EV platforms, constrained by foundry geographic concentration in Taiwan and South Korea for advanced nodes.
- Sensor:MEMS and image sensors enable environmental perception and in-cabin monitoring.
- Transceiver:CAN-FD and Ethernet PHY devices bridge zonal gateway communication architectures.
Today's leader: Microcontroller. Tomorrow's challenger: Processor.
Technology:
Power Management commands the steepest price escalation as 800-volt electrification multiplies.
- Power Management:Battery management ICs and DC-DC converters regulate voltage across electrified powertrains with silicon carbide and gallium nitride substrates displacing silicon IGBTs. Demand clusters in Stuttgart and Munich supplier ecosystems where Bosch and Infineon qualify wide-bandgap devices for 800-volt architectures, pressured by EU Green Deal carbon targets tightening efficiency standards.
- Embedded:Flash-based MCUs integrate non-volatile memory with deterministic real-time response for safety-critical loops. Deployment concentrates in legacy ECU consolidation projects across Japanese and German vehicle assemblers, constrained by shortages of ISO 26262-certified systems engineers extending development timelines.
- Analog:Signal conditioning and interface devices bridge physical sensors to digital processing chains.
- Digital:Logic and memory devices support infotainment and connectivity subsystems.
Power Management claims the fastest margin expansion. Embedded retains the deepest installed base.
Application:
Safety applications justify premium pricing through ASIL-D certification requirements while Infotainment drives volume.
- Safety:Airbag deployment, antilock braking, and electronic stability control demand analog front-ends and MCUs with deterministic fault response. Procurement concentrates in German tier-1 supply chains serving NHTSA-regulated US market entry, with REACH substance restrictions forcing substrate material reformulations that extend qualification timelines.
- Infotainment:Display controllers and audio DSPs manage cockpit experience with consumer-grade refresh cycles compressed into automotive timelines. Volume concentrates in Chinese domestic brands and Tesla's vertical integration, driven by MIIT domestic content requirements and consumer expectation convergence with mobile devices.
- Connectivity:V2X modems and telematics units enable over-the-air updates and fleet data extraction.
- Automation:Lidar point-cloud processors and radar DSPs feed sensor fusion pipelines.
Safety captures the highest certification premium. Automation faces the longest qualification runway.
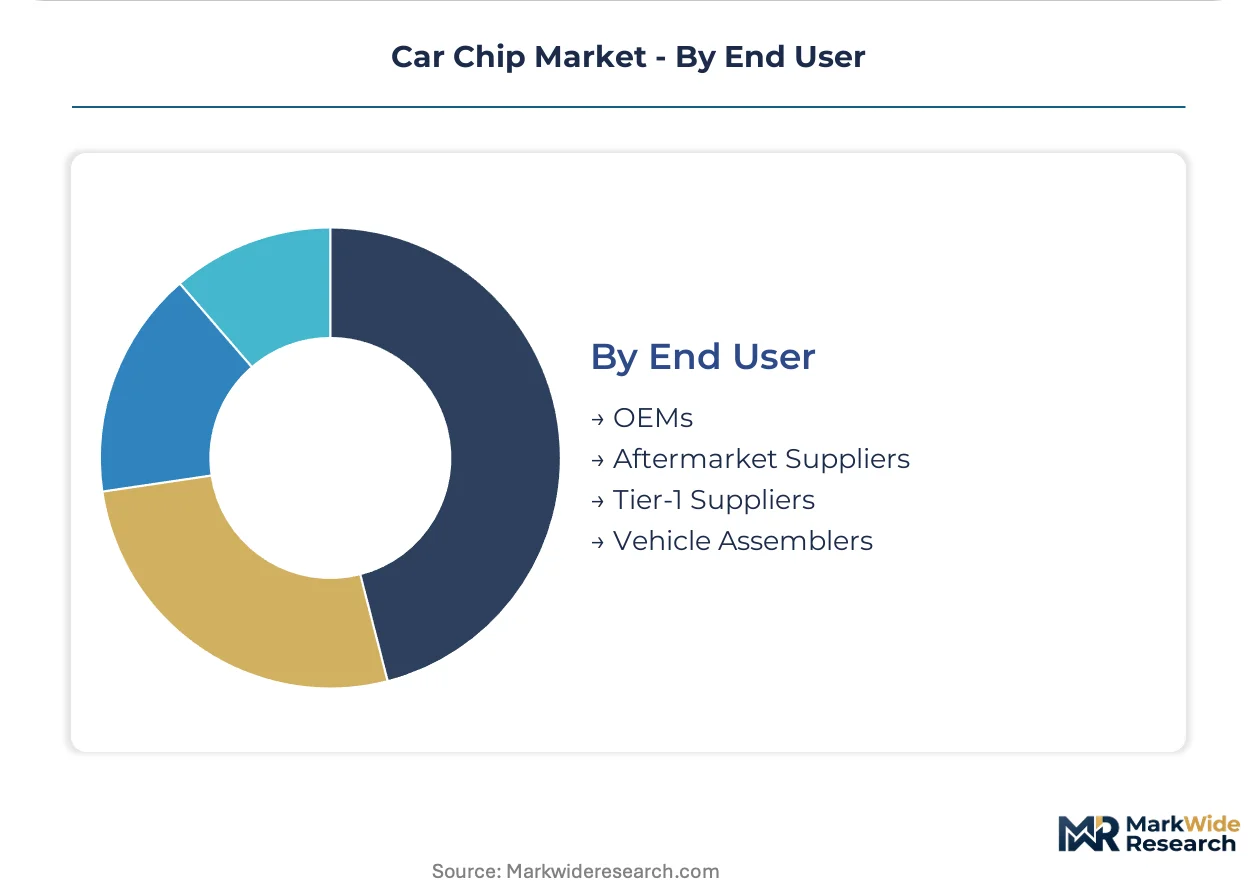
End User:
Tier-1 Suppliers mediate the largest contract value while OEM direct sourcing is accelerating fastest.
- Tier-1 Suppliers:Continental, Bosch, and Denso aggregate semiconductor demand across multiple vehicle platforms, consolidating microcontroller and power management IC procurement through long-term offtake agreements. Their concentration in Germany's Stuttgart-Munich corridor compresses component pricing cycles as Volkswagen Group and BMW bypass traditional distribution.
- OEMs:Tesla, BYD, and Volkswagen Group now contract directly with foundries for custom silicon, capturing margin previously allocated to tier-1 distribution. This shift concentrates in 800-volt battery platforms and autonomous compute stacks where differentiation requires co-designed semiconductors, constrained by foundry capacity allocation rigidity.
- Aftermarket Suppliers:Replacement ECUs and diagnostic tools serve vehicle parc maintenance.
- Vehicle Assemblers:Contract manufacturers integrate semiconductors into complete powertrain modules.
Tier-1 Suppliers retain contract volume leadership. OEMs are capturing strategic silicon relationships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage is accelerating as foundries migrate toward jurisdictions with lower compliance costs for automotive-grade qualification. The EU Green Deal and NHTSA mandates create divergent cost structures that reshape where silicon carbide substrates and microcontroller packaging concentrate.
United States
NHTSA ISO 26262 enforcement drives microcontroller demand for braking and steering systems. The Inflation Reduction Act domestic content provisions incentivize battery management IC sourcing from North American packaging facilities. Detroit-Windsor corridor suppliers concentrate ASIL-D component validation for electrified truck platforms.
Germany
Volkswagen Group and BMW consolidate direct foundry contracts for 800-volt powertrain silicon. EU Green Deal binding CO2 fleet targets compress supplier qualification timelines for wide-bandgap devices. Stuttgart-Munich corridor anchors Bosch and Infineon production of silicon carbide substrates with automotive-grade defect tolerances.
China
BYD and domestic EV brands multiply demand for domain controller processors and battery management systems. MIIT enforces GB standards and domestic chip content ratios through dual carbon goals. Yangtze River Delta clusters around Shanghai concentrate foundry capacity for mature-node automotive MCUs.
Japan
Renesas and Denso anchor procurement for hybrid powertrain controllers with deterministic real-time requirements. METI semiconductor revitalization policies subsidize domestic 40nm automotive node production. Nagoya-Tokyo corridor concentrates sensor fusion module assembly for Toyota and Honda electrification roadmaps.
India
Commercial vehicle electrification and two-wheeler battery management drive analog front-end demand. PLI scheme production-linked incentives attract semiconductor packaging investments to Gujarat and Tamil Nadu. Chennai-Bangalore corridor emerges as assembly and test capacity for tier-1 suppliers serving export markets.
Car Chip Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with IDMs controlling substrate production and fabless designers capturing domain controller value. Market structure concentrates around three vertical tiers: integrated device manufacturers with captive silicon carbide growth, automotive-qualified foundry services, and tier-1 system integrators with backward component sourcing. Dominant competitive moves include long-term offtake agreements displacing spot purchasing and direct OEM-foundry partnerships bypassing traditional distribution.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics exemplify the substrate-integrated archetype with in-house silicon carbide production. NXP Semiconductors anchors the vehicle networking specialist tier. These three entities occupy positions across the microcontroller, power management, and processor segments where automotive qualification timelines create defensive moats.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| Renesas Electronics Corp. |
| Texas Instruments |
| onsemi |
| Analog Devices |
| Microchip Technology |
| Robert Bosch GmbH |
| Others |
Pricing and Supply Chain Analysis
ISO 26262-certified systems engineers concentrated in Germany's Stuttgart-Munich corridor feed labor-cost differentials that widen spreads between ASIL-D premium tiers and commodity microcontroller pricing. Tier-1 procurement consolidation by Volkswagen Group and BMW compresses channel margins while elevating qualification premiums for safety-critical silicon.
Pricing Analysis
Distributor margins on automotive-grade microcontrollers have compressed to single-digit percentages as OEMs negotiate direct foundry contracts for power management ICs. Pricing stratifies across ASIL-D certified, automotive-grade, and industrial-crossover tiers, with certification level and volume scale driving differentiation. Cost compression in 28nm and below process nodes is intensifying because foundry capacity allocation rigidity favors consumer electronics. Tier-1 suppliers serving German vehicle assemblers exhibit highest price sensitivity, while custom silicon co-design programs for 800-volt platforms show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with advanced automotive node production concentrated in Taiwan and South Korea for 28nm and below technologies. Silicon carbide substrates draw from Japan, Germany, and the United States, while packaging capacity feeds from Malaysia, Vietnam, and China's Yangtze River Delta. Raw material dependencies center on high-purity silicon wafers, rare earth elements for magnetics, and epoxy molding compounds subject to REACH substance restrictions. Tariff exposure on Chinese-packaged components creates structural risk. Distribution runs through tier-1 system integrators with backward component sourcing into direct OEM-foundry partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate in-house production is compressing manufacturing costs while 800-volt electrification expands premium-tier addressable market. Margin expansion hinges on qualification timeline compression and captive supply chain control.
For Market Incumbents: Deepen silicon carbide substrate captive production to defend against Chinese foundry entrants qualifying automotive-grade wide-bandgap devices. Expand ASIL-D certification capacity in Germany to offset ISO 26262 systems engineer shortages extending development cycles. Prioritize long-term offtake agreements with Volkswagen Group and BMW that lock in microcontroller volume before direct OEM-foundry relationships mature. For New Entrants and Emerging Players: India's PLI scheme in Gujarat and Tamil Nadu opens a window for packaging and test investments serving export markets with lower compliance cost bases. Target battery management system integration for commercial vehicle electrification, where analog front-end consolidation with wireless cell monitoring remains underpenetrated. Pursue joint qualification programs with tier-1 suppliers lacking in-house silicon carbide expertise. For Investors and Strategic Acquirers: Tier-1 automotive suppliers are the most active acquirer in this space, seeking domain controller capabilities and wide-bandgap packaging expertise. Long-term viability favors vertically integrated specialists with captive substrate production and automotive qualification moats. Watch silicon carbide wafer price stabilization as the inflection indicator for power semiconductor margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Integration | Infineon and STMicroelectronics anchor competitive positioning through in-house crystal growth capacity. |
| Direct OEM-Foundry Partnership | Tesla and Volkswagen Group bypass tier-1 distribution to capture margin and accelerate customization cycles. |
| ASIL-D Certification Investment | Bosch and Continental extend validation timelines to meet NHTSA functional safety mandates for braking systems. |
| India PLI Scheme Participation | Assembly and test investments in Gujarat reduce geographic concentration risk for mature-node packaging. |
| Battery Management System Consolidation | Texas Instruments and Analog Devices capture analog front-end value in 800-volt commercial vehicle architectures. |
Research Methodology
Multiple input streams — primary interviews with tier-1 supplier procurement officers, OEM platform engineers, and semiconductor foundry account managers; secondary validation through SEC 10-K filings, IHS Markit vehicle production databases, and MIIT GB standards documentation — were reconciled through bottom-up and top-down triangulation. Automotive-grade qualification timelines and silicon carbide substrate capacity announcements anchored supply-side modeling.
Historical shipment data cross-referenced against panel input from Bosch, Infineon, and NXP Semiconductors commercial teams shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology node, application safety integrity level, propulsion architecture, and regional production cluster. CAGRs derived from unit-volume trajectory analysis weighted by content-per-vehicle escalation in electrified platforms. Foundry capacity allocation rigidity and EU Green Deal compliance cost differentials fed industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH substance restriction acceleration or Taiwan Strait logistics disruption. Forecasts reflect documented assumptions regarding silicon carbide substrate yield improvement and ISO 26262 certification pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Poe Chipsets Market