
 Global Neural Processors Market | 2026-2036
Global Neural Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neural Processors Market Foresight
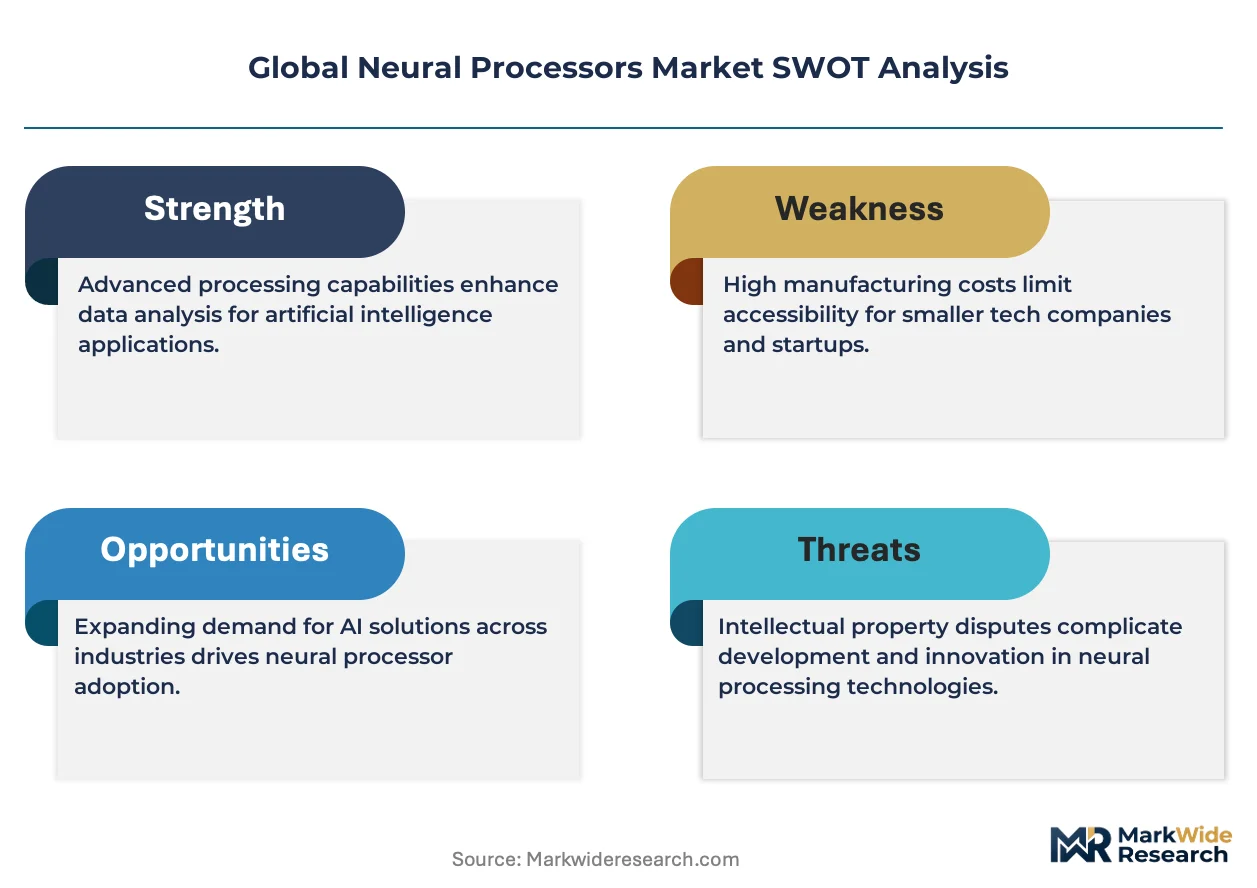
Edge inference revenue is reshaping margin pools across the neural processor value chain, pulling profitability away from cloud training clusters toward on-device silicon. NVIDIA Corporation dominates data center training with its proprietary interconnect and software stack. Qualcomm specializes in low-power mobile inference, occupying the smartphone application tier through integrated Snapdragon platforms. Intel Corporation leverages foundry partnerships and x86 ecosystem control to compete across both edge and cloud deployment scenarios.
Neural processors are integrated circuits architected for parallel matrix operations, typically fabricated on sub-5nm process nodes with dedicated tensor cores or systolic arrays that execute multiply-accumulate cycles at teraflop-scale throughput. Their primary commercial purpose is to accelerate machine learning inference and training while reducing energy consumption versus general-purpose CPUs. Application-specific integrated circuits capture the dominant value share where performance-per-watt requirements are fixed and volumes justify mask costs. Field-programmable gate arrays serve prototyping and low-volume defense or aerospace programs where reconfigurability outweighs unit economics. Deep learning accelerators within the technology dimension are expanding fastest as transformer-based models proliferate across enterprise and consumer workloads.
The FDA regulates AI-enabled medical devices through premarket review pathways that directly shape neural processor qualification requirements for healthcare edge deployments. The EU AI Act imposes risk-tiered conformity assessments that restrict high-risk autonomous system processors to certified supply chains. China's SAMR and MIIT enforce GB standards and dual carbon goals that constrain data center processor power density and foreign semiconductor procurement. Stakeholders must monitor how divergent national AI governance frameworks fragment certification requirements and force regional silicon sourcing strategies.
Market Dynamics
Transformer model proliferation is compressing inference latency requirements across enterprise workloads, forcing silicon architects to trade precision for throughput while cloud service providers consolidate procurement around programmable accelerator platforms.
Growth Catalysts
- EU AI Act risk-tiered conformity:High-risk autonomous system mandates are creating certified supply chain premiums for neural processors meeting MDR-equivalent reliability standards in healthcare edge deployments.
- Dual carbon goals in China:SAMR enforcement of GB standards on data center power density is accelerating domestic procurement of sub-5nm inference accelerators with teraflop-per-watt efficiency thresholds.
- FDA premarket review pathways:AI-enabled medical device qualification requirements are pulling specialized neural processors into diagnostic imaging and surgical robotics end-uses.
Market Restraints
- Advanced node mask cost volatility:Sub-3nm EUV lithography reticle sets exceed $500 million per design iteration, concentrating application-specific integrated circuit development among foundry customers with captive volume commitments.
- Wafer supply concentration:Taiwan-based advanced logic capacity controls over 90 percent of leading-edge neural processor fabrication, exposing the value chain to single-point geopolitical disruption.
- General-purpose GPU substitution:NVIDIA's CUDA software moat sustains programmable accelerator preference over fixed-function neural processors in research and development environments where model architectures shift quarterly.
Strategic Opportunities
- Germany sovereign AI infrastructure:Federal Ministry of Digital Affairs funding for Gaia-X compliant data centers is opening procurement channels for EU-manufactured inference accelerators with supply chain traceability documentation.
- Neuromorphic silicon convergence:Spiking neural network architectures paired with event-based sensors are creating sub-milliwatt inference tiers for always-on voice and vision endpoints in battery-constrained devices.
- India PLI scheme incentives:Production-linked incentive thresholds for semiconductor assembly and testing are attracting neural processor packaging investments serving Middle East and African distribution channels.
Industry Challenges
- Silicon-photonics integration complexity:Co-packaged optical interconnect qualification timelines extend neural processor time-to-market by 18-24 months versus electrical-only alternatives.
- Model compression expertise scarcity:Quantization-aware training and pruning optimization require rare combinations of hardware architecture and machine learning research skills that command compensation premiums exceeding 40 percent above standard VLSI design roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neural Processors Market |
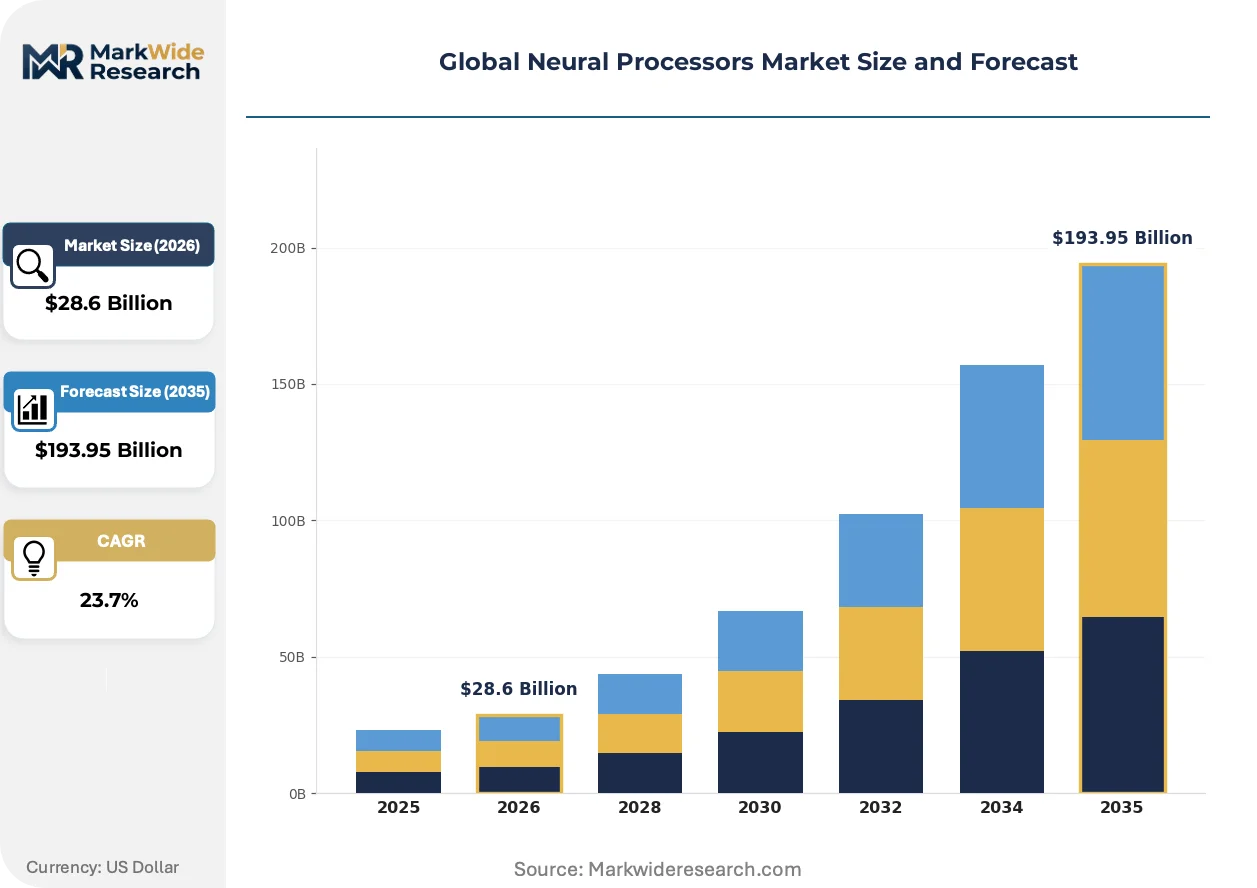
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $193.95 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Application-Specific Integrated Circuits, Field-Programmable Gate Arrays, Digital Signal Processors, General-Purpose Processors Technology: Neuromorphic Computing, Deep Learning Accelerators, Tensor Processing Units, Spiking Neural Networks Application: Smartphones, Autonomous Machines, Personal Assistants, Cybersecurity Systems, Intelligent Video Cameras End User: Consumer Electronics Manufacturers, Cloud Service Providers, Semiconductor Foundries, Research Institutions |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Advanced Micro Devices, Qualcomm, Arm Limited, Samsung Electronics, Google, BrainChip, Graphcore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neural Processors Market Shifts & Advancements
Silicon architectures are fragmenting between precision-scalable inference engines and fixed-function training monsters, with software-defined quantization emerging as the decisive layer where competitive advantage crystallizes.
Dynamic voltage and frequency scaling with per-layer precision adjustment is rendering obsolete static 8-bit integer inference pipelines that dominated mobile neural processors through 2024. Automotive tier-one suppliers are adopting these adaptive precision engines for real-time sensor fusion, compressing validation cycles by eliminating separate INT8 and FP16 silicon variants from bill-of-materials.
REACH substance restrictions on PFAS in semiconductor manufacturing are forcing wet chemistry process requalification across EU-bound neural processor supply chains. Foundry partners are migrating to fluorine-free etching chemistries, extending qualification timelines but securing CE marking eligibility for high-performance computing deployments in regulated European enterprise environments.
Cloud service providers are consolidating inference procurement around multi-tenant programmable accelerators with fine-grained power metering. Amazon Web Services and Microsoft Azure are displacing fixed-function ASIC reservations with usage-based instance contracts, concentrating demand in United States and Chinese hyperscaler data centers where workload multiplexing economics favor reconfigurable tensor core architectures over single-purpose vision or language accelerators.
Global Neural Processors Market Segmentation
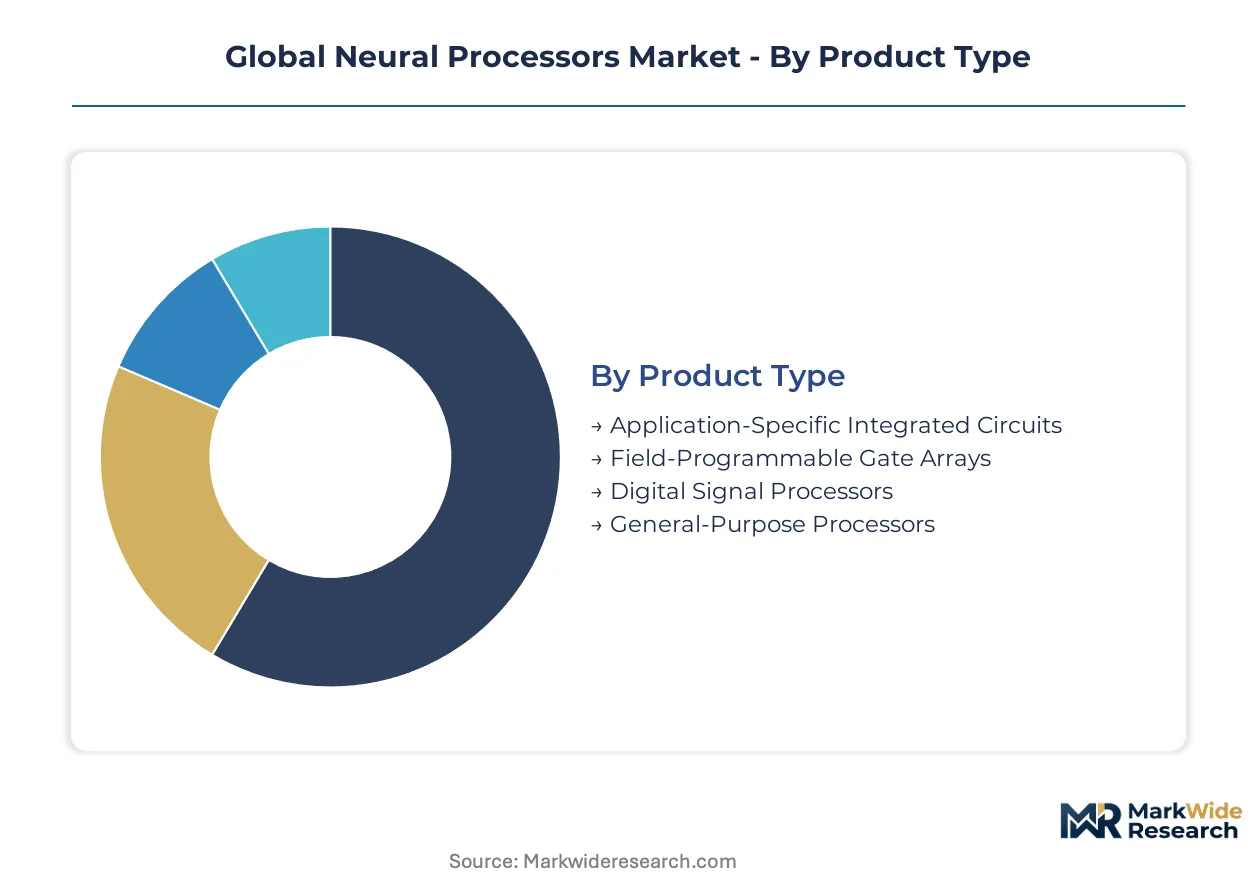
Neural processor procurement cycles vary dramatically across deployment contexts, from smartphone refresh schedules measured in months to foundry qualification timelines spanning years. Understanding these velocity differentials shapes inventory strategy and technology roadmap prioritization for silicon vendors and their customers.
Product Type:
Cycle times compress from years for mask-programmed silicon to weeks for reconfigurable alternatives, creating divergent cash conversion profiles across the product matrix.
- Application-Specific Integrated Circuits:Fixed-function designs fabricated on sub-5nm nodes deliver teraflop-per-watt efficiency through dedicated systolic arrays and tensor cores. Demand concentrates in United States hyperscaler data centers where cloud service providers commit to multi-year volume contracts that amortize $500 million mask set investments across captive inference workloads.
- Field-Programmable Gate Arrays:Reconfigurable logic fabrics enable post-deployment algorithm updates without silicon respins, extending useful life in defense and aerospace programs. Germany's Federal Ministry of Defense and similar procurement bodies in France prioritize FPGA-based neural processors for mission-critical autonomous systems requiring field-upgradeable certification.
- Digital Signal Processors:Programmable architectures with vector execution units serve audio and sensor fusion workloads in battery-constrained devices. Qualcomm integrates DSP clusters within Snapdragon platforms for smartphone manufacturers in South Korea and China.
- General-Purpose Processors:x86 and ARM cores with SIMD extensions handle inference fallback when specialized accelerators face software compatibility constraints. Intel and AMD supply these to enterprise server deployments across Japan and Australia where legacy application preservation outweighs efficiency optimization.
Application-Specific Integrated Circuits dominate installed base. Field-Programmable Gate Arrays are where expansion concentrates for regulated autonomous system deployments.
Technology:
Cost tiers separate commodity inference engines from research-grade architectures, with precision requirements and power budgets determining which technology commands premium pricing.
- Deep Learning Accelerators:Massively parallel matrix multiplication engines optimized for transformer inference at batch-scale throughput. Cloud service providers in the United States and China consolidate procurement around these programmable platforms, displacing fixed-function alternatives as model architectures shift quarterly.
- Neuromorphic Computing:Event-driven architectures with analog-memristive synapses execute spiking neural networks at sub-milliwatt power draws. Research institutions in Switzerland and the Netherlands deploy these for always-on voice and vision endpoints in battery-constrained IoT sensors.
- Tensor Processing Units:Google-designed systolic arrays with bfloat16 precision target training and inference within Alphabet's cloud infrastructure. TPU availability remains restricted to Google Cloud Platform customers, creating supply concentration in United States enterprise workloads.
- Spiking Neural Networks:Biological neuron-inspired architectures process temporal data through discrete spike events rather than continuous activation values. IBM and Intel research divisions supply experimental SNN processors to neuromorphic computing consortia in Germany and the United Kingdom.
Deep Learning Accelerators dominate installed base. Neuromorphic Computing is climbing the fastest as edge power constraints tighten across consumer and industrial endpoints.
Application:
Volume concentration separates billion-unit smartphone tiers from thousand-unit surgical robotics deployments, with qualification burdens inversely correlated with shipment scale.
- Smartphones:Snapdragon and Dimensity platforms integrate neural processing units within mobile SoCs for on-device photography, translation, and voice recognition. Apple, Samsung, and Xiaomi collectively drive procurement volume, with China-based ODMs capturing assembly concentration.
- Autonomous Machines:Automotive-grade neural processors with ISO 26262 functional safety certification execute real-time sensor fusion for robotic navigation. NVIDIA Drive and Mobileye EyeQ platforms serve German automotive tier-ones including Bosch and Continental.
- Intelligent Video Cameras:Edge inference engines with INT8 quantization enable real-time object detection without cloud round-trips. Hikvision and Dahua in China, alongside Axis Communications in Sweden, integrate these for enterprise security and smart city deployments.
- Cybersecurity Systems:Hardware-accelerated pattern matching identifies anomalous network traffic at line-rate throughput. Palo Alto Networks and Fortinet in the United States deploy these for enterprise firewall appliances.
- Personal Assistants:Low-power wake-word engines and natural language understanding accelerators enable ambient voice interfaces. Amazon Echo and Google Nest devices source these from MediaTek and Amlogic for consumer electronics manufacturers in Taiwan and mainland China.
Smartphones dominate installed base. Autonomous Machines are gaining share fastest as automotive safety regulations mandate redundant neural processing for Level 3+ automation.
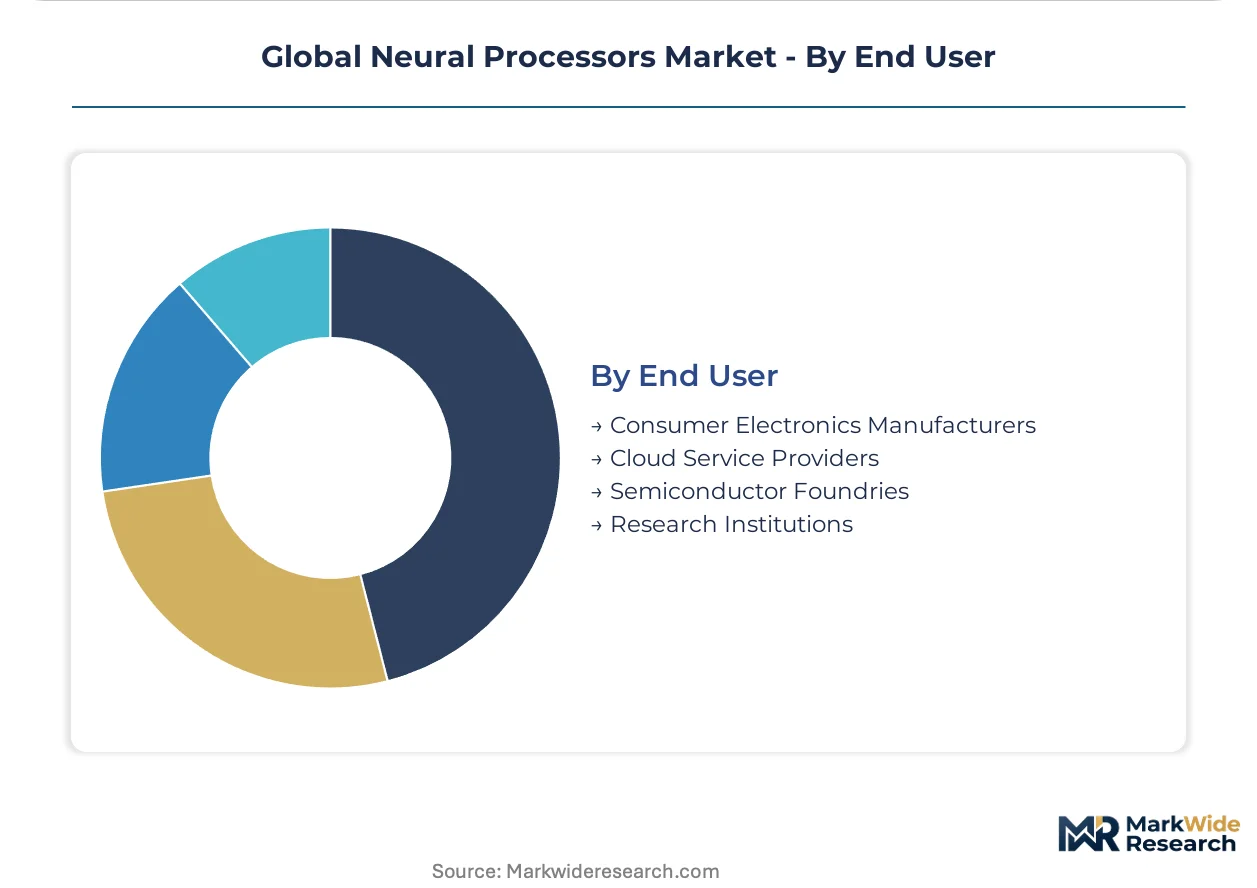
End User:
Customer type determines procurement sophistication, with cloud service providers demanding programmable roadmaps and foundries requiring process-portable IP.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Alibaba Cloud negotiate multi-year accelerator supply agreements with fine-grained power metering and usage-based instance economics. These hyperscalers in the United States and China favor reconfigurable tensor core architectures over single-purpose vision or language accelerators.
- Consumer Electronics Manufacturers:Smartphone and appliance OEMs prioritize bill-of-materials cost and time-to-market over peak performance. Foxconn, Pegatron, and BYD Electronics in Taiwan and China manage procurement for Apple, Samsung, and Xiaomi assembly programs.
- Semiconductor Foundries:TSMC, Samsung Foundry, and Intel Foundry Services license neural processor IP for integration into customer SoC designs. These Taiwan, South Korea, and United States-based facilities require DFM-optimized implementations across process nodes from 7nm to 2nm.
- Research Institutions:MIT CSAIL, ETH Zurich, and Tsinghua University acquire experimental architectures for algorithm-hardware co-design studies. Academic procurement favors FPGA-based prototyping platforms and neuromorphic test chips with open programming models.
Consumer Electronics Manufacturers dominate installed base. Cloud Service Providers are where expansion concentrates as inference workloads migrate from training clusters to multi-tenant data centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States hyperscalers prioritize programmable training clusters, Chinese deployments emphasize sovereign inference infrastructure, and European procurement channels demand certified supply chain traceability for regulated edge applications.
United States
FDA premarket review pathways for AI-enabled medical devices are accelerating specialized neural processor qualification in diagnostic imaging and surgical robotics. Amazon Web Services and Microsoft Azure negotiate multi-year accelerator supply agreements with fine-grained power metering requirements. The Boston-Cambridge corridor anchors healthcare edge deployments, while Seattle and San Francisco Bay Area clusters concentrate cloud service provider procurement.
China
SAMR enforcement of GB standards on data center power density is accelerating domestic procurement of sub-5nm inference accelerators with teraflop-per-watt efficiency thresholds. MIIT dual carbon goals constrain foreign semiconductor procurement while favoring indigenous foundry capacity expansion. Shenzhen and Beijing-Tianjin-Hebei clusters dominate smartphone SoC integration for Xiaomi and ODM assembly programs serving export markets.
Germany
Federal Ministry of Digital Affairs funding for Gaia-X compliant data centers is opening procurement channels for EU-manufactured inference accelerators with supply chain traceability documentation. KBA automotive safety regulations mandate redundant neural processing for Level 3+ automation systems. Bavaria and Baden-Württemberg host automotive tier-one suppliers including Bosch and Continental integrating NVIDIA Drive and Mobileye EyeQ platforms.
South Korea
MFDS medical device regulations are tightening conformity assessment requirements for AI-enabled diagnostic equipment deploying edge neural processors. Samsung Foundry and SK Hynix anchor advanced packaging investments serving hyperscaler customers across the Pacific Rim. Seoul Capital Area concentration spans both memory fabrication and system semiconductor design for smartphone and automotive end-uses.
Japan
METI semiconductor industry revitalization programs are subsidizing domestic neural processor design capabilities for automotive and industrial automation applications. PMDA guidance on AI-enabled medical devices shapes edge deployment qualification timelines for diagnostic imaging equipment. Tokyo-Osaka-Nagoya industrial corridor hosts precision manufacturing clusters integrating neuromorphic silicon for always-on sensor endpoints.
Global Neural Processors Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The neural processor market structures around three distinct competitive layers: hyperscale cloud service providers with captive silicon design teams, fabless semiconductor specialists licensing IP across foundry ecosystems, and integrated device manufacturers controlling captive fabrication and packaging capacity. Strategic moves concentrate on multi-year volume commitments that amortize mask set investments, alongside software stack differentiation that sustains programmable accelerator preference over fixed-function alternatives.
Within the fabless specialist tier, NVIDIA Corporation and Qualcomm exemplify divergent architectural bets—one dominating data center training through proprietary interconnect and software moats, the other occupying smartphone application tiers through integrated mobile platforms. Intel Corporation sits across both edge and cloud deployment scenarios, leveraging foundry partnerships and x86 ecosystem control. BrainChip and Graphcore represent neuromorphic and data center training archetypes respectively, anchoring experimental architecture development for spiking neural networks and massively parallel matrix engines.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Advanced Micro Devices |
| Qualcomm |
| Arm Limited |
| Samsung Electronics |
| BrainChip |
| Graphcore |
| Others |
Supply & Pricing Matrix
The Kaohsiung-Los Angeles transpacific corridor anchors neural processor logistics, with containerized freight rate volatility feeding directly into foundry pricing power and downstream tier differentiation between hyperscale contract volumes and spot-market procurement.
Pricing Analysis
Long-term offtake contracts dominate hyperscaler procurement, locking in multi-year volume commitments that amortize mask set investments across captive inference workloads. Price differentiation hinges on certification grade—FDA premarket clearance for medical edge deployments commands substantial premiums over consumer-grade silicon—and volume scale, with cloud service providers extracting steepest discounts. Cost compression in smartphone-tier application processors is intensifying because MediaTek and UNISOC are displacing premium Snapdragon platforms in China and India. Consumer electronics manufacturers exhibit highest price sensitivity, while German automotive tier-ones tolerate premium pricing for ISO 26262-certified safety silicon.
Supply Chain Analysis
Extended payment terms from Taiwan-based foundries to EUV equipment vendors are cascading through capital structure constraints, compressing working capital availability for fabless design houses. Supply concentrates in Taiwan, South Korea, and the United States, with TSMC controlling over ninety percent of leading-edge logic capacity. Raw material dependencies center on neon gas from Ukrainian purification facilities, high-purity silicon wafers from Japan's Shin-Etsu and SUMCO, and EUV photoresists from JSR and Tokyo Ohka Kogyo. Single-source vulnerability around Taiwan Strait geopolitics represents the dominant structural risk. Distribution runs through direct foundry relationships for hyperscalers, with smartphone OEMs sourcing through Taiwan-based ODMs including Foxconn and Pegatron.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural processors sit in early-cycle expansion as transformer architectures proliferate across enterprise and consumer workloads, with edge inference penetration in automotive and medical devices providing durable demand tailwinds.
For Market Incumbents: Pre-empt neuromorphic silicon convergence by acquiring event-based sensor fusion IP before automotive tier-ones consolidate procurement around spiking neural network platforms. Defend against Qualcomm's Snapdragon hegemony in smartphone inference by securing exclusive supply agreements with China-based ODMs. Certification investment in MDR-equivalent reliability standards for EU AI Act compliance represents the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India PLI scheme assembly and testing incentives, serving Middle East and African distribution channels underserved by incumbent packaging investments. Target Gaia-X compliant data center procurement in Germany, where supply chain traceability documentation requirements disadvantage non-EU incumbents. A software-defined quantization go-to-market angle—enabling per-layer precision adjustment without silicon respins—differentiates against static INT8 pipelines. For Investors and Strategic Acquirers: Fabless neuromorphic specialists with analog-memristive synapse IP and automotive safety certification roadmaps represent the highest-conviction acquisition archetype. Long-term viability across a five-to-ten year window rests on defensibility against NVIDIA's CUDA software moat and TSMC foundry access guarantees. The signal to watch is automotive OEM direct silicon design team formation—BMW, Mercedes-Benz, and Volkswagen captive chip initiatives would compress merchant silicon addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | MDR-equivalent reliability standards unlock high-risk autonomous system procurement in Germany and France. |
| Neuromorphic IP Acquisition | Event-based sensor fusion capabilities address sub-milliwatt inference requirements in battery-constrained automotive endpoints. |
| India PLI Scheme Participation | Production-linked incentives for assembly and testing secure packaging capacity serving Middle East and African channels. |
| Software-Defined Quantization Platform | Per-layer precision adjustment eliminates separate INT8 and FP16 silicon variants from automotive bill-of-materials. |
| Gaia-X Supply Chain Documentation | Traceability certification opens Federal Ministry of Digital Affairs funding channels for EU-manufactured inference accelerators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, foundry capacity announcements, and regulatory filings from FDA, EMA, and SAMR. Primary interviews engaged silicon architects at fabless design houses, procurement officers at cloud service providers, regulatory affairs leads at medical device OEMs, and automotive platform engineers at Tier 1 suppliers. Secondary sources included SEC 10-K and 20-F filings, EU AI Act implementation guidance, GB standards documentation from SAMR, and technical proceedings from ISSCC and VLSI Symposium. Bottom-up unit shipment estimates triangulated against top-down wafer allocation forecasts from foundry equipment utilization data.
Forecast inputs incorporate technology node migration curves, transformer model parameter growth trajectories, and regional regulatory enforcement timelines across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application tier, end-user procurement sophistication, and geographic regulatory cluster. CAGRs derived from slope-intercept fitting against historical silicon content growth in comparable compute-intensive markets. Industry-specific inputs include EUV lithography cost trajectories and automotive safety certification velocity.
Stress conditions across Taiwan Strait logistics disruption, EU AI Act enforcement severity, and transformer architecture obsolescence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about foundry capacity expansion schedules and hyperscaler inference workload migration patterns. Macroeconomic contraction, regulatory acceleration, or algorithm-hardware disaggregation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Application Processor Market
Chipset and Processors
China Edge AI Processor Market