
 North America Wireless Sensors Market | 2026-2036
North America Wireless Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireless Sensors Market Analytics
Multi-source component procurement is consolidating across the North America wireless sensors supply base as OEMs reduce exposure to single foundry dependencies. Texas Instruments Incorporated leverages its captive fab network to sustain die supply continuity for Bluetooth and Zigbee chipsets. Emerson Electric Co. anchors its position through deep calibration expertise in pressure and temperature sensing modules for process industries. Honeywell International Inc. dominates building automation channels with integrated sensor-to-cloud platforms that bypass third-party gateway vendors.
North America wireless sensors are self-contained transducer assemblies that convert physical variables into digital signals for transmission over unlicensed RF spectrum, typically operating at sub-gigahertz or 2.4 GHz bands with power budgets below 100 milliwatts to enable multi-year battery life in untethered installations. Their primary commercial purpose is eliminating wired infrastructure in distributed monitoring environments where conduit costs exceed device economics by an order of magnitude. Temperature sensors and pressure sensors command the deepest margin pools in industrial automation, while proximity sensors are gaining share fastest in automotive occupant detection and warehouse robotics. LoRaWAN technology leads in environmental monitoring and smart agriculture applications where kilometer-range links justify lower data rates, whereas Wi-Fi competes in building automation where existing access point density reduces incremental infrastructure spend.
FCC Part 15 rules govern unlicensed emissions across the United States, while Industry Canada RSS standards enforce parallel constraints north of the border, and both regulators are tightening coexistence requirements as 900 MHz and 2.4 GHz bands saturate with IoT traffic. NIST publications on lightweight cryptography for constrained devices are reshaping firmware development priorities as federal procurement contracts mandate demonstrated compliance. Stakeholders must monitor how forthcoming spectrum reallocation proceedings and cybersecurity labeling programs alter hardware certification timelines and customer qualification cycles.
Market Dynamics
LoRaWAN protocol standardization is compressing deployment timelines for kilometer-range environmental monitoring networks, while FCC spectrum congestion is forcing firmware architects toward adaptive channel-hopping algorithms.
Growth Catalysts
- FCC Part 15 unlicensed spectrum access:The 902-928 MHz ISM band allocation eliminates licensing fees for agricultural moisture monitoring networks across the Great Plains.
- Texas energy sector digitalization:Permian Basin operators are deploying pressure sensor meshes for pipeline integrity monitoring at densities exceeding 500 nodes per wellpad.
- NIST lightweight cryptography frameworks:Federal procurement mandates for demonstrated firmware compliance are accelerating R&D budgets among sensor OEMs bidding on Department of Energy smart grid contracts.
Market Restraints
- Lithium primary battery supply concentration:Cell production for coin-cell form factors concentrates in East Asian chemical processing facilities, exposing North American assemblers to freight cost volatility.
- 900 MHz band saturation:Coexistence failures between LoRaWAN and legacy SCADA radio systems are triggering costly site surveys in industrial corridors around Houston and Calgary.
- Silicon wafer foundry bottlenecks:Mature-node capacity constraints for sub-40nm RF transceiver dies are extending lead times for Zigbee chipset orders beyond 26 weeks.
Strategic Opportunities
- Canadian prairie smart agriculture:Saskatchewan grain cooperatives are piloting soil moisture arrays with satellite backhaul where cellular coverage gaps persist.
- California Title 24 building energy codes:Mandatory daylight harvesting controls in commercial structures are creating specification pull for integrated occupancy-lux sensors.
- Bluetooth Low Energy and energy harvesting convergence:Piezoelectric vibration harvesters paired with BLE 5.3 radios are eliminating battery swaps in rotating machinery monitoring.
Industry Challenges
- RF firmware engineering scarcity:Competent embedded developers with sub-gigahertz stack experience command premium compensation in Austin and Toronto labor markets.
- FCC and Industry Canada dual certification:Cross-border product launches require parallel testing lab engagements, compressing margin on low-volume SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireless Sensors Market |
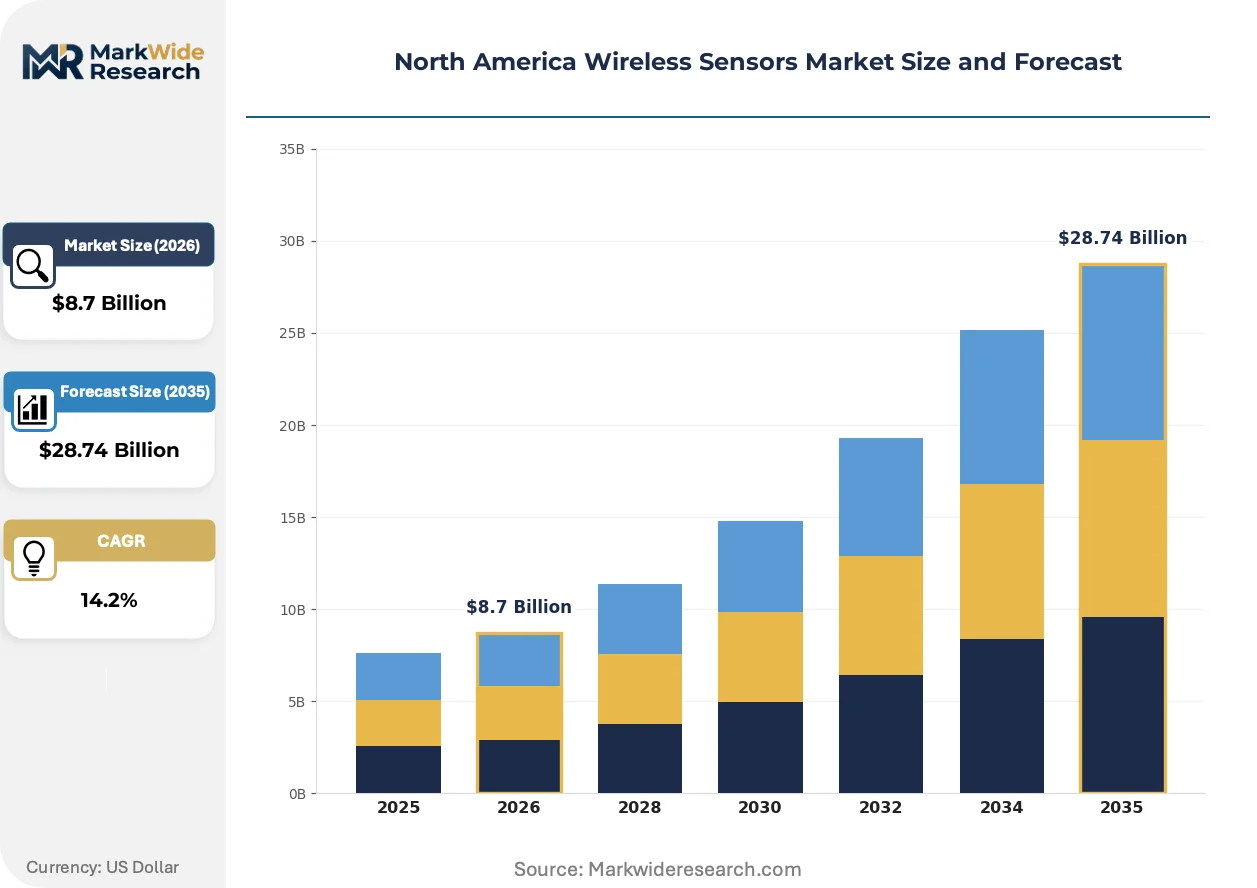
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Humidity Sensors, Proximity Sensors End User: Healthcare, Industrial Automation, Automotive, Smart Homes Technology: Bluetooth, Zigbee, LoRaWAN, Wi-Fi Application: Environmental Monitoring, Smart Agriculture, Asset Tracking, Building Automation |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Texas Instruments Incorporated, ABB Ltd., Siemens AG, TE Connectivity Ltd., STMicroelectronics, NXP Semiconductors, Analog Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireless Sensors Market Evolving Landscape
Mesh networking protocols and ambient energy harvesting are converging to eliminate battery maintenance in permanent installations, while regulatory pressure on spectrum efficiency is accelerating software-defined radio adoption.
Ultra-narrowband modulation is rewriting the economics of wide-area sensor telemetry. The technology squeezes 20 dB link budget improvement from 100 Hz channel widths, enabling single-hop coverage across 15-kilometer rural topographies. Agricultural cooperatives in Nebraska and Alberta are specifying UNB transceivers for grain silo monitoring, collapsing gateway infrastructure requirements by 60 percent versus conventional LoRa implementations.
NIST SP 800-213A device cybersecurity guidance is mandating firmware signing and secure boot chains for federal procurement eligibility. The framework requires attestation of cryptographic module validation, forcing sensor OEMs to redesign bootloaders and key injection processes. Building automation contractors bidding on General Services Administration schedules are prioritizing pre-certified hardware to compress qualification timelines.
Buyers are unbundling sensor hardware from managed connectivity services, shifting procurement toward component-level sourcing with internal DevOps integration. Oilfield service companies in Texas and Oklahoma are hiring RF systems engineers to operate private LoRaWAN networks, displacing turnkey SaaS subscriptions that bundled cellular backhaul. This pattern concentrates most visibly among supermajor operators with existing IT infrastructure and spectrum coordination expertise.
North America Wireless Sensors Market Segmentation
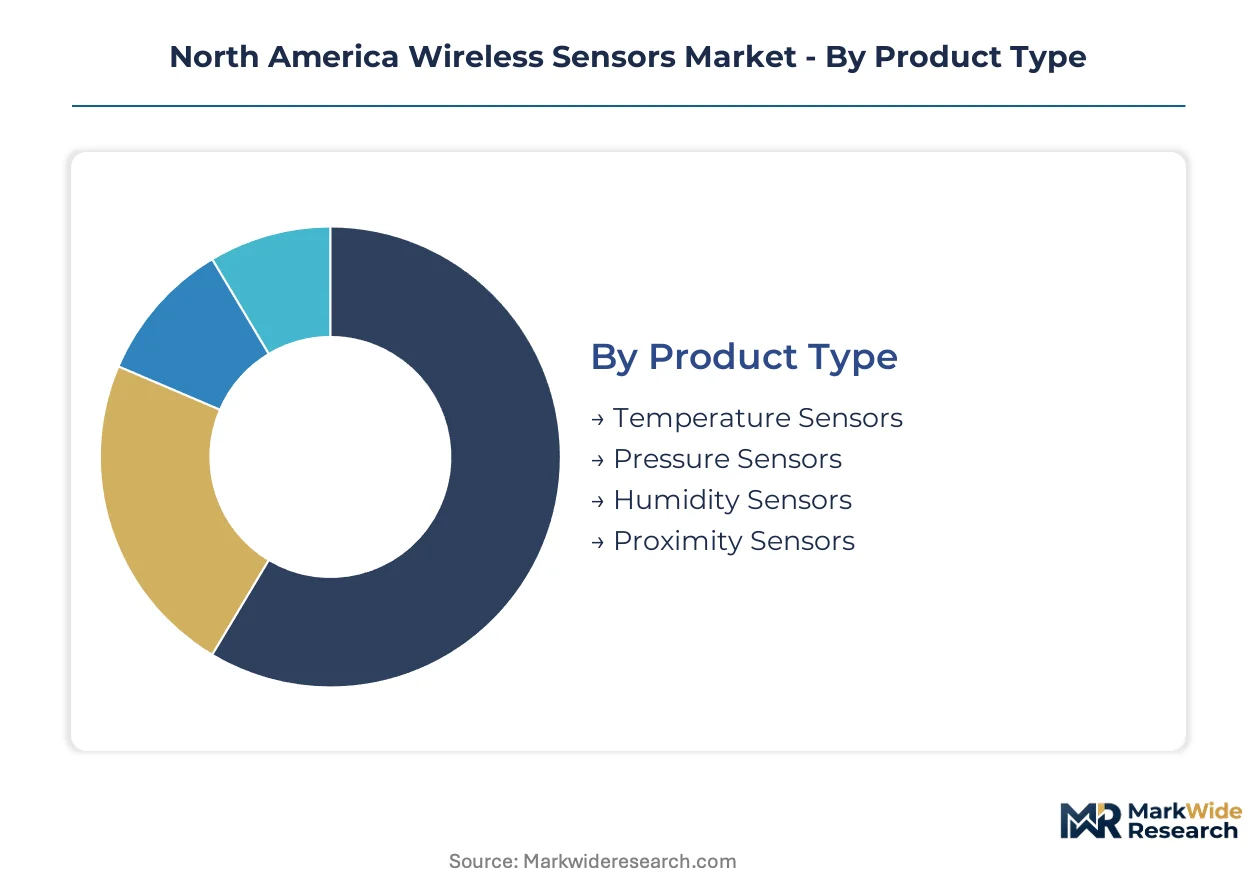
Wireless sensors in North America fragment across four critical dimensions that determine procurement priorities and margin structures. Product type dictates calibration depth and replacement cycles. Technology selection governs power budgets, range requirements, and firmware complexity. Application context determines whether buyers prioritize battery longevity, data throughput, or mesh resilience.
Product Type:
Temperature and pressure sensors dominate unit economics through high-volume industrial contracts, while proximity sensors command premium positioning in safety-critical automotive deployments.
- Temperature Sensors:Thermistor and RTD-based assemblies with ±0.1°C accuracy ratings anchor process control specifications in Texas refinery digitization projects. Permian Basin operators specify these for pipeline thermal monitoring where FCC Part 15 compliance enables unlicensed 900 MHz transmission across wellpad clusters.
- Pressure Sensors:MEMS capacitive and piezoresistive transducers with 0.25% full-scale accuracy serve hydraulic fracturing pressure envelope tracking. Calgary-based oilfield service firms deploy these at densities exceeding 300 nodes per drilling site, driving die-level procurement from captive fab networks.
- Humidity Sensors:Capacitive polymer film sensors with ±2% RH precision support HVAC optimization in California Title 24 compliance projects.
- Proximity Sensors:Inductive and capacitive variants with millimeter-range resolution enable occupant detection in Detroit-area automotive assembly lines.
Today's leader: Pressure sensors. Tomorrow's challenger: Proximity sensors.
End User:
Healthcare and industrial automation split the market between regulated clinical environments and rugged field deployments, with divergent certification burdens and replacement cadences.
- Healthcare:FDA-cleared wireless patient monitoring patches with encrypted BLE 5.2 stacks transmit vital signs across hospital mesh networks. Minnesota medical device clusters specify these for remote patient monitoring programs where NIST cybersecurity frameworks mandate firmware attestation.
- Industrial Automation:Hardened IP67-rated sensor nodes with 10-year battery life target predictive maintenance in Ohio manufacturing corridors. Emerson Electric and Honeywell anchor specifications here through deep calibration expertise and building automation channel dominance.
- Automotive:Tire pressure monitoring systems and battery thermal sensors integrate with vehicle CAN bus architectures for real-time safety telemetry.
- Smart Homes:Occupancy and ambient light sensors with voice assistant integration drive consumer electronics procurement through Amazon and Google ecosystem certification.
Industrial automation captures current volume concentration. Healthcare represents the steepest expansion trajectory as remote monitoring reimbursement codes mature.
Technology:
Protocol selection hinges on range-power-data tradeoffs, with LoRaWAN and Bluetooth anchoring opposite ends of the spectrum efficiency curve.
- Bluetooth:BLE 5.3 stacks with 2 Mbps PHY layer support mesh networking in dense building automation deployments. Texas Instruments sustains die supply continuity for these chipsets through captive fab networks, compressing lead times versus fabless competitors.
- Zigbee:IEEE 802.15.4-based mesh protocols with 250 kbps throughput target smart lighting and energy management in commercial structures. Silicon wafer foundry bottlenecks for sub-40nm RF transceiver dies extend procurement timelines beyond 26 weeks.
- LoRaWAN:Chirp spread spectrum modulation enables 15-kilometer rural links at sub-kilobit rates for agricultural moisture monitoring.
- Wi-Fi:HaLow and legacy 802.11 variants leverage existing access point density in campus and warehouse environments where infrastructure amortization outweighs power constraints.
LoRaWAN leads in environmental telemetry. Bluetooth gains share fastest as energy harvesting eliminates battery maintenance in rotating machinery applications.
Application:
Environmental monitoring and asset tracking diverge in network topology requirements, with the former favoring star architectures and the latter demanding mesh resilience.
- Environmental Monitoring:Multi-sensor air quality nodes with PM2.5 and VOC detection target EPA compliance in California Central Valley agricultural zones. LoRaWAN protocol standardization compresses deployment timelines for these kilometer-range networks.
- Smart Agriculture:Soil moisture arrays with satellite backhaul serve Saskatchewan grain cooperatives where cellular coverage gaps persist. FCC 902-928 MHz ISM band allocation eliminates licensing fees across Great Plains deployments.
- Asset Tracking:Battery-powered GPS-LoRa hybrid tags with geofencing alerts track high-value equipment in Houston petrochemical corridors.
- Building Automation:Integrated occupancy-lux sensors with daylight harvesting algorithms satisfy California Title 24 energy codes in commercial structures.
Building automation commands specification pull from energy code mandates. Smart agriculture climbs fastest as prairie cooperatives pilot satellite-backhaul soil monitoring arrays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors North American wireless sensor deployment density, with Texas energy operators specifying pressure sensor meshes at 500-plus nodes per wellpad. FCC Part 15 unlicensed spectrum rules and NIST cybersecurity frameworks are reshaping procurement requirements across the continent.
United States
Texas refinery digitization and California Title 24 building energy codes drive specification pull for temperature and occupancy-lux sensors. FCC Part 15 governs 902-928 MHz ISM band emissions for agricultural moisture networks. Houston petrochemical corridors concentrate asset tracking deployments where GPS-LoRa hybrid tags monitor high-value equipment.
Canada
Saskatchewan grain cooperatives pilot soil moisture arrays with satellite backhaul where cellular coverage gaps persist. Industry Canada RSS standards enforce coexistence constraints parallel to FCC rules. Calgary-based oilfield service firms deploy pressure sensors at densities exceeding 300 nodes per drilling site.
Mexico
Northern border states attract maquiladora investment in sensor assembly operations serving US industrial automation demand. Mexican federal energy reform programs mandate smart grid monitoring infrastructure. Monterrey manufacturing clusters are integrating wireless telemetry for automotive supplier quality tracking.
North America Wireless Sensors Market Competitive Landscape
Global majors compete with regional champions across calibration expertise and captive fab networks. The vendor base organizes around three tiers: diversified industrial conglomerates with building automation channel dominance, semiconductor specialists sustaining die supply continuity through captive manufacturing, and component-level suppliers anchoring process industry specifications. Consolidation pressures favor M&A activity among calibration-heavy sensor module producers and strategic partnerships linking RF stack developers with energy harvesting technology.
Among diversified industrial conglomerates, Honeywell International Inc. and Emerson Electric Co. occupy positions reflecting deep integration into building automation and process control channels. Texas Instruments Incorporated exemplifies the semiconductor archetype with captive fab networks sustaining Bluetooth and Zigbee chipset supply continuity. These three anchors represent distinct competitive vectors: channel-integrated platforms, calibration expertise, and upstream manufacturing control.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Texas Instruments Incorporated |
| ABB Ltd. |
| Siemens AG |
| TE Connectivity Ltd. |
| STMicroelectronics |
| NXP Semiconductors |
| Analog Devices Inc. |
| Others |
Value Network & Pricing Analysis
Lithium primary battery cell production anchors cost structures through East Asian chemical processing facilities, transmitting freight volatility into tiered hardware pricing across North American assembly operations. Die-level procurement from captive fab networks compresses lead time premiums for Bluetooth and Zigbee chipsets, while fabless competitors absorb margin erosion from mature-node capacity constraints.
Pricing Analysis
Input-cost pass-through from silicon wafer foundry bottlenecks and lithium cell supply concentration shapes a three-tier pricing structure across premium, standard, and economy levels. Certification grade under NIST cybersecurity frameworks and volume scale at the wellpad cluster level drive price differentiation, with federal procurement eligibility commanding substantial premiums. Cost compression in standard-tier pressure sensor modules is intensifying because die supply discontinuity extends procurement timelines. Mid-size oilfield service operators exhibit highest price sensitivity, while supermajor operators with captive IT infrastructure prioritize firmware attestation over unit economics.
Supply Chain Analysis
Photoresist and specialty chemical supply for sub-40nm RF transceiver fabrication rests on Japanese and South Korean producers, with mature-node silicon sourcing concentrated in Taiwan and mainland China. Lithium manganese dioxide cells, MEMS capacitive transducers, and ceramic substrate packages constitute critical input dependencies. Single-source vulnerability in East Asian battery chemical processing exposes North American assemblers to ocean freight rate volatility. Distribution runs through authorized distributor networks serving industrial automation channels, with direct procurement relationships dominating high-volume energy sector deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
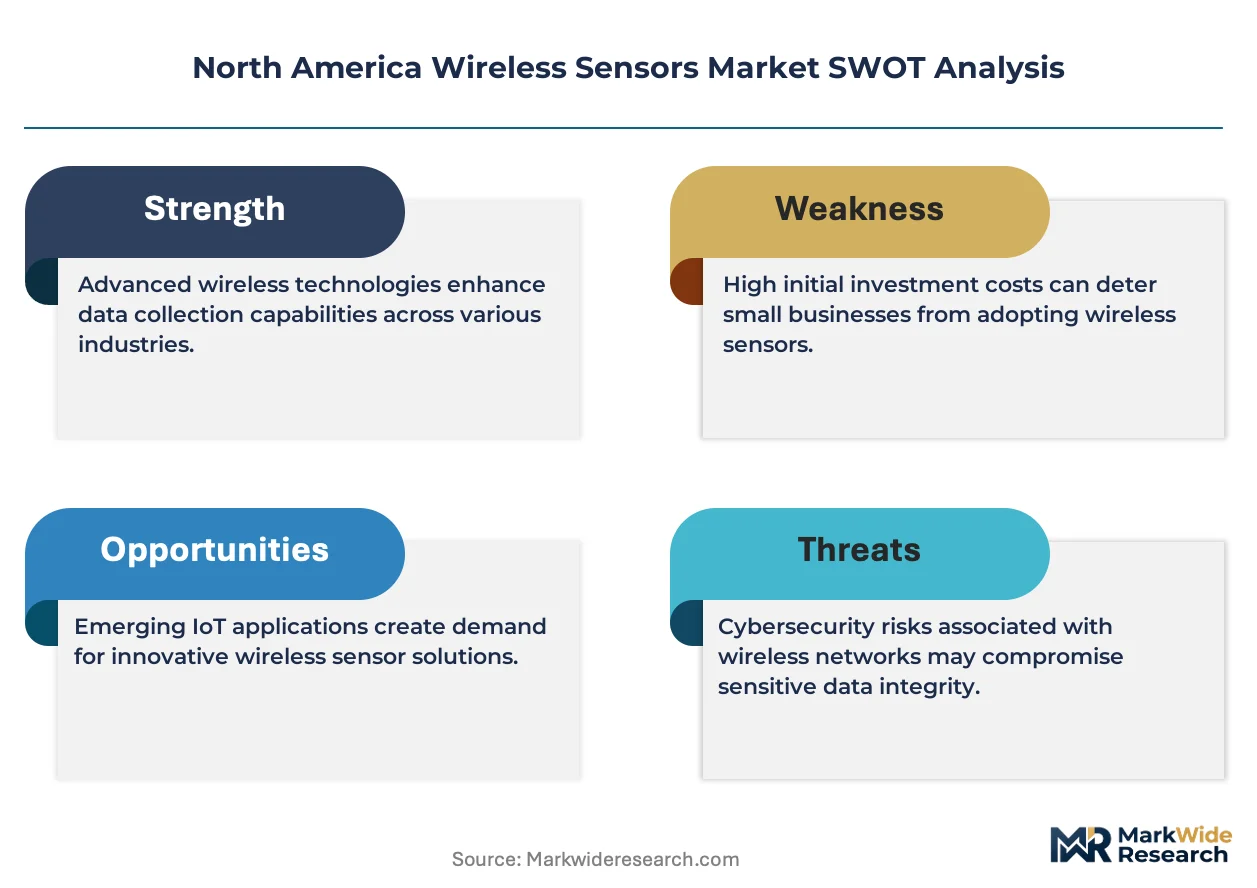
This market functions as a regulatory compounder where FCC spectrum reallocation proceedings and NIST cybersecurity labeling programs continuously reshape hardware certification timelines and customer qualification cycles.
For Market Incumbents: Anticipate firmware attestation requirements hardening into de facto barriers as General Services Administration schedules prioritize pre-certified hardware. Defensive consolidation should target calibration-heavy sensor module producers in Texas and Alberta to deepen process industry specifications. Channel control through integrated sensor-to-cloud platforms offers durable protection against third-party gateway vendor displacement. For New Entrants and Emerging Players: Saskatchewan grain cooperatives with satellite-backhaul soil moisture arrays represent an underserved buyer archetype with limited incumbent penetration. Canadian prairie smart agriculture and California Title 24 daylight harvesting compliance projects offer white-space targets with specification pull from energy code mandates. A go-to-market angle pairing piezoelectric vibration harvesters with BLE 5.3 radios addresses battery maintenance pain points in rotating machinery monitoring. For Investors and Strategic Acquirers: Roll-up economics work for calibration-specialist sensor module producers because federal procurement mandates for demonstrated firmware compliance fragment qualification timelines and favor scaled certification investments. Long-term viability centers on five-to-ten year positioning around NIST framework evolution and spectrum efficiency regulation. Acquisition targets should exhibit deep RF firmware engineering benches and captive relationships with Permian Basin operators. The signal to watch is Industry Canada RSS standard harmonization pressure accelerating cross-border product launch complexity.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Attestation Investment | NIST SP 800-213A compliance secures General Services Administration schedule eligibility ahead of competitors. |
| Captive Fab Network Expansion | Texas Instruments demonstrates die supply continuity advantages during mature-node capacity constraints. |
| Energy Harvesting Integration | Piezoelectric vibration harvesters paired with BLE 5.3 eliminate battery swaps in rotating machinery applications. |
| Cross-Border Certification Parallelism | Dual FCC and Industry Canada testing lab engagements compress margin on low-volume SKUs. |
| Private LoRaWAN Network Operation | Oilfield service companies in Texas displace turnkey SaaS subscriptions with internal DevOps integration. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combining structured interviews with RF firmware architects, industrial automation procurement leads, oilfield service operations managers, and building automation systems integrators with secondary validation. Secondary sources include FCC equipment authorization databases, Industry Canada RSS filings, NIST cybersecurity publications, SEC 10-K disclosures from semiconductor and industrial conglomerates, and customs records for lithium primary battery imports. Bottom-up sensor deployment counts triangulate against top-down market sizing from component-level bill-of-materials analysis.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include product type, technology protocol, end-use industry, and application context, with additional granularity on federal procurement eligibility tiers. CAGRs derive from regression analysis of historical deployment densities against regulatory milestone timing and energy sector capital expenditure patterns. Forecast inputs incorporate Permian Basin wellpad sensor node counts, California Title 24 compliance project pipelines, and Saskatchewan grain cooperative pilot program expansions.
Underlying measurement precision varies by segment; industrial automation and energy sector deployments carry tighter precision than emerging smart agriculture applications. Forecasts reflect documented assumptions regarding FCC spectrum reallocation timing, NIST framework adoption velocity, and lithium cell supply continuity. Material deviation in tariff exposure on East Asian battery chemicals or mature-node foundry capacity allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Automotive Image Sensors Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Calibrator Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
In-Display Fingerprint Sensors Market