
 Global LTE Modems Market | 2026-2036
Global LTE Modems Market Size, Share, and Industry Trends Forecast 2026-2036
Global LTE Modems Market Outlook
OEM direct procurement is tilting toward module suppliers with integrated certification stacks. Qualcomm Technologies Inc. leverages its Snapdragon X-series modem-RF system to dominate premium tier designs. MediaTek Inc. competes aggressively on cost-optimized silicon for emerging market routers. Sierra Wireless anchors North American enterprise channels through its certified gateway portfolio.
An LTE modem is a wireless communication device that modulates and demodulates radio signals to enable data transmission over 4G Long-Term Evolution cellular networks, typically supporting download speeds from 100 Mbps to over 1 Gbps in LTE-A Pro configurations depending on carrier aggregation levels. Router modems capture the largest revenue pool as ISPs and enterprises replace legacy DSL infrastructure with fixed wireless access solutions. IoT Connectivity represents the fastest-expanding application segment, driven by LTE-M and NB-IoT variants that extend battery life to ten years for utility metering and asset tracking endpoints.
The FCC governs spectrum allocation and device certification through Parts 15 and 27 rules, while the EU's Radio Equipment Directive mandates CE marking and harmonized frequency use across member states. Japan's MIC enforces stringent radio law compliance that shapes modem firmware regionalization strategies. Stakeholders must monitor spectrum reallocation decisions and 5G fallback compatibility requirements as regulators harmonize next-generation transition timelines.
Market Dynamics
Carrier aggregation complexity and CBRS spectrum commercialization are compressing modem design cycles while fragmenting certification requirements across national regulators, forcing suppliers to maintain parallel firmware stacks for identical hardware platforms.
Growth Catalysts
- Fixed Wireless Access mandates:The FCC's Rural Digital Opportunity Fund is channeling subsidy capital toward LTE-based broadband infrastructure, accelerating modem procurement by wireless internet service providers across underserved counties.
- LTE-M protocol maturation:Battery-optimized variants extending endpoint longevity to ten years are displacing proprietary mesh networks in utility metering and cold-chain logistics.
- Automotive telematics integration:Connected vehicle mandates in Brazil and Saudi Arabia are creating embedded modem demand that outpaces regional smartphone penetration curves.
Market Restraints
- GaAs and GaN substrate volatility:RF frontend material costs fluctuate with defense sector absorption rates, compressing gross margins on high-bandwidth modem configurations.
- Taiwanese foundry concentration:Advanced node capacity at TSMC and UMC dominates baseband silicon supply, creating geographic single-point vulnerability for fabless modem designers.
- 5G-NR substitution pressure:Carrier marketing of sub-6 GHz 5G is shortening LTE-A Pro upgrade cycles before full depreciation, stranding enterprise gateway investments.
Strategic Opportunities
- Indian manufacturing corridors:PLI scheme incentives for telecom equipment are attracting module assembly investments to Gujarat and Tamil Nadu, creating localized certification pathways.
- Private cellular networks:CBRS and n77 spectrum allocations enable enterprise-owned LTE infrastructure for mining and port automation, bypassing carrier subscription models.
- Dual-mode 5G fallback architectures:LTE-Advanced Pro modems with software-defined 5G NSA compatibility extend product lifecycles through standards transition periods.
Industry Challenges
- RF calibration expertise scarcity:Millimeter-wave test engineering talent concentrates in South Korea and California, forcing modem vendors to maintain distributed validation labs or outsource critical characterization.
- Carrier certification queue congestion:AT&T, Verizon, and T-Mobile each maintain incompatible acceptance test plans, extending time-to-revenue for new module introductions by six to nine months.
- Legacy SCADA protocol integration:Industrial IoT deployments require modem firmware customization for Modbus and DNP3 translation, fragmenting software maintenance obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LTE Modems Market |
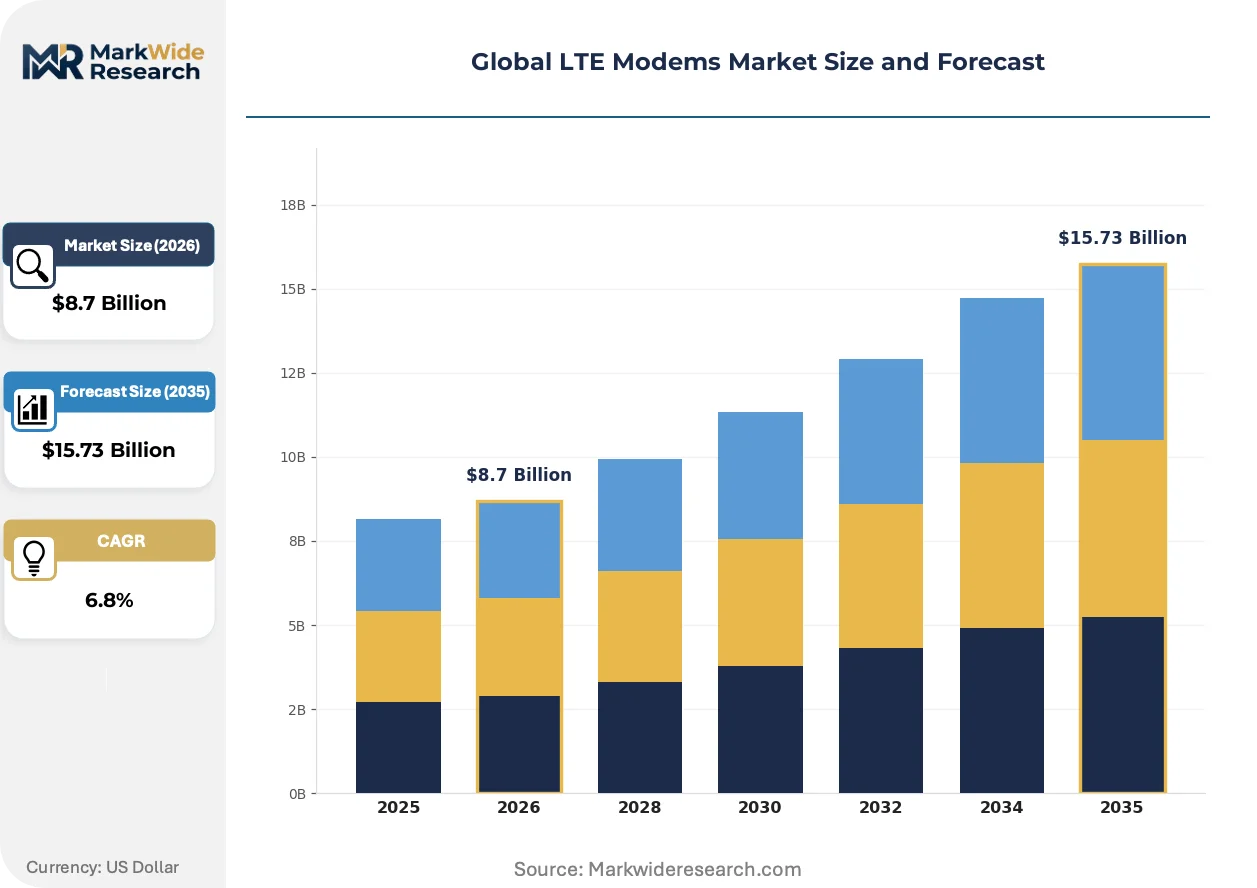
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Modems, Outdoor Modems, Router Modems, USB Modems Technology: 4G LTE, Advanced LTE, LTE-A Pro, LTE-M End User: Residential, Small Enterprises, Large Enterprises, Government Application: Mobile Broadband, IoT Connectivity, Fixed Wireless Access, Smart City Solutions |
| Companies Covered | Qualcomm Technologies Inc., MediaTek Inc., Sierra Wireless, Quectel Wireless Solutions, Fibocom Wireless Inc., u-blox Holding AG, Telit Communications PLC, Simcom Wireless Solutions Limited, Digi International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LTE Modems Market Strategic Shifts
Software-defined radio architectures and open-source baseband stacks are dissolving traditional hardware-software boundaries, enabling modem functionality to migrate between dedicated silicon and general-purpose compute.
Integrated modem-RF systems are collapsing the discrete component count in high-volume smartphone and tablet designs. Qualcomm's Snapdragon X-series architecture embeds power amplifiers, filters, and antenna tuners within a single package, compressing board area requirements by sixty percent versus discrete implementations. Android OEMs in the premium tier have adopted this integration wholesale, forcing second-tier suppliers to match density or exit flagship design slots.
The EU's Cyber Resilience Act imposes mandatory security update obligations on radio equipment with network connectivity, extending manufacturer liability periods to five years post-sale. Modem vendors must now maintain firmware signing infrastructure and CVE response pipelines for legacy product generations. Industrial gateway suppliers serving European manufacturing are restructuring support contracts to absorb these compliance costs.
Enterprise buyers are consolidating modem procurement through managed connectivity platforms rather than discrete hardware purchases. Fleet operators and utility deployers now subscribe to bundled device-plus-data services from Sierra Wireless and Telit Cinterion, shifting capital expenditure to operational models. This preference concentrates in North American enterprise channels where IT integration complexity drives outsourcing of cellular lifecycle management.
Global LTE Modems Market Segmentation
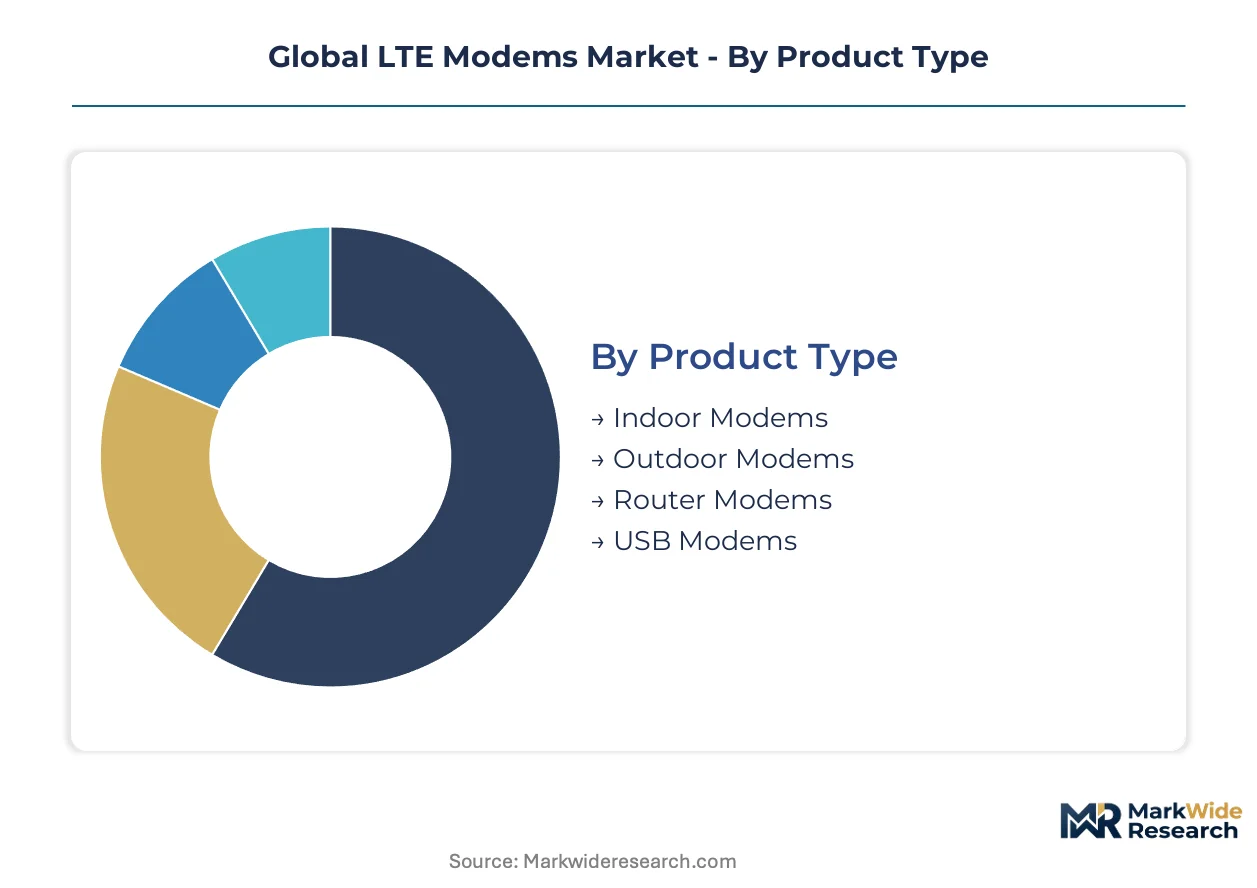
Segmentation in the LTE modems market reflects divergent technical requirements across deployment environments. Indoor residential installations prioritize cost-optimized silicon, while industrial outdoor deployments demand ruggedized thermal management and extended temperature tolerances.
Product Type:
Cost tier separation drives procurement patterns across installation environments and volume scales.
- Router Modems:These units integrate routing functionality with cellular baseband processing, typically housing external antenna ports and Ethernet switching for multi-device LAN distribution. ISP procurement in the United States concentrates on these configurations as the FCC's Rural Digital Opportunity Fund accelerates fixed wireless access buildouts in underserved counties.
- Outdoor Modems:Hardened enclosures with IP67 ratings and extended temperature specifications characterize this segment, designed for pole-mounted or tower installations without climate-controlled shelters. Mining operations in Western Australia and port automation projects in Rotterdam specify these units for direct environmental exposure.
- Indoor Modems:Desktop or wall-mount units with simplified thermal design serve consumer and SOHO markets.
- USB Modems:Compact dongle form factors provide plug-and-play connectivity for mobile professional use cases.
Router modems command the established base. The steepest expansion runs through outdoor modems.
Technology:
Application maturity and spectral efficiency requirements stratify the technology landscape across deployment scenarios.
- LTE-A Pro:Carrier aggregation across five component carriers enables theoretical peak rates exceeding 1 Gbps, with 256-QAM modulation and licensed-assisted access extending into unlicensed spectrum. Automotive OEMs in Germany and fleet telematics providers in Brazil specify these modems for high-definition video offload and real-time diagnostic streaming.
- LTE-M:Narrowband protocols reduce device complexity and power consumption to enable decade-long battery operation on compact cells. Utility metering deployments in Japan and cold-chain logistics trackers across Nordic markets are expanding most quickly through this specification.
- 4G LTE:Baseline Category 4 and Category 6 implementations serve cost-sensitive volume markets.
- Advanced LTE:Intermediate carrier aggregation configurations bridge performance and cost for mainstream enterprise gateways.
LTE-A Pro anchors premium-tier revenue. LTE-M gains share fastest among new design wins.
End User:
Customer type determines certification requirements, support contract structures, and procurement channel preferences.
- Large Enterprises:Multi-thousand-unit deployments with centralized IT integration demand modular firmware architectures and API-accessible management platforms. Manufacturing conglomerates in Gujarat and Tamil Nadu are qualifying locally assembled modules under India's PLI scheme incentives.
- Government:FIPS 140-2 cryptographic validation and supply chain integrity documentation dominate procurement specifications. Federal agencies in the United States and defense contractors in Saudi Arabia mandate these compliance layers for critical infrastructure connectivity.
- Residential:Consumer retail channels and ISP subscriber equipment programs drive volume.
- Small Enterprises:Managed service bundles simplify cellular adoption for IT-constrained organizations.
Large enterprises command the established base. Government procurement shows the steepest expansion trajectory.
Application:
Volume concentration and margin structure diverge sharply across use case categories.
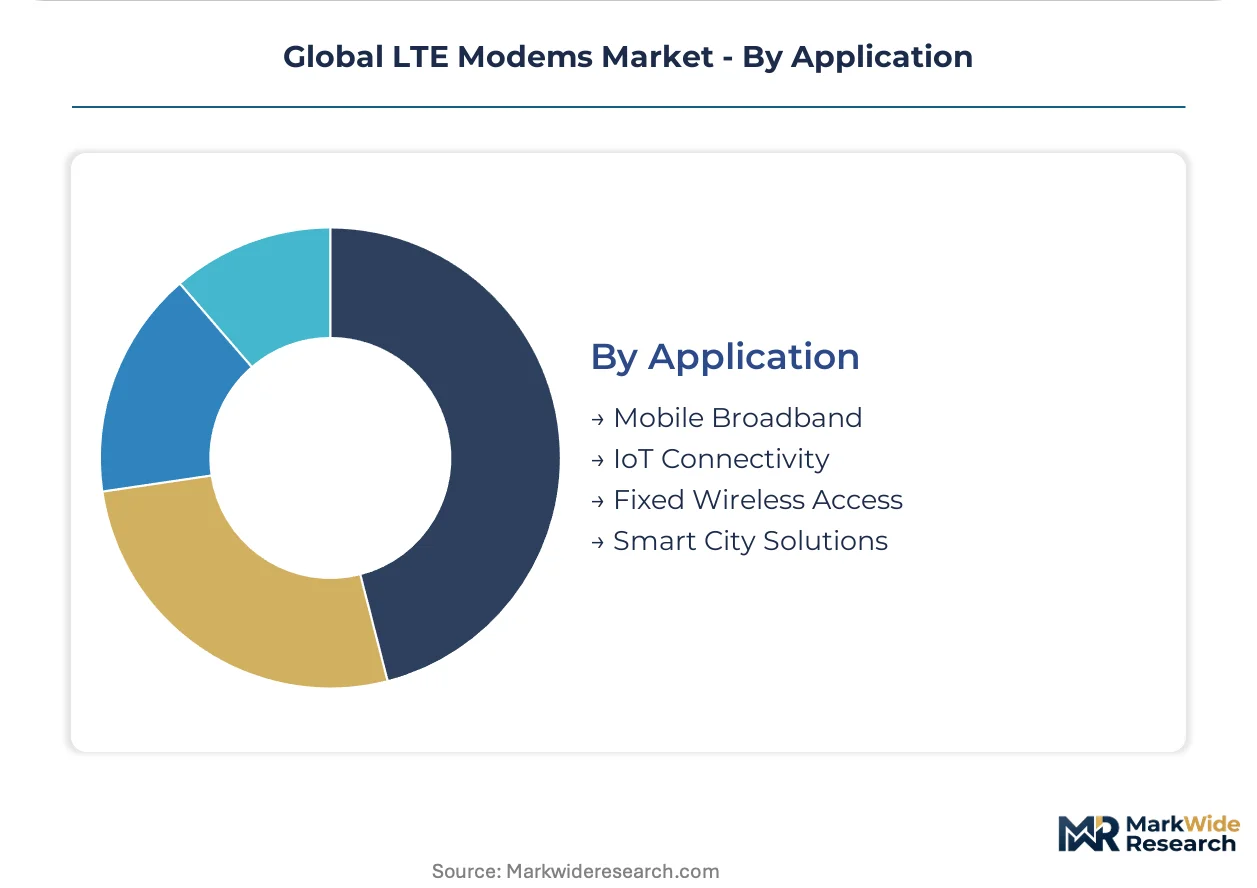
- IoT Connectivity:Massive endpoint densities with low ARPU per device characterize this segment, requiring modem variants with simplified RF chains and sleep-state optimization. Smart meter rollouts in France and asset tracking networks across German logistics corridors are scaling through LTE-M and NB-IoT certified modules.
- Fixed Wireless Access:Last-mile broadband substitution for DSL and cable infrastructure demands high-throughput modems with external antenna flexibility. Wireless internet service providers in rural Texas counties and Appalachian regions are deploying these units under FCC subsidy programs.
- Mobile Broadband:Portable hotspot and embedded laptop connectivity maintains steady replacement demand.
- Smart City Solutions:Integrated streetlight controllers and environmental sensors require municipal-scale deployment management.
Fixed wireless access commands the established base. IoT connectivity climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's Rural Digital Opportunity Fund subsidizes fixed wireless access buildouts across underserved American counties. Germany's automotive OEMs drive embedded modem demand for connected vehicle fleets. India's PLI scheme attracts module assembly to Gujarat and Tamil Nadu manufacturing corridors.
United States
Carrier aggregation investments and CBRS spectrum availability accelerate enterprise adoption of LTE-A Pro modems. The FCC governs device certification through Parts 15 and 27 rules while channeling Rural Digital Opportunity Fund capital toward wireless internet service providers. Rural Texas counties and Appalachian regions deploy high-throughput router modems under these subsidy programs.
Germany
Automotive telematics integration and industrial IoT deployments in manufacturing create sustained modem procurement. The EU's Radio Equipment Directive mandates CE marking and harmonized frequency use across member states. Stuttgart and Munich anchor embedded modem design wins for connected vehicle fleets serving European logistics corridors.
India
Large enterprise IT integration and utility metering scale-ups drive module demand across manufacturing and energy sectors. The PLI scheme for telecom equipment attracts assembly investments to Gujarat and Tamil Nadu. Ahmedabad and Chennai production lines now qualify locally assembled modules for domestic certification pathways.
Japan
LTE-M protocol maturation for utility metering and cold-chain logistics accelerates narrowband module deployment. METI enforces stringent radio law compliance that shapes modem firmware regionalization strategies. Tokyo and Osaka industrial zones concentrate smart meter rollouts requiring decade-long battery-optimized endpoints.
Brazil
Connected vehicle mandates and fleet telematics expansion outpace regional smartphone penetration curves. ANVISA and national telecom regulators align device certification with Mercosur harmonization frameworks. São Paulo automotive clusters integrate embedded modems for real-time diagnostic streaming and high-definition video offload.
Global LTE Modems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the baseband silicon layer. The vendor base stratifies across three tiers: premium-tier modem-RF system suppliers, cost-optimized silicon competitors, and certified gateway portfolio anchors. Two dominant competitive moves reshape positioning: strategic partnerships between fabless designers and Taiwanese foundries, and portfolio diversification into dual-mode 5G fallback architectures.
Within the premium-tier modem-RF integration segment, Qualcomm Technologies Inc. and MediaTek Inc. occupy positions at opposite ends of the cost-performance spectrum. Sierra Wireless anchors North American enterprise channels through its certified gateway portfolio. These three entities exemplify the archetype segmentation: integrated platform dominance, cost-optimized volume competition, and regional channel specialization.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| MediaTek Inc. |
| Sierra Wireless |
| Quectel Wireless Solutions |
| Fibocom Wireless Inc. |
| u-blox Holding AG |
| Telit Communications PLC |
| Simcom Wireless Solutions Limited |
| Digi International Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity at Taiwanese foundry nodes is compressing baseband silicon pricing while simultaneously forcing fabless designers toward longer-term capacity reservation contracts. This utilization dynamic creates divergent cost structures between premium-tier modem-RF integrators and cost-optimized module suppliers serving emerging market volume.
Pricing Analysis
Volume-discount tiering structures separate enterprise gateway procurement from consumer router shipments. Pricing stratifies across certification-grade premium tiers, standard commercial modules, and economy IoT variants. Cost compression in the economy tier intensifies because MediaTek and second-tier silicon vendors compete aggressively on die shrinks. Wireless internet service providers in rural subsidy programs exhibit highest price sensitivity; automotive OEMs in Germany demonstrate lowest sensitivity due to embedded lifecycle value.
Supply Chain Analysis
Contract-manufacturing concentration at TSMC and UMC in Taiwan anchors advanced node baseband production, with secondary capacity at Samsung Foundry in South Korea. The supply chain draws from GaAs and GaN substrate suppliers in California and Japan for RF frontend components. Single-source vulnerability concentrates at Taiwanese foundry nodes for sub-7nm silicon. Distribution runs through certified module aggregators serving North American enterprise channels and direct OEM procurement for automotive embedded designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global LTE Modems Market fragments across application-specific certification requirements, creating niche specialization opportunities as private cellular network demand diverges from carrier-managed connectivity.
For Market Incumbents: Build certification-queue moats by securing expedited carrier acceptance test plans with AT&T, Verizon, and T-Mobile. Invest in backward integration into RF calibration test infrastructure to reduce dependency on South Korean and California validation labs. The 5G-NR substitution threat accelerates margin compression; dual-mode 5G fallback architecture R&D preserves upgrade cycle revenue. For New Entrants and Emerging Players: India's PLI scheme manufacturing corridors offer geographic underpenetration for locally assembled module qualification. Target utility metering deployments in Japan and cold-chain logistics in Nordic markets with LTE-M firmware customization. Pursue managed connectivity platform partnerships rather than discrete hardware sales to bypass carrier certification queue congestion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across IoT connectivity modules as software-defined radio architectures reduce dedicated silicon requirements. Acquisition targets with private cellular network deployment expertise and CBRS certification stacks demonstrate strongest five-to-ten year viability. Monitor TSMC capacity allocation announcements as inflection indicator for supply-constrained premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode 5G Fallback Architecture Development | Extends product lifecycles through standards transition periods for automotive OEMs. |
| CBRS Spectrum Certification Investment | Unlocks enterprise-owned infrastructure opportunities in mining and port automation. |
| Managed Connectivity Platform Launch | Shifts fleet operators from capital expenditure to operational subscription models. |
| Indian PLI Scheme Manufacturing Localization | Qualifies modules for domestic certification pathways in Gujarat and Tamil Nadu. |
| RF Calibration Test Infrastructure Acquisition | Reduces six-to-nine month carrier certification queue delays for new introductions. |
Study Parameters
Operator-level perspectives from modem platform engineers, carrier certification managers, wireless internet service provider procurement leads, and industrial IoT deployment specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FCC Part 15 and Part 27 filings, EU Radio Equipment Directive harmonization documents, and METI radio law compliance databases. Bottom-up module shipment estimates triangulated against top-down semiconductor foundry capacity allocation disclosures.
Scenario-bracketing framed optimistic, baseline, and constrained demand paths across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user scale, and application environment. CAGRs derived from regression analysis of historical carrier aggregation deployment curves and spectrum reallocation timelines. Industry-specific inputs incorporated FCC Rural Digital Opportunity Fund disbursement schedules and automotive telematics mandate implementation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese module suppliers or accelerated 5G-NR substitution by carriers would shift outcomes. Quarterly review of foundry capacity utilization, carrier certification queue lengths, and CBRS spectrum auction participation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
4G Equipment Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
5G Radio Unit Market
Telecom Hardware
United States Set-Top Box Market