
 Radio Frequency Counter Market | 2026-2036
Radio Frequency Counter Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Counter Market Insights
Defense procurement agencies is unwinding legacy analog procurement patterns as telecommunications operators and research laboratories expand their share of RF counter purchases. Keysight Technologies leverages its vertical integration in calibration services to dominate high-frequency benchtop segments. Rohde & Schwarz anchors European demand through precision timebase architectures. Anritsu Corporation competes in portable field-test configurations for 5G deployment crews.
A radio frequency counter measures the number of cycles per second in an electromagnetic signal, typically operating from kilohertz to tens of gigahertz with resolution down to fractional hertz using oven-controlled crystal oscillators or rubidium references. The instrument serves spectrum management, radar validation, and oscillator manufacturing where frequency stability directly determines system interoperability. Handheld counters and portable counters now lead volume shipments as field technicians replace bench-bound workflows, while desktop counters retain the deepest margin pools in metrology-grade applications. Software-defined technology is displacing hybrid architectures fastest among aerospace integrators seeking programmable measurement personalities.
FCC equipment authorization rules mandate traceable frequency measurement for transmitters entering US commerce, while ITU Radio Regulations shape cross-border spectrum coordination and compliance test regimes. ISO/IEC 17025 accreditation requirements force calibration laboratories to maintain counters with documented uncertainty budgets, tightening vendor qualification criteria. Stakeholders must monitor how 6G research funding redirects procurement toward sub-terahertz measurement capability before standards solidify.
Market Dynamics
Defense procurement agencies are unwinding legacy analog procurement patterns as telecommunications operators and research laboratories expand their share of RF counter purchases. Software-defined architectures are compressing hardware refresh cycles while tightening calibration traceability mandates reshape vendor qualification criteria.
Growth Catalysts
- ITU spectrum allocation frameworks:Cross-border coordination protocols mandate traceable frequency measurement for transmitters entering commerce, expanding metrology-grade counter demand among certification laboratories.
- Electronic warfare testing:Defense procurement agencies are expanding instrumentation budgets for radar validation and signal intelligence applications requiring fractional-hertz resolution.
- Oven-controlled crystal oscillators:Advances in OCXO stability are enabling portable field-test configurations that match benchtop accuracy, opening new deployment scenarios for 5G installation crews.
Market Restraints
- Rubidium reference supply concentration:Atomic clock component manufacturing concentrates among a handful of specialized suppliers, creating input vulnerability for precision timebase architectures.
- ISO/IEC 17025 accreditation costs:Calibration laboratories must maintain documented uncertainty budgets, raising working capital requirements for smaller service providers.
- Hybrid architecture obsolescence:Mixed analog-digital designs face accelerated replacement as software-defined measurement personalities dominate aerospace integrator specifications.
Strategic Opportunities
- Sub-terahertz measurement capability:6G research funding is redirecting procurement toward unstandardized frequency bands before ITU-R recommendations solidify, creating first-mover positioning windows.
- Portable field-test configurations:Handheld counters are penetrating utility maintenance and broadcast engineering segments previously served by bench-bound workflows.
- FCC equipment authorization rules:Transmitter compliance mandates are expanding the addressable market for traceable frequency counters among importer certification services.
Industry Challenges
- Fractional-hertz calibration expertise:Metrology-grade applications require specialized technicians capable of managing rubidium reference drift and temperature coefficient compensation.
- Legacy system integration friction:Software-defined counters must interface with existing GPIB-controlled test racks, complicating aerospace integrator deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Counter Market |
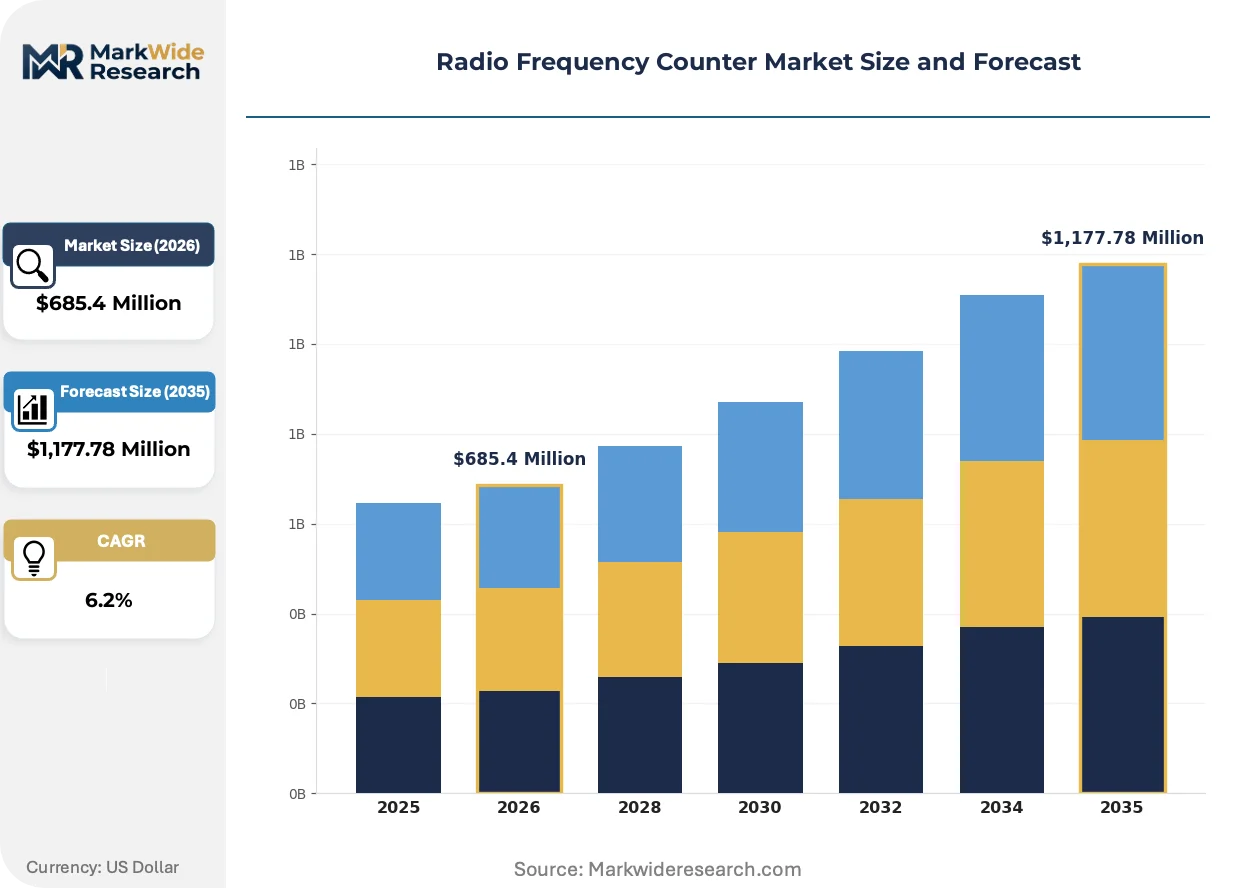
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Counters, Portable Counters, Desktop Counters, Network Counters Technology: Digital Technology, Analog Technology, Hybrid Technology, Software-Defined End User: Telecommunications, Aerospace, Defense, Research Laboratories Licensing Model: Subscription-Based, One-Time License, Freemium, Pay-Per-Use |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Anritsu Corporation, Fluke Corporation, Berkeley Nucleonics Corporation, OMRON Corporation, Simpson Electric, Yokogawa Electric Corporation, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Counter Market Trends and Innovations
Measurement instrumentation is undergoing architecture-level transformation as programmable personalities replace fixed-function hardware. Three developments are compressing traditional product lifecycles and redrawing competitive boundaries.
Software-defined radio architectures are supplanting hybrid analog-digital designs in frequency counter platforms. Aerospace integrators are adopting FPGA-based measurement personalities that reconfigure via firmware updates rather than hardware swaps. This supplanting of fixed-function instruments is collapsing refresh cycles from seven years to three while concentrating R&D spending among vendors with captive FPGA design capabilities.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are reshaping thermal management strategies for OCXO-based counters. Manufacturers must redesign oven-controlled crystal oscillator housings to comply with phasedown schedules, raising engineering costs for precision timebase architectures. European calibration laboratories are responding by extending equipment amortization periods and demanding vendor roadmaps for compliant thermal designs.
Field technicians are replacing purchase orders with short-term instrument rental agreements for episodic deployment validation. Telecommunications contractors are unbundling ownership from utilization, driving growth in certified pre-owned counters and calibration-included leasing programs. This behavioral shift is most pronounced in United States 5G rollout markets where crew mobility and project timing uncertainty favor operational expenditure models.
Radio Frequency Counter Market Segmentation
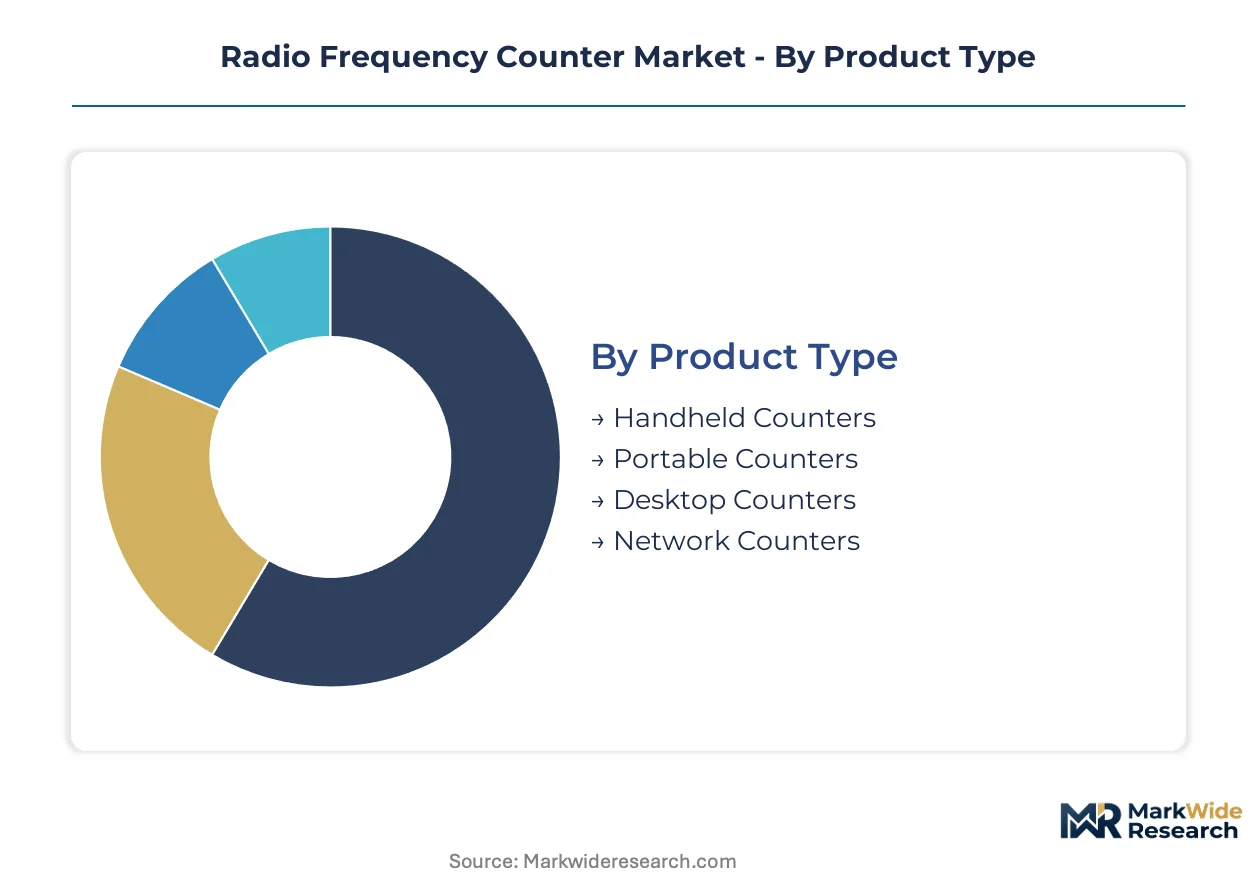
RF counter segmentation reveals how measurement requirements fragment across deployment contexts. Product form factors, underlying architectures, and procurement models each create distinct competitive arenas with diverging margin profiles and substitution vulnerabilities.
Product Type:
Handheld configurations face the most acute substitution pressure from smartphone-based measurement apps, forcing vendors to defend performance differentiation aggressively.
- Handheld Counters:Battery-powered units with integrated antennas serve field technicians validating transmitter installations. 5G deployment crews in the United States drive replacement demand as tower climbing workflows favor sub-kilogram instruments over bench-bound alternatives.
- Portable Counters:Transit-case designs bridge field and laboratory environments with OCXO stability in ruggedized enclosures. Aerospace maintenance teams at Lockheed Martin and Raytheon facilities specify these for flight-line diagnostic work where vibration tolerance matters.
- Desktop Counters:Rack-mount instruments deliver fractional-hertz resolution for metrology-grade calibration chains. FCC certification laboratories maintain these as primary standards for transmitter authorization testing.
- Network Counters:Ethernet-connected devices enable distributed spectrum monitoring across cellular infrastructure. Telecommunications operators deploy these at base station clusters for automated interference detection.
Portable counters retain volume leadership; handheld counters hold the steepest expansion curve.
Technology:
Cost tier stratification separates aerospace integrators demanding programmable architectures from budget-constrained education markets tolerating legacy analog designs.
- Digital Technology:FPGA-based counting engines with gate-array signal processing dominate mid-range procurement. Keysight Technologies and Rohde & Schwarz anchor this tier through proprietary ASIC development programs.
- Analog Technology:Discrete component designs persist in emerging market education budgets and legacy system spares. Indian technical institutes and Southeast Asian vocational programs sustain residual demand despite measurement speed limitations.
- Hybrid Technology:Mixed-signal architectures combining analog front-ends with digital post-processing face accelerated obsolescence. Defense procurement agencies are unwinding remaining hybrid inventories as software-defined alternatives mature.
- Software-Defined:Reconfigurable measurement personalities via firmware updates compress hardware refresh cycles from seven years to three. Aerospace integrators at Northrop Grumman and BAE Systems specify these for multi-mission test racks requiring rapid protocol adaptation.
Digital technology commands the largest installed base; software-defined architectures are gaining share fastest.
End User:
Customer type concentration determines how procurement authority fragments between centralized metrology laboratories and distributed field operations.
- Telecommunications:5G network operators and infrastructure contractors drive volume demand for portable validation tools. Verizon and AT&T field engineering teams specify handheld counters with automated reporting for tower commissioning workflows.
- Aerospace:Prime contractors and tier-one suppliers require traceable frequency measurement for avionics qualification. Boeing and Airbus test facilities maintain dedicated calibration hierarchies for radar and navigation oscillator validation.
- Defense:Electronic warfare testing programs at DARPA and service laboratories demand sub-hertz resolution for signal intelligence applications. Classified procurement channels limit vendor visibility but concentrate spending among cleared suppliers.
- Research Laboratories:National standards bodies and university physics departments anchor metrology-grade demand. NIST facilities in Boulder and Gaithersburg specify rubidium-referenced counters for primary frequency distribution services.
Telecommunications generates the highest shipment volumes; defense applications deliver the steepest margin expansion.
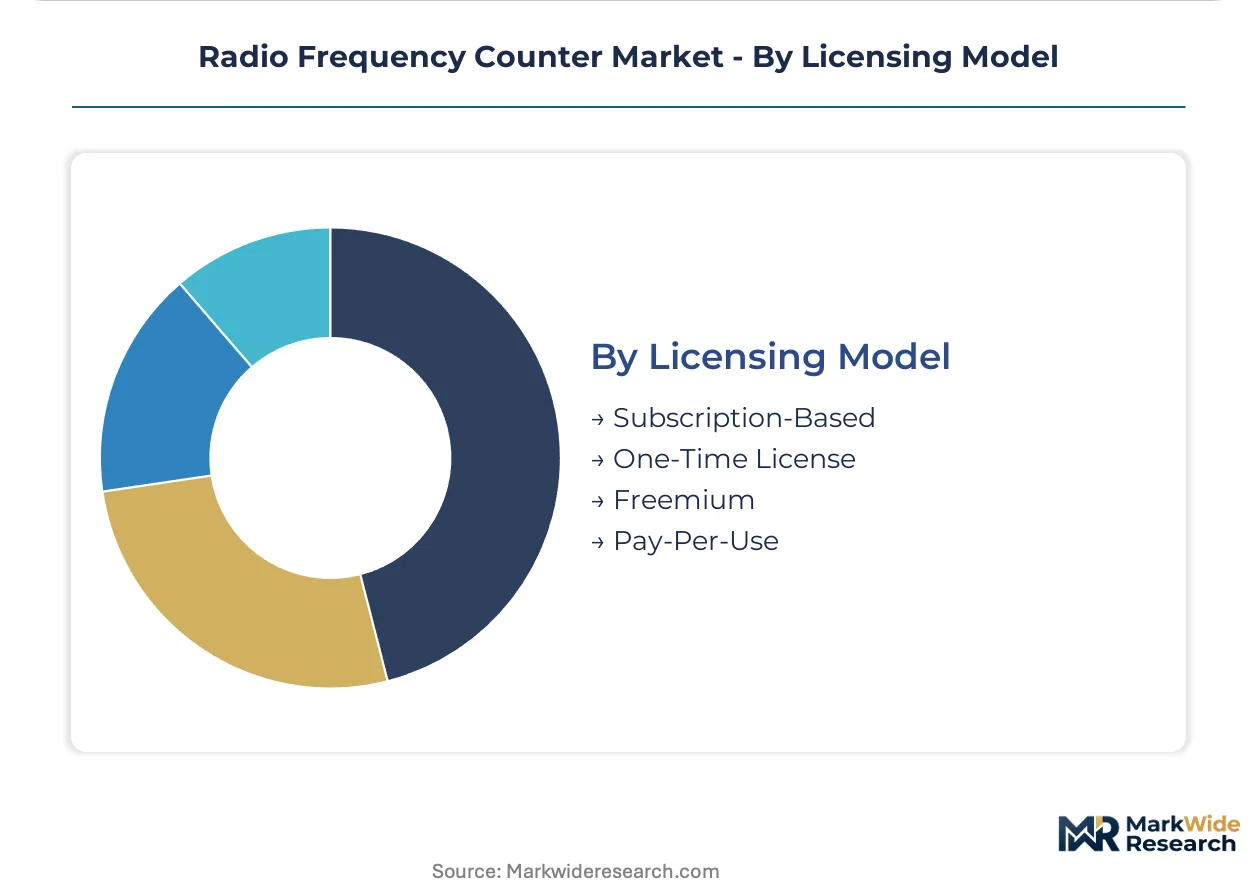
Licensing Model:
Supply concentration among calibration-capable vendors shapes how procurement flexibility varies across ownership and rental structures.
- Subscription-Based:Annual contracts bundling hardware access with calibration services appeal to project-based contractors. 5G rollout crews in Texas and California favor this model for equipment utilization matching deployment timelines.
- One-Time License:Perpetual purchase with optional service agreements dominates established laboratory procurement. NIST and FAA technical centers prefer capital expenditure treatment for depreciation scheduling.
- Freemium:Basic measurement apps with paid feature unlocks penetrate education and hobbyist markets. University engineering programs deploy these for undergraduate laboratory instruction before upgrading to benchtop instruments.
- Pay-Per-Use:Metered billing for episodic validation work suits utility maintenance and broadcast engineering. Regional telecommunications contractors in the Midwest adopt this for seasonal infrastructure audits.
One-time license procurement retains revenue concentration; subscription models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision instrument manufacturers export OCXO-stabilized counters to United States defense contractors and telecommunications operators, establishing a transatlantic trade corridor that channels European metrology expertise into North American procurement channels.
United States
Federal R&D spending at DARPA and NIST drives demand for rubidium-referenced counters with fractional-hertz resolution. FCC equipment authorization rules mandate traceable frequency measurement for transmitters entering US commerce. Boulder, Colorado hosts NIST facilities that anchor primary frequency distribution services and calibration hierarchies for aerospace integrators.
Germany
Precision timebase architectures from Bavarian engineering centers serve European aerospace and automotive test facilities. EU F-Gas Regulation restrictions force redesign of OCXO thermal management systems, raising compliance costs for oven-controlled oscillator housings. Munich and Stuttgart industrial clusters concentrate R&D spending for software-defined measurement personalities targeting automotive radar validation.
China
Domestic 5G infrastructure deployment creates volume demand for portable field-test configurations among tower installation crews. MIIT spectrum management frameworks tighten measurement accuracy requirements for base station commissioning. Shenzhen and Shanghai electronics manufacturing clusters absorb imported high-frequency benchtop segments while developing indigenous FPGA-based counting capabilities.
Japan
Research laboratories at national universities anchor metrology-grade demand for desktop counters with documented uncertainty budgets. METI industrial standards shape procurement specifications for telecommunications operators and broadcast engineering services. Tokyo and Osaka precision instrument districts maintain calibration hierarchies serving regional electronics manufacturers.
United Kingdom
Aerospace prime contractors at BAE Systems and Rolls-Royce facilities require traceable frequency measurement for avionics qualification and radar validation. National standards bodies align with ISO/IEC 17025 accreditation requirements for calibration laboratory certification. Cambridge and Bristol technology clusters concentrate defense electronics procurement for electronic warfare testing programs.
Radio Frequency Counter Market Competitive Landscape
Listed leaders compete with private specialists across calibration service bundling and FPGA design capabilities. The vendor base separates into three tiers: integrated instrumentation conglomerates with captive semiconductor fabrication, mid-scale specialists focused on portable field configurations, and regional distributors serving education and maintenance markets. Strategic archetypes include vertical integrators controlling oscillator supply chains, software-defined architecture pioneers, and calibration-service bundlers. Competitive moves concentrate on M&A for rubidium reference technology and strategic partnerships with telecommunications operators for 5G deployment toolkits.
Within the integrated instrumentation tier, Keysight Technologies and Rohde & Schwarz exemplify archetypes of calibration-service bundlers and precision timebase architects respectively. Anritsu Corporation occupies a position among portable configuration specialists. These three entities represent the dominant competitive anchors without exhaustive claims about specific product portfolios or strategic initiatives.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Anritsu Corporation |
| Fluke Corporation |
| Berkeley Nucleonics Corporation |
| OMRON Corporation |
| Simpson Electric |
| Yokogawa Electric Corporation |
| Teledyne Technologies |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for rubidium reference oscillators concentrate procurement leverage among three German and Swiss specialty suppliers, compressing margin pools for counter manufacturers while amplifying pricing power upstream. This inventory tightness cascades into tiered hardware economics where OCXO-stabilized portable units command premium positioning against field-configurable alternatives.
Pricing Analysis
Three-generation pricing stratification separates software-defined architectures from legacy hybrid designs and emerging sub-terahertz prototypes. Three-tier pricing structure across metrology-grade, field-portable, and education-economy levels anchors on calibration traceability and FCC certification tier. Pricing pressure stems from telecommunications operators unbundling ownership through rental agreements. Education markets exhibit highest price sensitivity; defense procurement shows lowest.
Supply Chain Analysis
Ninety-day lead times for precision timebase components signal single-source vulnerability in atomic clock subassemblies. Manufacturing concentrates in Germany, Switzerland, and the United States for OCXO and rubidium reference production. Component dependencies include FPGA silicon from Taiwan, precision crystals from Japan, and specialized thermal housings subject to EU F-Gas Regulation. Distribution runs through calibration-certified vendor-direct channels serving metrology laboratories and aerospace integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration-service bundling expands faster than hardware shipments as telecommunications contractors prioritize operational expenditure models over capital ownership. This service-attach dynamic reorients vendor economics toward recurring revenue streams.
For Market Incumbents: Fortify captive FPGA design capabilities against software-defined architecture commoditization. Deepen backward integration into OCXO thermal management systems ahead of EU F-Gas phasedown deadlines. Lock in long-term calibration service contracts with NIST-traceable laboratories to defend against emerging rental-platform competitors.
For New Entrants and Emerging Players: Short-term instrument rental gaps in 5G deployment markets offer white-space penetration where incumbents under-serve project-based contractors. Target Midwest utility maintenance segments with pay-per-use billing models. Lead with certified pre-owned counters bundled with calibration-included leasing to bypass capital-intensive manufacturing barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a precision-instrument consolidation play because rubidium reference supply concentration and ISO/IEC 17025 accreditation barriers protect incumbent returns. Target mid-scale specialists with captive oscillator technologies. Watch 6G research funding allocations as the inflection signal for sub-terahertz capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Bundling | Recurring revenue streams from NIST-traceable laboratories offset hardware margin compression. |
| FPGA Platform Integration | Software-defined personalities compress refresh cycles for aerospace integrators at Northrop Grumman. |
| Sub-terahertz Capability Investment | First-mover positioning in unstandardized 6G frequency bands before ITU-R recommendations solidify. |
| Strategic Partnership with Telecommunications Operators | 5G deployment toolkits with automated reporting capture tower commissioning workflows. |
| Acquisition of Rubidium Reference Technology | Atomic clock component supply concentration creates defensive moats against input cost volatility. |
Research Methodology
Cross-validation between primary fieldwork with calibration laboratory directors and secondary analysis of FCC equipment authorization databases anchors the qualitative findings. Interviews with aerospace test engineers, telecommunications field operations managers, metrology-grade procurement officers, and defense electronics integrators inform demand-side segmentation. Trade data from U.S. Census Bureau, ITU spectrum allocation filings, ISO/IEC 17025 accreditation registries, and vendor financial disclosures provide supply-side validation. Bottom-up shipment estimates and top-down instrumentation spending analysis triangulate market sizing.
Sensitivity analysis around OCXO stability advancement rates and 6G research funding trajectories shapes projection confidence intervals across the analysis window. Segmentation dimensions include product form factor, underlying architecture technology, end-user industry, and licensing model. CAGRs derive from curve-fitting historical procurement patterns against federal R&D budget appropriations and telecommunications infrastructure deployment schedules. Sub-terahertz measurement capability adoption curves and software-defined architecture penetration rates serve as key forecast inputs.
Forecasts assume regulatory continuity in FCC equipment authorization and EU F-Gas Regulation regimes; material policy shifts would require re-modeling. ITU spectrum allocation timelines and defense procurement budget volatility represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Analog Phase Shifter Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
Phase Shifters Market
RF Components
Global Inductors Market
RF Components
Radio Frequency Front End Market
RF Components
Power Amplifier Market
RF Components
RF Spectrum Analyzer Market
RF Components
Z-Wave Products Market
RF Components
US RFID Tags Market
RF Components
Latin America RFID Tags Market
RF Components
Digital Radio Frequency Memory Market
RF Components
Europe Small Signal Transistor Market
RF Components
Global RF Power Semiconductor Market
RF Components
RFID Antenna Market
RF Components
Digital Phase Shifter Market
RF Components
Microwave Devices Market