
 8-Bit MCU Market | 2026-2036
8-Bit MCU Market Size, Share, and Industry Trends Forecast 2026-2036
8-Bit MCU Market Insights
Embedded firmware engineering talent scarcity is redrawing competitive boundaries across the 8-bit MCU landscape. Microchip Technology leverages its vertically integrated fabrication network to sustain price competitiveness in high-volume consumer contracts. NXP Semiconductors anchors its position through automotive-grade qualification depth, while STMicroelectronics differentiates via extensive development board ecosystems that accelerate customer time-to-market.
An 8-bit microcontroller integrates a processor core, volatile and non-volatile memory, and programmable input-output peripherals on a single silicon die, typically operating at clock speeds below 50 MHz with memory addressing limited to 64 KB. These devices execute deterministic control tasks in cost-constrained environments where processing overhead must remain minimal. Automotive Controls commands the largest revenue pool among application segments due to safety-critical actuator and sensor interface requirements. Home Appliances represents the fastest-expanding category as appliance OEMs pursue motor control and touch-panel integration at sub-dollar unit costs. Development Boards concentrate margin capture upstream, where toolchain lock-in generates recurring royalty-equivalent revenue streams.
FCC Part 15 emissions rules in the United States, CE marking requirements under the EU RoHS and EMC directives, and China's GB 9254 electromagnetic compatibility standards collectively dictate PCB layout, shielding, and material selection for 8-bit MCU deployments. REACH substance restrictions further constrain solder and encapsulant chemistry across European-bound shipments. Stakeholders must monitor how automotive functional safety standards migrate downward into cost-optimized 8-bit tiers, as this migration will determine which suppliers retain access to electrification-driven contract volumes.
Market Dynamics
Automotive electrification mandates are compressing qualification timelines for 8-bit MCUs while concentrating procurement among vertically integrated East Asian foundries that serve appliance and industrial sensor OEMs with sub-dollar unit economics.
Growth Catalysts
- Vehicle Electrification Standards:Tightening tailpipe and energy efficiency regulations in the European Union, China, and California are forcing automakers to expand electronic actuator control. 8-bit MCUs handle safety-critical sensor interfaces at cost points 32-bit alternatives cannot match.
- Appliance Motor Control:Home appliance OEMs in China and Taiwan are integrating brushless DC motor controllers and capacitive touch panels into washing machines and air conditioners. These functions require deterministic 8-bit timing at unit costs below fifty cents.
- East Asian Manufacturing Density:Shenzhen, Taipei, and Suzhou host dense clusters of contract electronics manufacturers that procure 8-bit MCUs in multi-million-unit volumes. Proximity to assembly lines reduces logistics overhead and accelerates design iteration cycles.
Market Restraints
- Silicon Wafer Cost Volatility:Foundry capacity allocation favors advanced nodes, leaving 8-bit production on older 200mm lines with rising depreciation and maintenance cost burdens.
- Foundry Concentration Risk:Taiwan Semiconductor Manufacturing and United Microelectronics control disproportionate legacy node capacity. Geopolitical friction across the Taiwan Strait threatens supply continuity for fabless 8-bit designers.
- 32-bit Substitution Threat:ARM Cortex-M0 cores from NXP and STMicroelectronics now price within pennies of premium 8-bit alternatives, eroding the cost advantage that sustained 8-bit dominance in simple control tasks.
Strategic Opportunities
- India Appliance Manufacturing:Production-linked incentive schemes from India's Ministry of Electronics and Information Technology are attracting air conditioner and refrigerator assembly to Gujarat and Tamil Nadu. Local 8-bit sourcing remains underdeveloped.
- Functional Safety Migration:Automotive ISO 26262 standards are descending into cost-optimized microcontroller tiers. Suppliers that achieve ASIL-B qualification on 8-bit cores will capture electrification-driven contract volumes from legacy relay-based systems.
- Capacitive Touch Convergence:Integration of touch-sensing peripherals directly onto 8-bit die eliminates separate controller ICs. Appliance OEMs in Korea and China are adopting this consolidated architecture for panel interfaces.
Industry Challenges
- Embedded Firmware Talent Scarcity:Assembly-level optimization for 8-bit architectures requires specialized skills in register-level programming and interrupt latency management. Universities have shifted curricula toward 32-bit and Linux-based embedded systems.
- Certification Timeline Compression:Automotive customers now demand AEC-Q100 qualification completion within eighteen months. This accelerates failure analysis and documentation burdens for suppliers unaccustomed to automotive-grade rigor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 8-Bit MCU Market |
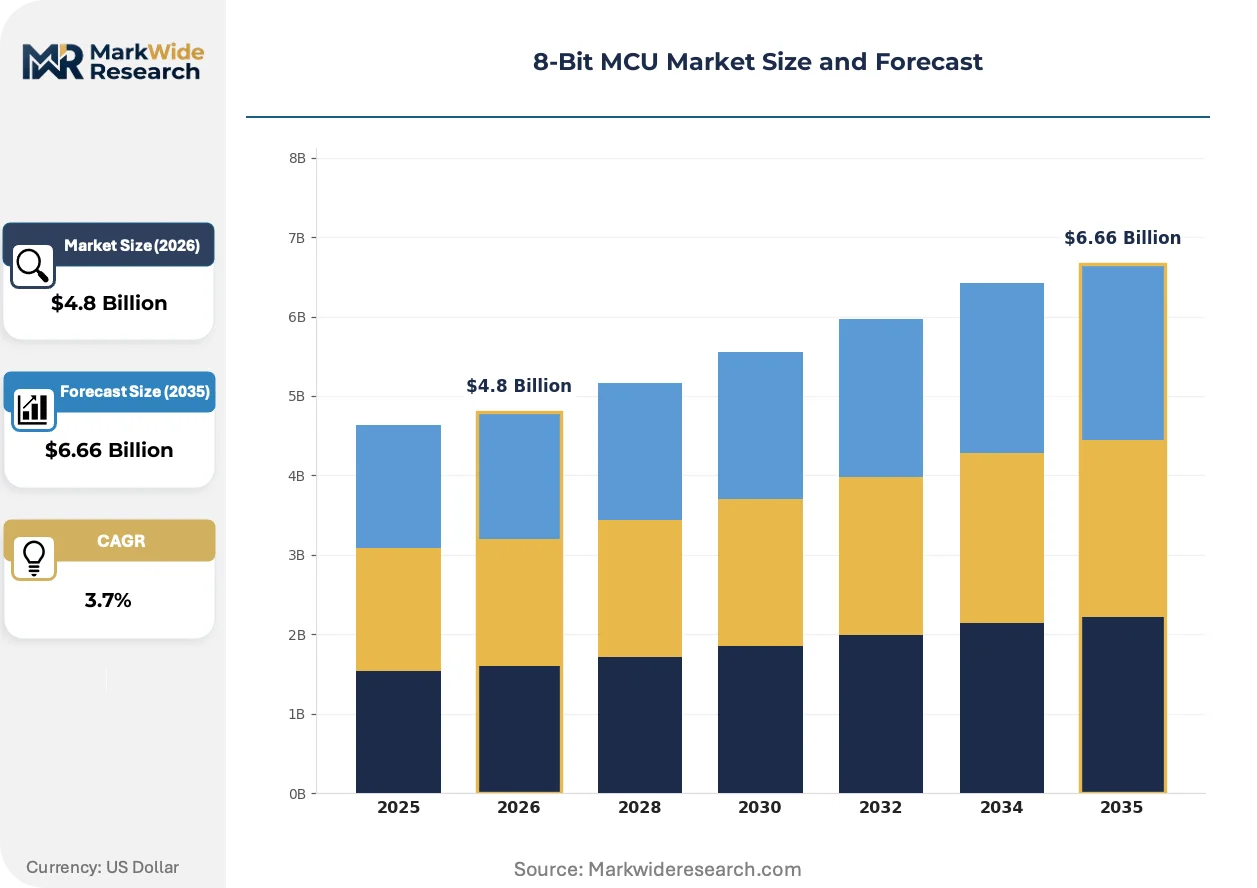
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Embedded Systems, Development Boards, Controller ICs Application: Consumer Electronics, Automotive Controls, Industrial Automation, Home Appliances End User: OEMs, System Integrators, Engineers, Developers Technology: Circuit Design, Sensor Integration, Power Management, Communication Protocols |
| Companies Covered | Microchip Technology, NXP Semiconductors, STMicroelectronics, Renesas Electronics, Infineon Technologies, Texas Instruments, Silicon Laboratories, Holtek Semiconductor, Zilog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
8-Bit MCU Market Trends and Innovations
Die-shrink economics and peripheral integration are redefining what 8-bit architectures can address, while regulatory pressure on material content and electromagnetic emissions is forcing PCB-level redesign across all deployment categories.
Copper pillar bumping and wafer-level chip-scale packaging are miniaturizing 8-bit MCU footprints to sub-2mm square dimensions. Wearable and implantable medical device manufacturers in Switzerland and Germany are adopting these formats for disposable health monitors. The technology is compressing board area requirements and enabling hermetic sealing for moisture-sensitive environments.
China's GB 9254 electromagnetic compatibility standards and updated EU RoHS substance restrictions are mandating revised PCB layout rules and lead-free solder formulations. Component suppliers must requalify existing 8-bit portfolios under stricter emission limits and material disclosure requirements. Automotive control modules bound for European and Chinese assembly plants face the most intensive retesting burdens.
Appliance OEM procurement departments are consolidating vendor lists and demanding multi-year price lock agreements with indexed raw material adjustments. Direct foundry relationships are displacing traditional distribution for volumes above five million units annually. This concentration is most visible among Chinese white-goods manufacturers headquartered in Qingdao and Foshan.
8-Bit MCU Market Segmentation
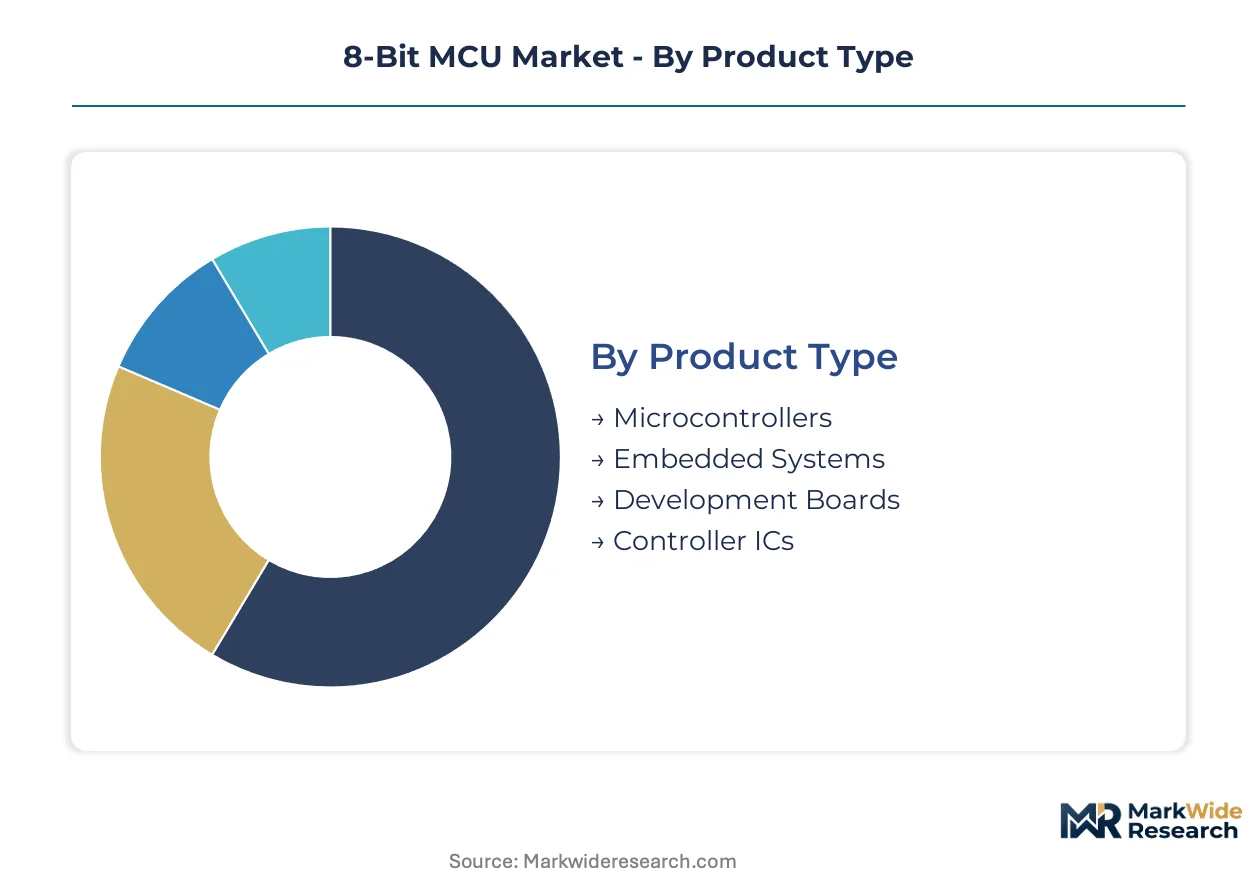
8-bit MCU procurement channels vary sharply by segment complexity. Development boards and controller ICs flow through distribution networks with heavy engineering support, while bare microcontrollers move direct to high-volume contract manufacturers. Understanding these channel dynamics is essential for suppliers optimizing margin capture.
Product Type:
Channel mix separates premium development tools from commodity silicon. Microcontrollers and controller ICs dominate direct foundry relationships, while development boards and embedded systems concentrate margin upstream through specialized distributors.
- Microcontrollers:Single-die integration of processor core, volatile and non-volatile memory, and programmable I/O peripherals operating below 50 MHz with 64 KB addressing limits. Demand concentrates among Chinese and Taiwanese contract manufacturers serving appliance OEMs with sub-fifty-cent unit economics for motor control and sensor interfaces.
- Development Boards:Pre-assembled hardware platforms bundling 8-bit MCU with power regulation, debug interfaces, and expansion headers. Procurement flows through Arrow, Avnet, and regional distributors in Shenzhen and Taipei, where toolchain lock-in generates recurring royalty-equivalent revenue from IDE and compiler licensing.
- Embedded Systems:Application-specific modules integrating MCU with pre-programmed firmware for defined control tasks.
- Controller ICs:Discrete motor control and power management companions to main 8-bit processors.
By volume, microcontrollers lead. By growth pace, development boards are climbing the fastest.
Application:
Cost tier stratification separates safety-critical automotive deployments from consumer price-elastic segments. Automotive and industrial automation command qualification premiums, while home appliances and consumer electronics compete on sub-dollar unit economics.
- Automotive Controls:Safety-critical actuator and sensor interface functions requiring deterministic timing under AEC-Q100 qualification. Revenue concentrates among European and Chinese electrification programs where 8-bit units handle tasks at price points 32-bit alternatives cannot match.
- Home Appliances:Brushless DC motor controllers and capacitive touch panels for washing machines, air conditioners, and refrigerators. Chinese OEMs in Qingdao and Foshan are consolidating vendor lists and demanding multi-year price lock agreements with indexed raw material adjustments.
- Consumer Electronics:Low-complexity control tasks in toys, remote controls, and disposable electronics.
- Industrial Automation:Programmable logic controllers and sensor nodes requiring extended temperature range operation.
Automotive controls generates the highest revenue per unit. Home appliances shows the steepest expansion trajectory as electrification standards tighten across major economies.
End User:
Customer type determines support intensity and contract structure. OEMs negotiate direct foundry relationships above five million units annually, while engineers and developers drive early-stage specification through evaluation kit adoption.
- OEMs:Original equipment manufacturers in white goods, automotive, and industrial equipment with multi-million-unit procurement scale. Chinese appliance OEMs headquartered in Qingdao and Foshan are displacing traditional distribution for high-volume contracts.
- System Integrators:Contract electronics manufacturers in Shenzhen, Taipei, and Suzhou that consolidate 8-bit MCU demand from multiple end customers. Proximity to dense manufacturing clusters reduces logistics overhead and accelerates design iteration cycles.
- Engineers:Hardware designers selecting MCU architecture during product development phase.
- Developers:Firmware programmers requiring toolchain compatibility and extensive code libraries.
OEMs dominate procurement volume. System integrators are gaining share fastest as outsourcing concentrates assembly in East Asian clusters.
Technology:
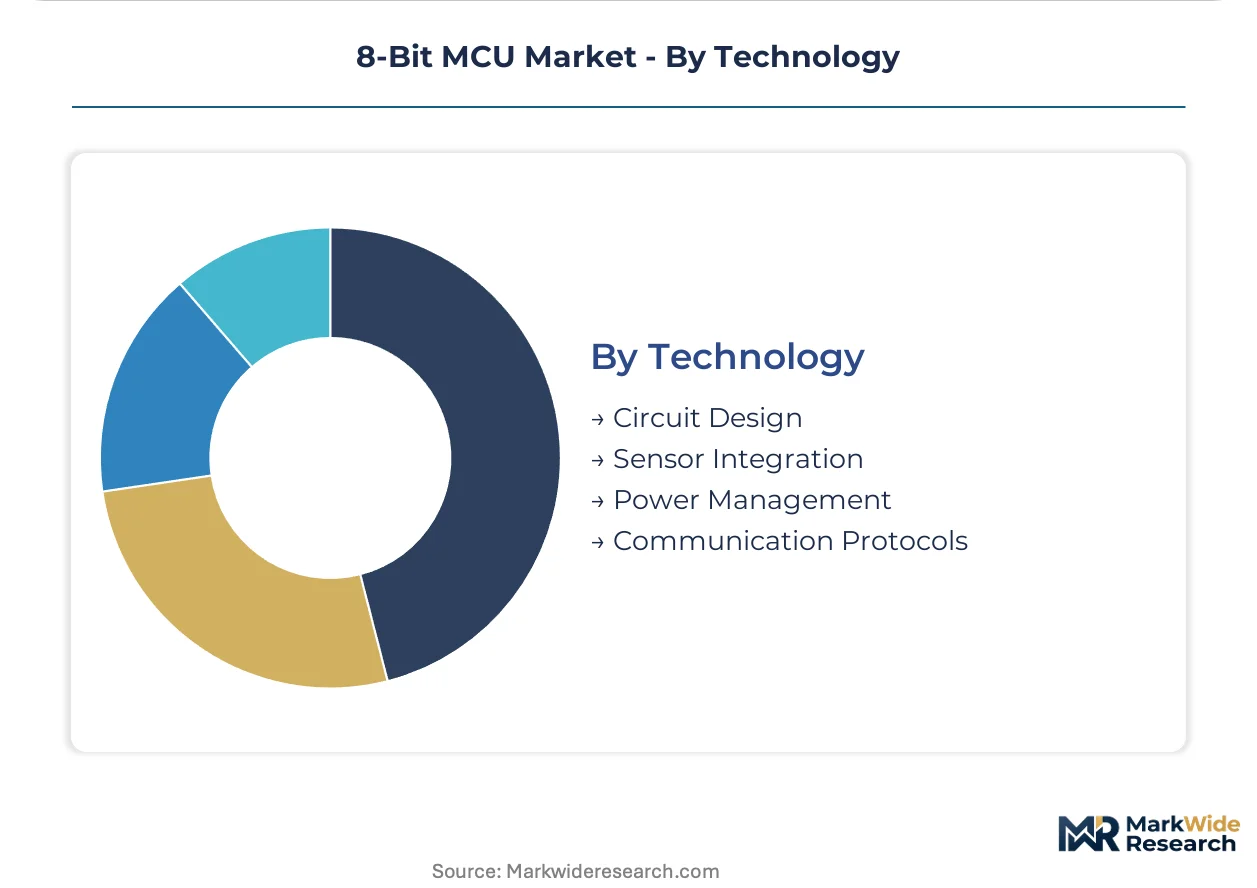
Maturity gradients separate established circuit design from emerging integration capabilities. Power management and communication protocols represent incremental evolution, while sensor integration is compressing board area through die-level consolidation.
- Sensor Integration:Capacitive touch-sensing peripherals embedded directly onto 8-bit die, eliminating separate controller ICs. Korean and Chinese appliance OEMs are adopting this consolidated architecture for panel interfaces in washing machines and air conditioners.
- Power Management:On-die voltage regulators and low-power modes extending battery life in portable and wearable applications. Swiss and German medical device manufacturers are adopting sub-2mm square wafer-level chip-scale packages for disposable health monitors.
- Circuit Design:Core processor architecture and memory organization optimized for deterministic control tasks.
- Communication Protocols:Integrated UART, SPI, I2C, and proprietary interfaces for peripheral connectivity.
Circuit design anchors existing volume. Sensor integration is expanding most quickly as appliance OEMs consolidate discrete functions onto single die.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for electromagnetic compatibility anchor procurement requirements across East Asian manufacturing clusters, where appliance OEMs and automotive suppliers concentrate 8-bit MCU demand. Regional differentiation sharpens between legacy node foundry capacity in Taiwan and emerging assembly incentives in India.
China
Appliance OEMs in Qingdao and Foshan consolidate vendor lists for brushless DC motor controllers and capacitive touch panels. GB 9254 electromagnetic compatibility standards mandate revised PCB layouts and shielding for white-goods exports. Shenzhen and Suzhou contract manufacturers procure 8-bit units in multi-million volumes for air conditioner and washing machine integration.
Taiwan
Foundry concentration at Taiwan Semiconductor Manufacturing and United Microelectronics supplies legacy 200mm node capacity for fabless 8-bit designers. The National Development Council monitors semiconductor supply continuity amid geopolitical friction. Taipei hosts dense clusters of MCU design houses serving mainland Chinese appliance contracts.
Germany
Automotive electrification programs in Bavaria and Baden-Württemberg demand AEC-Q100 qualified 8-bit units for safety-critical actuator control. REACH substance restrictions constrain solder and encapsulant chemistry for European-bound shipments. Stuttgart and Munich anchor development of ISO 26262 functional safety migration into cost-optimized tiers.
United States
FCC Part 15 emissions rules dictate PCB layout and shielding for consumer electronics deployments in California and Texas design centers. NHTSA tailpipe regulations indirectly expand electronic control module demand. Austin and Silicon Valley engineering teams specify 8-bit architectures for cost-constrained IoT sensor nodes.
India
Production-linked incentive schemes from the Ministry of Electronics and Information Technology attract air conditioner and refrigerator assembly to Gujarat and Tamil Nadu. BIS certification requirements apply to imported MCU components. Local 8-bit sourcing remains underdeveloped as OEMs rely on East Asian supply chains.
8-Bit MCU Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the 8-bit MCU landscape. Vertically integrated fabricators with captive foundry access compete on sub-fifty-cent unit economics against fabless specialists emphasizing development tool ecosystems. Three archetypes dominate: automotive-grade qualification specialists, high-volume consumer fabricators, and toolchain-integrated platform vendors. Competitive moves concentrate on backward integration into legacy node capacity and multi-year price lock agreements with indexed raw material adjustments.
Among automotive-grade specialists, NXP Semiconductors and Infineon Technologies occupy positions defined by AEC-Q100 depth and functional safety migration capabilities. Microchip Technology exemplifies the high-volume fabricator archetype through vertically integrated production networks serving appliance OEM procurement. STMicroelectronics anchors the toolchain-integrated segment via extensive development board ecosystems that accelerate customer time-to-market.
| Leading Market Players |
|---|
| Microchip Technology |
| NXP Semiconductors |
| STMicroelectronics |
| Renesas Electronics |
| Infineon Technologies |
| Texas Instruments |
| Silicon Laboratories |
| Holtek Semiconductor |
| Zilog |
| Others |
Pricing and Supply Chain Analysis
Eighteen-week lead times for AEC-Q100 qualified 8-bit MCUs concentrate pricing power among Taiwan Semiconductor Manufacturing and United Microelectronics, while appliance OEMs in Qingdao and Foshan exploit multi-million-unit scale to extract indexed raw material adjustments from fabless designers.
Pricing Analysis
Unit economics spread forty cents between German automotive-grade ASIL-B qualified devices and Chinese appliance-tier alternatives. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-economy levels separates AEC-Q100 depth from basic motor control functionality. Cost compression in consumer tiers intensifies because ARM Cortex-M0 cores now price within pennies of premium 8-bit alternatives. Appliance OEMs in China exhibit highest price sensitivity, while German automotive suppliers absorb certification premiums for functional safety migration.
Supply Chain Analysis
Port congestion at Kaohsiung and Shenzhen elevates inbound logistics costs for silicon wafers bound to legacy 200mm foundry lines. Supply concentrates in Taiwan, China, and South Korea, where 200mm node capacity feeds fabless 8-bit designers. Raw material dependencies include silicon wafers, copper pillar bumping substrates, and lead-free solder formulations. Single-source vulnerability concentrates at Taiwan Semiconductor Manufacturing and United Microelectronics amid Taiwan Strait friction. Distribution runs through Arrow and Avnet for development boards, while direct foundry relationships displace traditional channels above five million units annually.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification mandates are compressing 8-bit MCU procurement cycles, positioning this market for cyclical recovery as electrification-driven contract volumes expand from legacy relay-based systems.
For Market Incumbents: Shield automotive-grade qualification depth by accelerating ASIL-B certification timelines below eighteen months. Deepen backward integration into captive 200mm foundry capacity to offset Taiwan Strait concentration risk. Lock multi-year price agreements with indexed raw material adjustments before silicon wafer cost volatility intensifies.
For New Entrants and Emerging Players: Firmware engineering support gaps in Indian appliance manufacturing present exploitable white space. Target Gujarat and Tamil Nadu air conditioner assembly clusters where local 8-bit sourcing remains underdeveloped. Pursue capacitive touch integration partnerships with Korean panel OEMs as the fastest-penetrable application segment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive 8-bit MCU divisions lacking automotive certification depth. Long-term viability hinges on functional safety migration into cost-optimized tiers over the next decade. Monitor ISO 26262 qualification completion rates as the inflection signal separating qualified suppliers from commodity fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-B Qualification Acceleration | Captures electrification-driven contract volumes from German and Chinese automotive OEMs. |
| Backward Integration into 200mm Foundry Capacity | Secures legacy node supply continuity amid Taiwan Strait geopolitical friction. |
| Capacitive Touch Peripheral Integration | Eliminates separate controller ICs for Korean and Chinese appliance panel interfaces. |
| India Manufacturing Footprint Establishment | Exploits production-linked incentive schemes in Gujarat and Tamil Nadu assembly clusters. |
| Multi-Year Price Lock Agreements | Insulates margin position from silicon wafer cost volatility through indexed raw material adjustments. |
Research Methodology
Desk research of SEC semiconductor filings, MIIT GB standard documentation, and AEC-Q100 qualification databases preceded structured interviews with MCU product managers, automotive Tier 1 procurement directors, appliance OEM supply chain leads, and Taiwan foundry planning officers. Bottom-up unit shipment estimates by application segment triangulated against top-down wafer capacity allocation data from Taiwan Semiconductor Manufacturing and United Microelectronics disclosures.
Variance decomposition across product type, application tier, end-user category, and regional regulatory cluster anchored the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and average selling price erosion curves, with automotive electrification program timelines and appliance motor control adoption curves as primary forecast inputs.
Material uncertainties — Taiwan Strait supply disruption, ARM Cortex-M0 pricing aggression, and REACH substance restriction expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding foundry capacity allocation and certification timeline compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Secure Microcontrollers/Processors Market