
 Microprocessor Market | 2026-2036
Microprocessor Market Size, Share, and Industry Trends Forecast 2026-2036
Microprocessor Market Analysis
Multi-sourced wafer supply is expanding across leading microprocessor vendors as geopolitical risk reshapes procurement strategies. Intel Corporation sustains captive fabrication in Arizona, Oregon, and Ireland while competing for external foundry allocation. Samsung Electronics anchors South Korea's logic foundry capacity with in-house production of Exynos and contract manufacturing for Qualcomm. NVIDIA Corporation leverages Taiwan Semiconductor Manufacturing for advanced node GPUs while navigating supply diversification into Japan.
A microprocessor is a central processing unit fabricated on one or more integrated circuits, typically containing billions of transistors with gate lengths measured in nanometers, designed to execute arithmetic, logic, and input-output operations from stored instructions. Its primary purpose is to serve as the computational brain of electronic systems ranging from smartphones to industrial controllers. Server-grade x86 processors command premium margins in data center deployments, while ARM architecture dominates mobile and embedded power-constrained applications. Automotive end users represent the fastest-expanding demand pool as vehicle electrification and software-defined architectures multiply silicon content per platform.
The U.S. Department of Commerce export controls restrict advanced lithography equipment transfers to specific foundries, altering competitive access to leading-edge nodes. The EU Chips Act subsidizes European fabrication capacity while REACH and RoHS directives govern substance restrictions in semiconductor packaging materials. China's MIIT promotes domestic substitution through GB standards and dual carbon goals that constrain energy-intensive wafer production. Stakeholders must monitor which regulatory jurisdictions capture next-generation fab investments and how architecture licensing terms evolve under fragmented trade policy regimes.
Market Dynamics
Automotive electrification is compressing processor qualification cycles while Taiwan's foundry concentration forces procurement diversification into Japan and Europe.
Growth Catalysts
- EU AI Act compliance mandates:High-performance inference chips for autonomous systems face new conformity requirements, expanding demand for automotive-grade silicon with certified safety architectures.
- Electric vehicle powertrain integration:Battery management systems and motor controllers require dedicated microcontrollers with real-time processing capabilities.
- Advanced packaging adoption:Chiplet-based designs using 2.5D and 3D integration reduce yield losses on large dies while enabling heterogeneous compute.
Market Restraints
- EUV lithography equipment scarcity:ASML's annual production capacity limits access to sub-5nm nodes for all but the largest foundry customers.
- Wafer substrate cost volatility:Silicon carbide and gallium nitride substrates command premiums that constrain power semiconductor scaling.
- REACH substance restrictions:European packaging material regulations complicate lead-free solder alternatives and thermal interface compounds.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic fabrication incentives attract OSAT investments and design center relocations from multinational chip vendors.
- Edge AI inference at manufacturing sites:Industrial automation buyers deploy vision processors for quality inspection without cloud latency.
- Chiplets plus photonics convergence:Co-packaged optical I/O reduces data center interconnect power while enabling terabit-scale bandwidth.
Industry Challenges
- Physical design automation talent scarcity:Advanced node implementation requires specialists in computational lithography and power integrity analysis.
- Automotive functional safety certification:ISO 26262 ASIL-D compliance timelines extend 18-24 months for new processor architectures.
- Legacy instruction set migration friction:Embedded controller customers face software porting costs when shifting between proprietary and open architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microprocessor Market |
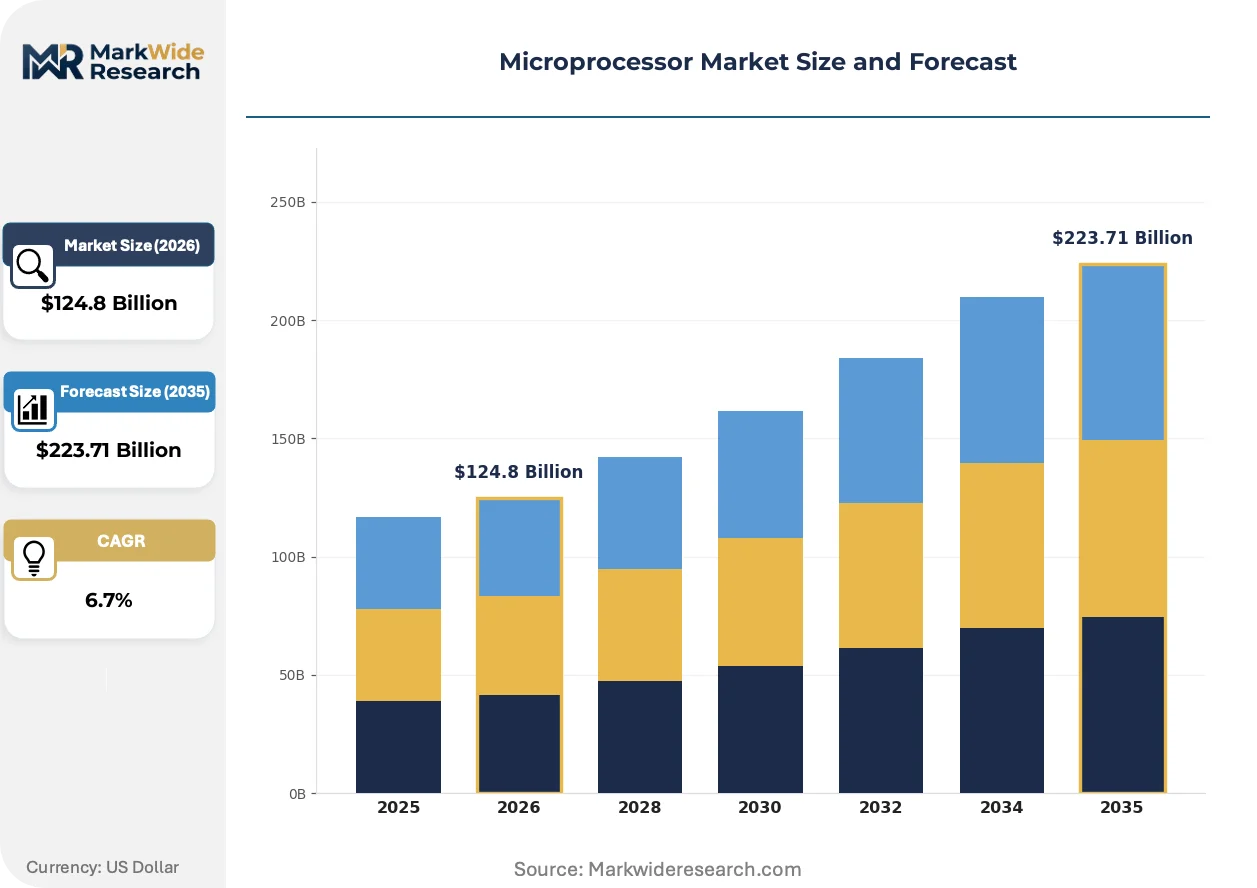
| Market Size in 2026 | $124.8 Billion |
| Market Size in 2035 | $223.71 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded, Desktop, Mobile, Server Architecture: x86, ARM, Power, RISC End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Service Type: Custom Design, Manufacturing, Testing, Support |
| Companies Covered | Qualcomm, Samsung Electronics, Intel Corporation, Broadcom Inc., Texas Instruments, Advanced Micro Devices (AMD), Arm Holdings, Apple Inc., NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microprocessor Market Emerging Trajectories
Compute architectures are fragmenting across domain-specific accelerators while packaging innovations compress power and latency constraints.
Chiplet-based modular processors are electrifying server and AI accelerator designs. Hyperscale data center operators adopt disaggregated memory and logic configurations to optimize total cost of ownership. This packaging approach is electrifying competitive dynamics by lowering barriers for custom silicon programs.
REACH and RoHS substance directives are tightening restrictions on halogenated flame retardants and lead-bearing solders in semiconductor packages. European automotive OEMs now require full material disclosure from tier-two component suppliers. Memory-integrated logic suppliers are accelerating green chemistry qualification programs to maintain CE marking eligibility.
Long-term foundry service agreements are replacing spot wafer purchases among fabless processor vendors. Automotive and aerospace buyers lock in multi-year capacity allocations to secure supply continuity. Japan's METI semiconductor subsidies are amplifying this contracting shift among domestic industrial equipment manufacturers.
Microprocessor Market Segmentation
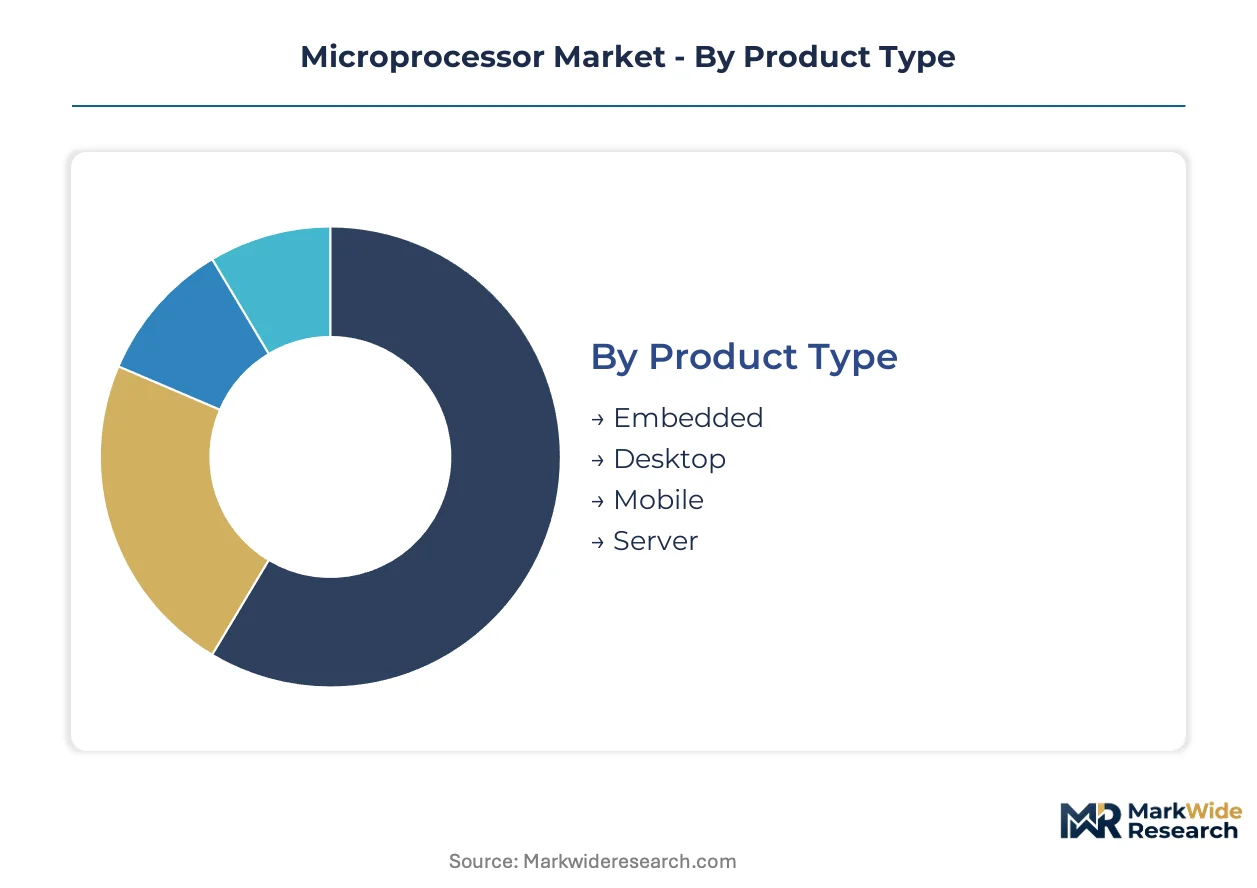
Microprocessor segmentation reveals how architectural choices and end-use requirements fragment procurement strategies across computing domains. Product specifications determine foundry node allocation, while service models reshape vendor-customer relationships in an era of custom silicon proliferation.
Product Type:
Gate density and thermal design power specifications differentiate processor categories across computing environments.
- Server:Multi-core designs with 64-bit addressing and extensive cache hierarchies dominate data center deployments. Hyperscale operators in the United States and China drive demand for accelerators with high memory bandwidth and PCIe interconnects.
- Embedded:Deterministic real-time execution with sub-10 watt thermal envelopes characterizes industrial controller and IoT gateway applications. Automotive ECU consolidation in Germany and Japan concentrates demand for ASIL-certified embedded cores.
- Mobile:Heterogeneous big.LITTLE configurations optimize battery life in smartphones and tablets.
- Desktop:Unlocked multiplier variants serve enthusiast gaming and workstation segments.
Mature deployment sits with Desktop processors in corporate refresh cycles. Newer deployment is concentrated in Server accelerators for generative AI training clusters.
Architecture:
Instruction set licensing terms determine royalty burdens and software ecosystem access for semiconductor designers.
- ARM:Reduced instruction set computing with variable-length pipeline stages enables power-efficient mobile and embedded implementations. South Korean smartphone OEMs and Taiwanese tablet manufacturers anchor volume demand for Cortex-A and Cortex-M series cores.
- x86:Complex instruction set computing with deep out-of-order execution sustains backward compatibility across decades of software. United States-based cloud providers and enterprise IT departments maintain installed base dominance.
- Power:Multithreading-optimized designs persist in legacy telecommunications infrastructure.
- RISC:Open-source instruction set architectures gain traction in academic and government research programs.
ARM licensing revenue scales with mobile attach rates. x86 maintains the steepest expansion trajectory in high-performance computing and AI inference.
End User:
Application-specific qualification requirements fragment processor validation timelines and reliability standards.
- Automotive:Functional safety certification under ISO 26262 mandates lockstep cores and error-correcting memory for autonomous driving computers. European OEMs in Stuttgart and Munich and Japanese manufacturers in Toyota City drive demand for ASIL-D capable silicon.
- Industrial Automation:Extended temperature ranges and deterministic latency characterize programmable logic controller and motion control applications. German machine tool builders and Japanese robotics manufacturers specify processors with 10-year supply guarantees.
- Consumer Electronics:Annual product refresh cycles prioritize cost optimization over longevity.
- Telecommunications:Network function virtualization shifts baseband processing from fixed-function ASICs to programmable architectures.
Automotive qualification timelines extend 18-24 months. Consumer Electronics procurement cycles compress below 12 months.
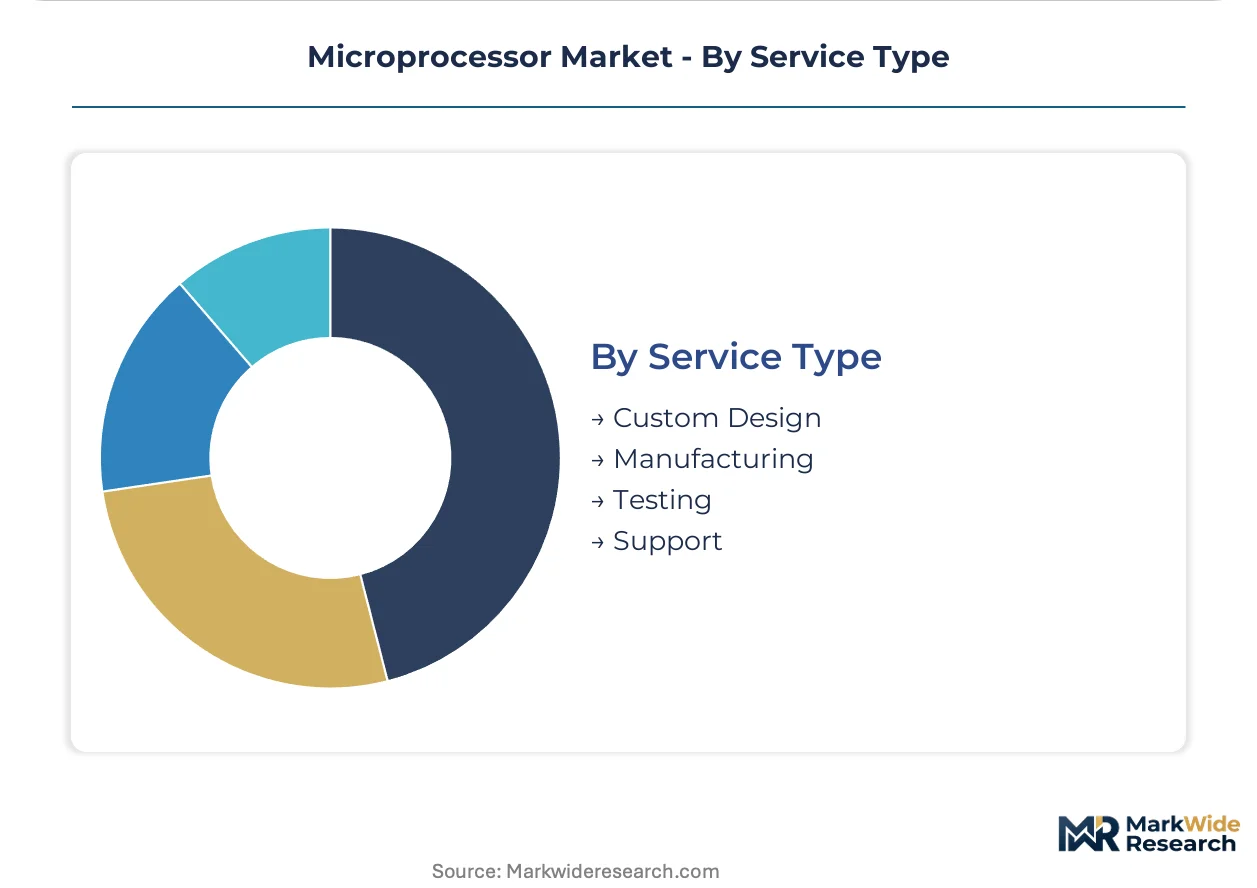
Service Type:
Value chain positioning determines margin capture and customer stickiness for semiconductor vendors.
- Custom Design:Application-specific integrated circuit and system-on-chip development services translate customer algorithms into optimized silicon implementations. United States hyperscalers and Chinese AI chip startups commission bespoke accelerators from design houses in Taiwan and Israel.
- Manufacturing:Wafer fabrication and advanced packaging services convert design files into physical devices. Taiwan's foundry ecosystem and South Korea's memory-integrated logic corridors concentrate leading-edge production capacity.
- Testing:Burn-in and wafer sort services verify yield and reliability before shipment.
- Support:Long-term maintenance contracts secure revenue from military and aerospace programs.
Manufacturing commands the highest capital intensity. Custom Design captures expanding share as system companies internalize silicon development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for microprocessors concentrates in East Asian manufacturing corridors and North American design centers, with regulatory fragmentation forcing supply chain reconfiguration across multiple jurisdictions.
United States
Hyperscale data center operators in Northern Virginia and Oregon drive demand for server-grade accelerators and high-bandwidth memory interfaces. The Department of Commerce export controls restrict advanced lithography equipment transfers to specific foundries, altering competitive access to sub-5nm nodes. Intel Corporation sustains captive fabrication in Arizona and Oregon while competing for external foundry allocation.
Taiwan
Foundry concentration for advanced logic nodes creates procurement bottlenecks for fabless processor vendors worldwide. The National Science and Technology Council subsidizes domestic semiconductor R&D while restricting technology outflows to mainland competitors. Hsinchu Science Park anchors TSMC's leading-edge fabrication complex with co-located packaging and testing facilities.
South Korea
Memory-integrated logic manufacturing corridors supply high-bandwidth DRAM and NAND alongside custom processors for smartphone OEMs. METI-equivalent industrial policy channels subsidies into domestic foundry capacity expansion and materials science research. Samsung Electronics anchors Pyeongtaek and Hwaseong production clusters with in-house Exynos fabrication and Qualcomm contract manufacturing.
China
Domestic substitution mandates accelerate demand for locally designed processors in telecommunications infrastructure and industrial automation. MIIT promotes domestic substitution through GB standards and dual carbon goals that constrain energy-intensive wafer production. Yangtze Memory Technologies and SMIC concentrate advanced packaging and mature-node logic in the Yangtze River Delta.
Germany
Automotive OEMs in Stuttgart and Munich specify ASIL-D certified processors for autonomous driving computers and powertrain controllers. The EU Chips Act subsidizes European fabrication capacity while REACH and RoHS directives govern substance restrictions in semiconductor packaging materials. Dresden's Silicon Saxony cluster hosts Infineon and Bosch semiconductor operations with expanding 300mm wafer capacity.
Microprocessor Market Vendor Landscape
Capacity expansion dominates the current landscape as foundry vendors race to secure EUV lithography equipment and construct greenfield fabrication complexes. The vendor base stratifies across three tiers: integrated device manufacturers with captive fabs, pure-play foundries with leading-edge nodes, and fabless designers reliant on external manufacturing. Strategic archetypes include vertically integrated technology conglomerates, specialized accelerator architects, and intellectual property licensing specialists. M&A activity concentrates in advanced packaging capabilities and automotive-qualified design teams, while long-term foundry service agreements replace spot wafer purchases among risk-averse procurement departments.
Among the integrated device manufacturers, Intel Corporation and Samsung Electronics occupy positions spanning design, fabrication, and packaging. NVIDIA Corporation exemplifies the fabless accelerator archetype, leveraging Taiwan Semiconductor Manufacturing for advanced node GPUs while navigating supply diversification into Japan. Qualcomm and Broadcom occupy positions within the wireless and networking semiconductor segments, respectively.
| Leading Market Players |
|---|
| Qualcomm |
| Samsung Electronics |
| Intel Corporation |
| Broadcom Inc. |
| Texas Instruments |
| Advanced Micro Devices (AMD) |
| Arm Holdings |
| Apple Inc. |
| NVIDIA Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed foundry subsidies in Taiwan and South Korea have compressed capital recovery timelines for advanced node production, tightening pricing discipline among leading-edge suppliers while forcing tier-two vendors toward mature-node specialization. This ownership pattern concentrates pricing power with state-anchored producers capable of absorbing multi-billion-dollar fab investments, while fabless designers face take-or-pay contract structures that lock in volume commitments regardless of downstream demand fluctuations.
Pricing Analysis
Volume-mature server and mobile processors trade on thin margins at wafer-scale, while automotive-grade and custom AI accelerators capture premium returns through ASIL-D certification requirements and long-term supply guarantees. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-level processors separates qualification-intensive segments from commodity silicon. Pricing pressure stems from EUV equipment scarcity forcing foundry customers into binding multi-year prepayments that strain working capital. Consumer electronics OEMs exhibit highest price sensitivity, whereas automotive procurement teams prioritize supply continuity over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore, Penang, and Rotterdam buffer finished processor inventory against fab concentration risk in Taiwan and South Korea. Raw material dependencies center on high-purity silicon wafers from Japan, photoresist chemicals from Belgium and Japan, and noble gases extracted from Ukrainian and Russian feedstocks. Single-source vulnerability at ASML's EUV lithography equipment creates chokepoint exposure for sub-5nm production. Distribution runs through authorized distributor networks serving contract manufacturers in Vietnam and Mexico, with direct fulfillment to hyperscale data center operators in Northern Virginia and Frankfurt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microprocessor market functions as a cost-of-compliance arena where EU AI Act conformity requirements and ISO 26262 certification timelines erect formidable barriers against unqualified competitors. This regulatory moat rewards incumbents with established automotive safety architectures while forcing aspirants into protracted qualification investments that delay revenue recognition.
For Market Incumbents: Cement captive foundry allocation through multi-year prepayment structures with Taiwan Semiconductor Manufacturing and Samsung Foundry, insulating against capacity competition from AI chip startups. Accelerate backward integration into advanced packaging capabilities in Arizona and Penang to capture margin erosion from heterogeneous integration trends. Prioritize ASIL-D certification pipeline expansion ahead of European OEM platform consolidation in Stuttgart and Munich. For New Entrants and Emerging Players: Enter via India's PLI-subsidized assembly and test facilities, exploiting tariff advantages and design center cost structures unavailable in established corridors. Target industrial automation segments in Germany and Japan where 10-year supply guarantees command pricing premiums unavailable in consumer electronics. Pursue chiplet-based modular architectures that reduce upfront mask costs and accelerate time-to-revenue versus monolithic designs. For Investors and Strategic Acquirers: Distressed-cycle entries favor automotive-qualified design teams in Israel and automotive software-integration specialists in Germany as valuation multiples compress from interest rate normalization. Long-term viability hinges on securing foundry capacity allocation through the current capex cycle rather than design IP alone. Monitor Japan's METI subsidy disbursement velocity as an inflection indicator for regional supply chain rebalancing away from Taiwan concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Foundry Service Agreements | Automotive OEMs in Germany and Japan lock multi-year wafer allocations to secure ASIL-D supply continuity. |
| Advanced Packaging Capacity Expansion | Co-packaged optical I/O investments in Penang and Singapore reduce data center interconnect power consumption. |
| Automotive Functional Safety Certification | ISO 26262 ASIL-D compliance programs in Dresden and Toyota City extend processor qualification timelines. |
| Chiplet Architecture Adoption | Modular designs using 2.5D integration lower yield losses while enabling heterogeneous compute configurations. |
| Geographic Supply Diversification | Japan's METI subsidies attract foundry investments that reduce procurement concentration in Taiwan's Hsinchu corridor. |
Methodological Framework
Document review covered SEC 10-K filings from fabless semiconductor vendors, foundry utilization disclosures from Taiwan and South Korea, and EU regulatory filings under REACH and RoHS directives, complemented by interviews with fab operations executives, automotive procurement managers at German OEMs, and IP licensing specialists at ARM Holdings. Primary fieldwork engaged foundry capacity planners, EDA tool vendors, and packaging substrate suppliers across the analysis window. Secondary validation drew from customs wafer import records, SEMI equipment billings data, and hyperscaler capex announcements. Bottom-up unit demand estimates triangulated against top-down foundry revenue allocations.
Historical shipment patterns from IHS Markit semiconductor databases cross-referenced against panel input from foundry customer advisory boards established projection baselines. Segmentation modeling spanned architecture type, thermal design power tier, end-use qualification level, and regional production cluster across the modeling period. CAGRs derived from node transition timelines and automotive silicon content trajectories. Forecast inputs incorporated EUV equipment delivery schedules, automotive platform electrification roadmaps, and packaging technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation or Taiwan Strait logistics disruption scenarios. Projections reflect documented assumptions regarding node yield maturation and automotive qualification cycle stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
Global Microprocessor and GPU Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Europe Neuromorphic Chip Market