
 China Microprocessor (MPU) Market | 2026-2036
China Microprocessor (MPU) Market Size, Share, and Industry Trends Forecast 2026-2036
China Microprocessor (MPU) Market Insights
Multi-source procurement is consolidating among state-backed server OEMs seeking to reduce dependence on foreign silicon. HiSilicon leverages its Kirin and Kunpeng architectures to anchor domestic supply for telecom and cloud infrastructure. Loongson Technology sustains LoongArch ISA development for government and education procurement. Zhaoxin competes in x86-compatible desktop segments through joint-venture licensing arrangements.
A microprocessor unit executes programmed instructions via integrated arithmetic logic, control units, and register arrays fabricated on monolithic semiconductor dies using sub-7nm lithography nodes, functioning as the central computation engine for electronic systems. Embedded MPU architectures dominate industrial and automotive deployments where real-time deterministic processing meets stringent thermal envelopes. General-purpose MPUs lead volume in consumer computing, while 64-bit multi-core configurations capture the highest value per socket in data center and edge AI workloads. Application-specific MPUs for baseband and AI acceleration represent the fastest-growing margin pool as telecommunications vendors integrate heterogeneous compute.
MIIT sets domestic IC industry targets through the Made in China framework, while SAMR enforces antitrust and merger review over foreign semiconductor firms operating locally. GB standards for information security and cryptography mandate certified implementations in government and critical infrastructure procurement. Stakeholders must monitor how export control reciprocity and domestic certification timelines reshape competitive access to advanced process nodes and design tools.
Market Dynamics
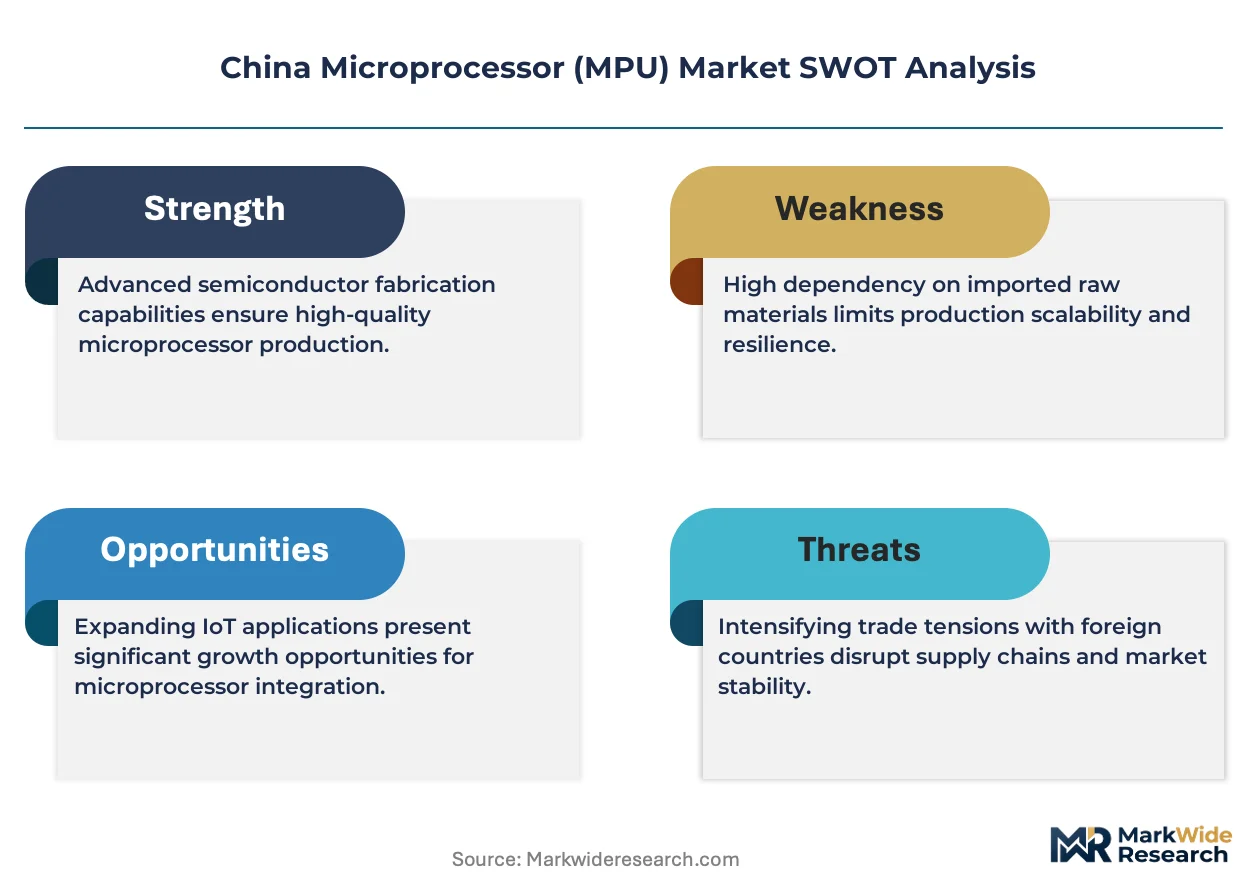
Import substitution mandates from MIIT are restructuring procurement flows across China's server and infrastructure compute segments, forcing rapid domestic architecture validation and foundry capacity allocation toward locally designed MPUs.
Growth Catalysts
- Domestic Data Center Buildout:State-backed cloud operators are expanding hyperscale facilities in the Yangtze River Delta, creating captive demand for server-grade silicon with certified supply chain provenance.
- GB Standards Mandate:National information security and cryptography certification requirements now govern government and critical infrastructure procurement, disqualifying non-compliant foreign designs from tender eligibility.
- Sub-7nm Lithography Maturation:Domestic foundry progression toward advanced nodes is enabling performance parity for indigenous CPU architectures in high-throughput workloads.
Market Restraints
- EUV Equipment Access Bottleneck:Export control restrictions on extreme ultraviolet lithography systems constrain domestic foundry progression beyond certain node thresholds, capping peak performance for locally fabricated designs.
- ISA Licensing Friction:x86 and ARM architectural licensing remains concentrated with foreign IP holders, creating royalty exposure and legal uncertainty for domestic vendors pursuing compatible implementations.
- Design Tool Dependency:Electronic design automation software for advanced physical verification and sign-off remains dominated by non-domestic suppliers, creating workflow vulnerability.
Strategic Opportunities
- Edge AI Inference Deployment:Base station and industrial gateway installations are generating demand for heterogeneous compute combining CPU cores with dedicated neural acceleration, opening margin-rich socket configurations.
- Automotive Zonal Architecture:Electric vehicle platforms are integrating centralized compute nodes for ADAS and infotainment, creating specification opportunities for automotive-qualified MPU suppliers.
- Made in China 2025 Incentives:Tax credits and procurement preference policies for domestically designed ICs are reducing effective R&D cost burdens for qualifying development programs.
Industry Challenges
- Physical Design Talent Scarcity:Experienced engineers capable of full-custom layout and power optimization for sub-7nm implementations remain concentrated among a small number of domestic design houses.
- Certification Timeline Compression:GB standards compliance validation for new processor families requires extended test cycles that lag product announcement schedules, delaying revenue recognition.
- Heterogeneous Software Stack Integration:Operating system and compiler ecosystem porting to indigenous ISAs demands sustained engineering investment beyond silicon tape-out.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Microprocessor (MPU) Market |
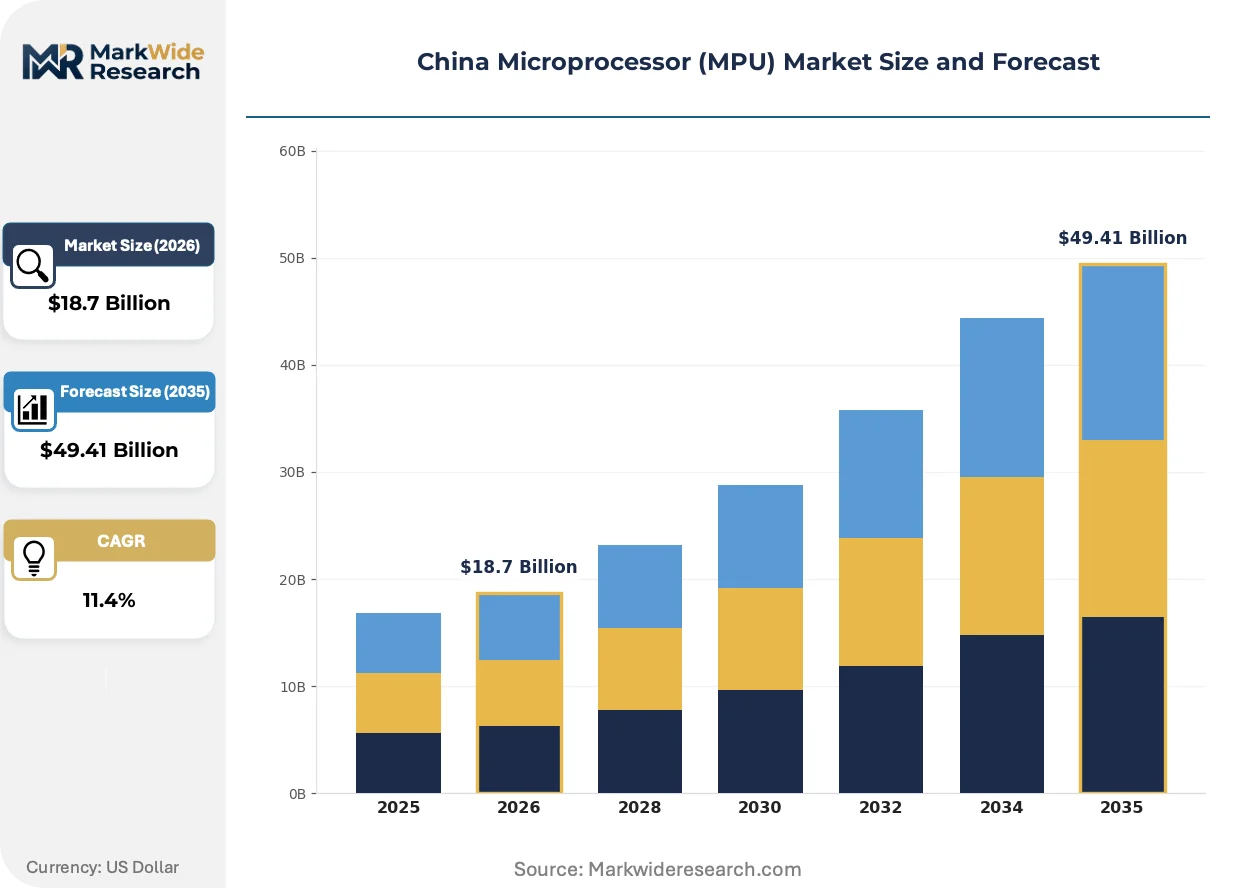
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded MPU, Digital Signal Processor, General-Purpose MPU, Application-Specific MPU Technology: 32-bit, 64-bit, Multi-core, Single-core End User: Consumer Electronics, Automotive Systems, Industrial Automation, Telecommunications Application: Smartphones, IoT Devices, Gaming Consoles, Embedded Systems |
| Companies Covered | HiSilicon, Loongson Technology, Zhaoxin, Intel Corporation, Advanced Micro Devices, Qualcomm Technologies, SMIC, UNISOC, Texas Instruments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Microprocessor (MPU) Market Trends and Innovations
Compute specialization is fragmenting the monolithic CPU model, with dedicated acceleration engines for AI and cryptography displacing general-purpose cores in high-value sockets across China's infrastructure buildout.
Chiplet-based modular architectures are expanding into server and high-performance computing segments, enabling yield recovery and cost optimization through disaggregated die assembly. Domestic designers are adopting advanced packaging techniques to integrate logic, memory, and I/O on interposer substrates. This approach is expanding into the supply strategies of state-backed OEMs seeking to mitigate single-die reticle limits.
MIIT's integrated circuit promotion policies are tightening procurement qualification windows for government and critical infrastructure tenders. The framework mandates domestic design ownership thresholds and certified foundry provenance for eligible suppliers. Server OEMs are responding by accelerating validation roadmaps for indigenous CPU platforms to maintain tender eligibility.
Multi-source silicon strategies are consolidating among state-backed operators, with direct foundry relationships displacing merchant semiconductor distribution channels. Procurement teams are negotiating long-term capacity reservations with domestic fabs to secure allocation priority. This pattern is most visible among telecom infrastructure vendors integrating compute into 5G baseband and edge aggregation platforms.
China Microprocessor (MPU) Market Segmentation
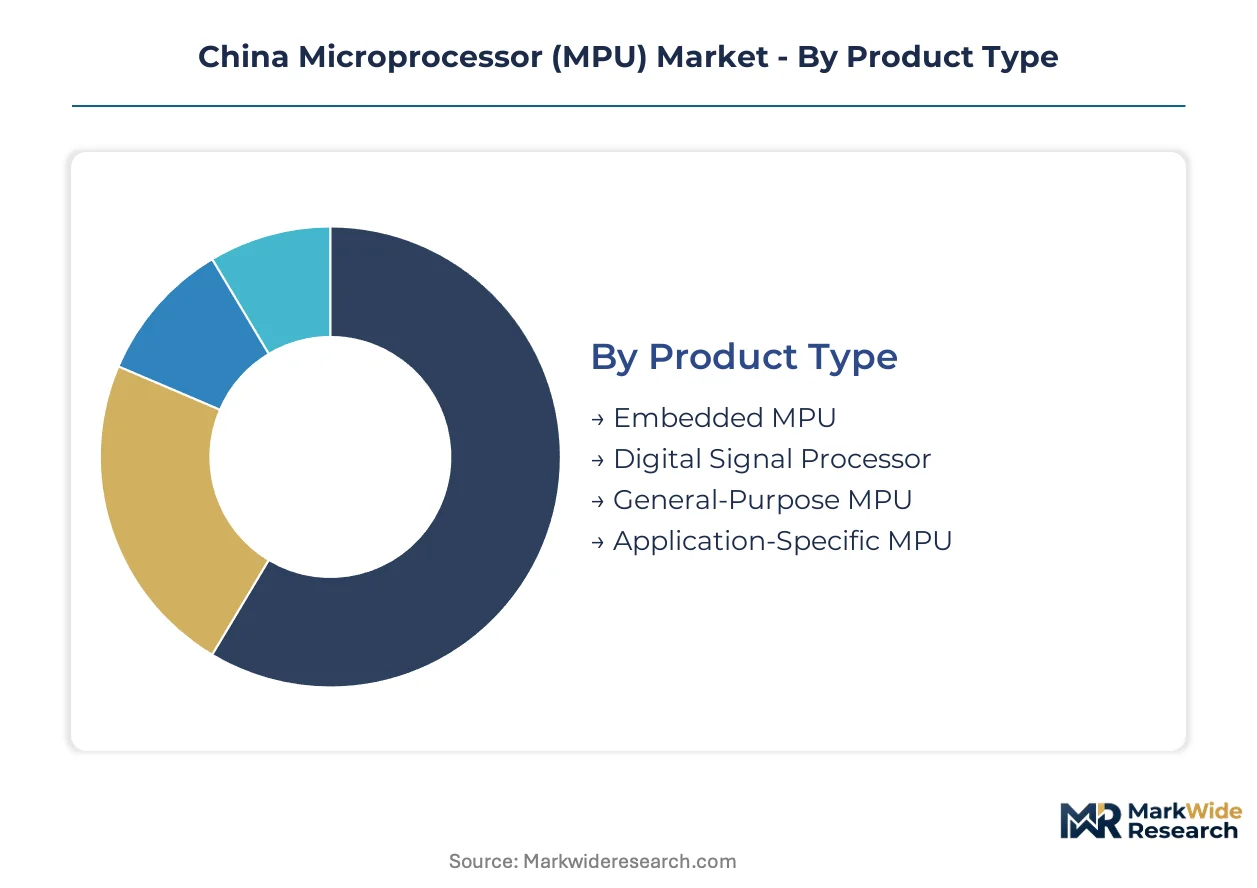
Segmentation reveals how procurement mandates and certification requirements reshape competitive access across China's MPU landscape. Domestic vendors calibrate architecture roadmaps against GB standards compliance windows and foundry capacity allocation priorities.
Product Type:
Standardization dominates embedded and general-purpose categories, while application-specific designs demand heavy customization for cryptography and AI acceleration.
- General-Purpose MPU:These architectures execute broad instruction sets across consumer computing and enterprise servers without workload-specific optimization. Procurement from state-backed cloud operators in the Yangtze River Delta cluster anchors volume, though ISA licensing friction constrains x86-compatible domestic alternatives.
- Application-Specific MPU:Custom silicon integrates dedicated engines for baseband processing, neural network inference, or cryptographic acceleration alongside general-purpose cores. 5G infrastructure vendors in Shenzhen and Beijing drive specification requirements for heterogeneous compute sockets combining CPU cores with fixed-function acceleration.
- Embedded MPU:Deterministic real-time architectures serve industrial controllers and automotive ECUs with strict thermal and latency envelopes. Factory automation deployments in Jiangsu province generate specification demand for extended temperature-grade silicon.
- Digital Signal Processor:Specialized multiply-accumulate pipelines accelerate audio, video, and sensor fusion workloads. Automotive ADAS platforms integrate these cores for radar and lidar signal processing.
Leading the category by volume: General-Purpose MPU. Growing fastest: Application-Specific MPU.
Technology:
Node migration economics favor 64-bit multi-core configurations in data center sockets, while 32-bit architectures retain cost advantages at the edge.
- 64-bit:Extended address spaces and register files enable memory-intensive workloads across server virtualization and AI training pipelines. Domestic foundry progression toward sub-7nm nodes unlocks performance parity for indigenous designs in high-throughput applications.
- Multi-core:Die-level parallelism scales throughput for thread-rich cloud and edge AI workloads without frequency-driven power penalties. Telecom infrastructure vendors specify octa-core and above configurations for baseband aggregation platforms.
- 32-bit:Compact instruction sets and reduced memory footprints suit cost-constrained IoT endpoints and legacy industrial controllers. Sensor gateway deployments in Zhejiang manufacturing corridors sustain procurement volume.
- Single-core:Minimal silicon area and deterministic execution profiles serve ultra-low-power wearable and medical device applications. Battery-constrained designs in consumer electronics procurement favor these implementations.
Highest margin concentration: 64-bit Multi-core. Steepest expansion trajectory: Multi-core configurations with AI acceleration extensions.
End User:
Automotive and telecommunications segments command premium pricing through qualification rigor, while consumer electronics drives absolute volume.
- Telecommunications:Baseband processing, edge aggregation, and core network functions demand carrier-grade reliability with 99.999% uptime specifications. MIIT procurement mandates for domestic silicon provenance redirect supply chain validation toward indigenous CPU and NPU architectures.
- Automotive Systems:Zonal E/E architectures consolidate ADAS, infotainment, and body control onto centralized compute nodes with ASIL-D functional safety requirements. Electric vehicle platforms from Shanghai and Guangzhou anchor specification development for automotive-qualified MPUs.
- Industrial Automation:Real-time deterministic control and extended temperature operation specifications govern PLC and motion controller deployments. Smart factory initiatives in Suzhou and Wuxi generate socket opportunities for ruggedized embedded processors.
- Consumer Electronics:High-volume smartphone and tablet procurement prioritizes cost-optimized silicon with integrated connectivity and multimedia acceleration. Domestic OEMs in Shenzhen and Dongguan negotiate directly with foundries for allocation priority.
Largest absolute demand: Consumer Electronics. Fastest specification evolution: Automotive Systems.
Application:
Smartphone sockets concentrate procurement scale, while embedded systems fragment across specialized vertical requirements.
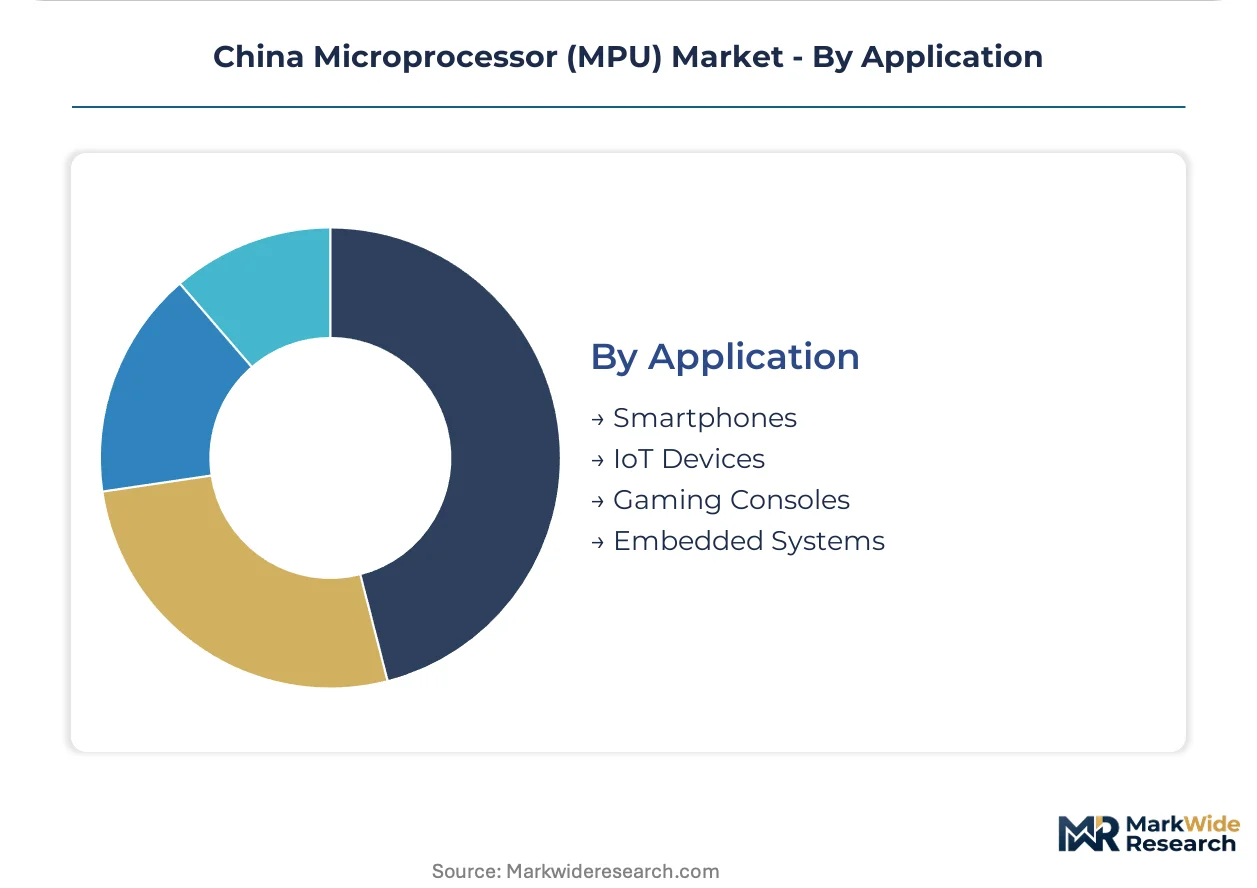
- Smartphones:Application processors integrate CPU, GPU, NPU, and modem subsystems on monolithic or chiplet-based dies. Domestic brands source from captive silicon divisions and merchant suppliers with certified supply chain documentation for government tender eligibility.
- Embedded Systems:Industrial controllers, medical devices, and infrastructure equipment demand long lifecycle support with decade-plus availability guarantees. Railway signaling and power grid automation in the Yangtze River Delta specify extended-temperature industrial-grade silicon.
- IoT Devices:Ultra-low-power microcontrollers with integrated wireless connectivity serve sensor networks and smart home endpoints. Agricultural monitoring deployments in Shandong and Henan provinces drive volume for sub-gigahertz radio-integrated MPUs.
- Gaming Consoles:Custom APUs with high-bandwidth memory interfaces and dedicated graphics pipelines target performance-per-watt optimization. Cloud gaming infrastructure in Beijing and Shanghai creates secondary demand for server-grade rendering silicon.
Dominant procurement volume: Smartphones. Most fragmented requirements: Embedded Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon feedstock from the Yangtze River Delta anchors China's domestic MPU fabrication ecosystem. Provincial industrial policies and municipal semiconductor funds concentrate capacity expansion across eastern coastal clusters. Sub-national competition for design talent and foundry investment reshapes procurement geography.
Shanghai
Hyperscale cloud operators expand server-grade MPU procurement with certified supply chain documentation. MIIT's integrated circuit promotion policies mandate domestic design ownership thresholds for government tender eligibility. Zhangjiang Hi-Tech Park hosts validation laboratories for sub-7nm process qualification.
Jiangsu
Smart factory automation generates socket demand for industrial-grade embedded processors with extended temperature specifications. SAMR enforces antitrust review over foreign semiconductor firms operating locally. Suzhou and Wuxi manufacturing corridors concentrate motion controller and PLC deployments.
Zhejiang
Sensor gateway installations in Hangzhou manufacturing zones sustain 32-bit microcontroller procurement volume. GB standards for information security govern critical infrastructure qualification timelines. Ningbo and Shaoxing industrial clusters drive sub-gigahertz radio-integrated MPU specifications.
Beijing
Telecom infrastructure vendors specify heterogeneous compute sockets for 5G baseband and edge aggregation platforms. Dual carbon goals accelerate power efficiency requirements for data center silicon. Zhongguancun software corridor concentrates compiler and operating system ecosystem porting investment.
Guangdong
Consumer electronics OEMs negotiate direct foundry relationships for smartphone application processor allocation priority. Export control reciprocity measures reshape competitive access to advanced design tools. Shenzhen and Dongguan electronics manufacturing clusters integrate captive silicon divisions into procurement strategies.
China Microprocessor (MPU) Market Competitive Landscape
Global majors compete with regional champions across architecture licensing and foundry capacity allocation. The vendor base stratifies into three tiers: foreign IP holders with established x86 and ARM ecosystems, domestic designers pursuing indigenous ISAs, and state-backed foundries enabling captive supply chains. Strategic archetypes include architecture licensors, fabless design houses, and integrated device manufacturers. Competitive moves concentrate on long-term capacity reservations and certification timeline acceleration.
Among domestic fabless designers, HiSilicon and Loongson Technology exemplify contrasting approaches to ISA independence. HiSilicon occupies a position within the ARM-compatible tier leveraging telecom infrastructure relationships. Loongson Technology anchors the indigenous ISA vector through government and education procurement channels. Zhaoxin sits within the x86-compatible segment via joint-venture licensing arrangements.
| Leading Market Players |
|---|
| HiSilicon |
| Loongson Technology |
| Zhaoxin |
| Intel Corporation |
| Advanced Micro Devices |
| Qualcomm Technologies |
| SMIC |
| UNISOC |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
Polysilicon spot price volatility in the Yangtze River Delta cascades through wafer fabrication costs into three-tier pricing structures across premium, standard, and economy certification levels for server-grade MPUs. State-backed cloud operators absorb premium tier premiums for GB-compliant provenance while industrial buyers negotiate standard-tier contracts with extended availability guarantees.
Pricing Analysis
Warranty and field service bundling separate premium-tier server MPUs from unbundled standard offerings where aftermarket support carries separate negotiation. Pricing stratifies across GB-certified, MIIT-registered, and uncertified tiers with cryptography engine integration commanding quality premiums. Cost compression in the standard tier intensifies as domestic foundry capacity expansion outpaces demand growth from provincial cloud buildouts. Consumer electronics OEMs in Guangdong exhibit highest price sensitivity while telecom infrastructure vendors accept premium positioning for carrier-grade reliability specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from state-backed cloud operators while merchant distribution serves fragmented industrial and automotive procurement. Wafer fabrication concentrates in Taiwan, South Korea, and mainland China with advanced node dependency on EUV equipment from Dutch and Japanese suppliers. Raw material flows draw from high-purity polysilicon in Xinjiang, photoresist chemicals from Japan, and specialty gases from South Korea. Single-source vulnerability in EUV lithography systems creates structural risk for domestic foundry progression beyond certain node thresholds. Distribution runs through captive silicon divisions for smartphone OEMs and long-term capacity reservations for server operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MPU market functions as a cost-of-compliance story where MIIT's integrated circuit promotion policies erect barrier-to-entry moats favoring domestic design houses with certified foundry relationships and GB standards validation.
For Market Incumbents: Deepen backward integration into captive wafer supply through long-term SMIC capacity reservations to defend against emerging fabless competitors. Accelerate certification timeline compression by pre-positioning validation data with MIIT laboratories before product announcements. State-backed cloud operators' procurement consolidation threatens merchant silicon channels without direct foundry relationships.
For New Entrants and Emerging Players: Enter via automotive zonal compute sockets where ASIL-D qualification requirements filter out established consumer electronics suppliers. Target Jiangsu industrial automation corridors for embedded MPU specifications with decade-plus lifecycle guarantees. Position through direct engagement with Suzhou and Wuxi smart factory initiatives rather than competing for saturated server sockets.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless design houses with validated LoongArch or RISC-V implementations in Beijing and Shanghai corridors. Long-term viability hinges on ISA independence from ARM and x86 licensing friction. Watch for MIIT procurement mandate expansion into telecommunications edge infrastructure as inflection signal for domestic architecture demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Foundry Capacity Reservation | Secures allocation priority at SMIC and Hua Hong for state-backed OEM qualification roadmaps. |
| GB Standards Pre-certification Investment | Compresses revenue recognition delays by front-loading cryptography validation with MIIT laboratories. |
| Chiplet-based Modular Architecture Adoption | Enables yield recovery and cost optimization through disaggregated die assembly at advanced packaging facilities. |
| Automotive ASIL-D Qualification Pathway | Opens premium socket opportunities in Shanghai and Guangzhou electric vehicle platform specifications. |
| Indigenous ISA Ecosystem Porting | Reduces royalty exposure from foreign IP holders while aligning with government procurement preference policies. |
Research Methodology
Independent corroboration across MIIT policy filings, SAMR merger review records, and provincial semiconductor fund disclosures underwrites the qualitative findings on competitive access restructuring. Primary interviews with fabless design house executives, foundry planning officers, and state-backed server OEM procurement directors combined with secondary validation from customs trade data, SEC semiconductor firm filings, and hyperscaler capex disclosures. Bottom-up socket demand modeling and top-down industrial policy impact assessment triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from value migration across the projection horizon. Segmentation dimensions modeled include product architecture type, bit-width and core configuration, end-use industry vertical, and application socket with regional procurement cluster overlay. CAGRs derive from installed base replacement cycles, foundry capacity expansion schedules, and MIIT mandate implementation timelines. Forecast inputs incorporate EUV equipment access constraints and domestic lithography node progression curves without specific year anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control reciprocity escalation or accelerated domestic certification timeline compression. Periodic stress-testing of base assumptions is recommended given policy implementation velocity and foundry equipment access uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Plasmonic Chip Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Micro Server IC Market