
 Secure Microcontrollers/Processors Market | 2026-2036
Secure Microcontrollers/Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Secure Microcontrollers/Processors Market Analytics
Subscription-based firmware update services is realigning how semiconductor vendors monetize secure microcontroller deployments over multi-year lifecycles. Infineon Technologies leverages its embedded security software stack to extend recurring revenue beyond silicon sales. NXP Semiconductors anchors automotive trust anchor programs through long-term service agreements with tier-one suppliers. STMicroelectronics differentiates via integrated secure manufacturing services that bundle provisioning with device lifecycle management.
Secure microcontrollers and processors are integrated circuits incorporating dedicated cryptographic accelerators, tamper-resistant memory, and isolated execution environments designed to protect data integrity and authentication in connected systems. These devices typically operate at frequencies between 32 MHz and 500 MHz with embedded flash densities from 128 KB to 2 MB, serving critical functions in payment terminals, vehicle networks, and medical devices where hardware-rooted trust is mandatory. Secure elements and hardware security modules command premium positioning due to certification requirements under Common Criteria and FIPS 140-2 standards that constrain supply. Microcontrollers for automotive applications sustain the largest volume base, while trusted execution environments represent the fastest-expanding technology segment as edge AI workloads multiply attack surfaces.
FDA cybersecurity guidance for connected medical devices, EPA requirements for secure industrial control systems, and FCC equipment authorization rules collectively mandate hardware-level security implementations that shape procurement specifications across North America. The EU Cyber Resilience Act and GDPR data protection standards in Europe impose parallel compliance burdens that favor pre-certified component sourcing. Stakeholders must monitor quantum-resistant algorithm standardization timelines to align product roadmaps with anticipated NIST migration requirements.
Market Dynamics
Post-quantum cryptography migration is compressing replacement cycles across industrial automation and automotive ECU architectures, forcing hardware security module refreshes ahead of traditional semiconductor obsolescence schedules.
Growth Catalysts
- UN R155 Vehicle Cybersecurity Mandates:Automotive OEMs embed hardware security modules in ECU architectures to satisfy type-approval requirements, creating mandatory pull for certified secure elements.
- EU Cyber Resilience Act:Connected device manufacturers face hardware-level security obligations that favor pre-certified microcontroller sourcing over in-house security implementations.
- Edge AI Workload Expansion:Trusted execution environments multiply attack surfaces in distributed inference systems, accelerating demand for isolated cryptographic processing.
Market Restraints
- Common Criteria Certification Bottlenecks:Evaluation facility capacity constraints extend qualification timelines to 18-24 months for EAL4+ secure elements.
- Advanced Node Wafer Costs:Tamper-resistant memory architectures require specialized foundry processes at 40nm and above, insulating secure microcontroller production from mainstream cost curves.
- Post-Quantum Algorithm Uncertainty:NIST standardization timelines for lattice-based cryptography delay product roadmaps as vendors await final parameter sets.
Strategic Opportunities
- Medical Device Cybersecurity Gaps:FDA premarket guidance for connected diagnostics creates unmet demand for hardware-rooted trust in patient monitoring systems.
- Subscription Firmware Services:Semiconductor vendors capture recurring revenue through long-term service agreements bundling provisioning with lifecycle management.
- Industrial Control System Hardening:EPA requirements for secure SCADA architectures drive replacement of legacy PLCs lacking hardware security modules.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:Side-channel analysis and fault injection expertise concentrates in a handful of specialized design houses.
- Multi-Jurisdiction Certification Stacking:FIPS 140-2, Common Criteria, and automotive PP-0084 evaluations impose parallel compliance burdens without mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secure Microcontrollers/Processors Market |
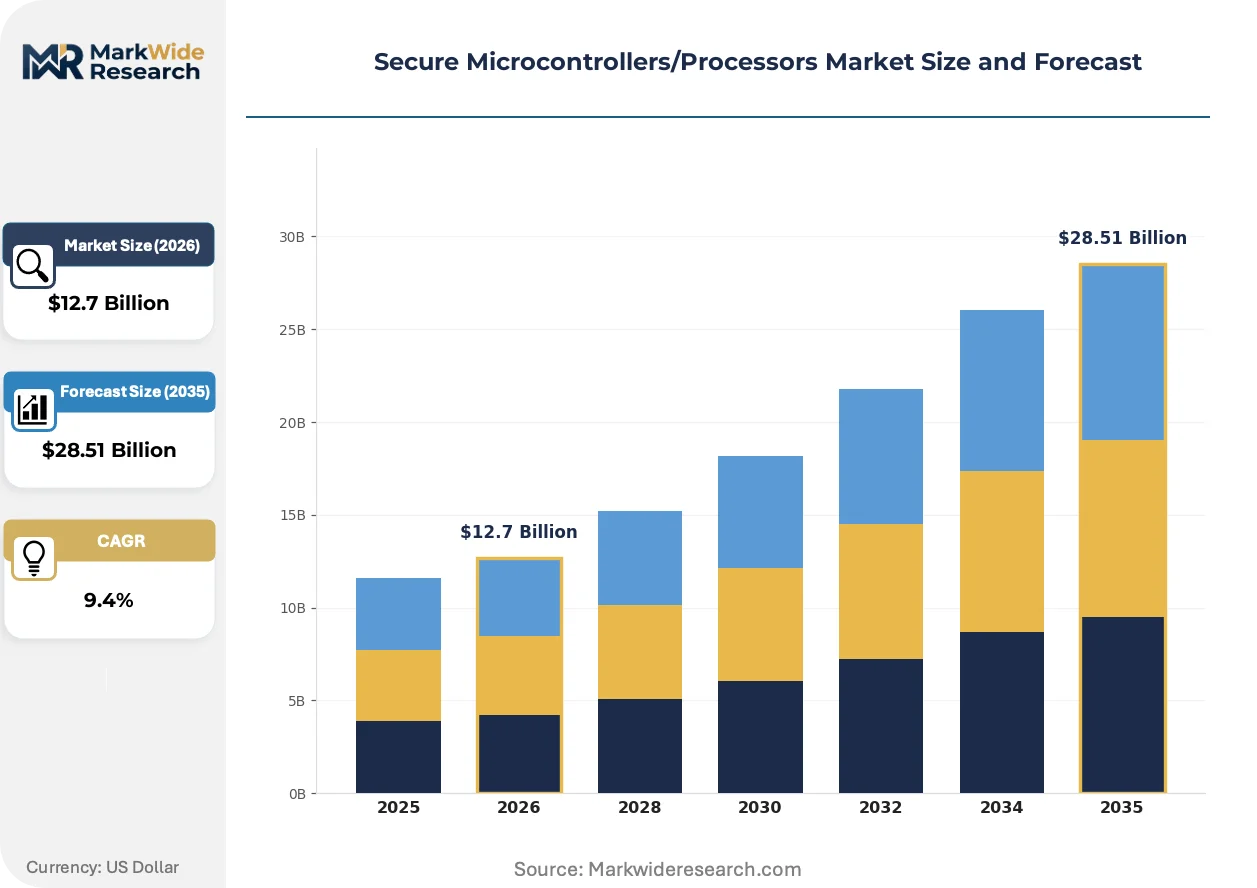
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Processors, Secure Elements, Microcontrollers, System-on-Chip End User: Automotive, Consumer Electronics, Industrial, Healthcare Application: Access Control, Secure Communication, Payment Processing, Identity Management Technology: Hardware Security Modules, Trusted Execution Environments, Secure Boot, Cryptography |
| Companies Covered | Infineon Technologies, NXP Semiconductors, STMicroelectronics, Microchip Technology, Renesas Electronics, Texas Instruments, Winbond Electronics, Analog Devices, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secure Microcontrollers/Processors Market Evolving Landscape
Hardware security architectures are fragmenting into composable subsystems that disaggregate cryptographic acceleration from application processing, enabling tiered security configurations across cost-sensitive and high-assurance deployments.
Physically unclonable function integration is modularizing device-unique key generation into standard cell libraries. Automotive tier-one suppliers adopt PUF-based secure boot implementations at volume scale. This modularization collapses the traditional boundary between discrete secure elements and host microcontrollers.
EU AI Act risk-classification rules mandate hardware-backed audit logging for high-risk AI systems. Medical device manufacturers pre-position tamper-evident secure elements to satisfy conformity assessment requirements. Industrial automation vendors in Germany anchor compliance roadmaps to anticipated EN harmonized standards.
Long-term service agreements displace discrete component sales in automotive trust anchor programs. Tier-one suppliers contract directly with semiconductor vendors for multi-year firmware update entitlements. This pattern concentrates most visibly in German automotive supply chains where OEMs outsource cybersecurity lifecycle management.
Secure Microcontrollers/Processors Market Segmentation
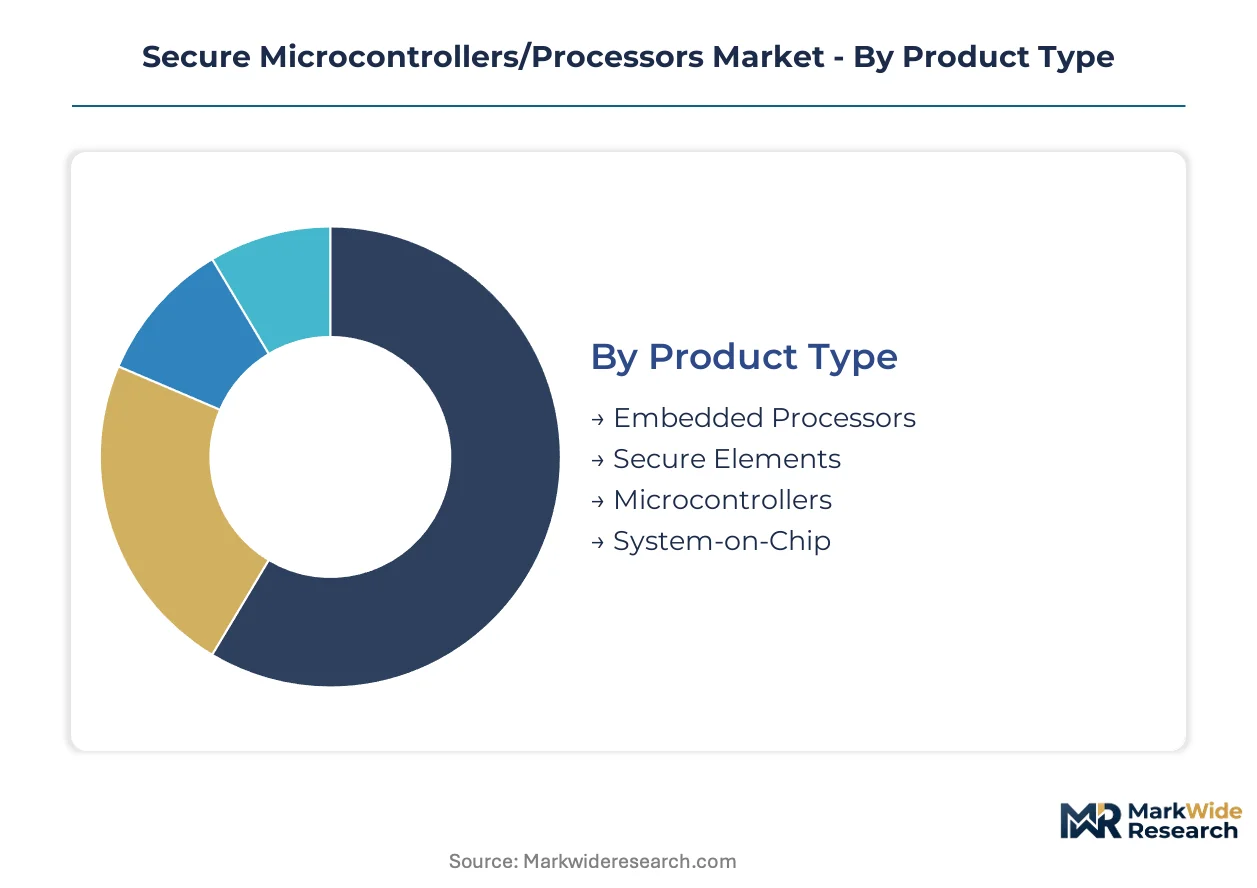
Segmentation in secure microcontrollers and processors reflects divergent certification burdens, performance thresholds, and lifecycle requirements across end-use verticals. Buyers select architectures based on tamper-resistance grades, cryptographic throughput needs, and regulatory pre-certification status rather than unit cost alone.
Product Type:
Procurement patterns across product types track directly to the certification depth buyers require and the integration complexity their systems tolerate.
- Microcontrollers:These devices integrate cryptographic accelerators, tamper-resistant memory, and isolated execution environments on single dies operating between 32 MHz and 500 MHz. Automotive ECU architectures in Germany anchor the largest volume deployments, driven by UN R155 mandates that hardware-security-module embedding satisfies type-approval requirements. Microcontrollers lead volumes today; secure elements are gaining share fastest.
- Secure Elements:Discrete tamper-resistant chips certified to Common Criteria EAL4+ or FIPS 140-2 Level 3 provide root-of-trust isolation from host processors. Payment terminal manufacturers in France concentrate demand here, constrained by evaluation facility bottlenecks that extend qualification timelines to 18-24 months.
- Embedded Processors:Higher-frequency application processors with cryptographic coprocessors serve edge AI inference workloads requiring hardware-backed audit logging.
- System-on-Chip:Integrated solutions combining application processing, connectivity, and security subsystems reduce bill-of-materials complexity for cost-sensitive consumer electronics.
Secure elements command premium positioning due to certification scarcity; microcontrollers dominate unit economics at scale.
End User:
End-user segmentation isolates where hardware-rooted trust transitions from competitive differentiation to regulatory mandate.
- Automotive:OEMs embed hardware security modules across ECU architectures to satisfy UN R155 vehicle cybersecurity type-approval requirements. Tier-one suppliers in Germany contract for multi-year firmware update entitlements, displacing discrete component sales with service-based relationships. Automotive sustains the largest revenue base; healthcare is expanding most quickly.
- Industrial:EPA requirements for secure SCADA architectures drive PLC replacements lacking hardware security modules, with German automation vendors anchoring compliance roadmaps to anticipated EN harmonized standards.
- Healthcare:FDA cybersecurity guidance for connected medical devices creates unmet demand for hardware-rooted trust in patient monitoring systems.
- Consumer Electronics:Cost sensitivity favors integrated secure boot implementations over discrete security elements, though EU Cyber Resilience Act hardware-level obligations are shifting procurement specifications.
Automotive generates the steepest revenue concentration; healthcare shows the steepest expansion trajectory as FDA premarket guidance hardens.
Application:
Application segmentation reveals how cryptographic function specialization maps to attack surface exposure and data sensitivity.
- Payment Processing:PCI-DSS compliance and EMVCo specifications mandate certified secure elements for card-present transactions, with terminal manufacturers sourcing pre-certified components to avoid in-house security implementations. Payment processing retains dominant volume share; identity management is climbing the fastest.
- Secure Communication:Post-quantum cryptography migration is compressing replacement cycles for industrial fieldbus and automotive V2X protocols, forcing hardware refreshes ahead of traditional semiconductor obsolescence schedules.
- Access Control:Physical and logical access systems leverage secure microcontrollers for credential storage and mutual authentication protocols.
- Identity Management:Government e-ID programs and corporate credentialing systems drive demand for high-assurance secure elements with biometric binding capabilities.
Payment processing anchors current procurement volumes; identity management is accelerating as government digital ID programs proliferate.
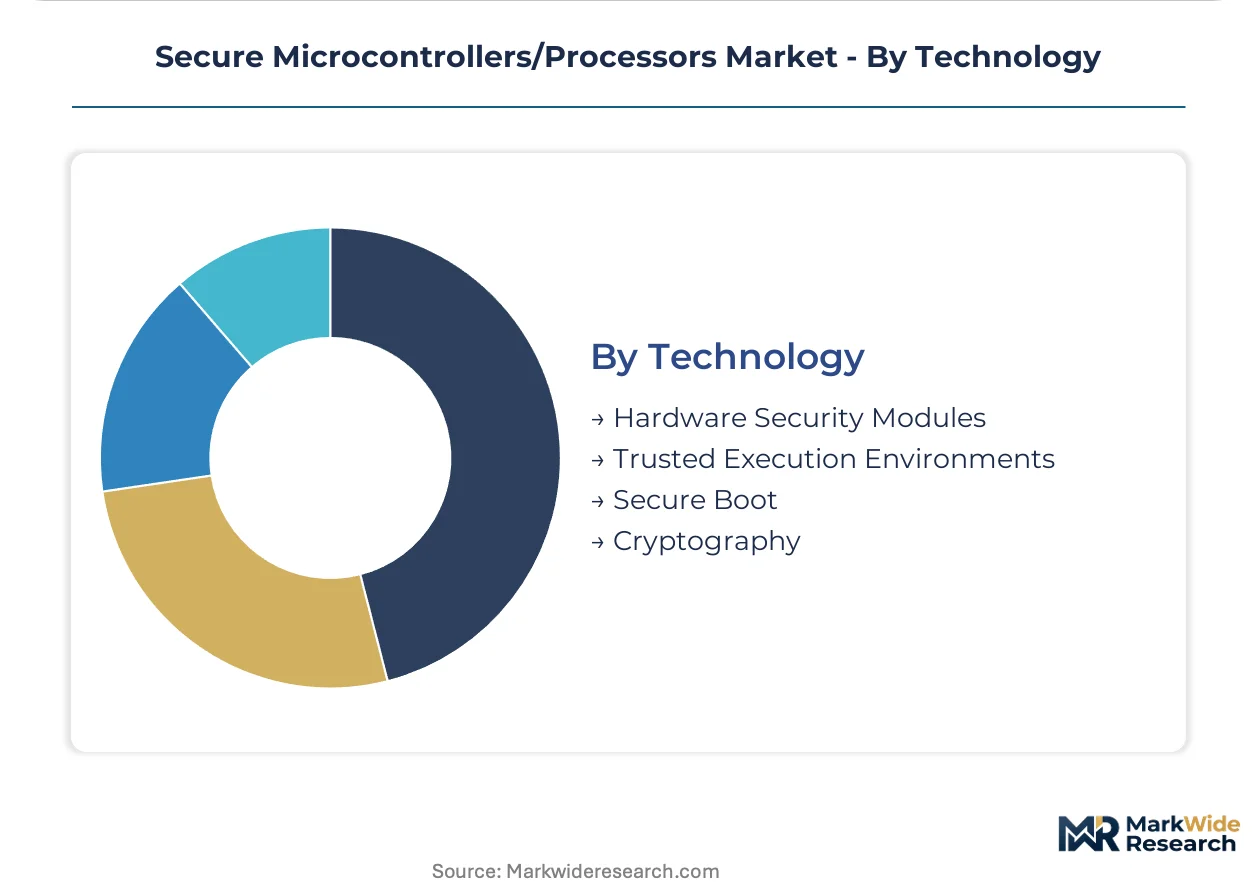
Technology:
Technology segmentation tracks the disaggregation of security functions from application processing as attack surfaces multiply.
- Trusted Execution Environments:Isolated processing domains within application processors enable secure inference for edge AI workloads without discrete security chips. EU AI Act risk-classification rules for high-risk systems mandate hardware-backed audit logging, positioning TEEs as compliance pathways for medical device and industrial automation vendors. Trusted execution environments represent the fastest-growing technology segment; hardware security modules retain the revenue concentration.
- Hardware Security Modules:Standalone cryptographic appliances and embedded modules provide the highest assurance levels for root key generation and certificate authority operations.
- Secure Boot:Cryptographically verified firmware initialization chains, increasingly implemented via physically unclonable functions, modularize into standard cell libraries at volume scale.
- Cryptography:Algorithm agility features enabling post-quantum migration dominate roadmap prioritization as NIST standardization timelines approach finalization.
Hardware security modules dominate high-assurance revenue; trusted execution environments are capturing share fastest as edge AI workloads proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting secure microcontroller production toward jurisdictions where certification costs align with end-market proximity. Vendors optimize between Common Criteria evaluation expenses in Europe and volume manufacturing scale in Asia.
Germany
UN R155 vehicle cybersecurity mandates and the EU Cyber Resilience Act drive automotive ECU hardware security module adoption. KBA type-approval requirements force tier-one suppliers to source pre-certified secure elements. Infineon Technologies and NXP Semiconductors anchor supply chains in Munich and Hamburg, displacing discrete component sales with multi-year firmware service agreements.
United States
FDA cybersecurity guidance for connected medical devices and EPA secure industrial control system rules create hardware-rooted trust procurement specifications. NIST post-quantum cryptography standardization timelines shape vendor roadmaps. Austin and Silicon Valley clusters concentrate fabless design houses specializing in side-channel analysis and fault injection resistant architectures.
China
MIIT domestic semiconductor self-sufficiency targets and GB standards for financial payment terminals accelerate local secure element production. Dual carbon goals intersect with industrial automation upgrades requiring hardware security modules. Yangtze River Delta foundries specialize in 40nm tamper-resistant memory processes insulated from mainstream cost curves.
Japan
METI semiconductor supply chain resilience initiatives and PMDA medical device cybersecurity guidance position hardware security modules as critical infrastructure components. JIS standards for industrial control systems mandate cryptographic accelerators in legacy PLC replacements. Tokyo and Osaka design centers concentrate physically unclonable function integration expertise.
South Korea
MFDS connected medical device regulations and KISA financial security standards drive secure microcontroller procurement for patient monitoring and payment terminals. Government digital ID programs expand identity management secure element volumes. Seoul Capital Area fabless specialists supply algorithm-agile architectures awaiting NIST lattice-based cryptography finalization.
Secure Microcontrollers/Processors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive trust anchor programs favoring direct vendor-OEM relationships over distribution channels. Market structure concentrates around three to five vertically integrated semiconductor conglomerates controlling certification pipelines and foundry access. Strategic archetypes include automotive-anchored secure element specialists, industrial automation focused hardware security module vendors, and edge AI trusted execution environment providers. Competitive moves center on long-term service agreement structures replacing discrete silicon sales, and post-quantum algorithm agility partnerships with standards bodies.
Within the automotive-anchored tier, Infineon Technologies and NXP Semiconductors represent the dominant archetype of European semiconductor conglomerates with captive certification expertise and multi-decade tier-one supplier relationships. STMicroelectronics occupies a position exemplifying integrated secure manufacturing capabilities that bundle provisioning with device lifecycle management. These three companies collectively anchor regional supply chain configurations across German automotive clusters, where OEMs outsource cybersecurity lifecycle management through contracted firmware update entitlements rather than component procurement.
| Leading Market Players |
|---|
| Infineon Technologies |
| NXP Semiconductors |
| STMicroelectronics |
| Microchip Technology |
| Renesas Electronics |
| Texas Instruments |
| Winbond Electronics |
| Analog Devices |
| Broadcom |
| Others |
Value Network & Pricing Analysis
EU Cyber Resilience Act hardware-level security obligations gate qualified supply to pre-certified microcontroller vendors, concentrating premium-tier pricing power with Infineon Technologies, NXP Semiconductors, and STMicroelectronics while excluding uncertified competitors from automotive and industrial procurement pools.
Pricing Analysis
Capacity additions in Germany and Taiwan are reshaping price floors for Common Criteria EAL4+ secure elements. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth and tamper-resistance grade. Pricing pressure stems from advanced node wafer costs at 40nm and above, which insulate secure microcontroller production from mainstream semiconductor cost curves. Automotive tier-one suppliers show lowest price sensitivity due to UN R155 mandate compliance requirements, while consumer electronics OEMs gravitate toward economy-tier integrated secure boot implementations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive clusters, displacing traditional distribution for trust anchor programs. Geographic supply concentrates in Germany, Taiwan, and the United States, with Munich and Hamburg anchoring Infineon and NXP captive certification expertise. Raw material dependencies include specialized 40nm wafer substrates, tamper-resistant memory IP cores, and side-channel analysis engineering talent concentrated in Austin and Silicon Valley design houses. Single-source vulnerability around Common Criteria evaluation facility capacity extends qualification timelines to 18-24 months, constraining supply elasticity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Secure Microcontrollers/Processors Market functions as a stable compounder, with regulatory mandate stacking across UN R155, EU Cyber Resilience Act, and FDA cybersecurity guidance generating replacement cycle visibility that insulates revenue from cyclical downturns.
For Market Incumbents: Deepen backward integration into tamper-resistant memory foundry processes to defend margin position against advanced node cost inflation. Secure captive evaluation facility capacity or partnership arrangements to compress 18-24 month Common Criteria bottlenecks. Prioritize post-quantum algorithm agility investments ahead of NIST lattice-based cryptography finalization to preempt competitor roadmap displacement. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in healthcare secure microcontrollers offers white-space entry for FDA pre-certified alternatives to automotive-anchored incumbents. Target patient monitoring system OEMs in the United States facing unmet hardware-rooted trust demand. Penetrate through algorithm-agile architectures that bridge post-quantum migration uncertainty without full EAL4+ certification investment. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap secure element specialists because Common Criteria certification scarcity creates durable moats that scale across automotive, medical device, and industrial automation verticals. Five-to-ten year viability hinges on post-quantum cryptography standardization timing rather than technology obsolescence. Watch NIST parameter set finalization as the inflection signal triggering replacement cycle acceleration and valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Algorithm Agility Investment | NIST lattice-based cryptography finalization will force hardware refreshes across automotive V2X and industrial fieldbus protocols. |
| Common Criteria Evaluation Facility Partnership | Captive access to EAL4+ certification pipelines compresses 18-24 month qualification timelines for secure element market entry. |
| Automotive Trust Anchor Service Agreement | Multi-year firmware update entitlements with German tier-one suppliers displace discrete silicon sales with recurring revenue streams. |
| Healthcare Secure Element Pre-Certification | FDA cybersecurity guidance for connected diagnostics creates procurement specifications favoring pre-certified hardware-rooted trust components. |
| Physically Unclonable Function IP Licensing | PUF-based secure boot modularization into standard cell libraries collapses boundaries between discrete secure elements and host microcontrollers. |
Research Methodology
Direct dialogue with semiconductor vendor product managers, automotive tier-one supplier procurement directors, medical device cybersecurity officers, Common Criteria evaluation facility engineers, and industrial automation compliance managers grounded qualitative insights. Secondary validation drew from SEC 10-K filings, NIST post-quantum cryptography standardization documents, FDA cybersecurity guidance publications, UN R155 type-approval records, and EU Cyber Resilience Act draft texts. Bottom-up and top-down triangulation cross-checked unit shipment estimates against OEM platform content assumptions and foundry capacity disclosures.
Bottom-up modeling built from secure microcontroller unit economics across product type, end user, application, and technology segments, with automotive ECU architectures, payment terminal deployments, and edge AI inference systems as primary volume anchors. Top-down validation referenced semiconductor industry revenue benchmarks and secure element certification pipeline throughput. CAGRs derived from replacement cycle compression analysis under post-quantum migration timelines and regulatory mandate stacking effects. Forecast inputs included NIST algorithm standardization schedules, KBA type-approval velocity, and EPA secure SCADA rule implementation pace.
The model assumes a particular technology adoption path; alternative pathways for lattice-based cryptography or hardware security module disaggregation into TEE-dominant architectures would alter the outlook. Forecasts reflect documented assumptions regarding certification facility capacity expansion, foundry node migration timing, and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Automotive Chip Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Europe Digital Signal Processor Market