
 G Fast Chipset Market | 2026-2036
G Fast Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
G Fast Chipset Market Intelligence
Demand from large incumbent telecom providers is bifurcating the market away from smaller, regional internet service providers. Broadcom Ltd. leverages its extensive portfolio and scale to serve these large accounts. Sckipio Technologies SI Ltd. specializes in G.fast distribution point unit (DPU) solutions for network operators. MaxLinear Inc. competes with integrated system-on-a-chip (SoC) offerings designed for customer premises equipment.
A G Fast chipset is a set of integrated circuits compliant with the ITU-T G.9701 standard, enabling gigabit speeds over short copper lines. These chipsets operate in high-frequency bands, such as the 212 MHz profile, to deliver fiber-like performance for last-mile connectivity. The residential application segment commands the largest share, driven by consumer appetite for faster internet for streaming and remote work. Telecom Providers, as the main end-user category, dictate requirements for both hardware and network protocol compatibility.
Compliance with telecommunications standards, such as FCC Part 15 in the United States and CE marking requirements in Europe, is mandatory for market access. In China, network equipment must align with specifications set by the MIIT, influencing chipset design and interoperability. Future investment decisions for network operators will hinge on the evolving cost-benefit analysis between G.fast upgrades and full fiber-to-the-home rollouts.
Market Dynamics
The central dynamic in the G Fast chipset market is the economic calculation by telecom providers, weighing the immediate benefits of upgrading existing copper infrastructure against the long-term capital expenditure of full fiber-to-the-home rollouts, a decision that directly shapes chipset demand.
Growth Catalysts
- Urban Infrastructure Economics:In dense urban centers like those in the United Kingdom and Germany, the high cost of civil works for new fiber installation makes leveraging existing last-mile copper with G.fast a highly cost-effective path to gigabit speeds.
- ITU-T G.9701 Standard Evolution:Continuous enhancements to the G.9701 standard, including the 212 MHz profile, expand performance capabilities over short copper loops, maintaining the technology's competitiveness against pure fiber alternatives for network operators.
- Government Broadband Mandates:National policies promoting universal high-speed internet access create a favorable regulatory environment for telecom providers to adopt G.fast as a rapid, scalable method to meet government targets without massive upfront investment.
Market Restraints
- Fiber-to-the-Home (FTTH) Price Erosion:The decreasing cost of deploying all-fiber networks presents a significant substitution threat, as FTTH offers superior long-term performance and scalability, making it the preferred choice for greenfield deployments and some brownfield upgrades.
- Physical Loop Length Limitations:G.fast performance degrades sharply on copper lines exceeding a few hundred meters, which confines its practical application to high-density areas where distribution point units (DPUs) can be placed close to customer premises.
- Crosstalk Interference Management:Signal interference within multi-pair copper bundles necessitates complex vectoring technology to cancel out noise. This requirement increases chipset complexity, power consumption, and overall system cost for network equipment manufacturers.
Strategic Opportunities
- Multi-Dwelling Unit (MDU) Penetration:Targeting apartment buildings and dense residential complexes in North American and European cities provides a scalable opportunity, as G.fast can deliver fiber-like speeds to each unit without the disruptive cost of in-building fiber rewiring.
- Hybrid 5G Fixed Wireless Access (FWA) Integration:Combining G.fast for in-building connectivity with 5G FWA for backhaul creates a potent hybrid solution, enabling gigabit service delivery in areas where fiber backhaul is either unavailable or economically unfeasible for operators.
- Emerging Market Urbanization:Densely populated cities in regions like Southeast Asia and Latin America represent a significant growth frontier, where G.fast can serve as a pragmatic bridge technology for providing advanced broadband services quickly.
Industry Challenges
- Multi-Vendor Interoperability:Achieving seamless plug-and-play interoperability between G.fast chipsets from different vendors within distribution point units and customer premises equipment remains a persistent integration hurdle for telecom providers deploying large-scale networks.
- DPU Power and Thermal Management:The high power consumption of G.fast chipsets operating at high frequencies creates significant thermal management challenges for designers of passively cooled, outdoor-hardened DPU enclosures, impacting equipment reliability and operational costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | G Fast Chipset Market |
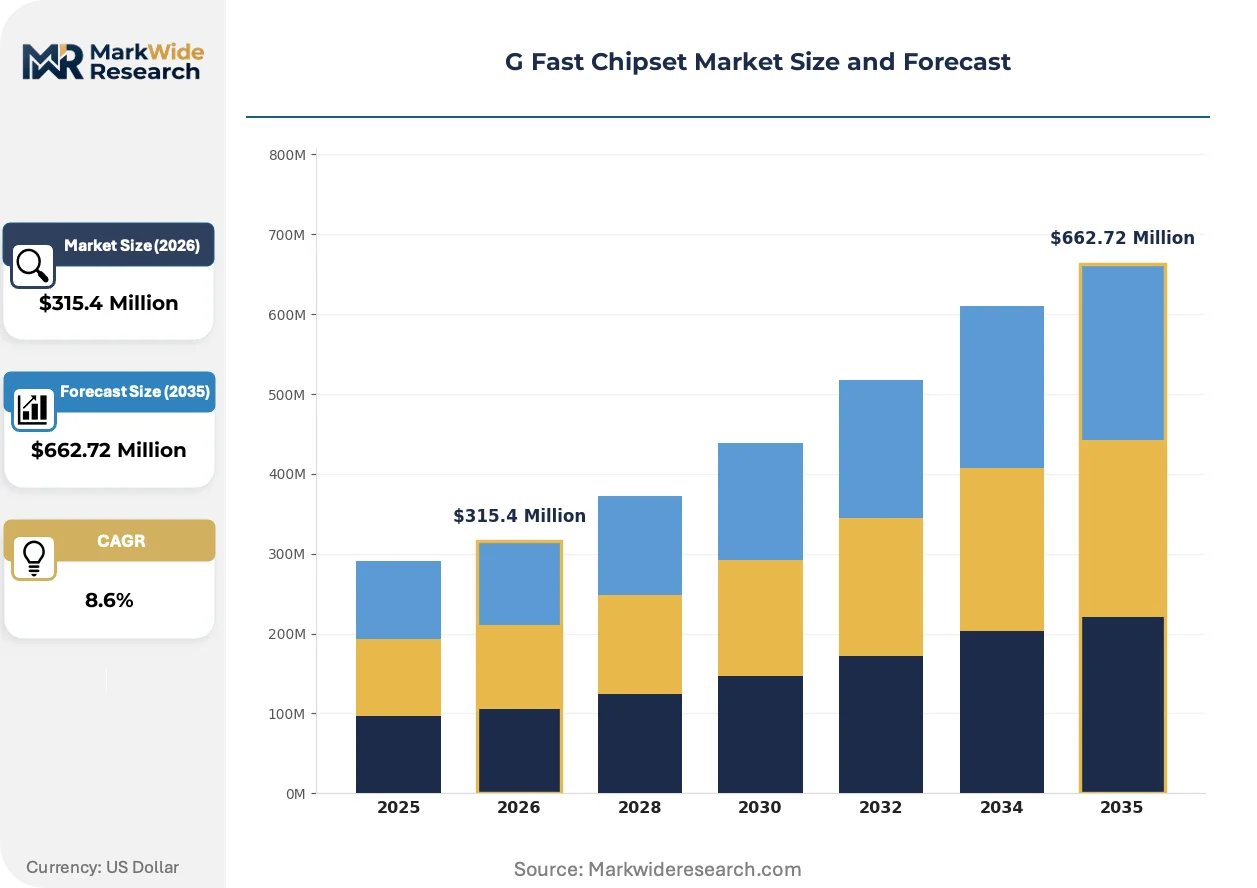
| Market Size in 2026 | $315.4 Million |
| Market Size in 2035 | $662.72 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential, Commercial, Industrial, Utilities Technology: Waveform, Frequency Modulation, Signal Processing, Network Protocol End User: Telecom Providers, Internet Service Providers, Equipment Manufacturers, Data Centers Product Type: Hardware, Firmware, Software, Accessory |
| Companies Covered | Qualcomm Technologies Inc., Broadcom Ltd., Marvell Technology Group Ltd., Sckipio Technologies SI Ltd., MediaTek Inc., Metanoia Communications Inc., Calix Inc., ADTRAN Inc., MaxLinear Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
G Fast Chipset Market Strategic Shifts & Innovations
The evolution of chipset design is driving a divergence in network upgrade strategies. Telecom operators are increasingly making technology choices based on the specific economic and physical constraints of their last-mile infrastructure, impacting vendor selection and product requirements.
System-on-a-Chip (SoC) designs integrate the G.fast modem, vectoring processors, and networking functions onto a single piece of silicon. Customer premises equipment (CPE) manufacturers are rapidly adopting these SoCs to reduce the cost and size of residential gateways. This high level of integration is bifurcating the market between specialized, high-performance DPU chipset suppliers and volume-oriented SoC vendors focused on the CPE segment.
Regulatory frameworks for electromagnetic compatibility directly influence chipset architecture. In the United States, FCC Part 15 rules define the limits for radiated emissions, which is a critical design constraint for chipsets using high-frequency profiles like 212 MHz. Chipset designers must therefore incorporate advanced signal processing and shielding techniques to ensure compliance, particularly for equipment destined for dense residential areas.
A shift toward dual-sourcing strategies by large incumbent telecom providers is altering purchasing behavior. This approach displaces the traditional single-vendor lock-in model, compelling chipset suppliers to focus more on standards compliance and proven interoperability to win business. This trend is most prominent in Europe, where operators like Deutsche Telekom manage extensive, multi-vendor networks and require component flexibility.
G Fast Chipset Market Segmentation
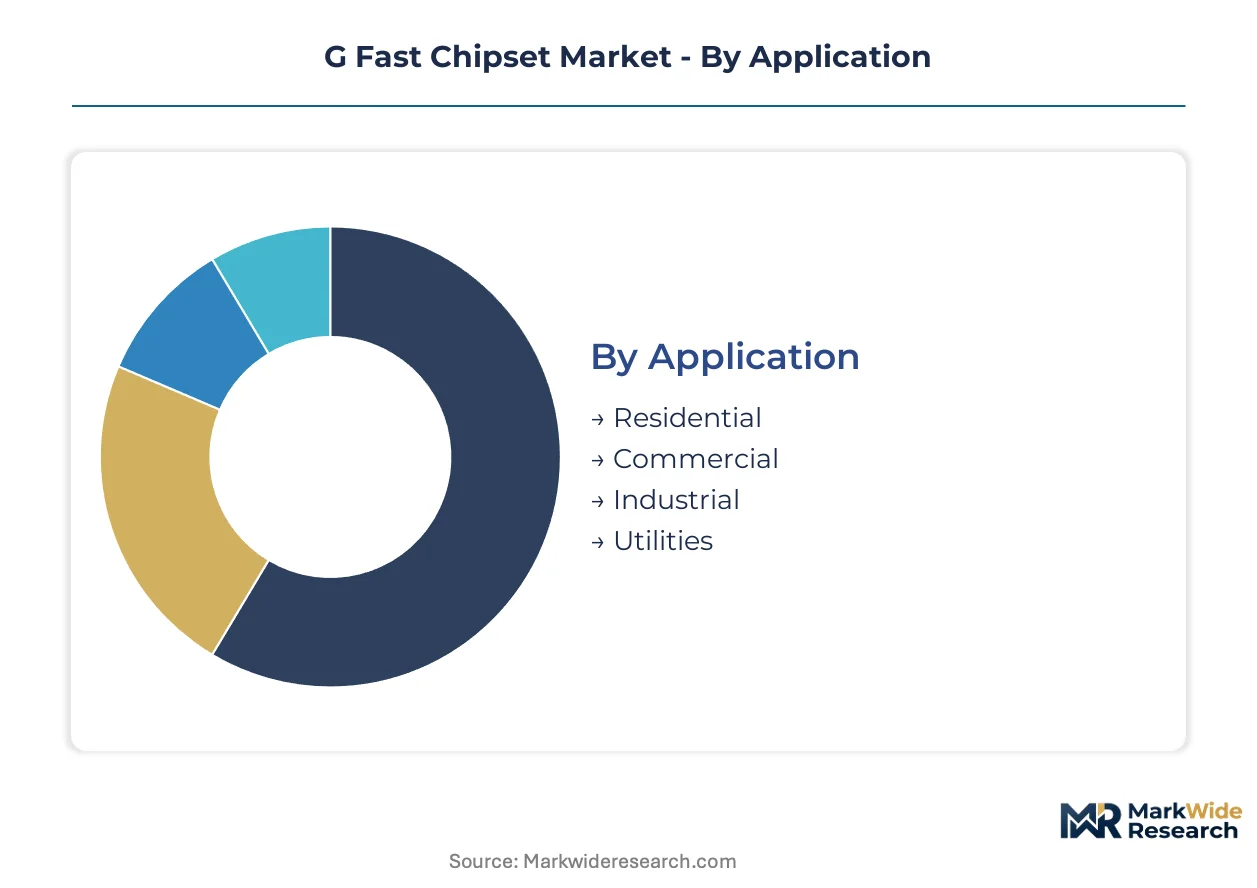
The G Fast chipset market segments reflect the diverse technical requirements and deployment scenarios for high-speed copper broadband. Understanding these distinctions helps network operators and equipment manufacturers tailor solutions to specific end-user needs and infrastructure constraints. Each segment presents unique opportunities and challenges in the evolving telecommunications landscape.
Application:
Regulatory frameworks often differentiate broadband service requirements by application type, influencing chipset design for power, emissions, and interoperability across various deployment environments.
- Residential:This segment encompasses G.fast chipsets deployed in customer premises equipment (CPE) for home internet access. Consumer demand for streaming and remote work drives performance requirements, particularly in dense urban centers in the United Kingdom and Germany.
- Commercial:G.fast solutions for small and medium-sized businesses (SMBs) and multi-tenant units (MTUs) fall under this category. These deployments prioritize reliability, security, and often require higher symmetrical bandwidth, particularly in North American cities.
- Industrial:Chipsets for industrial applications support specialized communication needs, often requiring robust environmental specifications for factories or remote sites.
- Utilities:This segment involves G.fast chipsets integrated into smart grid infrastructure or utility monitoring systems, demanding high reliability and extended operational lifespans.
Established volume favors Residential; emerging adoption favors Utilities.
Technology:
The technical complexity of G.fast chipsets varies significantly across different technology components, directly impacting their performance capabilities and integration challenges within network infrastructure.
- Signal Processing:This involves advanced digital signal processing (DSP) techniques, such as vectoring, crucial for mitigating crosstalk interference in multi-pair copper bundles. Complex algorithms ensure high data rates over short loop lengths.
- Network Protocol:Chipsets must support specific network protocols (e.g., ATM, Ethernet) for seamless integration with existing telecom provider infrastructure. Compatibility dictates deployment flexibility and operational efficiency.
- Waveform:Different modulation schemes and waveform shaping techniques optimize data transmission over copper lines, influencing spectral efficiency and noise immunity.
- Frequency Modulation:This pertains to how carrier frequencies are varied to encode data, impacting the effective bandwidth and reach of the G.fast signal.
Performance requirements drive demand for Signal Processing, while system compatibility drives Network Protocol.
End User:
Different end-user types exhibit distinct purchasing behaviors and technical requirements, influencing the features and scale of G.fast chipset solutions offered by vendors.
- Telecom Providers:Large incumbent telecom providers dictate the bulk of G.fast chipset demand, focusing on cost-effective upgrades to their last-mile copper infrastructure. Their scale requires robust, interoperable solutions for extensive network deployments.
- Equipment Manufacturers:These entities integrate G.fast chipsets into their distribution point units (DPUs) and customer premises equipment (CPE). They seek highly integrated, power-efficient system-on-a-chip (SoC) designs to reduce product cost and size.
- Internet Service Providers:Smaller, regional ISPs leverage G.fast to offer competitive broadband speeds in specific geographic niches, often prioritizing ease of deployment and lower initial investment.
- Data Centers:While less common, some data centers might use G.fast for short-reach, high-speed connectivity within campus environments or for specific backhaul scenarios.
Investment decisions by Telecom Providers shape market demand, while Equipment Manufacturers focus on product innovation.
Product Type:
The supply concentration for G.fast product types varies, with specialized manufacturers dominating the core hardware components and a broader ecosystem providing supporting software and accessories.
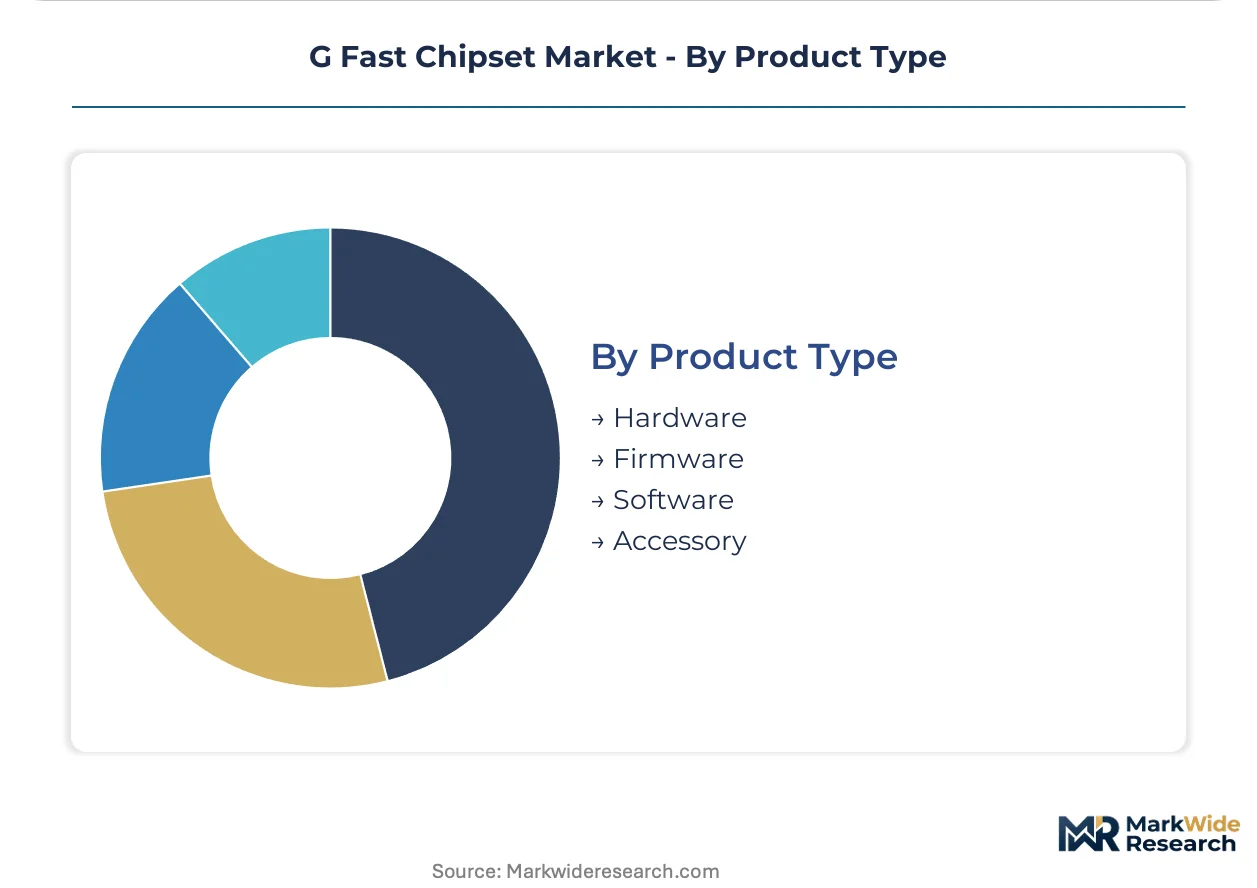
- Hardware:This segment includes the physical integrated circuits, such as System-on-a-Chip (SoC) designs, which perform the core G.fast modulation, demodulation, and vectoring functions. Broadcom Ltd. and MaxLinear Inc. are key suppliers in this area.
- Software:This covers the embedded operating systems, drivers, and management planes that enable G.fast chipsets to function within network devices. Software ensures protocol compatibility and network integration.
- Firmware:Firmware provides the low-level instructions for the hardware, enabling specific functions and ensuring stable operation. Updates often introduce new features or performance enhancements.
- Accessory:This segment includes peripheral components like power supplies, enclosures, and specialized cabling required for G.fast DPU deployments, particularly for outdoor-hardened units.
Core functionality resides in Hardware, with Software enabling system intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The G.fast chipset market sees significant technology and product flow from major semiconductor manufacturing nations to end-user markets. Chipsets developed in the United States and Taiwan are crucial for network upgrades across Europe and Asia. This global distribution supports varied infrastructure modernization initiatives.
United Kingdom
Demand for G.fast chipsets in the United Kingdom arises from telecom providers upgrading dense urban copper networks. Ofcom regulations encourage faster broadband deployment, making G.fast an attractive option for rapid service expansion. London and other major cities prioritize these upgrades to meet high consumer demand for streaming and remote work.
Germany
German telecom operators utilize G.fast technology to extend gigabit broadband services in densely populated areas. The Federal Network Agency (Bundesnetzagentur) supports infrastructure investments that leverage existing copper lines. Major metropolitan areas like Berlin and Munich are seeing significant G.fast deployments to bridge the fiber gap.
United States
In the United States, G.fast chipset adoption helps incumbent telecom providers deliver competitive speeds over short copper loops. FCC Part 15 rules define electromagnetic compatibility requirements for these high-frequency devices. Urban centers such as New York City and Chicago benefit from G.fast as a less disruptive alternative to full fiber builds.
China
China's G.fast chipset market is influenced by the Ministry of Industry and Information Technology (MIIT) specifications for network equipment interoperability. Telecom operators deploy G.fast in multi-dwelling units within large cities to quickly expand broadband access. Shanghai and Beijing represent key hubs for these dense urban deployments, leveraging existing infrastructure.
Japan
Japanese telecom companies employ G.fast solutions to enhance existing fiber-to-the-building deployments, particularly in multi-dwelling units. METI guidelines promote efficient broadband infrastructure development. Tokyo and Osaka's high-rise residential complexes are prime locations for G.fast DPU installations, providing fiber-like speeds.
G Fast Chipset Market Key Industry Players
Listed leaders compete with private specialists across product portfolio breadth and technological innovation. The G.fast chipset market exhibits a mix of large, publicly traded semiconductor companies and specialized private firms. The market structure is bifurcated between high-volume System-on-a-Chip (SoC) providers and niche distribution point unit (DPU) solution developers. Strategic partnerships and technology licensing are common competitive moves, alongside continuous portfolio diversification to meet evolving telecom provider demands.
On the scale-driven end, Broadcom Ltd. exemplifies companies offering extensive portfolios to large incumbent telecom providers. Sckipio Technologies SI Ltd. represents specialized firms focusing on G.fast distribution point unit (DPU) solutions for network operators. MaxLinear Inc. occupies a position among integrated system-on-a-chip (SoC) vendors, primarily targeting customer premises equipment. These entities anchor distinct segments of the G.fast chipset supply chain, from high-performance DPU components to cost-optimized CPE solutions. Their market presence reflects the varied technical requirements and economic models within the broadband upgrade landscape.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| Broadcom Ltd. |
| Marvell Technology Group Ltd. |
| Sckipio Technologies SI Ltd. |
| MediaTek Inc. |
| Metanoia Communications Inc. |
| Calix Inc. |
| ADTRAN Inc. |
| MaxLinear Inc. |
| Others |
Cost & Logistics Intelligence
Fiber-to-the-home (FTTH) technology's decreasing cost simultaneously reshapes the supply geography for last-mile connectivity solutions and intensifies pricing economics for G.fast chipsets. This dynamic forces chipset manufacturers to optimize production and integrate functions to maintain competitiveness.
Pricing Analysis
The technology-generation pricing gap between G.fast and full fiber solutions creates constant downward pressure on chipset costs. Per-unit transactional pricing models dominate for G.fast chipsets, reflecting the volume-driven nature of semiconductor sales. Price differentiation stems from performance tier, such as 212 MHz profile capabilities, and the level of integration into system-on-a-chip (SoC) designs. Pricing softness reflects the increasing cost-effectiveness of FTTH deployments. Smaller, regional internet service providers exhibit higher price sensitivity compared to large incumbent telecom providers seeking robust, interoperable solutions.
Supply Chain Analysis
Inventory management and lead-time observations indicate a critical reliance on established semiconductor manufacturing hubs for G.fast chipsets. Geographic supply concentrates predominantly in Taiwan, South Korea, and the United States, which host major foundries and design houses. The supply chain draws from essential raw materials like silicon wafers and specialized high-frequency components. Single-source vulnerability for advanced vectoring IP or specific manufacturing processes represents a structural risk. Distribution runs through direct sales channels to large equipment manufacturers and telecom providers, complemented by specialized distributors serving smaller market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The G.fast chipset market is at a platform-economics inflection point, driven by the need for seamless interoperability across diverse vendor ecosystems for last-mile copper upgrades.
For Market Incumbents:Secure long-term supply agreements with multiple chipset vendors to mitigate single-source risks and support dual-sourcing strategies. Invest in advanced vectoring algorithm development to extend G.fast performance and maintain a competitive edge against FTTH price erosion. Prioritize network protocol compatibility to ensure seamless integration with existing infrastructure. Form strategic partnerships with DPU and CPE manufacturers to co-develop optimized solutions for specific deployment scenarios.
For New Entrants and Emerging Players:Anchor in niche segments like multi-dwelling units (MDUs) and hybrid 5G fixed wireless access (FWA) integration. These areas offer scalable opportunities without directly confronting established players head-on. The most penetrable segment lies in emerging market urbanization, particularly in dense cities across Southeast Asia and Latin America. A focused go-to-market angle involves offering highly integrated, cost-optimized system-on-a-chip (SoC) solutions specifically for customer premises equipment.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with specialized DPU chipset developers, representing an attractive long-term viability play for G.fast as a bridge technology in urban density. Investors should target companies with proven expertise in high-performance signal processing and robust thermal management solutions. The signal to watch is increased government broadband mandates in emerging markets, indicating accelerated G.fast adoption. Acquisition targets should also demonstrate strong intellectual property portfolios in vectoring and high-frequency design.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop next-generation 212 MHz profile chipsets | Enhances data rates and reach over short copper loops for urban deployments. |
| Form strategic alliances with telecom operators | Secures preferred vendor status and aligns product roadmaps with network upgrade cycles. |
| Invest in integrated SoC designs for CPE | Reduces equipment cost and size, driving broader consumer adoption of G.fast. |
| Expand into emerging market urban centers | Captures new demand for rapid broadband deployment in densely populated regions. |
| Acquire specialized DPU technology firms | Strengthens portfolio in high-performance network-side G.fast solutions. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings. This approach included discussions with telecom network architects, chipset design engineers, DPU equipment manufacturers, and regulatory body representatives. Secondary validation drew from ITU-T standards documents, FCC filings, MIIT specifications, and industry association reports, providing a comprehensive market view. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy and consistency.
Sensitivity analysis framed the quantitative market projections across the analysis window. The analytical framework modeled market segmentation across application type, technology component, end-user category, product type, and regional deployment density. Compound annual growth rates were derived from historical data and projected market drivers, including G.9701 standard adoption rates and fiber-to-the-home rollout schedules. This comprehensive approach allowed for robust forecasting of market evolution.
Decision-makers should treat outputs as directional under current base assumptions; material deviation in key market drivers would warrant model refresh. Forecasts reflect assumptions regarding technological evolution and regulatory stability within the telecommunications sector. Rapid FTTH cost reduction or unforeseen regulatory changes impacting copper infrastructure represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Global Microprocessor and GPU Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Microserver Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Integrated Graphics Chipset Market