
 Tablet Application Processor Market | 2026-2036
Tablet Application Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Application Processor Market Outlook
Multi-source silicon procurement is repositioning supply chain risk management across the tablet application processor industry. Qualcomm Technologies leverages its Snapdragon portfolio to anchor premium-tier design wins with major OEMs. MediaTek competes aggressively on cost-optimized ARM-based SKUs for mid-range education tablets. Apple sustains captive demand through in-house A-series and M-series silicon that never reaches external markets.
A tablet application processor is a system-on-chip (SoC) integrating CPU cores, GPU, memory controller, and I/O interfaces onto a single die, typically fabricated at 5nm to 3nm process nodes with thermal design power below 15 watts for fanless tablet enclosures. The chip's primary purpose is to execute operating systems, multimedia codecs, and touch-responsive interfaces while maximizing battery endurance in thin-form-factor devices. ARM-based product types dominate unit shipments due to their power efficiency advantage in mobile workloads, while x86-based variants occupy premium productivity segments where Windows compatibility matters. Mobile SoC technology leads R&D investment as vendors integrate AI accelerators and 5G modems into unified die designs.
FCC equipment authorization in the United States, CE marking under the EU's Radio Equipment Directive, and China's MIIT network access licensing collectively gate market entry for tablet application processors by mandating electromagnetic compatibility, SAR limits, and cybersecurity baseline assessments. REACH substance restrictions in Europe and RoHS hazardous material limits in multiple jurisdictions constrain substrate materials and solder compositions used in chip packaging. Stakeholders must monitor how emerging AI hardware regulations in the European Union and export control classifications on advanced process nodes reshape which architectures qualify for which geographic markets.
Market Dynamics
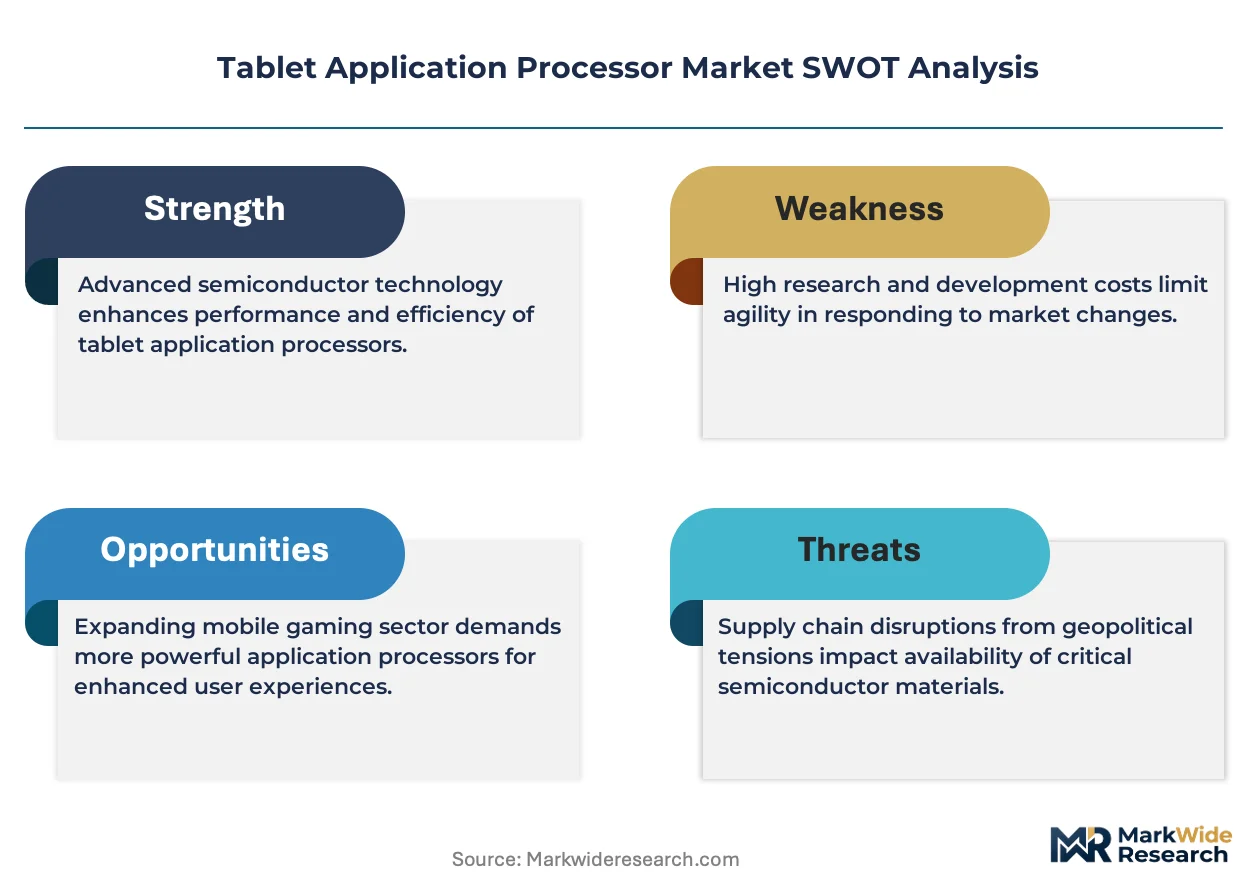
Enterprise procurement teams in education are consolidating purchases around ARM-based chipsets, forcing silicon vendors to reconfigure product roadmaps toward fanless, all-day-battery designs rather than peak performance benchmarks.
Growth Catalysts
- EU AI Act hardware thresholds:European-bound tablets now require dedicated neural processing units, pulling NPU-integrated SoCs into mid-range education SKUs.
- Shenzhen cluster concentration:Final assembly and testing capacity in Guangdong province compresses time-to-market for new processor designs by 30-40%.
- 5G modem integration:Unified die designs combining application processors with cellular basebands reduce bill-of-materials complexity for always-connected tablets.
Market Restraints
- Advanced node access constraints:Sub-5nm fabrication depends on a concentrated equipment supplier base subject to multilateral export controls.
- Thermal envelope limitations:Fanless tablet enclosures cap thermal design power below 15 watts, constraining peak CPU and GPU performance scaling.
- REACH substance restrictions:European regulations on substrate materials and solder compositions limit packaging options and raise compliance costs.
Strategic Opportunities
- India education procurement:State-level tablet distribution programs under the Digital India initiative create volume demand for cost-optimized ARM SoCs.
- AI accelerator convergence:On-device large language model inference is expanding into student assessment and personalized tutoring applications.
- Refurbishment channel expansion:Secondary markets for enterprise and education fleet tablets extend processor lifecycle value through certified pre-owned programs.
Industry Challenges
- MIIT network access licensing:China's cybersecurity baseline assessments add 4-6 months to product qualification timelines for new SoC variants.
- Multi-source silicon validation:OEMs must qualify identical processor SKUs across TSMC, Samsung Foundry, and SMIC process nodes without performance deviation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Application Processor Market |
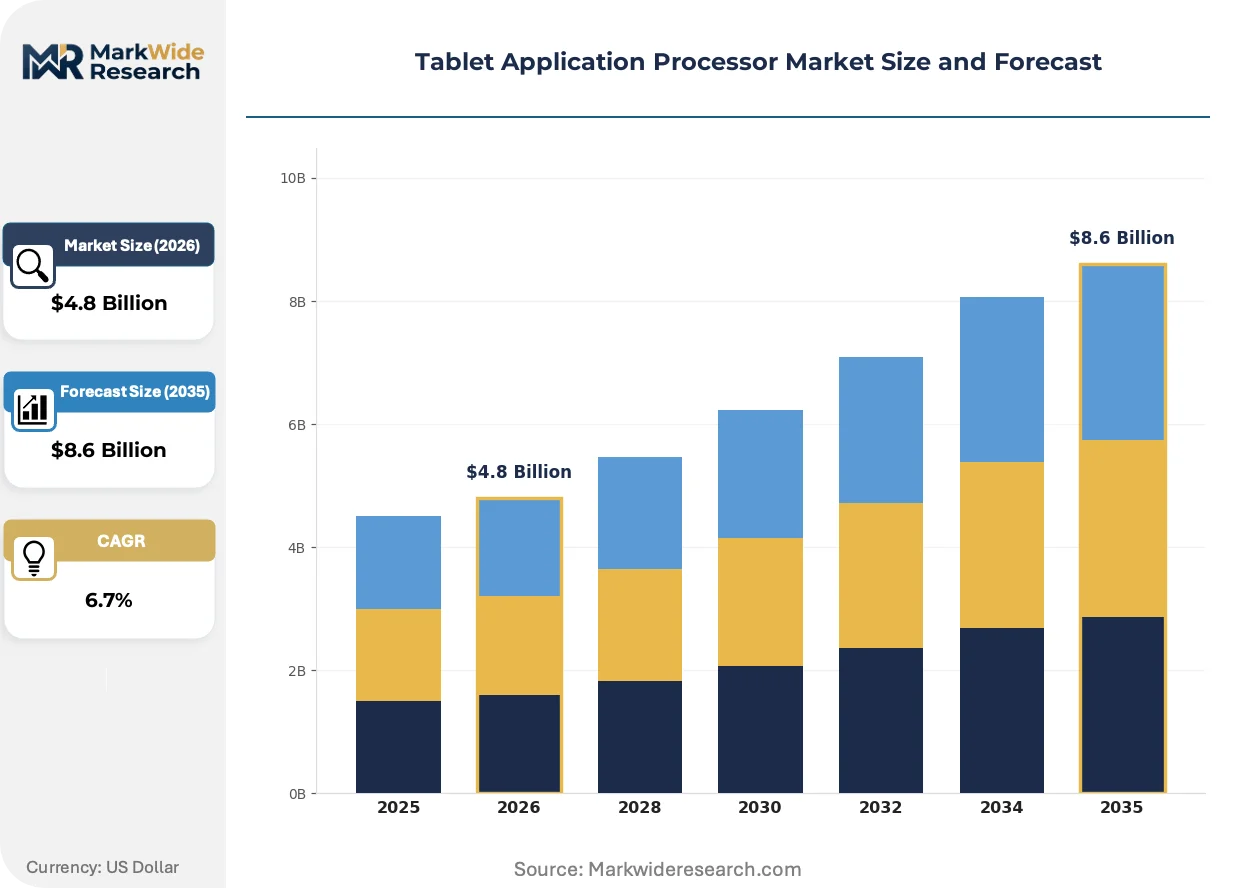
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ARM-based, x86-based, Low Power, High Performance Technology: Mobile SoC, Application Specific, Multi-core, System on Chip End User: Education, Entertainment, Healthcare, Business Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Qualcomm Technologies, MediaTek, Apple, Samsung Electronics, NVIDIA Corporation, NXP Semiconductors, Texas Instruments, Rockchip Electronics, Advanced Micro Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Application Processor Market Strategic Shifts
Silicon vendors are racing to integrate discrete-function accelerators into unified die architectures, compressing what were once separate chips for AI, graphics, and connectivity into single SoC footprints.
Chiplet-based modular designs are expanding into tablet application processors, enabling vendors to mix CPU, GPU, and NPU tiles from different process nodes on a single package substrate. Education OEMs in North America are adopting these designs for mid-range student devices where cost flexibility matters more than peak performance. This modularity is expanding into supply chain resilience strategies by allowing rapid tile substitution when specific foundry capacity tightens.
CE marking under the EU's Radio Equipment Directive now mandates pre-market cybersecurity assessments for tablets with integrated AI accelerators, forcing SoC vendors to embed hardware root-of-trust features at the die level. German and French OEMs are prioritizing processors with certified secure enclaves to accelerate their own compliance timelines. The directive is expanding into procurement specifications for European education ministries, which now require documented hardware security certifications.
School district IT departments are consolidating device purchases through centralized state procurement frameworks, displacing individual school-level buying decisions. Texas and California education agencies now negotiate master service agreements directly with tablet OEMs, specifying ARM-based processor families and minimum five-year support commitments. This concentration is expanding into pricing pressure on mid-range SoC vendors, who must commit to extended production lifecycles to qualify for these contracts.
Tablet Application Processor Market Segmentation
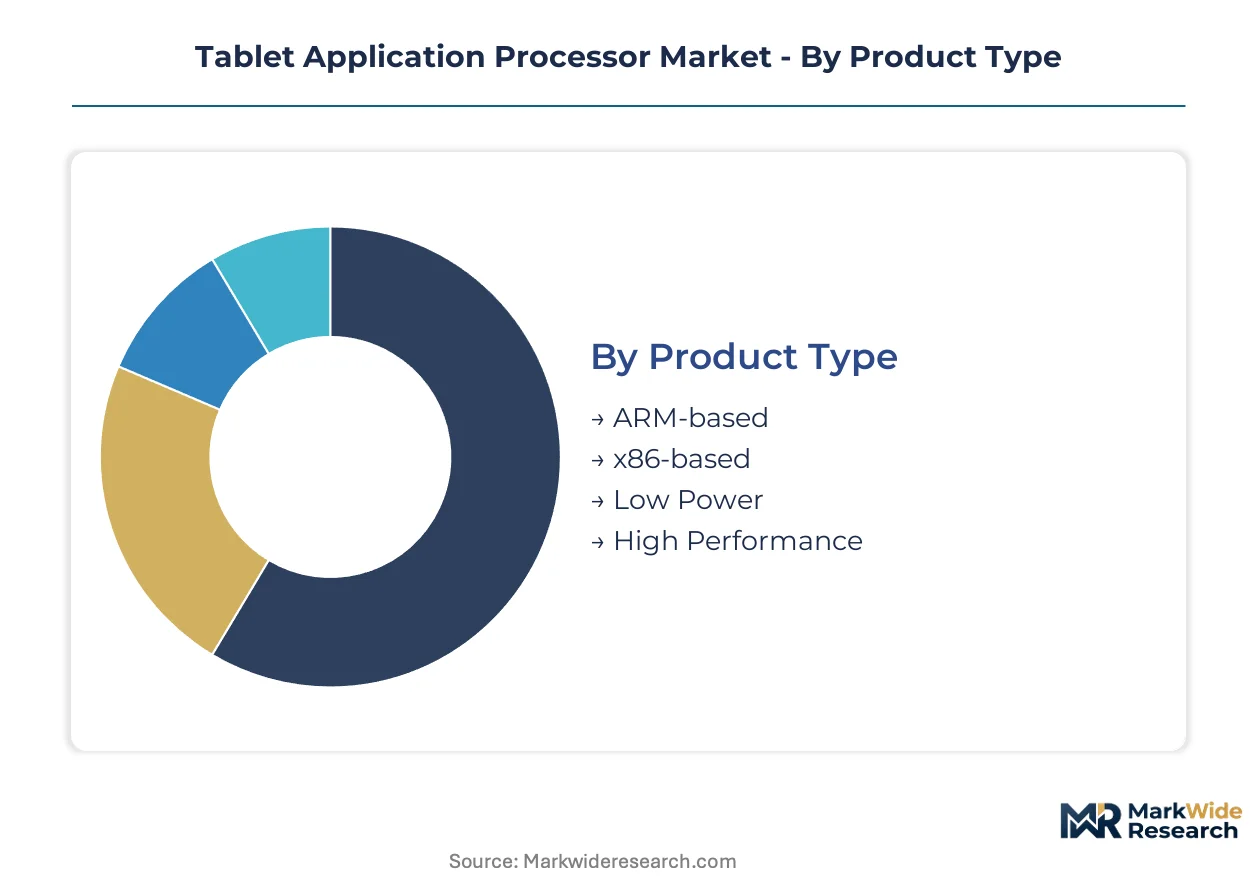
Tablet application processor procurement hinges on matching thermal envelopes, software ecosystems, and regulatory compliance to specific use cases. Segmentation reveals how education ministries, healthcare systems, and enterprise IT departments impose divergent qualification requirements on silicon vendors.
Product Type:
CE marking under the EU's Radio Equipment Directive and FCC equipment authorization in the United States impose distinct electromagnetic compatibility and SAR testing burdens on each processor architecture. ARM-based designs face streamlined certification paths for education tablets, while x86-based variants encounter additional Windows compatibility validation for enterprise deployments.
- ARM-based:These SoCs integrate CPU cores, GPU, and memory controllers on dies fabricated at 5nm to 3nm nodes, with thermal design power optimized below 15 watts for fanless enclosures. Texas and California education agencies specify ARM architectures in master service agreements for student devices, driven by all-day battery requirements and cost-optimized unit economics.
- x86-based:Intel and AMD processor designs maintain instruction set compatibility with legacy Windows applications, enabling productivity-oriented tablets for business segments. German and French OEMs prioritize these SKUs for enterprise fleet deployments where software compatibility outweighs power efficiency considerations.
- Low Power:Sub-10-watt TDP designs target healthcare monitoring tablets requiring extended field deployment without charging infrastructure.
- High Performance:Premium-tier silicon with discrete AI accelerators serves creative professional segments in Japan and South Korea.
ARM-based processors sit at the top of the volume ranking, with High Performance variants climbing the fastest.
Technology:
Process node selection and integration complexity drive margin stratification across technology tiers, with unified die designs commanding premium positioning over discrete-component alternatives.
- Mobile SoC:Unified die architectures combining application processors with 5G modems and AI accelerators reduce bill-of-materials complexity for always-connected tablets. Shenzhen's electronics cluster in Guangdong province compresses time-to-market for these designs by 30-40% through concentrated final assembly capacity.
- System on Chip:Complete integration of CPU, GPU, NPU, and I/O interfaces enables the thinnest tablet form factors for entertainment and education markets. India's Digital India state-level tablet distribution programs create volume demand for these cost-optimized designs.
- Multi-core:Heterogeneous CPU cluster configurations balance performance and efficiency cores for mixed-workload tablets.
- Application Specific:Custom silicon variants address narrow healthcare imaging or industrial control use cases with dedicated accelerator blocks.
Mobile SoC technology captures the dominant revenue share, with System on Chip designs expanding most quickly in education procurement.
End User:
Institutional procurement frameworks and compliance mandates reshape processor specifications across vertical markets, with education and healthcare imposing the most stringent qualification timelines.
- Education:State-level centralized purchasing in the United States and national programs in India specify ARM-based chipsets with minimum five-year support commitments. FCC equipment authorization and BIS certification requirements in India add 4-6 months to product qualification for new SoC variants entering these channels.
- Healthcare:Patient data security requirements under HIPAA in the United States and GDPR in Europe mandate hardware root-of-trust features at the die level. German OEMs prioritize processors with certified secure enclaves to accelerate compliance timelines for clinical tablet deployments.
- Entertainment:Consumer retail channels emphasize GPU performance for streaming and gaming workloads.
- Business:Enterprise IT departments require Windows compatibility and extended security patch guarantees.
Education represents the largest addressable volume, with Healthcare gaining share fastest on security certification requirements.
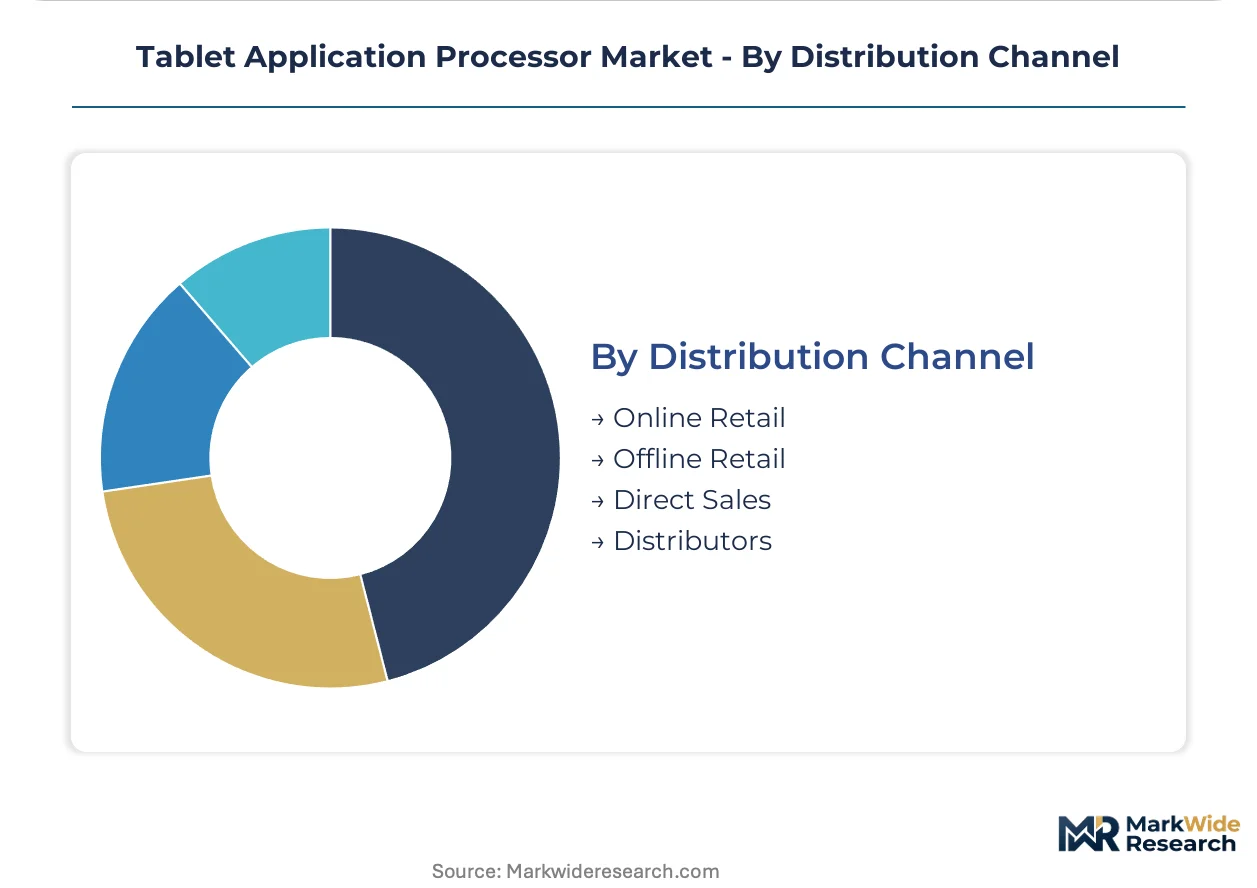
Distribution Channel:
Channel selection determines qualification burden intensity, with direct sales to institutional buyers imposing documentation requirements that consumer retail channels bypass.
- Direct Sales:OEM relationships with Texas and California education agencies bypass distributor margins but require documented hardware security certifications and extended production lifecycle commitments. These contracts specify ARM-based processor families with MIIT network access licensing for China-manufactured components.
- Distributors:Value-added resellers aggregate demand from smaller school districts and healthcare clinics, consolidating certification documentation across multiple OEM portfolios.
- Online Retail:Consumer-direct channels emphasize price transparency and specification comparison for entertainment and prosumer segments.
- Offline Retail:Big-box electronics chains maintain inventory for immediate-need business purchases with shorter procurement cycles.
Direct Sales commands the highest revenue per unit, with Distributors showing the steepest expansion trajectory in fragmented institutional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics cluster anchors global tablet application processor assembly and testing capacity, compressing time-to-market for new designs by 30-40%. Regulatory fragmentation across major demand centers is redirecting silicon vendor qualification priorities toward region-specific compliance mandates.
United States
Texas and California education agencies negotiate master service agreements specifying ARM-based processor families with minimum five-year support commitments. FCC equipment authorization mandates electromagnetic compatibility and SAR limit testing for all tablet SoCs entering the market. Austin and San Jose host design centers where vendors validate chipsets against institutional procurement frameworks.
China
Guangdong province concentrates final assembly capacity for education and enterprise tablets bound for domestic and export markets. MIIT network access licensing adds 4-6 months to product qualification timelines for new SoC variants. Shenzhen's integrated electronics ecosystem spans wafer-level packaging through finished device logistics.
Germany
CE marking under the EU's Radio Equipment Directive mandates pre-market cybersecurity assessments for tablets with integrated AI accelerators. German OEMs prioritize processors with certified secure enclaves to accelerate compliance timelines for enterprise fleet deployments. Bavaria's industrial corridor hosts validation labs testing hardware root-of-trust features.
India
State-level tablet distribution programs under the Digital India initiative generate volume demand for cost-optimized ARM SoCs. BIS certification requirements extend product qualification timelines for new processor variants entering education procurement channels. Karnataka and Telangana assemble devices for national distribution under centralized government tenders.
South Korea
Premium-tier creative professional segments demand high-performance silicon with discrete AI accelerators for content creation workloads. MFDS and national cybersecurity standards govern data processing hardware used in enterprise and healthcare applications. Seoul's semiconductor design cluster specializes in advanced node validation for export-bound tablet processors.
Tablet Application Processor Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized vertical integration and modular chiplet architectures. The vendor base stratifies across captive silicon designers, merchant SoC suppliers, and fabless IP licensors. Three archetypes dominate: vertically integrated device makers withholding silicon from external markets; merchant vendors competing on cost-optimized education SKUs; and specialty suppliers targeting narrow healthcare or industrial use cases. Capacity expansion and strategic IP licensing represent the dominant competitive vectors.
Within the merchant semiconductor tier, Qualcomm Technologies and MediaTek exemplify divergent positioning strategies—one anchoring premium-tier design wins through cellular modem integration, the other capturing mid-range education volume through aggressive cost engineering. Apple occupies a unique captive position where in-house A-series and M-series silicon never reaches external markets, insulating its device ecosystem from merchant competition. Samsung Electronics represents the hybrid archetype, supplying both captive tablet lines and external OEMs through foundry and design services.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| MediaTek |
| Apple |
| Samsung Electronics |
| NVIDIA Corporation |
| NXP Semiconductors |
| Texas Instruments |
| Rockchip Electronics |
| Advanced Micro Devices |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed foundry investments in East Asia are reshaping both supply availability and pricing discipline across the tablet application processor industry. These state-financed capacity expansions in Taiwan and South Korea compress wafer costs for education-tier ARM SoCs while tightening margin capture for merchant silicon vendors serving premium segments.
Pricing Analysis
Advanced node wafer costs pass through directly to tablet OEM bill-of-materials, with sub-5nm fabrication premiums widening spreads between mid-range education SKUs and high-performance creative-tier silicon. Price differentiation rests on NPU certification grade under EU AI Act thresholds and volume scale commitments from Texas and California education agencies. Cost compression in mid-range ARM SoCs is intensifying because MediaTek and Rockchip Electronics compete aggressively for India's Digital India tenders. Education procurement teams exhibit highest price sensitivity, while healthcare system buyers prioritize hardware root-of-trust features over unit economics.
Supply Chain Analysis
India's phased manufacturing program and local-content rules for government tablet tenders are redirecting final assembly from Guangdong toward Karnataka and Telangana. Geographic supply concentration centers on Taiwan for leading-edge wafer fabrication, South Korea for memory integration, and China for wafer-level packaging and finished device logistics. Raw material dependencies include EUV photoresist from Japan, high-purity silicon wafers from Germany, and rare-earth substrates from China's processing facilities. Single-source vulnerability in extreme ultraviolet lithography equipment constrains sub-3nm capacity expansion. Distribution runs through Shenzhen's integrated electronics cluster for export-bound education tablets, with direct OEM relationships bypassing distributor margins for state-level US procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tablet application processor market functions as a stable compounder, with education sector refresh cycles and AI hardware mandates in Europe providing predictable demand visibility across the analysis window.
For Market Incumbents: Hedge against foundry concentration risk by qualifying identical processor SKUs across TSMC, Samsung Foundry, and SMIC process nodes without performance deviation. Anchor premium-tier positioning through 5G modem integration that emerging fabless entrants cannot replicate, while extending production lifecycle commitments to capture Texas and California education agency master service agreements. For New Entrants and Emerging Players: Enter via India's state-level tablet distribution programs under the Digital India initiative, where cost-optimized ARM SoCs face limited incumbent lock-in. Target healthcare monitoring tablets requiring sub-10-watt TDP designs and extended field deployment without charging infrastructure. Pursue chiplet-based modular architectures that enable rapid tile substitution when specific foundry capacity tightens. For Investors and Strategic Acquirers: Valuations sit cheapest among specialty suppliers targeting narrow healthcare imaging or industrial control use cases with dedicated accelerator blocks. Long-term viability over a multi-year horizon hinges on securing hardware security certifications that European education ministries now require. Watch for inflection signals in MIIT network access licensing timelines, as acceleration or delays in China's cybersecurity baseline assessments reshape qualification burdens for new SoC variants.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet-Based Modular Architecture Adoption | Enables rapid tile substitution when TSMC or Samsung Foundry capacity tightens for education tablets. |
| Hardware Root-of-Trust Certification Investment | Accelerates CE marking timelines for German and French OEMs under EU Radio Equipment Directive mandates. |
| Multi-Source Silicon Qualification Program | Reduces single-foundry dependency risks for OEMs supplying Texas and California education agencies. |
| NPU Integration for EU AI Act Compliance | Pulls neural processing units into mid-range education SKUs bound for European procurement channels. |
| Refurbishment Channel Partnership Development | Extends processor lifecycle value through certified pre-owned programs for enterprise fleet tablets. |
Study Parameters
Multiple input streams — semiconductor design engineering leads, education procurement officers at Texas and California agencies, foundry capacity planners, and regulatory compliance specialists — were reconciled against secondary validation from SEC 10-K filings, MIIT network access licensing records, EU CE marking databases, and hyperscaler capex disclosures. Bottom-up unit shipment estimates by processor architecture were cross-checked against top-down wafer allocation data from Taiwan and South Korea.
Historical shipment trajectories were cross-referenced against panel input from OEM product managers and distributor channel heads to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include ARM versus x86 architecture, education versus healthcare versus enterprise end-use, and direct sales versus distributor versus retail channel structure. CAGRs were derived from slope analysis of normalized shipment curves, with specific adjustment for EU AI Act hardware threshold implementation timelines and India Digital India program procurement schedules.
Inputs from foundry utilization reports and education ministry tender documents were available through the study window; gaps in real-time inventory positioning at Shenzhen logistics hubs introduce uncertainty bands around near-term shipment estimates. Forecasts reflect documented assumptions regarding process node yield maturation and regulatory certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market