
 Nano Chip Market | 2026-2036
Nano Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Chip Market Foresight
EU Green Deal carbon-border adjustments and automotive OEM net-zero procurement mandates are repositioning nano chip demand toward energy-efficient fabrication. TSMC dominates leading-edge silicon-based production through captive EUV lithography scale. Samsung Electronics anchors memory chip supply through vertical control over DRAM and NAND flash capacity. Intel Corporation competes in processor chips by extending IDD manufacturing investments across Arizona and Oregon facilities.
A nano chip is a semiconductor device with feature sizes below 100 nanometers, typically fabricated using extreme ultraviolet lithography on 300mm silicon wafers with atomic-layer deposition for gate oxides; its primary purpose is to deliver maximum computational density per watt for data processing, storage, and signal conversion. Processor chips command the highest margin pools as AI inference workloads expand, while carbon nanotube technology represents the fastest-growing segment as researchers overcome contact resistance barriers for post-silicon logic. Memory chips remain the volume anchor, with logic chips capturing premium pricing in automotive safety systems.
The EPA enforces TSCA reporting for nanoscale materials in U.S. fabrication facilities, while REACH restricts hazardous substances in European semiconductor chemicals, and METI's JIS standards govern Japanese nano chip reliability for automotive qualification. These frameworks elevate compliance costs for new entrants but create durable certification barriers for incumbents with established testing protocols. Stakeholders must monitor which technology node—silicon-based or carbon nanotube—secures dominant automotive design wins as electrification redefines chip thermal specifications.
Market Dynamics
Automotive electrification is compressing chip thermal specifications while expanding computational load requirements, forcing foundries to recalibrate process nodes for extended temperature ranges without sacrificing logic density.
Growth Catalysts
- EU Green Deal carbon-border adjustments:German automotive OEMs now mandate net-zero procurement for logic chips, redirecting fabrication capacity toward energy-efficient process nodes.
- AI inference workload expansion:Data center operators in Taiwan and South Korea are scaling orders for advanced processors, pulling 3nm and 2nm capacity allocation from consumer electronics.
- Carbon nanotube contact resistance breakthroughs:Research institutions in Japan and the Netherlands are achieving sub-10nm channel control, opening post-silicon logic pathways for 2030s device architectures.
Market Restraints
- EUV lithography equipment concentration:ASML's monopoly on high-NA systems creates single-source dependency for sub-3nm production ramps.
- Fluorinated gas supply volatility:Etching chemistries face input cost spikes under F-Gas Regulation phase-down schedules, compressing margin at mature nodes.
- Silicon substrate diameter lock-in:450mm wafer transition failures strand the industry on 300mm tooling, capping die-per-wafer economics.
Strategic Opportunities
- Indian PLI scheme for semiconductor manufacturing:Gujarat and Karnataka states offer 50% capex reimbursement for fabs serving automotive and defense logic demand.
- Chiplets and 2.5D/3D integration:Heterogeneous packaging is enabling fabless designers to mix process nodes within single devices, bypassing monolithic scaling costs.
- METI energy-efficiency mandates:Japanese automotive qualification standards reward chips with sub-5W thermal design power, creating premium pricing tiers for compliant suppliers.
Industry Challenges
- EUV photoresist chemist scarcity:Only three universities worldwide produce doctoral candidates qualified for 13.5nm wavelength materials engineering.
- REACH substance authorization timelines:European chemical restrictions delay new dielectric formulations by 18-24 months against Asian competitor cadences.
- Automotive functional safety certification:ISO 26262 ASIL-D qualification requires 2-3 year validation cycles that misalign with consumer chip development velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Chip Market |
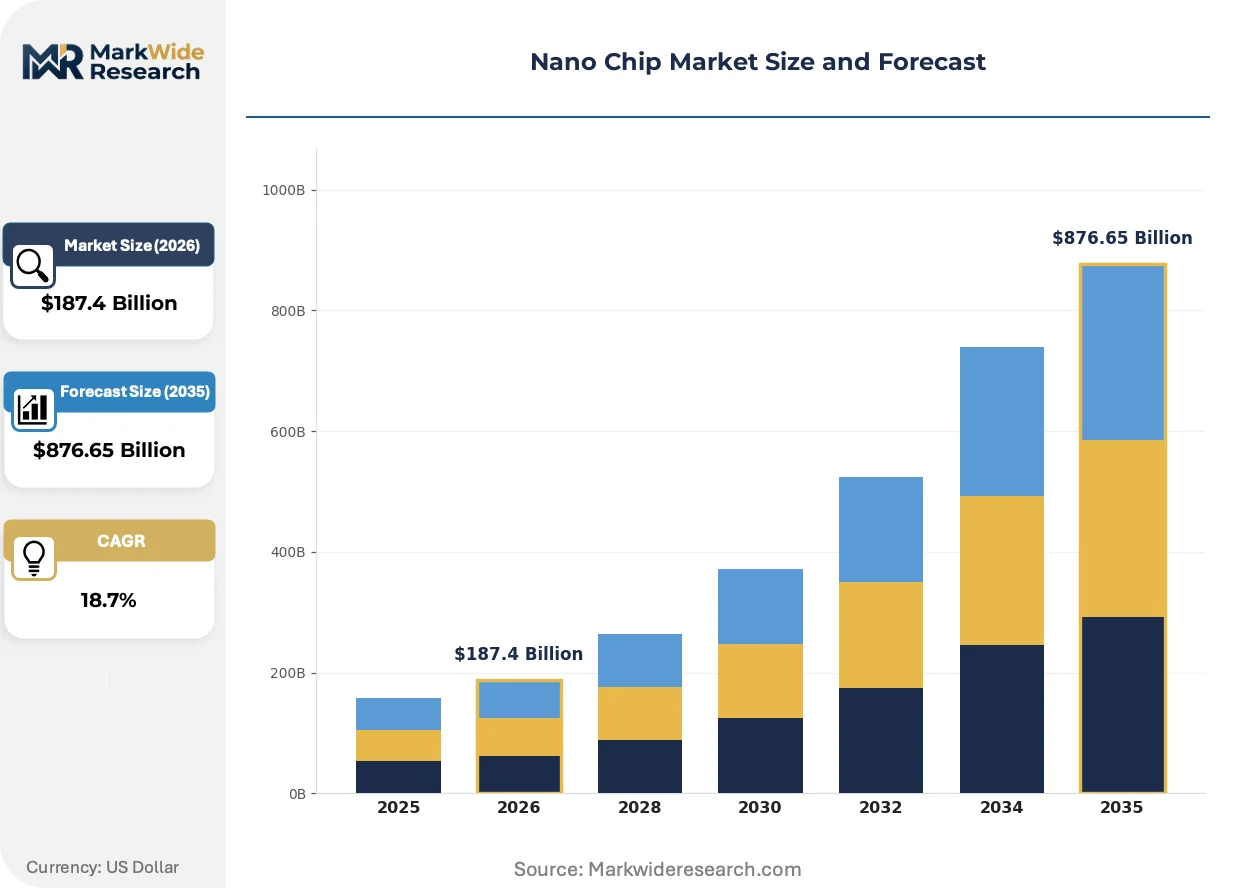
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $876.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Chips, Processor Chips, Logic Chips, Analog Chips Application: Consumer Electronics, Telecommunications, Automotive Electronics, Aerospace Electronics Technology: Silicon-based, Carbon Nanotubes, Quantum Dots, Graphene End User: Manufacturers, R&D Institutions, Government Agencies, Academic Institutions |
| Companies Covered | NVIDIA Corporation, Qualcomm Incorporated, Taiwan Semiconductor Manufacturing Company (TSMC), Broadcom Inc., SK Hynix, Samsung Electronics, Advanced Micro Devices (AMD), Micron Technology, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Chip Market Shifts & Advancements
Process-architecture-packaging co-optimization is displacing transistor-scaling-only roadmaps, while regulatory carbon accounting and buyer procurement consolidation are rewriting competitive differentiation criteria.
Gate-all-around transistor architectures are expanding into high-volume production as Samsung and TSMC transition 3nm classes from FinFET structures. Automotive powertrain controllers and smartphone application processors are absorbing initial wafer starts despite yield learning curves. This geometry shift is expanding into thermal management subsystems, forcing package-level liquid cooling adoption that was previously confined to data center accelerators.
REACH substance restrictions are tightening permissible chemistries in European lithography and cleaning processes, elevating compliance costs for non-captive chemical suppliers. The regulation's SVHC candidate list now captures several fluorinated polymers used in chamber components, driving equipment makers toward ceramic and metal replacements. German and French fabrication facilities are responding with closed-loop solvent recovery systems that add 8-12% to operating expenditure but secure operating permits.
Automotive OEMs are consolidating chip procurement through direct foundry relationships, bypassing traditional tier-one semiconductor distributors for advanced logic categories. BMW, Mercedes-Benz, and Toyota have established dedicated supply agreements with TSMC and Samsung Foundry, locking multi-year capacity allocations. This disintermediation is most visible in Germany and Japan, where METI and KBA qualification requirements make distributor inventory liability untenable for safety-critical device categories.
Nano Chip Market Segmentation
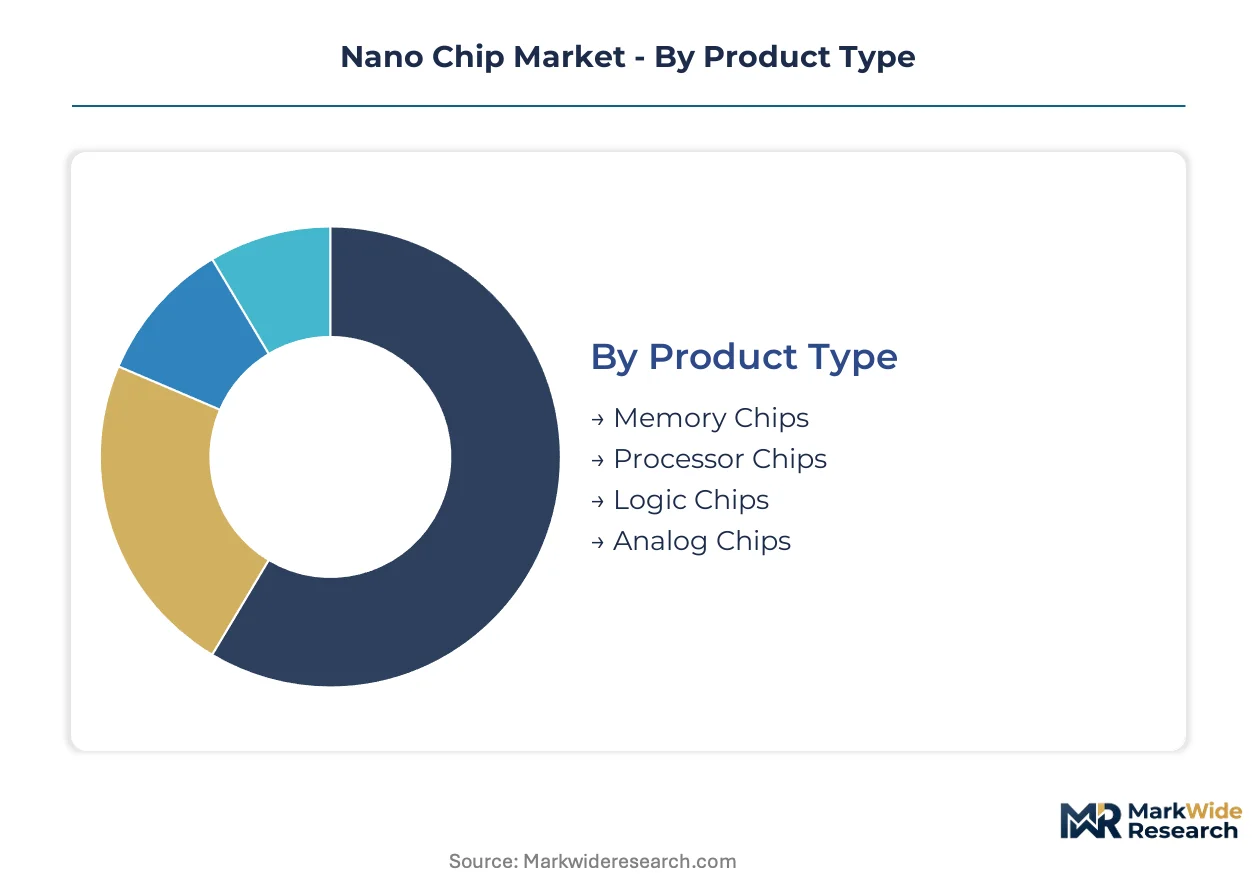
Nano chip segmentation reveals how fabrication complexity and end-use thermal requirements fragment supply chains. Each dimension—product architecture, application workload, material platform, and buyer sophistication—creates distinct margin pools and certification barriers.
Product Type:
Supply concentration varies dramatically across functional categories, with high-margin logic and processor segments captive to EUV-equipped foundries while memory and analog production disperses across mature-node facilities.
- Processor Chips:Advanced logic devices fabricated at 3nm and 2nm nodes using gate-all-around architectures. AI inference demand from Taiwan and South Korean data center operators is pulling capacity allocation from consumer electronics, tightening supply for automotive qualification.
- Logic Chips:General-purpose computational devices spanning microcontroller to system-on-chip integration. German automotive OEMs under EU Green Deal procurement mandates are redirecting fabrication toward energy-efficient process nodes with verified carbon accounting.
- Memory Chips:DRAM and NAND flash devices produced through vertical integration of wafer fabrication and assembly/test operations. Samsung Electronics anchors global supply through captive capacity scaling.
- Analog Chips:Signal conversion and power management devices with relaxed lithography requirements. Foundries in Japan and Europe maintain competitive position through automotive reliability certifications.
Today's leader: Processor Chips. Tomorrow's challenger: Logic Chips.
Application:
End-use thermal specifications and functional safety requirements stratify demand across radically different procurement timelines and qualification protocols.
- Automotive Electronics:Powertrain controllers, ADAS processors, and battery management systems requiring ISO 26262 ASIL-D certification. METI energy-efficiency mandates and KBA qualification requirements in Japan and Germany compress development velocities to 2-3 year cycles.
- Consumer Electronics:Smartphone application processors and wearable device chipsets with 12-18 month product lifecycles. Volume concentration in Taiwan's Hsinchu Science Park fabrication cluster drives die-per-wafer economics optimization.
- Telecommunications:Baseband processors and RF front-end modules for 5G infrastructure deployment. Network equipment manufacturers in South Korea and Finland prioritize sub-5W thermal design power for edge computing nodes.
- Aerospace Electronics:Radiation-hardened processors and high-reliability memory for satellite and avionics systems. Extended temperature range requirements force foundry recalibration of standard process nodes.
Procurement timelines stretch from 18 months in consumer electronics to 36 months in aerospace, fragmenting supplier engagement models.
Technology:
Material platform selection determines equipment compatibility, chemical supply chain access, and post-silicon migration pathways for 2030s device architectures.
- Silicon-based:Dominant platform using extreme ultraviolet lithography on 300mm wafers with atomic-layer deposition for gate oxides. TSMC's EUV lithography scale in Taiwan creates single-source dependency for sub-3nm production ramps.
- Carbon Nanotubes:Post-silicon logic pathway achieving sub-10nm channel control through contact resistance breakthroughs. Research institutions in Japan and the Netherlands are expanding fastest as semiconductor physics limits approach.
- Quantum Dots:Nanoscale semiconductor crystals for optoelectronic and quantum computing applications. R&D procurement from government agencies in the US and EU drives pilot production volumes.
- Graphene:Two-dimensional material platform for high-frequency and flexible electronics. Academic institutions in the UK and Singapore dominate fundamental research publications.
Silicon-based platforms command current volume; carbon nanotube architectures show steepest expansion trajectory in research funding and patent filings.
End User:
Buyer sophistication and procurement scale fragment demand across captive fabrication, outsourced foundry services, and speculative R&D volumes.
- Manufacturers:Integrated device manufacturers and fabless designers with direct foundry relationships. BMW, Mercedes-Benz, and Toyota have established dedicated supply agreements with TSMC and Samsung Foundry, locking multi-year capacity allocations.
- R&D Institutions:Corporate research laboratories and national semiconductor initiatives. India's PLI scheme for semiconductor manufacturing targets Gujarat and Karnataka facilities with 50% capex reimbursement.
- Government Agencies:Defense and space procurement programs with radiation-hardening and supply chain security requirements. US EPA TSCA reporting and REACH substance restrictions elevate compliance costs for non-captive chemical suppliers.
- Academic Institutions:University fabrication facilities and materials science departments. Only three universities worldwide produce doctoral candidates qualified for 13.5nm wavelength EUV photoresist materials engineering.
Direct manufacturer-foundry relationships are displacing traditional tier-one semiconductor distributors for advanced logic categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon-based nano chip fabrication traces its industrial lineage to Bell Labs' transistor breakthrough in the United States, with subsequent scaling concentrated in East Asian manufacturing clusters over subsequent decades.
United States
AI inference workloads from hyperscale data center operators in Arizona and Oregon are pulling advanced processor demand toward domestic EUV-equipped facilities. EPA TSCA reporting requirements for nanoscale materials elevate compliance costs for fabrication entrants. Intel Corporation anchors leading-edge production through captive manufacturing investments across its Southwest and Pacific Northwest facility network.
Taiwan
Hsinchu Science Park fabrication cluster concentrates silicon-based processor supply for global consumer electronics and automotive qualification programs. The absence of domestic carbon-border adjustments enables faster process node ramps compared to European competitors. TSMC dominates sub-3nm production capacity through exclusive ASML high-NA lithography deployment.
Germany
BMW and Mercedes-Benz procurement mandates under EU Green Deal carbon-border adjustments are redirecting logic chip demand toward energy-efficient fabrication with verified carbon accounting. KBA automotive qualification requirements compress development cycles to 2-3 year validation timelines. Saxony's Dresden semiconductor cluster hosts European-leading cleanroom capacity for automotive safety system chips.
Japan
Toyota's direct foundry relationships for powertrain controllers and ADAS processors are bypassing traditional semiconductor distributors. METI energy-efficiency mandates reward chips with sub-5W thermal design power through premium pricing tiers. Kyushu's Kumamoto prefecture fabrication complex supplies radiation-hardened devices for aerospace and automotive qualification programs.
South Korea
Memory chip demand from domestic data center operators is scaling DRAM and NAND flash orders alongside advanced processor procurement. MFDS pharmaceutical-grade cleanroom standards create certification spillover effects for medical device nano chip applications. Samsung Electronics anchors supply through captive control over wafer fabrication and assembly-test operations in the Seoul Capital Area.
Nano Chip Market Competitive Landscape
Premium-margin players sit above commodity-margin players across EUV lithography access and automotive qualification certification dimensions. Market structure consolidates around three tiers: foundry operators with captive high-NA equipment, integrated device manufacturers with backward integration into wafer fabrication, and fabless designers dependent on outsourced capacity allocation. Dominant competitive moves include direct OEM-foundry supply agreements that disintermediate traditional distributors, and heterogeneous packaging investments that bypass monolithic scaling economics.
Among foundry-based fabricators, Taiwan Semiconductor Manufacturing Company exemplifies the premium-tier archetype through exclusive equipment relationships, while Samsung Electronics occupies a position spanning memory and logic production with vertical control over capacity scaling. Intel Corporation represents the integrated device manufacturer model with domestic facility investments. These three anchors illustrate how equipment access and qualification certification separate margin tiers in advanced nano chip supply.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Qualcomm Incorporated |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Broadcom Inc. |
| SK Hynix |
| Samsung Electronics |
| Advanced Micro Devices (AMD) |
| Micron Technology |
| Intel Corporation |
| Others |
Supply & Pricing Matrix
Automotive OEM direct-foundry procurement mandates in Germany and Japan are compressing distributor margins and forcing foundries to absorb qualification cost burdens, reshaping how value distributes across the nano chip supply chain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates nano chip transactions. Premium tiers attach to ISO 26262 ASIL-D certified devices for automotive safety systems; standard tiers serve consumer electronics with relaxed thermal specifications; economy tiers capture mature-node analog chips. Cost compression in the economy tier is intensifying because fluorinated gas supply restrictions under EU F-Gas Regulation phase-down schedules elevate etching chemistry input costs. Automotive electronics buyers exhibit the lowest price sensitivity due to functional safety requirements, while consumer electronics procurement teams drive aggressive die-per-wafer economics negotiations.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke patterns for finished device logistics. Manufacturing concentration in Taiwan, South Korea, and the United States creates geographic dependency for EUV-equipped leading-edge production. Raw material inputs draw from high-purity silicon wafers, fluorinated etching chemistries, and photoresist polymers. Single-source vulnerability around ASML high-NA lithography equipment exposes sub-3nm production ramps to equipment allocation bottlenecks. Distribution runs through direct OEM-foundry agreements that disintermediate traditional tier-one semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon-border adjustments create arbitrage opportunities between European fabrication with verified carbon accounting and Asian production without such compliance overhead, rewarding geographic positioning that anticipates regulatory divergence.
For Market Incumbents: Extend captive EUV lithography scale through exclusive ASML equipment relationships to defend against carbon nanotube substitution threats. Deepen backward integration into photoresist materials engineering by sponsoring doctoral programs at qualified universities, addressing the scarcity of 13.5nm wavelength specialists. Lock multi-year capacity allocations with automotive OEMs before METI energy-efficiency mandates expand premium pricing tiers.
For New Entrants and Emerging Players: Fabless designers specializing in chiplets and 2.5D/3D heterogeneous integration can access white-space in automotive powertrain controllers where monolithic scaling costs exclude established competitors. Target India's Gujarat and Karnataka fabrication incentives under the PLI scheme, where 50% capex reimbursement lowers barrier to entry for automotive and defense logic demand. Pursue direct qualification partnerships with German KBA and Japanese METI to bypass distributor inventory liability requirements.
For Investors and Strategic Acquirers: Asymmetric upside sits with carbon nanotube research institutions achieving sub-10nm channel control breakthroughs, positioning for post-silicon logic migration in the 2030s. Long-term viability hinges on which material platform secures dominant automotive design wins as electrification redefines thermal specifications. Watch for ASML high-NA lithography allocation decisions as the inflection indicator for sub-3nm production capacity scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct OEM-Foundry Supply Agreement | BMW, Mercedes-Benz, and Toyota bypass distributors to lock multi-year capacity allocations. |
| Heterogeneous Packaging Investment | Chiplets enable fabless designers to mix process nodes, bypassing monolithic scaling costs. |
| EUV Lithography Capacity Expansion | TSMC's exclusive ASML high-NA deployment creates single-source dependency for sub-3nm production. |
| Carbon Nanotube R&D Partnership | Japanese and Dutch research institutions achieve sub-10nm channel control for post-silicon pathways. |
| Closed-Loop Solvent Recovery System | German and French fabs add 8-12% operating expenditure to secure REACH-compliant operating permits. |
Research Methodology
Bottom-up automotive and consumer electronics modeling reconciled against top-down foundry capacity tracking forms the analytical core. Primary interviews with foundry operations executives, automotive Tier 1 supplier procurement leads, fabless design house CTOs, and EUV equipment engineering directors combined with secondary validation. Secondary sources include EPA TSCA filings, ECHA REACH substance restriction updates, METI JIS standard publications, ASML equipment shipment disclosures, and SEMI wafer fab capacity databases. Triangulation across these sources reconciles demand-side procurement timelines with supply-side process node ramps.
Input-output matrices map fabrication capacity investments against end-use demand projections across the analysis window. Segmentation dimensions modeled include product architecture, application thermal requirements, material platform, and buyer procurement sophistication. CAGRs derive from equipment shipment trajectories, foundry revenue mix disclosures, and OEM direct procurement agreement announcements. Industry-specific forecast inputs incorporate EUV lithography equipment lead times and automotive functional safety certification cycle durations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon nanotube contact resistance breakthroughs and EU carbon-border adjustment enforcement timelines. Outputs reflect documented assumptions around ASML equipment allocation, REACH substance authorization timelines, and METI mandate implementation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Display Driver Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Asia Pacific Data Center Processor Market