
 CW Fiber Amplifier Market | 2026-2036
CW Fiber Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
CW Fiber Amplifier Market Outlook
Distributor relationships between component suppliers and systems integrators is tilting toward direct OEM partnerships. IPG Photonics leverages its in-house fiber fabrication to control amplifier cost structures. Thorlabs anchors North American supply through vertically integrated photonics manufacturing. Lumentum Holdings specializes in telecom-grade pump lasers that feed into erbium-doped amplifier chains.
A CW fiber amplifier boosts continuous-wave optical signals without converting them to electrical form, typically using erbium-doped fiber pumped at 980 nm or 1480 nm to achieve noise figures below 5 dB and output powers exceeding 30 dBm for long-haul transmission. EDFA product lines command the largest revenue share due to their maturity in submarine and terrestrial telecom networks. Raman amplifiers compete for ultra-long-haul routes where distributed amplification reduces nonlinear penalties. Semiconductor optical amplifiers occupy cost-sensitive short-reach applications in data center interconnects.
FCC Part 15 emissions rules constrain amplifier packaging for military and aerospace end uses in the United States. REACH and RoHS directives in Europe restrict rare-earth dopant sourcing and flame-retardant materials in amplifier modules. NMPA certification requirements in China create separate approval pathways for imported fiber amplifier systems. Stakeholders must weigh regulatory compliance costs against the margin advantages of serving certified defense and medical imaging segments.
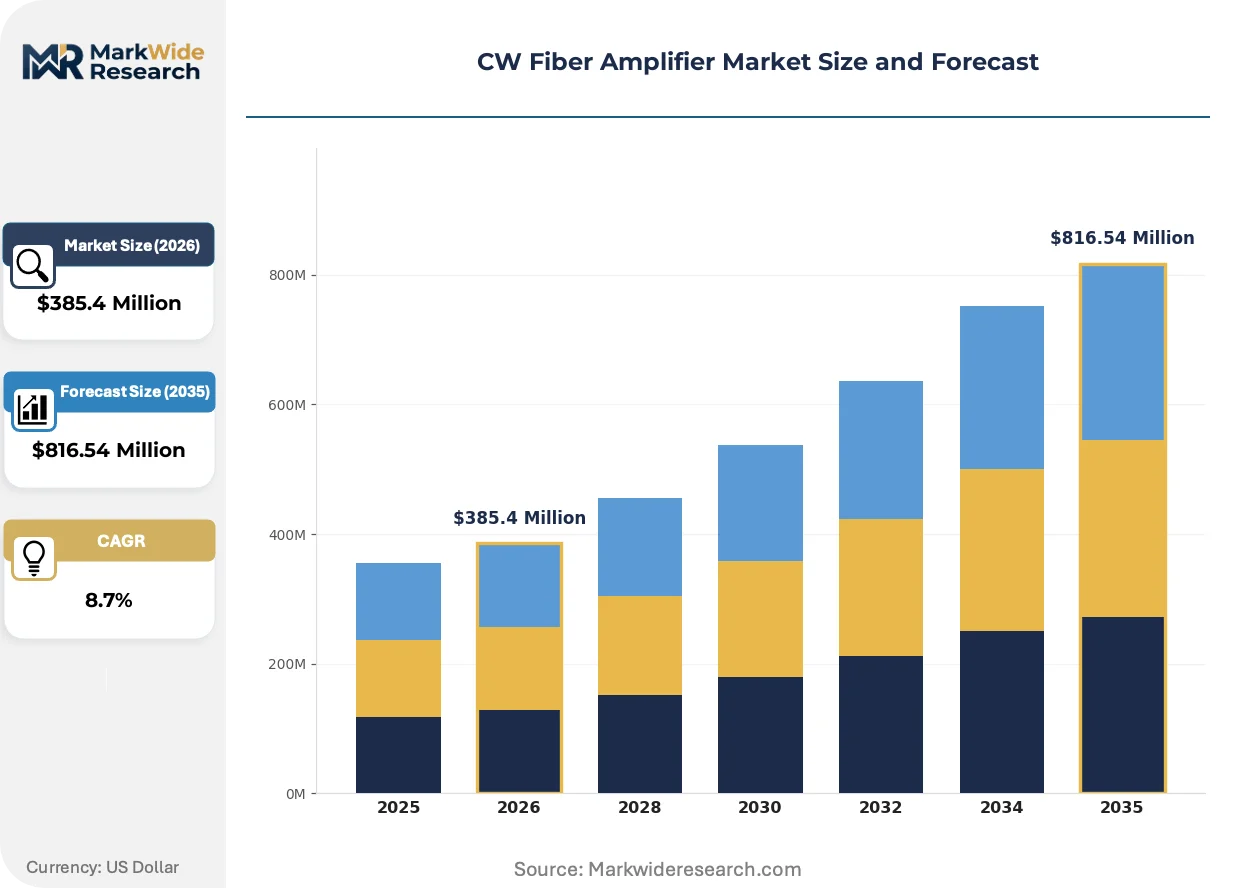
Market Dynamics
The CW fiber amplifier market is restructuring around energy efficiency mandates and supply chain consolidation, with EU Green Deal standards forcing redesigns of erbium-doped pump architectures while component suppliers bypass distributors to secure direct OEM relationships.
Growth Catalysts
- EU Green Deal energy standards:Tightening efficiency benchmarks under the EU Green Deal are compelling amplifier manufacturers to redesign pump laser architectures, creating replacement demand across installed telecom infrastructure.
- 5G backhaul buildouts:Telecom operators in Germany and South Korea are deploying high-power EDFA chains to support millimeter-wave fronthaul density requirements.
- Raman amplification for submarine cables:Distributed amplification architectures are displacing lumped EDFA designs on transpacific routes to reduce nonlinear signal distortion.
Market Restraints
- Rare-earth supply concentration:Erbium and ytterbium refining capacity clusters in China, exposing amplifier manufacturers to export quota volatility and dual carbon policy disruptions.
- REACH chemical compliance:ECHA restrictions on flame-retardant materials in amplifier housings force costly redesigns of heat-dissipation systems for European deployments.
- Semiconductor optical amplifier substitution:SOAs are capturing cost-sensitive data center interconnects below 10 km, compressing addressable volume for fiber amplifiers in short-reach applications.
Strategic Opportunities
- Free-space optical communications:Satellite constellations and airborne laser terminals require radiation-hardened EDFA modules with hermetic packaging, opening aerospace-grade product lines.
- Quantum key distribution networks:Ultra-low-noise amplifiers for quantum cryptography are migrating from laboratory to metropolitan testbeds in Switzerland and Japan.
- US IRA manufacturing incentives:Domestic content credits under the Inflation Reduction Act are attracting pump laser and specialty fiber fabrication to Arizona and Florida photonics corridors.
Industry Challenges
- Rare-earth dopant chemistry expertise:The pool of engineers capable of optimizing erbium concentration profiles for low-noise operation remains shallow relative to deployment timelines.
- FCC Part 15 emissions certification:Military and aerospace amplifier variants face extended approval cycles for electromagnetic compatibility testing, delaying program deliveries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CW Fiber Amplifier Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EDFA, Raman Amplifier, Semiconductor Optical Amplifier, Erbium Doped Fiber End User: Telecom Operators, Data Centers, Research Institutions, Military Applications Technology: Optical Fiber Technology, Wavelength Division Multiplexing, Coherent Technology, Integrated Photonics Application: Long-Haul Transmission, Short-Haul Transmission, Test and Measurement, Signal Processing |
| Companies Covered | IPG Photonics, RPMC Lasers Inc, Cybel, Nufern, Azurlight Systems, Thorlabs, NKT Photonics, Keopsys, Lumentum Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CW Fiber Amplifier Market Strategic Shifts
Amplifier architectures are fragmenting across performance-optimized and cost-optimized design paths, with efficiency regulations and application-specific noise requirements driving divergence in component selection and thermal management approaches.
Multimode pump laser technology is migrating from telecom-grade erbium-doped fiber amplifiers to industrial cutting and welding systems. IPG Photonics and nLight are shipping kilowatt-class fiber lasers into automotive battery production lines. This migration is compressing margins for 980 nm pump diodes as industrial demand absorbs supply previously reserved for communications applications.
REACH and RoHS directives in Europe are banning halogenated flame retardants in amplifier module housings. Manufacturers are substituting aluminum nitride ceramic substrates and graphene thermal interface materials to maintain heat dissipation without restricted polymers. Medical imaging and defense segments face the steepest compliance costs due to hermetic sealing requirements.
Telecom procurement teams are consolidating amplifier purchases under multi-year framework agreements with systems integrators rather than sourcing discrete components. This consolidation is displacing traditional distributor relationships in Germany and Japan. Equipment vendors are responding by embedding amplifiers into sealed line cards, reducing field-replaceable unit options.
CW Fiber Amplifier Market Segmentation
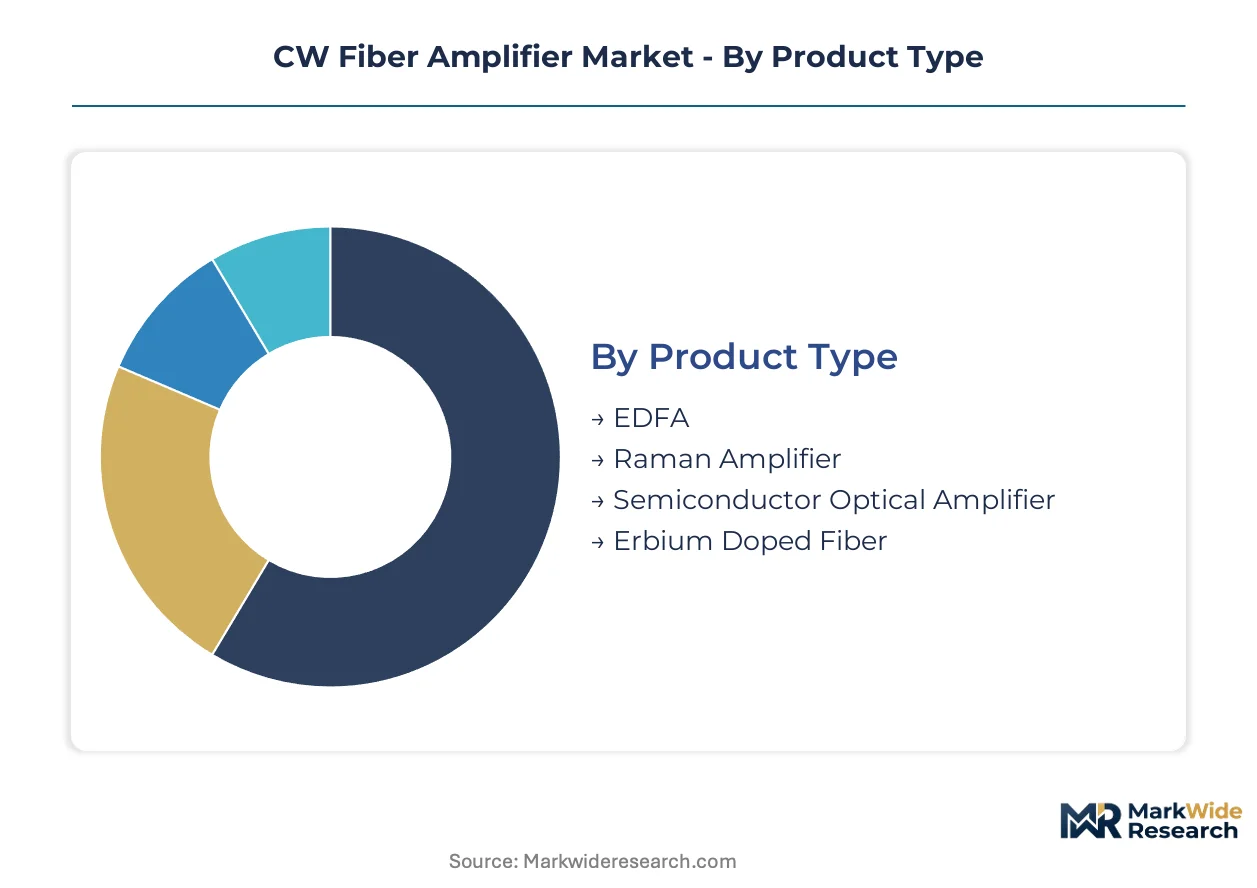
CW fiber amplifier procurement patterns diverge sharply across product architectures and end-use requirements, with service intensity varying from field-replaceable pump modules in submarine cables to sealed line cards in data center interconnects. Segment boundaries are blurring as telecom integrators embed amplification functions into broader transport systems.
Product Type:
After-sales service intensity peaks for erbium-doped fiber amplifiers deployed in submarine and long-haul terrestrial networks, where pump laser degradation drives recurring maintenance contracts and field engineering visits.
- EDFA:Erbium-doped fiber amplifiers achieve noise figures below 5 dB through 980 nm or 1480 nm pumping architectures. Demand concentrates in Germany's photonics cluster around Berlin and Jena, where telecom operators are rebuilding pump laser chains to meet EU Green Deal efficiency benchmarks.
- Raman Amplifier:Distributed amplification using stimulated Raman scattering reduces nonlinear penalties on ultra-long-haul routes. Submarine cable operators on transpacific routes are displacing lumped EDFA designs with these architectures to extend unrepeatered reach.
- Semiconductor Optical Amplifier:III-V chip-based amplification offers compact form factors for cost-sensitive short-reach links below 10 km.
- Erbium Doped Fiber:Specialty fiber with optimized erbium concentration profiles serves as the gain medium in custom amplifier builds for research and defense applications.
EDFA holds the largest share; momentum sits with Raman amplifiers on submarine routes.
End User:
Cost tier differentiation separates defense-certified hermetic modules from commercial-grade sealed line cards, with price multiples exceeding 3x for aerospace-qualified pump laser assemblies.
- Telecom Operators:5G backhaul buildouts in South Korea and millimeter-wave fronthaul density requirements in Germany are driving high-power EDFA chain deployments. Procurement is consolidating under multi-year framework agreements with systems integrators.
- Data Centers:Coherent transceivers with embedded amplification are displacing discrete amplifiers in interconnects below 80 km. SOAs are capturing cost-sensitive links under 10 km, compressing addressable volume for fiber amplifiers.
- Research Institutions:Ultra-low-noise amplifiers for quantum key distribution networks are migrating from laboratory to metropolitan testbeds in Switzerland and Japan.
- Military Applications:Radiation-hardened EDFA modules with hermetic packaging serve satellite constellations and airborne laser terminals. FCC Part 15 emissions rules constrain packaging designs and extend electromagnetic compatibility certification cycles.
Telecom operators dominate volume; research institutions are expanding most quickly as quantum networks scale.
Technology:
Volume concentration favors wavelength division multiplexing equipment, while integrated photonics commands premium pricing for coherent transceiver-on-chip architectures.
- Optical Fiber Technology:Conventional single-mode and specialty fibers form the physical layer for discrete amplifier modules. IPG Photonics leverages in-house fiber fabrication to control cost structures.
- Wavelength Division Multiplexing:Dense and coarse WDM systems aggregate multiple channels through shared amplification stages. EDFA product lines command the largest revenue share due to maturity in submarine and terrestrial networks.
- Coherent Technology:Digital signal processing with forward error correction enables higher spectral efficiency and longer unrepeatered reach.
- Integrated Photonics:Silicon photonics and indium phosphide platforms embed amplification functions within transceiver assemblies. This technology is climbing the fastest as data center operators prioritize form factor and power density.
Wavelength division multiplexing anchors installed base; integrated photonics shows the steepest expansion trajectory.
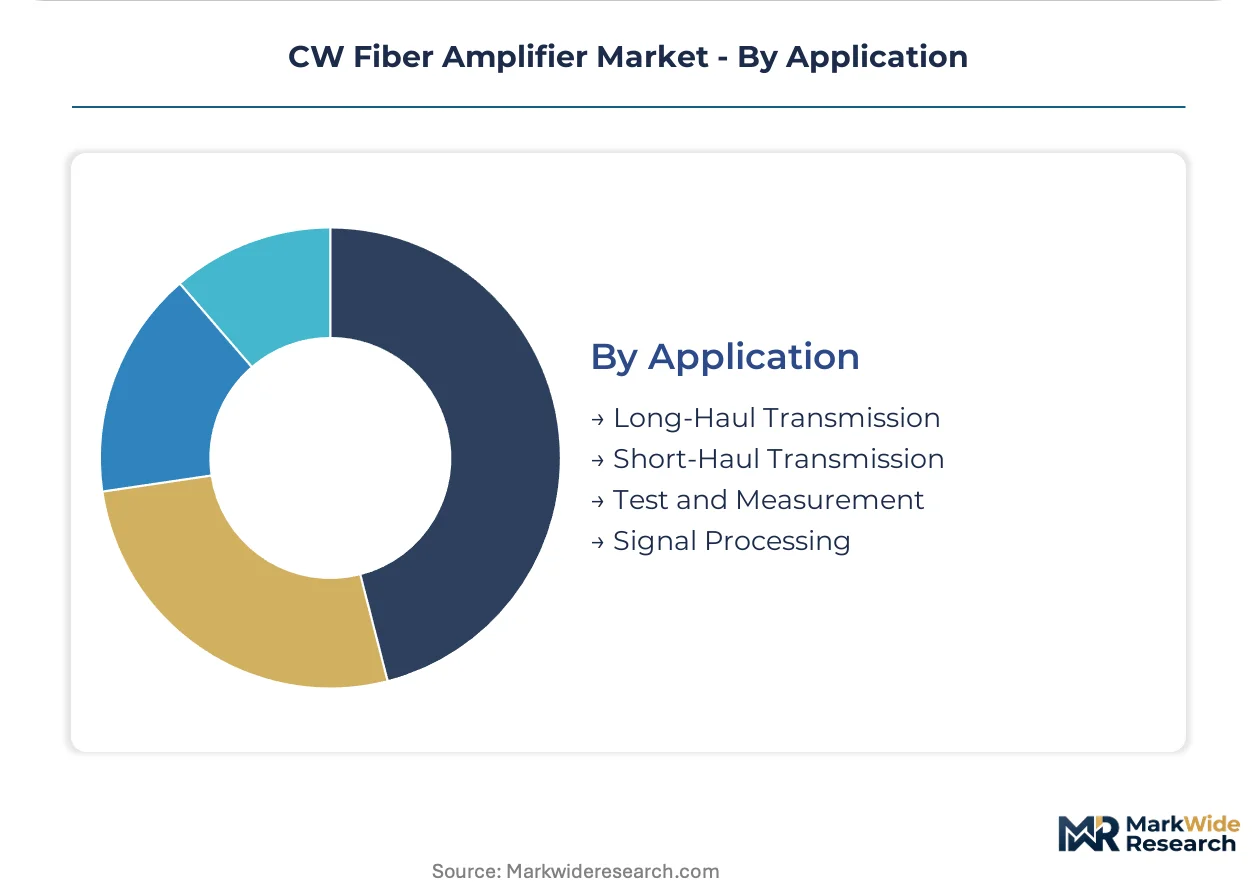
Application:
Customer type segmentation separates performance-optimized designs for submarine routes from cost-optimized architectures in metro and data center environments.
- Long-Haul Transmission:Transoceanic and continental backbone routes require low-noise, high-output-power amplification exceeding 30 dBm. Distributed Raman amplification is gaining share on the most demanding transpacific routes.
- Short-Haul Transmission:Metro and regional networks balance cost against noise figure requirements. Semiconductor optical amplifiers are substituting fiber amplifiers in links below 10 km.
- Test and Measurement:Broadband amplifiers with flat gain profiles support optical spectrum analyzer and component characterization applications.
- Signal Processing:Amplifiers with linear phase response enable analog photonic signal processing for radar and electronic warfare systems.
Long-haul transmission holds the largest share; signal processing for defense applications is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing stations at Porthcurno, Cornwall and Hinkley Point anchor the United Kingdom's role in transatlantic fiber amplification demand. These facilities drive replacement cycles for erbium-doped pump modules on transpacific and transatlantic routes.
United States
Defense procurement for satellite laser terminals and free-space optical communications drives demand for radiation-hardened EDFA modules. FCC Part 15 emissions rules constrain packaging designs and extend electromagnetic compatibility certification cycles for military variants. Arizona and Florida photonics corridors are attracting pump laser fabrication through Inflation Reduction Act domestic content credits.
Germany
Telecom operators are rebuilding pump laser chains to meet EU Green Deal efficiency benchmarks for 5G backhaul and millimeter-wave fronthaul density requirements. REACH and RoHS directives restrict rare-earth dopant sourcing and flame-retardant materials in amplifier modules. Berlin and Jena host the densest concentration of photonics manufacturing and systems integration activity.
China
NMPA certification requirements create separate approval pathways for imported fiber amplifier systems, fragmenting procurement for medical imaging and defense segments. Dual carbon policy disruptions and export quota volatility in erbium and ytterbium refining expose amplifier manufacturers to supply concentration risk. Yangtze River Delta facilities dominate rare-earth processing and specialty fiber preform production.
Japan
METI funding for quantum key distribution networks is migrating ultra-low-noise amplifiers from laboratory to metropolitan testbeds in Tokyo and Osaka. Coherent transceiver procurement is consolidating under multi-year framework agreements with systems integrators, displacing traditional distributor relationships. Kanto region hosts the primary concentration of integrated photonics foundry capacity.
Switzerland
Quantum cryptography testbeds in Geneva and Zurich are driving demand for amplifiers with noise figures optimized for single-photon detection thresholds. Swissmedic certification requirements for medical imaging equipment create premium pricing tiers for hermetically sealed modules. Basel-area precision manufacturing clusters supply ceramic substrates and thermal interface materials for REACH-compliant amplifier housings.
CW Fiber Amplifier Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated photonics manufacturers and specialized pump laser suppliers. Tiered competitive positioning separates in-house fiber fabricators from module assemblers dependent on external specialty fiber supply. Three archetypes dominate: captive fiber producers controlling cost structures, telecom-grade pump laser specialists, and systems integrators embedding amplification into sealed line cards. M&A activity concentrates on pump laser technology acquisitions, while capacity expansion targets Arizona and Florida corridors under US manufacturing incentive programs.
Within the captive fiber tier, IPG Photonics exemplifies backward integration into specialty fiber preform production. Thorlabs anchors North American supply through vertically integrated photonics manufacturing in New Jersey. Lumentum Holdings occupies the telecom-grade pump laser specialist position, supplying 980 nm and 1480 nm sources into erbium-doped amplifier chains. These three companies represent distinct strategic paths: upstream control over gain media, regional manufacturing scale, and component specialization for communications applications.
| Leading Market Players |
|---|
| IPG Photonics |
| RPMC Lasers Inc |
| Cybel |
| Nufern |
| Azurlight Systems |
| Thorlabs |
| NKT Photonics |
| Keopsys |
| Lumentum Holdings |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in 980 nm pump diode fabrication is compelling telecom equipment vendors to accept longer lead times and volume-commitment contracts, tilting supplier power toward in-house fiber fabricators and compressing margins for module assemblers dependent on external specialty fiber supply.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing separating aerospace-qualified hermetic modules from commercial sealed line cards and economy-grade data center interconnects. Price differentiation rests on certification grade and after-sales service bundling, with FCC Part 15 and REACH compliance adding 15-25% cost premiums for defense and medical segments. Cost compression in the data center tier is intensifying as coherent transceivers with embedded amplification displace discrete amplifiers. Telecom operators show the lowest price sensitivity due to multi-year framework agreements, while data center procurement teams drive the hardest volume negotiations.
Supply Chain Analysis
Upstream feedstock concentration in erbium and ytterbium refining centers the supply chain on China's Yangtze River Delta, with secondary processing clusters in Germany's Jena-Berlin corridor and Japan's Kanto region. Specialty fiber preforms, 980 nm pump diodes, and hermetic packaging ceramics constitute critical input dependencies. Single-source vulnerability in rare-earth processing exposes amplifier manufacturers to export quota volatility under China's dual carbon policy. Distribution runs through direct OEM partnerships that are displacing traditional distributor relationships in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from pump laser replacement contracts and field engineering visits is expanding faster than hardware sales, making after-sales infrastructure the decisive margin lever for sustained profitability.
For Market Incumbents: Build captive fiber fabrication moats to insulate cost structures from rare-earth supply volatility. IPG Photonics exemplifies this path through backward integration into specialty fiber preform production. Defend against semiconductor optical amplifier substitution in sub-10 km links by embedding amplifiers into sealed line cards that reduce field-replaceable unit options. Prioritize EU Green Deal compliance investments to capture replacement demand across Germany's telecom infrastructure. For New Entrants and Emerging Players: Establish a beachhead in quantum key distribution amplifier modules, where ultra-low-noise requirements and shallow engineering talent pools limit incumbent response speed. Switzerland and Japan metropolitan testbeds offer the most penetrable geographic entry points. Lead with radiation-hardened packaging expertise to differentiate from commodity telecom-grade suppliers and command aerospace-tier margins. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pump laser specialists with installed base maintenance contracts, making Lumentum-type component suppliers attractive relative to pure-play module assemblers. Long-term viability favors targets with in-house fiber fabrication or hermetic sealing capabilities that cannot be replicated through contract manufacturing. Watch NMPA certification timeline acceleration in China as the inflection signal for import substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Pump Laser Technology Acquisition | Consolidates 980 nm supply control for EU Green Deal-compliant EDFA chains. |
| Hermetic Packaging Certification Investment | Unlocks FCC Part 15 defense procurement with 3x pricing multiples over commercial tiers. |
| Quantum Network Amplifier Development | Captures METI-funded testbed demand in Tokyo and Osaka metropolitan areas. |
| Arizona-Florida Manufacturing Expansion | Secures IRA domestic content credits for pump laser and specialty fiber fabrication. |
| Direct OEM Partnership Consolidation | Displaces distributor relationships and locks in multi-year framework agreements with German telecom operators. |
Study Parameters
Cross-validation between primary interviews with telecom procurement directors, pump laser engineering leads, and submarine cable systems integrators and secondary validation through ECHA REACH filings, FCC Part 15 equipment authorization databases, and METI quantum network funding disclosures anchors the qualitative findings. Bottom-up modeling of amplifier unit shipments by product architecture and top-down reconciliation against telecom capex disclosures ensures triangulation integrity.
Calibration against historical EDFA replacement cycles and Raman amplifier adoption curves on transpacific routes shapes the projection framework across the analysis window. Segmentation dimensions include product type, end-user vertical, application distance, and regional regulatory cluster. CAGRs derive from slope analysis of installed base growth against efficiency-mandated replacement demand, with EU Green Deal compliance timelines and 5G backhaul deployment schedules as primary forecast inputs.
Stress conditions across rare-earth export quota volatility, REACH chemical restriction expansion, and semiconductor optical amplifier performance thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding pump laser degradation rates and framework agreement renewal probabilities. Cross-checking against submarine cable systems integrator order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Tunable Filter Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Display Optical Film Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Global Optical Diode Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Fogless Mirror Market
Optical Components
Optical Spectrum Analyzer (OSA) Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Optical Isolator Market
Optical Components
Global Adaptive Optics Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Spatial Light Modulator Market
Optical Components
North America Tunable Laser Market