
 Solar PV Tracker Market | 2026-2036
Solar PV Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Tracker Market Outlook
Utility procurement channels is reshaping how tracker vendors access multi-gigawatt pipelines, with EPC-led bundling displacing direct OEM sales in emerging markets. Nextracker leverages its vertically integrated steel supply to sustain margin control across volatile raw material cycles. Array Technologies anchors North American utility-scale deployment through its centralized drive architecture, while Arctech Solar dominates bifacial-compatible tracker designs for high-albedo desert environments.
A solar PV tracker is a mechanical mounting system that orients photovoltaic modules toward the sun throughout the day, typically achieving 20-35% additional energy yield over fixed-tilt systems through single or dual-axis rotation. The technology employs electromechanical drive trains, astronomical algorithms, and sensor feedback to optimize incidence angle across seasonal and diurnal variation. Single-axis trackers command the largest installed base due to favorable LCOE economics in utility-scale settings, while dual-axis configurations capture premium margin pools in concentrated solar hybrid applications. Electromechanical systems lead technology adoption, though programmable control architectures are gaining traction as grid operators impose dynamic curtailment protocols.
FERC Order 2023 interconnection reforms in the United States are compressing queue timelines for tracker-equipped solar assets, while the EU Green Deal's renewable acceleration mandates are tightening local content requirements for European project pipelines. Saudi Arabia's SASO technical regulations for solar mounting systems are creating conformity barriers for non-GCC manufacturers seeking PIF-backed contracts. Stakeholders must monitor how bifacial eligibility criteria in evolving IEC standards redefine tracker structural load specifications and warranty terms.
Market Dynamics
Tracker vendors face mounting pressure from bifacial module standardization, as NREL's performance protocols force rapid recalibration of structural load assumptions and warranty frameworks across electromechanical portfolios.
Growth Catalysts
- Utility-Scale Procurement Bundling:EPC-led contracting in Saudi Arabia and the UAE is consolidating tracker orders into multi-gigawatt packages, compressing vendor qualification cycles and accelerating deployment velocity.
- FERC Order 2023:Interconnection queue reforms in the United States are shortening approval timelines for tracker-equipped solar assets, reducing project development risk premiums.
- Bifacial-Compatible Architectures:Dual-axis and enhanced single-axis designs optimized for high-albedo desert environments are capturing incremental yield premiums in Middle Eastern installations.
Market Restraints
- Steel Price Volatility:Galvanized steel accounts for the majority of tracker bill-of-materials, exposing margins to commodity cycle swings that vendors cannot fully pass through in competitive tenders.
- SASO Technical Barriers:Saudi Arabia's mounting system regulations create conformity costs for non-GCC manufacturers, effectively regionalizing supply bases for PIF-backed projects.
- Fixed-Tilt Substitution:Low-cost fixed-tilt racking retains cost advantage in high-latitude, low-irradiance zones where tracker yield premiums fail to justify capital outlay.
Strategic Opportunities
- Concentrated Solar Hybrid Integration:Dual-axis trackers are hybridizing with CSP thermal collection, opening premium margin pools in dispatchable solar projects across Morocco and Chile.
- Dynamic Curtailment Protocols:Grid operators in California and Texas are mandating programmable control architectures, creating upgrade revenue streams for legacy tracker fleets.
- EU Green Deal Local Content:Renewable acceleration mandates are tightening domestic sourcing requirements, advantaging European tracker fabricators with captive steel supply.
Industry Challenges
- Electromechanical Talent Scarcity:Drive train engineering and astronomical algorithm development expertise concentrates among a narrow cohort of specialists, constraining R&D throughput.
- IEC Standard Uncertainty:Evolving bifacial eligibility criteria in structural load specifications are forcing premature warranty recalibrations ahead of finalized test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Tracker Market |
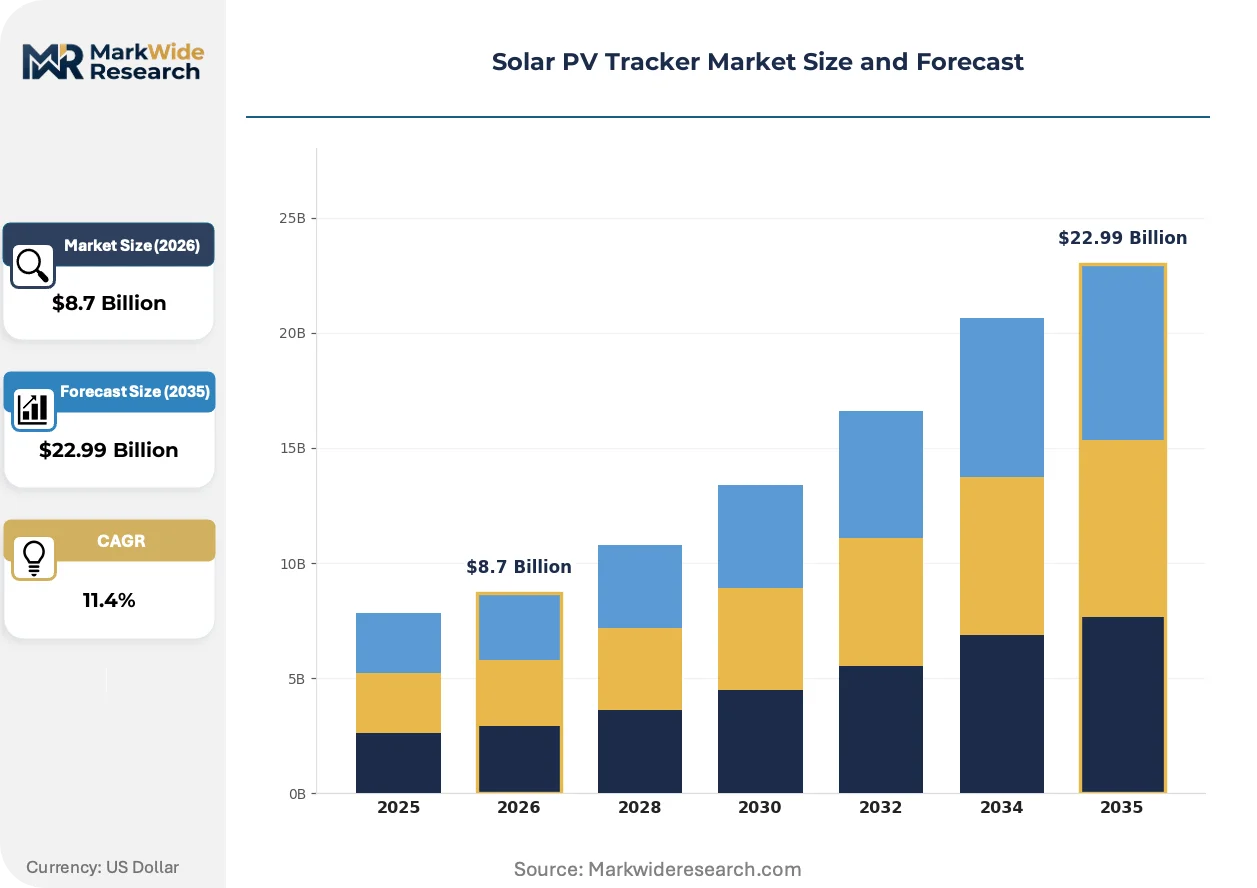
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axis, Dual Axis, Fixed Tilt, Bifacial Technology: Electromechanical, Optical, Programmable, Manual End User: Utility Scale, Commercial, Residential, Industrial Installation: Ground Mounted, Rooftop, Floating, Integrated |
| Companies Covered | Nextracker, Array Technologies, Arctech Solar, Soltec Power Holdings, PV Hardware, GameChange Solar, Trina Tracker, STI Norland, Convert Italia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Tracker Market Strategic Shifts
Control architectures and material science are converging to redefine tracker value propositions, as grid interactivity requirements and module form factor evolution force hardware-software co-development cycles.
Tracker drive systems are hybridizing with distributed energy resource management platforms, enabling real-time tilt adjustment in response to wholesale price signals and grid curtailment commands. Utility-scale developers in ERCOT and CAISO territories are piloting these responsive configurations to capture peak pricing windows. The convergence is compressing traditional tracker hardware margins while opening software-subscription revenue streams.
The EU Green Deal's renewable acceleration mandates are tightening local content thresholds for tracker steel and electromechanical components, forcing supply chain reconfiguration toward European fabrication capacity. German and Spanish EPCs are now specifying regional sourcing quotas in tender documents. This regulatory friction is advantaging mid-scale fabricators with captive rolling mills while disadvantaging import-dependent vendors.
Asset owners are unbundling tracker O&M contracts from EPC wrap agreements, creating direct procurement channels for predictive maintenance and component refresh services. Independent service providers in Arizona and Rajasthan are capturing these disaggregated contracts through performance-guarantee pricing models. The shift is visible most acutely in operational fleets exceeding 500 MW where scale economics justify dedicated service teams.
Solar PV Tracker Market Segmentation
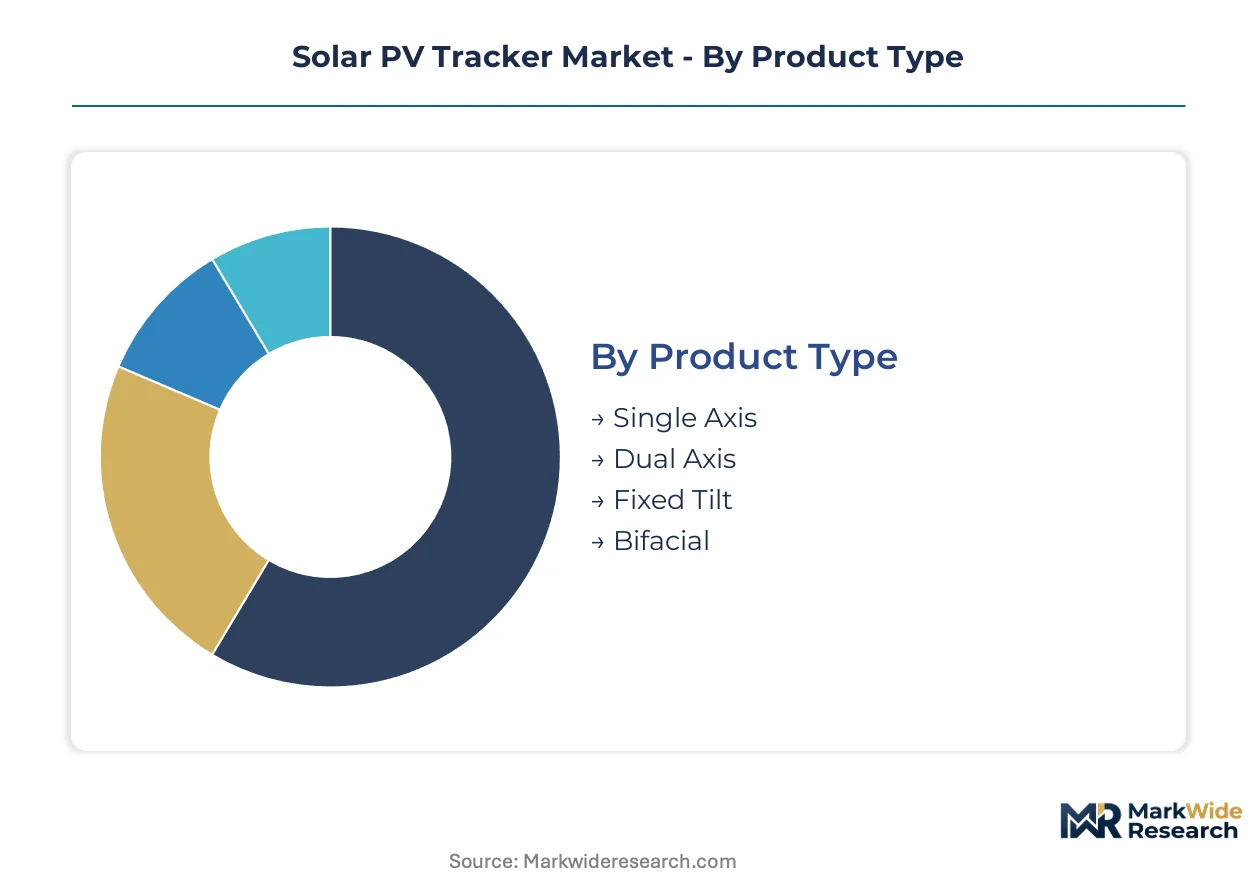
Tracker segmentation reveals divergent service intensity profiles across electromechanical architectures. Single-axis systems dominate installed base volumes but generate lower per-unit service revenue than precision dual-axis configurations demanding specialized calibration protocols.
Product Type:
After-sales service intensity escalates sharply with rotational complexity, creating tiered margin pools for maintenance providers across the tracker fleet.
- Single Axis:Horizontal or tilted rotation along one axis captures 20-35% yield uplift over fixed-tilt at moderate capital cost. Utility-scale procurement in Saudi Arabia and the UAE concentrates demand where EPC bundling compresses vendor margins but extends service contract durations.
- Dual Axis:Azimuth and elevation tracking maximizes energy harvest through continuous sun alignment. Concentrated solar hybrid installations in Morocco and Chile absorb premium-priced units where precision electromechanics justify elevated O&M expenditure.
- Fixed Tilt:Static mounting eliminates drive train maintenance entirely. Low-irradiance European markets retain this architecture where tracker yield premiums fail to offset capital outlay.
- Bifacial:Elevated structures optimized for rear-side irradiance capture in high-albedo desert environments. NREL performance protocols force structural recalibration of legacy designs.
By volume, Single Axis leads. By growth pace, Bifacial is ahead.
Technology:
Control sophistication determines software attach rates and recurring revenue potential across tracker technology tiers.
- Electromechanical:Motor-driven gear trains execute astronomical positioning algorithms. This installed base commands the largest replacement parts market as bearing and drive component wear accelerates in abrasive desert conditions.
- Optical:Sensor-based sun tracking corrects astronomical drift through direct irradiance measurement. High-precision CSP hybrid applications in Chile favor this architecture where beam alignment tolerance is tightest.
- Programmable:Grid-interactive controllers enable dynamic tilt adjustment responding to curtailment commands. ERCOT and CAISO procurement specifications now mandate this capability for new interconnection approvals.
- Manual:Seasonal adjustment by maintenance crews persists in cost-constrained emerging markets. Minimal technology content leaves no attachable software revenue.
Electromechanical systems anchor current revenue. Programmable architectures are climbing the fastest.
End User:
Customer scale dictates procurement channel structure and vendor qualification burden intensity.
- Utility Scale:Multi-hundred-megawatt procurement bundles concentrate through EPC-led tenders. ACWA Power gigawatt-scale Saudi deployments exemplify this channel where vendor steel supply integration determines award outcomes.
- Commercial:Behind-the-meter installations for retail and logistics facilities. Distributed scale fragments procurement across regional installer networks with limited standardization.
- Residential:Rooftop trackers remain niche due to structural load constraints and permitting complexity. European suburban markets show sporadic adoption.
- Industrial:On-site solar for manufacturing and data center loads. Corporate renewable targets in Germany and Spain drive specification of EU-sourced steel components.
Utility Scale commands absolute volume. Commercial applications show steepest expansion trajectory as C&I procurement accelerates.
Installation:
Site topology constrains tracker architecture selection and foundation engineering cost structures.
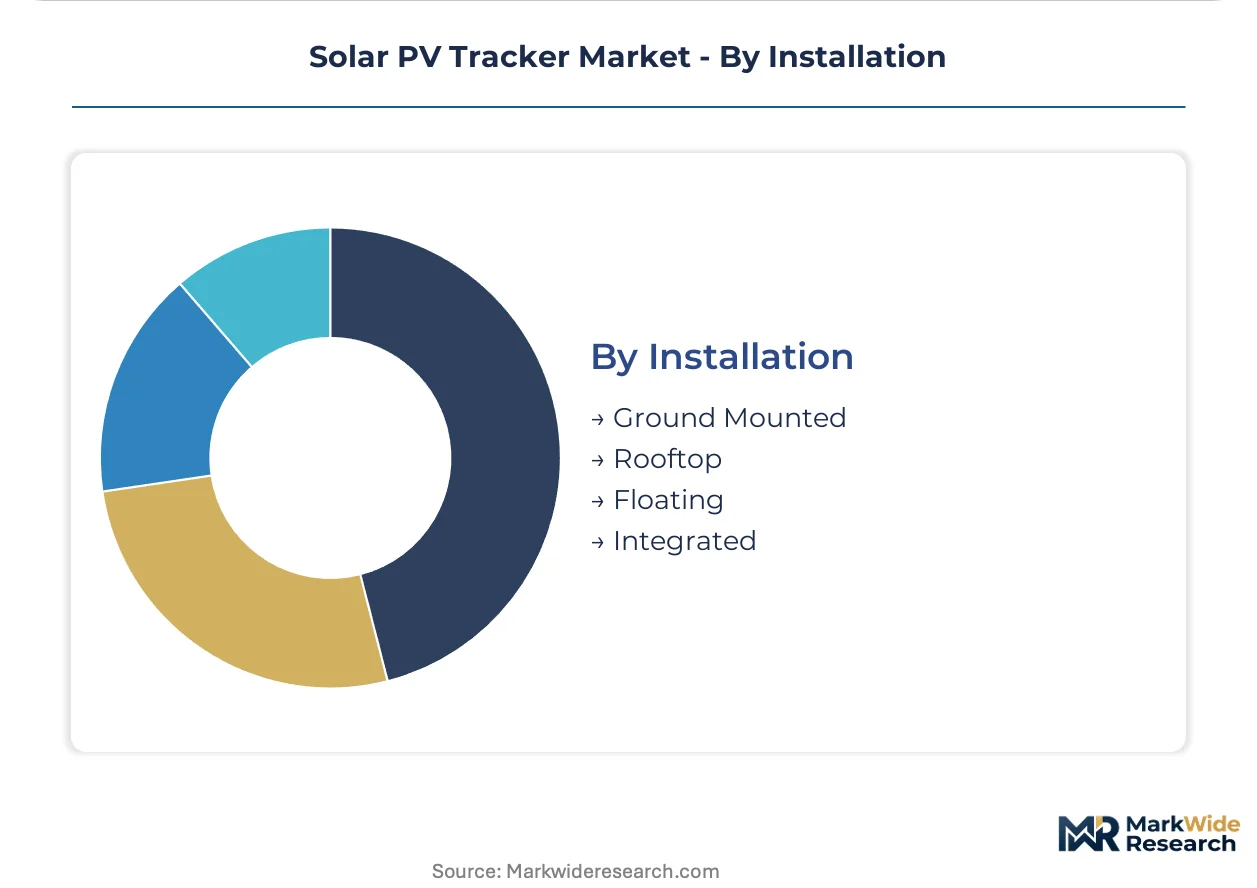
- Ground Mounted:Terrestrial pile or ballast foundations enable full rotational freedom. Desert solar farms across Saudi Arabia, Morocco, and Chile standardize on this approach.
- Rooftop:Structural load limits restrict tracker mass and wind exposure. Commercial building applications in Germany face stringent building code constraints.
- Floating:Pontoon or mooring systems for reservoir and coastal deployment. Southeast Asian markets pilot this architecture where land scarcity intersects high irradiance.
- Integrated:Building-embedded or agricultural co-use structures. Agrivoltaic installations in France and Japan adopt elevated single-axis configurations.
Ground Mounted dominates deployment volume. Floating installations are gaining share fastest as land-constrained markets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 765-kilometer Red Sea coastal transmission corridor underwrites Saudi Arabia's emergence as the dominant demand center for solar PV tracker deployment across the Middle East and North Africa.
Saudi Arabia
ACWA Power's gigawatt-scale procurement programs concentrate tracker demand in the Eastern Province and NEOM Northwest development zones. SASO technical regulations for solar mounting systems impose conformity costs on non-GCC manufacturers, effectively regionalizing supply bases for PIF-backed desert installations. The Al-Faisaliah industrial cluster near Riyadh hosts emerging steel fabrication capacity serving tracker OEM localization requirements.
United States
ERCOT and CAISO grid operators mandate programmable control architectures for new interconnection approvals, compressing deployment timelines for tracker-equipped solar assets. FERC Order 2023 interconnection reforms shorten queue approval cycles, reducing project development risk premiums in Texas and California markets. The Permian Basin solar corridor anchors concentrated demand where bifacial-compatible single-axis systems capture high-albedo yield premiums.
Morocco
Noor Ouarzazate solar complex expansion drives concentrated solar hybrid integration, opening premium margin pools for dual-axis tracker configurations. The country's renewable energy agency Masen enforces local content thresholds for steel components in utility-scale tenders. The Tangier Med industrial zone hosts fabrication capacity serving both domestic deployment and re-export to European project pipelines.
Chile
Atacama Desert high-irradiance conditions justify dual-axis precision electromechanics where beam alignment tolerance is tightest for CSP hybrid applications. The central bank's green bond framework channels institutional capital toward tracker-equipped solar assets in Antofagasta and Tarapacá regions. Mejillones port infrastructure supports import logistics for electromechanical drive train components.
India
Gujarat and Rajasthan state renewable purchase obligations concentrate utility-scale tracker deployment in the western solar belt. Central Electricity Authority grid codes impose dynamic curtailment protocols that favor programmable control architectures. The Mundra port cluster enables steel import logistics for tracker fabricators serving domestic EPC bundling contracts.
Solar PV Tracker Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in steel supply and drive train engineering. The vendor base concentrates around three to five vertically integrated players with captive steel supply, while mid-scale fabricators compete on regional sourcing compliance. Two strategic archetypes dominate: EPC-aligned bundlers capturing multi-gigawatt procurement packages, and technology specialists defending margin through bifacial-compatible structural IP. Competitive moves center on backward integration into galvanization capacity and strategic partnerships with module OEMs for co-developed mounting solutions.
Among North American platform integrators, Nextracker and Array Technologies exemplify the EPC-aligned archetype with steel supply integration, while Arctech Solar occupies a position within the bifacial-specialist tier serving high-albedo desert environments. These three anchors represent divergent competitive vectors: scale-driven procurement bundling, centralized drive architecture standardization, and precision electromechanics for dual-axis applications. Their positioning reflects how tracker value capture splits between hardware margin defense and software-subscription revenue streams in grid-interactive configurations.
| Leading Market Players |
|---|
| Nextracker |
| Array Technologies |
| Arctech Solar |
| Soltec Power Holdings |
| PV Hardware |
| GameChange Solar |
| Trina Tracker |
| STI Norland |
| Convert Italia |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese galvanized steel rolling mills is compressing input costs for tracker OEMs while simultaneously eroding pricing power across competitive tender environments. This utilization dynamic forces vendors to absorb commodity volatility through margin compression rather than pass-through mechanisms, reshaping procurement negotiations for EPC-led bundling contracts.
Pricing Analysis
Volume-discount tiering structures dominate utility-scale procurement, with gigawatt-scale EPC packages commanding 15-25% unit cost reductions against fragmented commercial orders. Price differentiation hinges on steel supply integration and after-sales service bundling, where vertically integrated vendors defend margin against import-dependent competitors. Cost compression in standard single-axis configurations is intensifying as Saudi and UAE procurement pools consolidate, while bifacial-compatible premium tiers retain pricing resilience. Commercial and residential segments exhibit acute price sensitivity, whereas utility developers prioritize performance guarantees and localization compliance over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for electromechanical drive train components. Manufacturing gravity centers on China for galvanized steel and precision gearing, Spain and Germany for control system fabrication, and India for emerging steel conversion capacity. Raw material dependencies span high-grade steel coil, rare-earth motor magnets, and polymer bearing compounds. Single-source vulnerability concentrates in astronomical control algorithm IP held by narrow specialist cohorts. Distribution runs through EPC prime contractors rather than direct OEM channels in utility-scale segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar PV tracker market is exiting a steel price trough and entering cyclical recovery as desert utility procurement accelerates across the Middle East and North Africa. Galvanized steel cost normalization is restoring vendor margin structures that commodity spikes compressed.
For Market Incumbents: Insulate margin structures through captive galvanization capacity and backward integration into regional steel rolling. EPC-led bundling consolidation threatens direct sales channels; defend position by embedding service contracts within procurement packages. SASO conformity requirements in Saudi Arabia create regulatory moats for GCC-localized fabrication.
For New Entrants and Emerging Players: Pursue programmable control architecture specialization as grid operators mandate dynamic curtailment responsiveness. White-space concentrates in floating solar tracker adaptation for Southeast Asian reservoir deployment and agrivoltaic elevated structures for European agricultural co-use. Channel entry through independent service provider partnerships bypasses EPC qualification barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among programmable control vendors with software-subscription attach rates. Long-term viability favors fabricators with dual-axis precision electromechanics and CSP hybrid integration capability. The inflection signal to monitor is bifacial eligibility criteria finalization in IEC structural load standards, which will force warranty recalibration across legacy fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanization | Captive coating capacity insulates margin against steel commodity cycles in Saudi procurement. |
| Programmable Control Architecture Development | ERCOT and CAISO curtailment mandates create software-subscription revenue streams. |
| Regional Steel Fabrication Localization | EU Green Deal local content thresholds advantage European rolling mill proximity. |
| CSP Hybrid System Integration | Morocco Noor complex expansion opens premium dual-axis margin pools. |
| Predictive Maintenance Service Unbundling | Arizona and Rajasthan operational fleets exceeding 500 MW justify dedicated O&M teams. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EIA project databases, IEA renewable technology reports, FERC interconnection filings, and customs trade records for steel and electromechanical components. Primary interviews engaged EPC procurement directors, utility planning officers, tracker OEM product managers, and grid operator interconnection specialists across Saudi Arabia, the United States, Morocco, and Chile. Bottom-up installation forecasts triangulate against top-down renewable capacity targets from national energy agencies.
Forecast inputs incorporate tracker adoption rates by project scale tier, bifacial module penetration curves, and regional steel price indices across the projection horizon. Segmentation dimensions span electromechanical versus programmable control architectures, single-axis versus dual-axis rotation complexity, and ground-mounted versus floating installation topology. CAGRs derive from regression against historical utility-scale procurement velocity and EPC bundling contract announcements.
Sensitivities concentrate around IEC bifacial load standard finalization, Saudi SASO technical regulation enforcement intensity, and steel commodity cycle amplitude. Forecasts reflect assumptions regarding EPC consolidation continuity and grid curtailment protocol adoption timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Southeast Asia Solar Energy Market