
 South America Solar PV Inverters Market | 2026-2036
South America Solar PV Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
South America Solar PV Inverters Market Analytics
Brazil's distributed generation legal framework is shifting the cost-of-entry calculus for residential and commercial inverter suppliers. Enphase Energy leverages its microinverter architecture to capture rooftop demand in São Paulo and Minas Gerais. Sungrow Power Supply anchors utility-scale deployments through high-capacity central inverter supply to projects in Bahia and Piauí. SMA Solar Technology competes across both segments with modular string inverter platforms that navigate Brazil's grid code requirements.
South America solar PV inverters are power electronic devices that convert direct current from photovoltaic modules into alternating current synchronized to grid frequency, typically operating at efficiency ratings above 98% and incorporating maximum power point tracking algorithms. Their primary purpose is enabling grid injection or local consumption of solar-generated electricity across residential, commercial, and utility installations. String inverters dominate residential and commercial rooftop applications due to lower balance-of-system costs and flexible design configurations. Central inverters sustain margin concentration in utility-scale projects where economies of scale and 1500-volt DC architecture reduce levelized cost of energy. Hybrid technology tied to battery storage represents the fastest-expanding segment as Chile and Brazil implement time-of-use tariffs and backup power requirements.
ANVISA certification requirements for electrical equipment and Brazil's ABNT NBR technical standards shape product compliance pathways for inverter manufacturers seeking market access. Chile's SEC electrical safety regulations and net billing mechanisms under Law 21.118 direct product specification toward grid-tied solutions with anti-islanding protection. Argentina's CNEA renewable energy promotion framework and import substitution policies influence localization decisions. Stakeholders must monitor regulatory divergence across Mercosur member states when configuring regional supply chains and service networks.
Market Dynamics
Brazil's distributed generation legal framework is compressing procurement timelines for residential and commercial inverter suppliers while Chile's utility-scale auctions concentrate demand for 1500-volt central systems. This dual-track demand structure is fragmenting supplier strategies across voltage classes and application segments.
Growth Catalysts
- Brazil's net metering regulations:The country's distributed generation framework enables residential prosumers to offset grid consumption, expanding addressable market for single-phase string inverters in São Paulo and Minas Gerais.
- Utility-scale solar parks:High irradiance corridors in Brazil's Northeast and Chile's Atacama Desert attract gigawatt-scale project development requiring high-capacity central inverter deployments.
- Time-of-use tariff structures:Brazil's ANEEL regulatory adjustments and Chile's SEC-mandated rate designs incentivize battery-coupled hybrid inverters for peak shaving and backup power applications.
Market Restraints
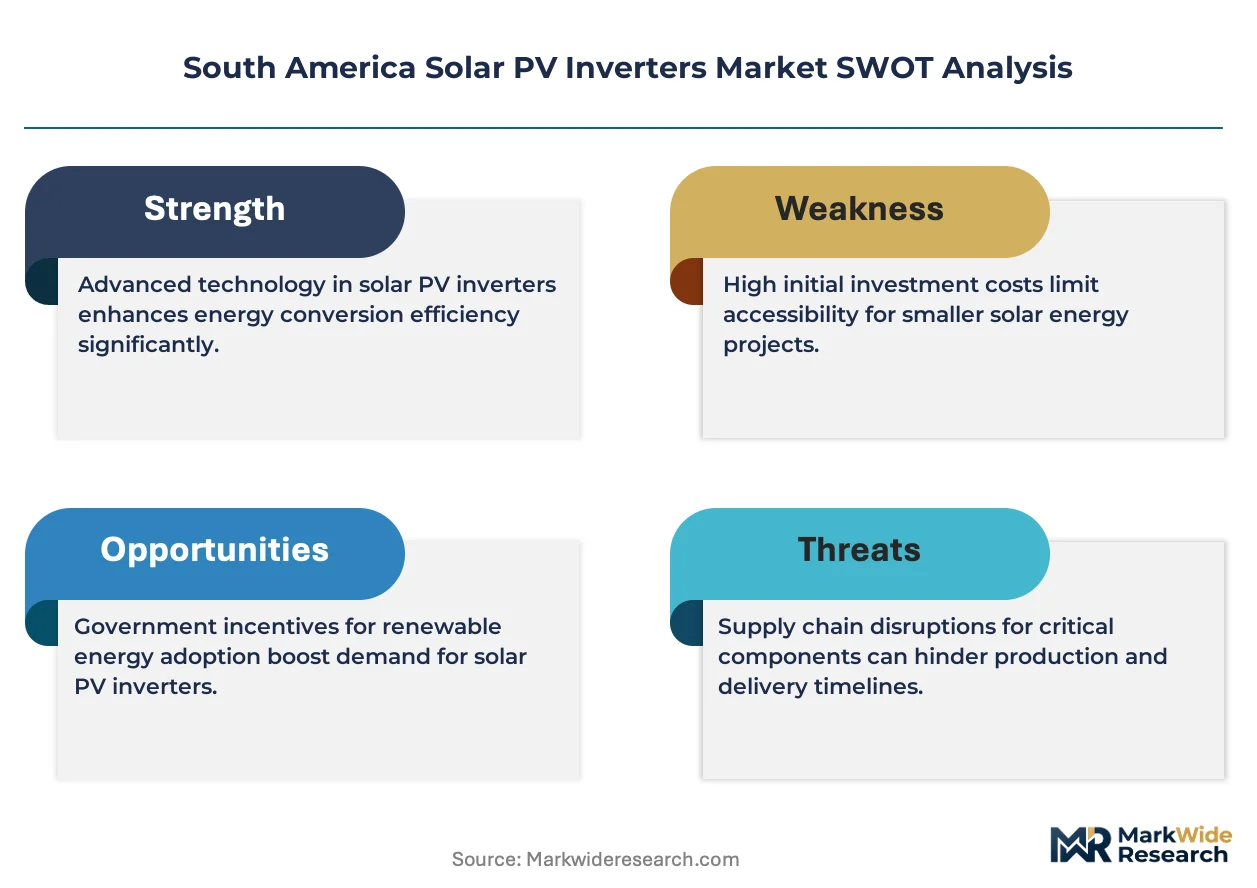
- IGBT and silicon carbide supply concentration:Power semiconductor sourcing remains concentrated among East Asian foundries, exposing inverter manufacturers to input cost volatility and extended lead times.
- ANVISA certification timelines:Brazil's electrical equipment safety protocols impose multi-month approval processes that delay product launches and freeze inventory commitments.
- Grid interconnection bottlenecks:Transmission infrastructure constraints in Brazil's Northeast and Chile's northern regions limit project energization regardless of inverter availability.
Strategic Opportunities
- Argentina's CNEA renewable promotion:The country's import substitution policies and renewable energy auctions create localization incentives for inverter assembly operations serving Mercosur demand.
- Hybrid storage convergence:Battery inverter integration with lithium-ion systems opens retrofit opportunities across Brazil's existing distributed generation fleet.
- Direct-to-installer digital channels:E-commerce platforms and manufacturer-direct portals are bypassing traditional electrical distributor markups in Colombia and Peru.
Industry Challenges
- Power electronics engineering scarcity:Specialized firmware and grid synchronization expertise remains concentrated among a limited talent pool across São Paulo and Santiago technical institutes.
- Multi-certification burden:Divergent ABNT NBR, SEC, and IRAM standards force product variant proliferation that strains R&D and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Solar PV Inverters Market |
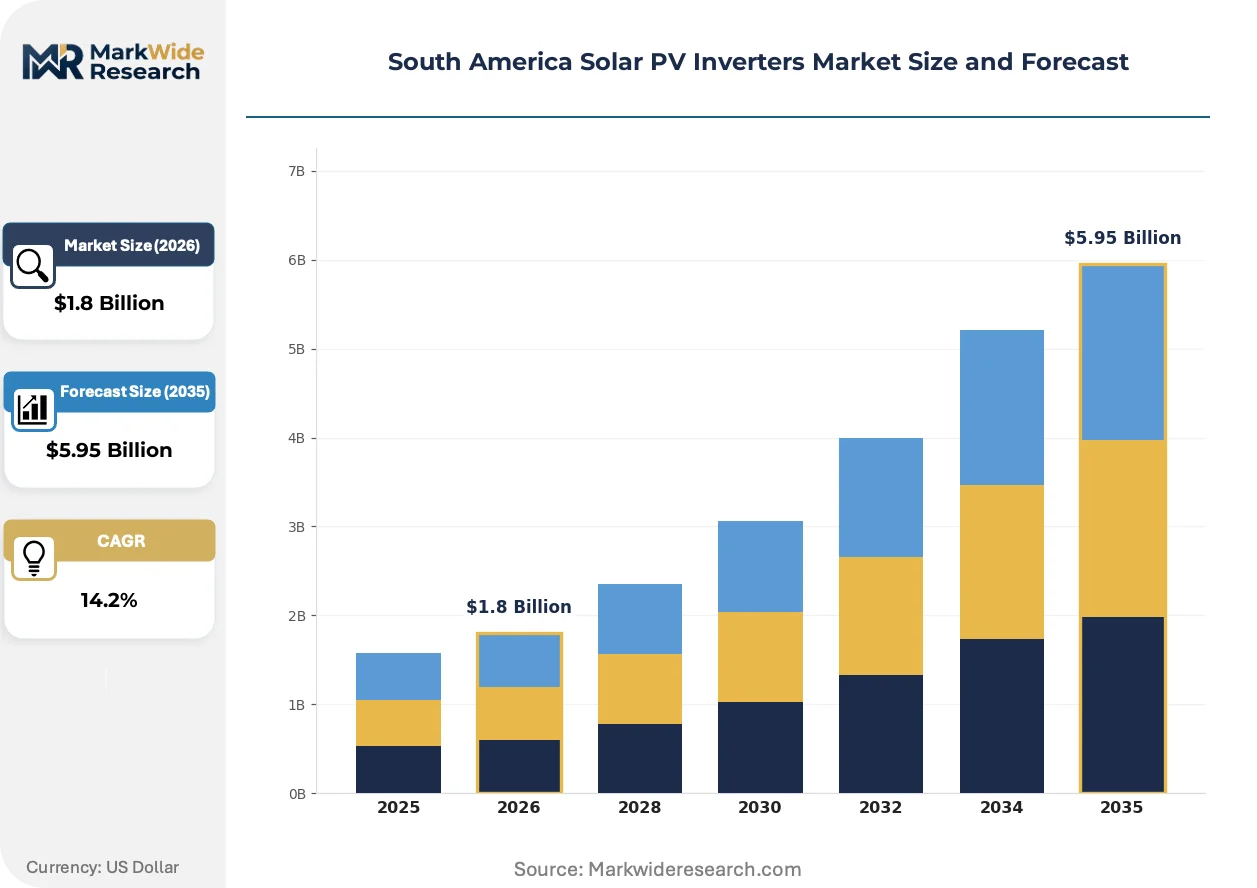
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Microinverters, Central Inverters, Power Optimizers Technology: Grid-Tied, Off-Grid, Hybrid, Battery Storage End User: Residential, Commercial, Industrial, Utility Installation Type: Rooftop, Ground-Mounted, Building-Integrated, Community |
| Companies Covered | Enphase Energy Inc., Growatt New Energy Co. Ltd., Ginlong (Solis) Technologies, Fronius International GmbH, ABB Ltd., Sungrow Power Supply Co. Ltd., SolarEdge Technologies Inc., Ingeteam, SMA Solar Technology AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Solar PV Inverters Market Evolving Landscape
Inverter architecture is fragmenting across voltage classes and integration levels as distributed generation scales collide with utility-scale procurement concentration. Three distinct trajectories are reshaping product development priorities and supplier competitive positioning.
String inverter platforms are modularizing from traditional 3-10 kilowatt residential units into 100-150 kilowatt commercial blocks that reduce balance-of-system costs. Large rooftop developers in Brazil's industrial zones are adopting these higher-capacity string configurations to minimize combiner boxes and DC cabling runs. This shift is modularizing project engineering workflows and compressing installation labor requirements.
Chile's SEC electrical safety regulations under Law 21.118 are mandating enhanced anti-islanding protection and grid support functions for all new installations. The policy requires firmware upgrades and hardware modifications that increase bill-of-materials costs for grid-tied inverters. Utility-scale developers are responding by specifying central inverters with integrated grid stabilization capabilities.
Service unbundling is separating hardware supply from commissioning and long-term maintenance contracts. Brazilian commercial installers are negotiating direct O&M agreements with inverter manufacturers rather than bundled EPC arrangements. This pattern is most visible in São Paulo's distributed generation market where project financiers demand performance guarantees independent of installation contractors.
South America Solar PV Inverters Market Segmentation
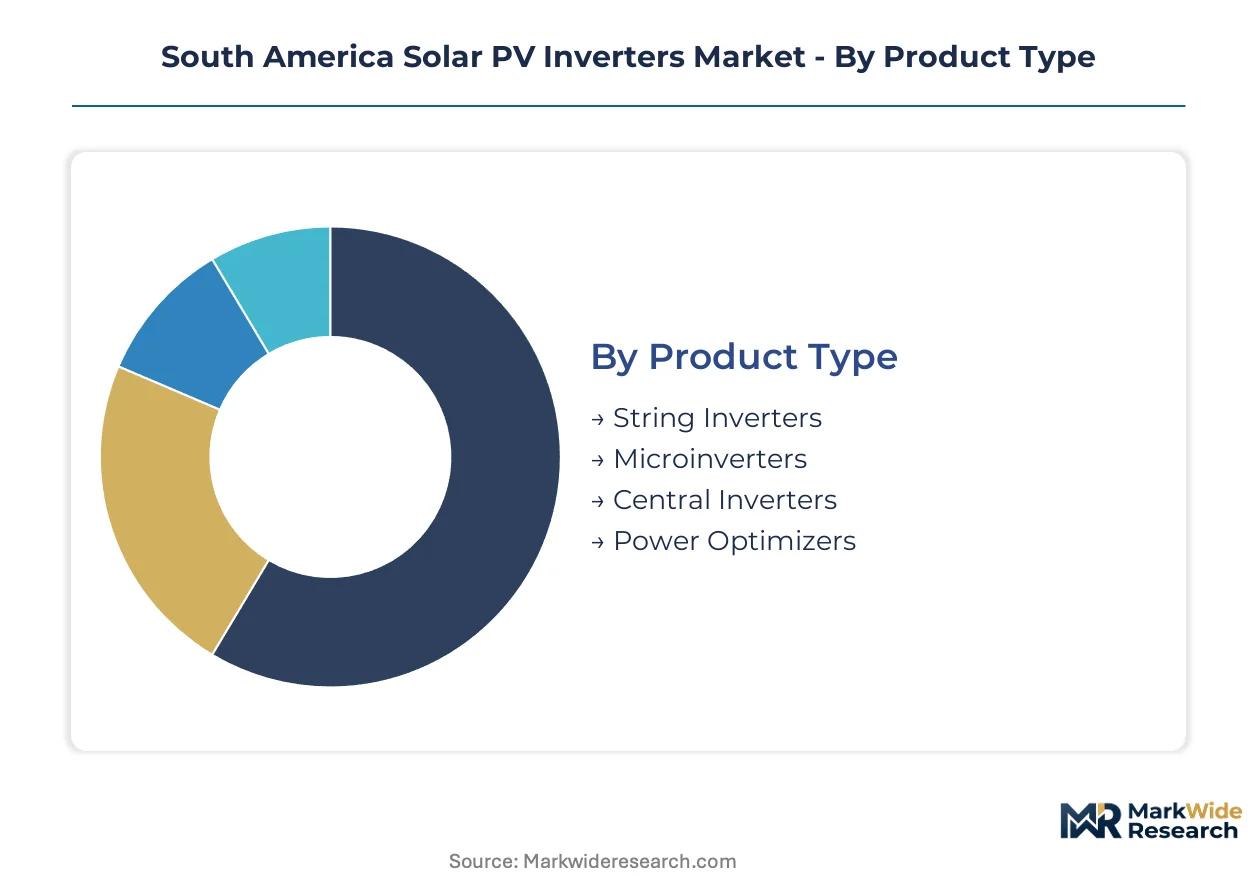
Inverter procurement across South America fragments sharply across voltage classes and application scales, with certification requirements from ANVISA, SEC, and IRAM forcing product variant proliferation that strains regional supply chains.
Product Type:
ANVISA electrical safety certification applies universally, yet ABNT NBR grid synchronization standards impose stricter firmware validation on grid-tied architectures than off-grid alternatives.
- String Inverters:Modular platforms operating at 98.5%+ conversion efficiency with 3-150 kilowatt power bands. Demand concentrates in São Paulo's commercial rooftop segment where flexible string sizing reduces DC cabling costs. Brazil's net metering framework accelerates procurement for single-phase residential units in Minas Gerais.
- Central Inverters:High-capacity units exceeding 2.5 megawatts with 1500-volt DC architecture optimized for utility-scale parks. Deployments cluster in Brazil's Northeast—Bahia and Piauí—where gigawatt-scale projects require centralized power conversion with integrated medium-voltage transformers.
- Microinverters:Module-level power electronics with per-panel maximum power point tracking for shaded or complex roof geometries. Residential prosumers in Santiago's hillside neighborhoods favor distributed conversion architectures.
- Power Optimizers:DC-to-DC conditioning units paired with string inverters for module-level monitoring without full microinverter cost. Commercial installations in Colombia's Andean region adopt hybrid architectures.
Leading the category by volume: String Inverters. Growing fastest: Central Inverters.
Technology:
Cost tier differentiation separates premium hybrid systems with lithium-ion integration from baseline grid-tied units serving pure export economics.
- Grid-Tied:Synchronous inverters matching utility frequency with anti-islanding protection mandated under Chile's SEC Law 21.118. Brazil's ANEEL net metering regulations drive residential adoption across Southeast states.
- Off-Grid:Standalone systems with battery charging controllers for rural electrification. Remote mining operations in Peru's sierra and agricultural processing in Bolivia's lowlands create isolated demand pockets.
- Hybrid:Bidirectional power conversion enabling grid export, battery charging, and backup power from single hardware platform. Time-of-use tariffs in São Paulo and Santiago accelerate retrofit demand across existing distributed generation fleets.
- Battery Storage:Dedicated storage inverters with DC-coupled or AC-coupled architecture for lithium-ion systems. Utility-scale co-location projects in Chile's Atacama Desert specify 4-hour duration configurations.
Volume concentration: Grid-Tied. Steepest expansion trajectory: Hybrid.
End User:
Customer type determines procurement channel structure—residential flows through electrical distributors, utility-scale routes through direct manufacturer negotiation.
- Residential:Single-phase and small three-phase systems under 10 kilowatts. São Paulo's metropolitan zone anchors regional demand through net metering enrollment.
- Commercial:Mid-scale rooftop and carport installations from 30 kilowatts to 1 megawatt. Industrial zones in Minas Gerais and Rio de Janeiro favor 100+ kilowatt string configurations.
- Industrial:Large rooftop and behind-the-meter systems with power factor correction requirements. Food processing and textile manufacturers in Argentina's Córdoba province drive procurement.
- Utility:Front-of-meter solar parks requiring central inverters with medium-voltage step-up. Brazil's Northeast transmission corridors and Chile's northern desert host gigawatt-scale development.
Revenue concentration: Utility. Margin expansion: Commercial.
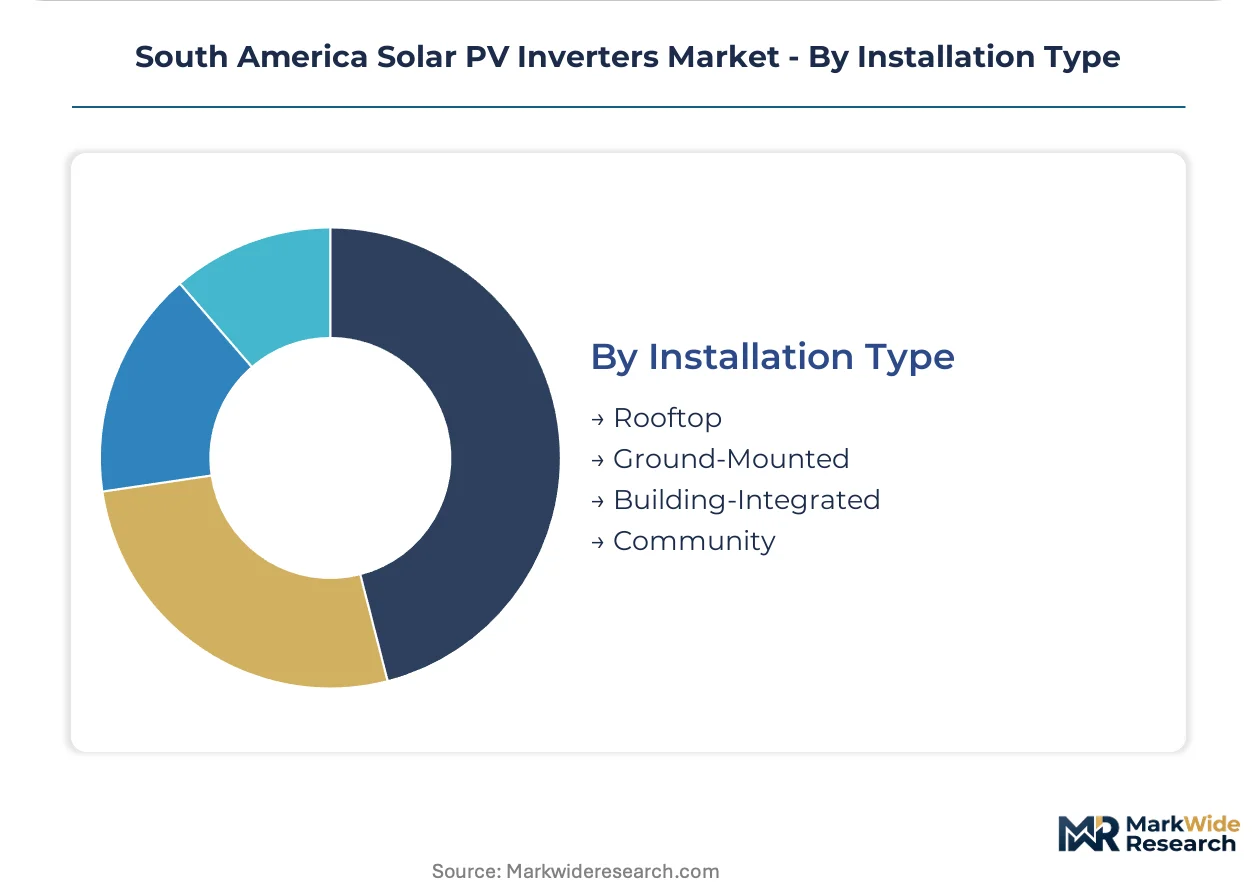
Installation Type:
Geography shapes hardware specification—rooftop density favors string modularity, ground-mounted scale rewards central inverter economics.
- Rooftop:Distributed generation on residential, commercial, and industrial building envelopes. São Paulo's urban fabric and Santiago's hillside residential zones dominate addressable volume.
- Ground-Mounted:Utility-scale arrays on dedicated land parcels with tracking systems. Brazil's Piaui and Bahia states offer flat terrain with high irradiance.
- Building-Integrated:PV modules as architectural elements requiring specialized inverter sizing for irregular electrical characteristics. Commercial developments in Buenos Aires test facade integration.
- Community:Shared solar arrays serving multiple subscribers through virtual net metering. Regulatory pilots in Colombia and Peru explore subscription-based models.
Installed capacity leader: Ground-Mounted. Emerging segment: Community.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil absorbs the dominant share of inverter procurement across South America, with Chile anchoring utility-scale demand and Argentina emerging as a localization opportunity under import substitution frameworks.
Brazil
Net metering enrollment in São Paulo and Minas Gerais accelerates residential string inverter procurement, while ANEEL's distributed generation regulations compress supplier qualification timelines. ANVISA certification protocols for electrical equipment impose multi-month approval windows that delay product launches. Bahia and Piauí in the Northeast corridor host gigawatt-scale ground-mounted arrays demanding 1500-volt central systems.
Chile
The Atacama Desert's irradiance concentration attracts utility-scale developers specifying high-capacity central inverters with integrated grid stabilization. SEC regulations under Law 21.118 mandate enhanced anti-islanding protection and frequency response capabilities for all grid-tied installations. Northern transmission constraints limit project energization regardless of hardware availability.
Argentina
CNEA's renewable energy auction mechanisms and import substitution policies create assembly localization incentives for Mercosur market access. The national electrical safety regulator enforces IRAM standards that diverge from Brazilian ABNT NBR protocols. Córdoba province's food processing and textile manufacturers drive behind-the-meter commercial demand.
Colombia
Andean region commercial installations adopt power optimizer architectures to manage module-level performance across variable terrain. The national mining and energy planning unit oversees grid interconnection protocols for distributed generation systems. Bogotá's urban fabric and Medellín's industrial zones concentrate rooftop development.
Peru
Remote mining operations in the sierra generate isolated demand for off-grid inverter systems with battery integration capabilities. The Ministry of Energy and Mines administers rural electrification programs targeting agricultural processing facilities. E-commerce platforms are bypassing traditional electrical distributor channels in Lima's metropolitan procurement.
South America Solar PV Inverters Market Competitive Landscape
Chinese producers anchor the scale-driven tier; European specialists hold premium positioning through grid-code expertise and service density. The supplier base fragments across voltage classes and application segments rather than consolidating around integrated platforms. Three archetypes dominate: vertically integrated power electronics conglomerates, pure-play inverter specialists with regional service networks, and module-level electronics providers targeting residential retrofit. Capacity expansion and firmware localization represent the dominant competitive vectors as certification requirements harden.
Within the utility-scale central inverter tier, Sungrow Power Supply Co. Ltd. and SMA Solar Technology AG exemplify divergent geographic anchoring strategies. Enphase Energy Inc. occupies the module-level power electronics position. Chinese-origin suppliers concentrate on cost-engineered string and central platforms for price-sensitive procurement in Brazil's Northeast. European GmbH and AG structures emphasize firmware validation and long-term service contracting to defend margin position in Chile's grid-code-intensive environment.
| Leading Market Players |
|---|
| Enphase Energy Inc. |
| Growatt New Energy Co. Ltd. |
| Ginlong (Solis) Technologies |
| Fronius International GmbH |
| ABB Ltd. |
| Sungrow Power Supply Co. Ltd. |
| SolarEdge Technologies Inc. |
| Ingeteam |
| SMA Solar Technology AG |
| Others |
Value Network & Pricing Analysis
1500-volt DC architecture migration in utility-scale deployments simultaneously compresses balance-of-system costs and concentrates procurement power among gigawatt-scale project developers in Brazil's Northeast and Chile's Atacama corridor. This voltage-class transition rewards suppliers with scale manufacturing capabilities while squeezing margins for mid-tier competitors lacking high-capacity central inverter portfolios.
Pricing Analysis
Volume concentration in utility-scale tenders compresses per-watt pricing for central inverters, while residential string units in São Paulo and Minas Gerais retain modest margin buffers. Three-tier pricing structure across premium European firmware-validated systems, mid-tier Chinese scale platforms, and economy-grade regional assemblers reflects certification grade and after-sales service bundling. Pricing pressure stems from IGBT and silicon carbide supply volatility among East Asian foundries. Utility developers exhibit lowest price sensitivity due to long-term PPA economics, while residential prosumers in Brazil's net metering segment demonstrate highest elasticity.
Supply Chain Analysis
Power semiconductor sourcing rests on Taiwanese and Chinese foundry capacity for IGBT modules and silicon carbide wafers, with Japanese and South Korean suppliers anchoring premium component tiers. Inverter assembly draws from Chinese and Brazilian manufacturing bases, with European facilities serving Chile's grid-code-intensive demand. Single-source vulnerability concentrates in advanced wide-bandgap semiconductor substrates. Distribution runs through electrical wholesalers for residential segments and direct manufacturer negotiation for utility-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as multi-certification burdens across ANVISA, SEC, and IRAM standards force sub-scale competitors toward exit or acquisition, favoring suppliers with captive firmware development and regional service density.
For Market Incumbents: Extend firmware localization capabilities to compress ANVISA approval timelines and defend against emerging Chinese competitors with Brazilian assembly operations. Anchor utility-scale relationships through integrated medium-voltage transformer offerings in Bahia and Piauí. Prioritize backward integration into power semiconductor sourcing to buffer East Asian supply volatility. For New Entrants and Emerging Players: E-commerce direct-to-installer channels in Colombia and Peru bypass traditional distributor markups and open white-space access. Target Argentina's CNEA auction pipeline before Mercosur localization requirements harden. Pursue hybrid inverter retrofit opportunities across Brazil's existing distributed generation fleet as time-of-use tariffs expand. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to power electronics conglomerates seeking Mercosur market access. Long-term viability favors suppliers with dual capability across string modularity and central inverter scale. Watch ANEEL regulatory adjustments to net metering caps as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Fast-Track | Accelerated approval timelines unlock inventory deployment ahead of competitors in Brazil's Northeast utility corridor. |
| Hybrid Inverter Platform Launch | Battery-ready architectures capture retrofit demand as São Paulo's time-of-use tariffs reshape residential economics. |
| Power Semiconductor Supply Agreement | Long-term IGBT and SiC sourcing contracts insulate margins from East Asian foundry volatility. |
| Argentina Assembly Localization | CNEA import substitution compliance secures Mercosur market access under evolving trade frameworks. |
| Direct Installer Digital Channel | Bypassing electrical distributor networks in Colombia and Peru captures margin compression from traditional channels. |
Research Methodology
Document review covered ANEEL regulatory filings, SEC electrical safety protocols, project development databases, and customs trade records, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and distributor procurement leads. Primary fieldwork across São Paulo, Santiago, and Buenos Aires validated secondary data on certification timelines and channel structures. Bottom-up project pipeline analysis triangulated against top-down manufacturer shipment disclosures.
Segment-level volume and value trajectories reflect modeling across product type, technology architecture, end-user scale, and installation configuration dimensions throughout the forecast period. CAGRs derive from regression analysis of historical procurement patterns and regulatory scenario weighting. Key inputs include ANEEL net metering enrollment curves, Chilean auction pipeline disclosures, and power semiconductor lead time indices.
The model holds under stable regulatory frameworks and intact transmission interconnection schedules; deviation in ANEEL policy adjustments or Northeast grid congestion would shift utility-scale deployment timing. Forecasts embed assumptions on certification timeline normalization and continued East Asian semiconductor supply access. A small set of named triggers—net metering cap revisions, IRAM-Brazil standards convergence, and lithium-ion battery cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Frameless Solar Panel Market