
 Argentina Solar Energy Market | 2026-2036
Argentina Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Solar Energy Market Analysis
Utility-scale procurement is decoupling from traditional fossil-fuel baseload planning as Argentine energy providers diversify supply portfolios. Trina Solar Co. Ltd. leverages its vertically integrated cell-to-module manufacturing to compete on landed cost in Buenos Aires port corridors. YPF Energia Eléctrica SA anchors its renewable pivot through captive project development tied to provincial offtake agreements. Genneia SA specializes in hybrid solar-wind configurations that navigate grid interconnection bottlenecks in Patagonia.
Argentina solar energy encompasses photovoltaic and concentrated solar power systems that convert electromagnetic radiation into electricity through semiconductor junctions or thermal cycles, with monocrystalline silicon modules achieving conversion efficiencies above 21% in high-irradiance zones. Photovoltaic technology dominates installed capacity due to modular scalability and declining module pricing, while bifacial modules capture incremental yield gains from albedo reflection in arid northwestern provinces. Utility-scale application leads capital deployment through RenovAr auction contracts, though rooftop installation is accelerating among commercial end users seeking tariff hedges against peso-denominated utility volatility.
Argentina's Secretariat of Energy and provincial regulators enforce grid codes and environmental impact standards that shape project timelines and equipment certification requirements. The RenovAr program and Law 27.424 on distributed generation create regulated revenue streams that reduce offtake risk for developers and financiers. Stakeholders must monitor foreign exchange access rules and local content thresholds that determine module import economics and EPC contractor selection.
Market Dynamics
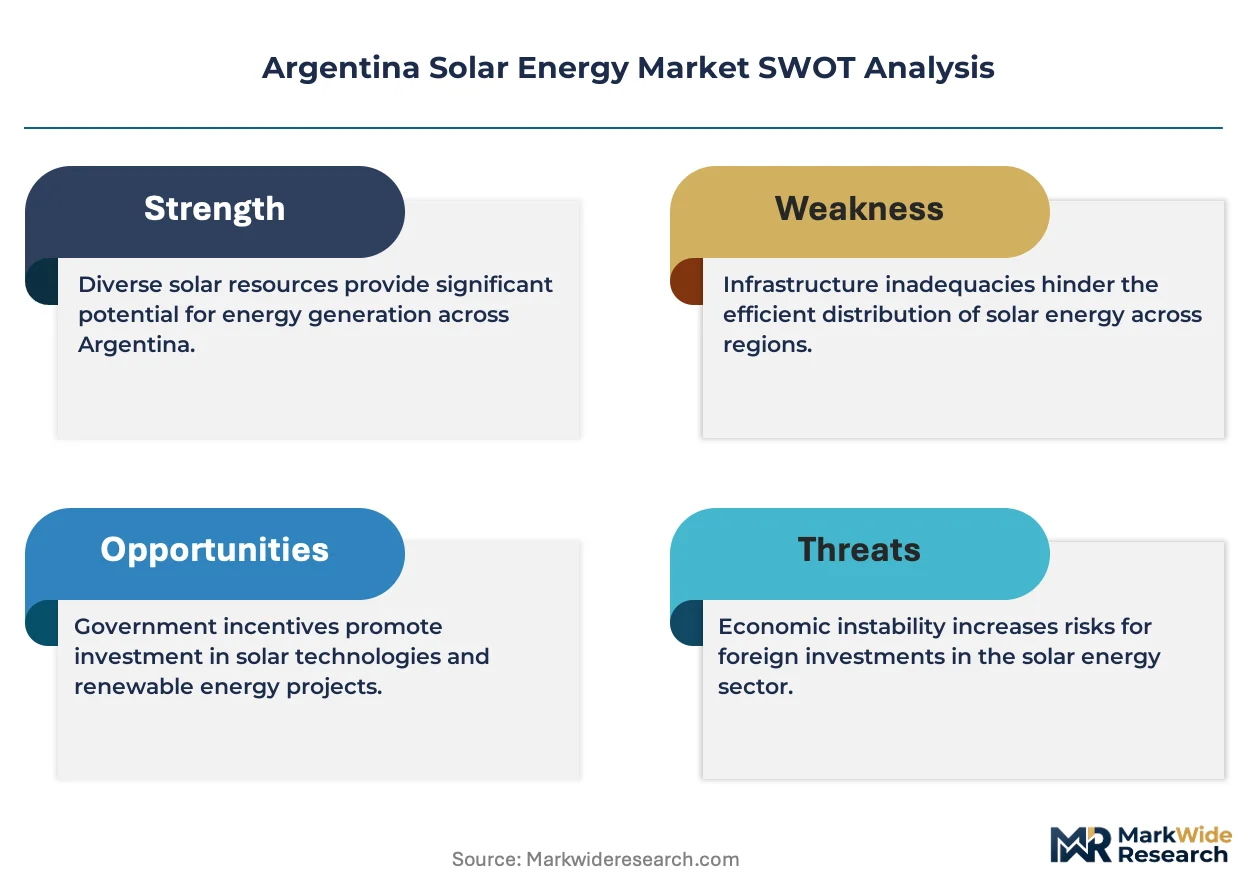
The RenovAr auction mechanism is decoupling utility-scale solar procurement from fossil-fuel baseload planning, while provincial permitting incentives in high-irradiance zones reshape capital deployment geography.
Growth Catalysts
- Law 27.424:Argentina's distributed generation framework enables commercial rooftops to sell surplus electricity into the grid, creating regulated revenue streams that reduce offtake risk for behind-the-meter developers.
- Mendoza Province Incentives:Accelerated environmental permitting and property tax abatements for solar projects concentrate developer capital in this high-albedo, high-irradiance corridor.
- Bifacial Module Adoption:Double-sided photovoltaic panels capture reflected radiation from arid northwestern terrain, delivering yield premiums that improve project IRRs without expanding land footprints.
Market Restraints
- Foreign Exchange Access Rules:Central Bank restrictions on dollar-denominated module imports create working capital squeezes for EPC contractors and delay equipment procurement timelines.
- Grid Interconnection Bottlenecks:Patagonia's sparse transmission infrastructure limits hybrid solar-wind project scaling despite excellent renewable resource quality.
- Local Content Thresholds:Domestic assembly mandates for photovoltaic modules raise landed costs when domestic cell manufacturing capacity remains underdeveloped.
Strategic Opportunities
- San Juan Province:Untapped high-irradiance zones with streamlined provincial permitting offer first-mover advantages for utility-scale developers ahead of auction saturation in Mendoza.
- Agricultural Solar Irrigation:Photovoltaic-powered water pumping for wine and olive growers creates captive demand that bypasses grid interconnection queues entirely.
- Hybrid Configuration Expansion:Coupling solar with lithium-ion storage or wind generation navigates grid constraints while capturing complementary generation profiles.
Industry Challenges
- Certification Timeline Compression:Secretariat of Energy grid code compliance and environmental impact approvals stretch project development cycles, requiring specialized regulatory affairs staffing.
- Technical Skill Scarcity:Shortages of certified electricians and O&M technicians trained on bifacial tracking systems constrain operational ramp-up for commissioned assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Solar Energy Market |
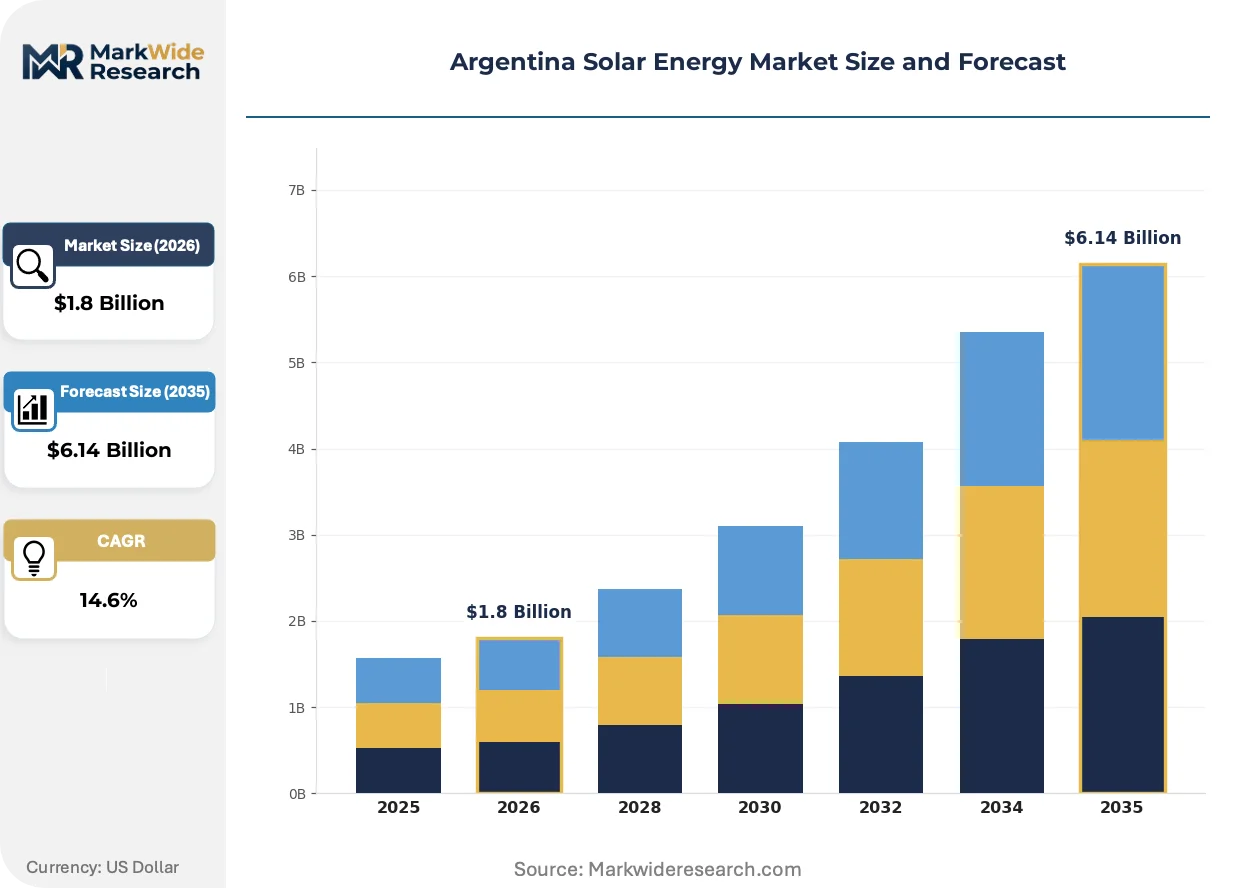
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Thin Film, Bifacial Modules Application: Residential, Commercial, Industrial, Utility-Scale End User: Homeowners, Businesses, Government, Energy Providers Installation Type: Rooftop, Ground-Mounted, Off-Grid, Hybrid Systems |
| Companies Covered | Trina Solar Co. Ltd., YPF Energia Eléctrica SA, Genneia SA, LONGi Green Energy Technology Co., Empresa Mendocina De Energías A.P.E.M, Canadian Solar Inc., JinkoSolar Holding Co. Ltd., Pampa Energia, 360 Energy SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Solar Energy Market Emerging Trajectories
Argentine solar deployment is pivoting from auction-dependent utility-scale models toward distributed commercial generation and hybrid configurations that circumvent infrastructure constraints.
Tracker-mounted bifacial arrays is automating yield optimization across high-albedo northwestern provinces. Large commercial offtakers in Buenos Aires industrial corridors are adopting these systems fastest, drawn by tariff hedge economics. This hardware shift is automating the displacement of fixed-tilt installations in new project pipelines, compressing LCOE spreads between premium and standard configurations.
RenovAr program refinements now prioritize hybrid solar-wind and solar-storage bids over pure-play photovoltaic submissions. The Secretariat of Energy's auction design changes reward dispatchable renewable capacity that addresses evening demand peaks. Patagonian developers with existing wind portfolios are restructuring submissions to capture these scoring premiums.
Commercial buyers are consolidating procurement through energy service companies rather than direct EPC contracting. Industrial users in Córdoba and Rosario manufacturing belts increasingly prefer ten-year power purchase agreements with guaranteed tariff escalators over capital-intensive asset ownership. This intermediation shift concentrates credit risk assessment with specialized financiers and squeezes margins for pure construction players.
Argentina Solar Energy Market Segmentation
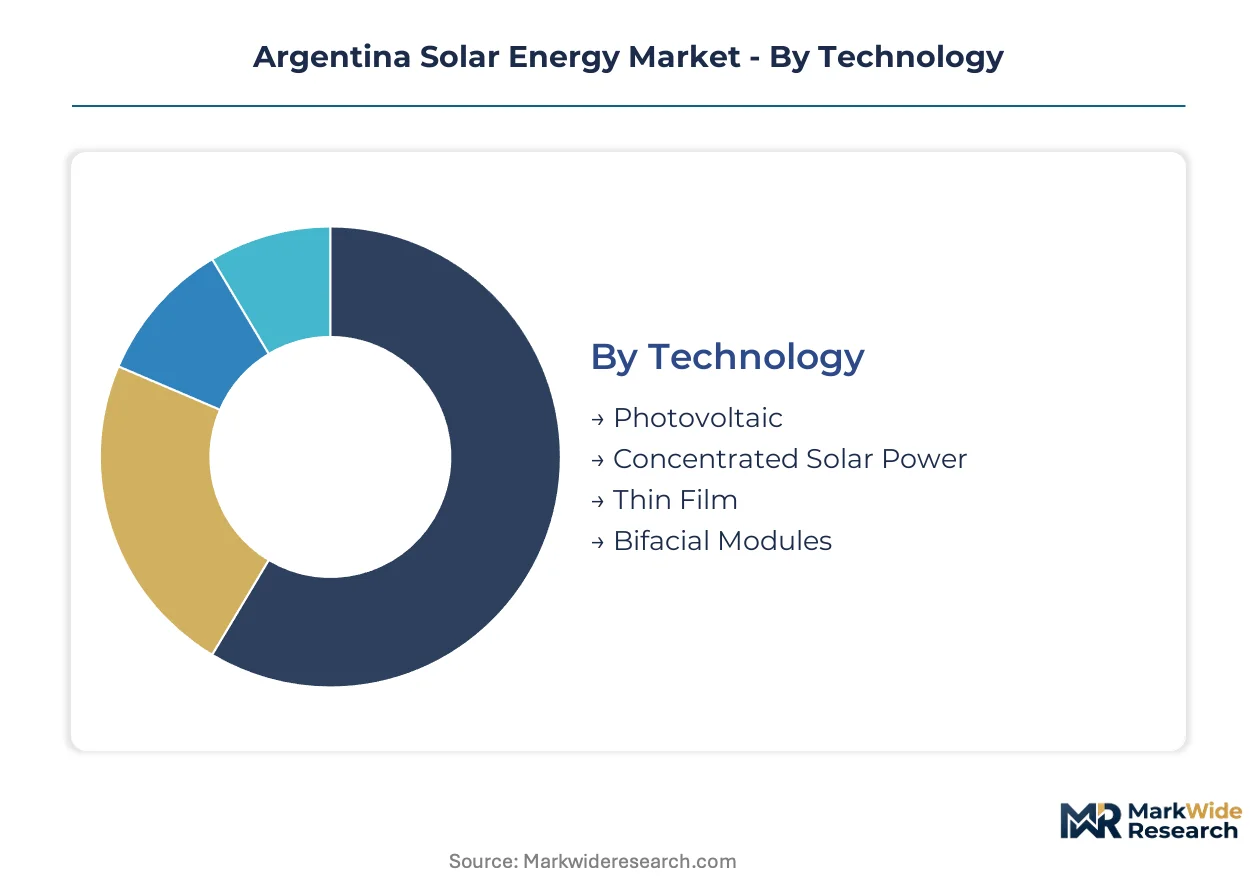
Argentina's solar market segments reflect divergent capital intensity and regulatory exposure across technologies and customer types. Procurement patterns in each category trace distinct paths through RenovAr auctions, provincial permitting regimes, and foreign exchange access constraints.
Technology:
Module conversion efficiency and manufacturing standardization create a clear premium-to-economy spectrum across photovoltaic technologies.
- Photovoltaic:Crystalline silicon cells dominate installed capacity through modular scalability and declining unit economics. Demand clusters in Mendoza and San Juan provinces where high irradiance maximizes capacity factors for monocrystalline deployments.
- Concentrated Solar Power:Thermal storage integration enables dispatchable renewable generation suited to evening demand peaks. Deployment concentrates where provincial regulators prioritize grid stability over pure capacity additions.
- Thin Film:Cadmium-telluride and CIGS technologies occupy niche applications with superior temperature coefficients in arid northwestern zones.
- Bifacial Modules:Double-sided panels capture albedo reflection from high-albedo terrain, delivering yield premiums without land footprint expansion.
Most installed capacity flows through Photovoltaic. Expansion is steepest in Bifacial Modules.
Application:
Project scale determines revenue model structure, from net-metering residential tariffs to long-term auction contracts.
- Utility-Scale:RenovAr auction mechanisms anchor capital deployment through 15-20 year power purchase agreements with guaranteed dollar-indexed revenue streams. Projects above 10 MW concentrate in Mendoza and San Juan corridors with streamlined provincial environmental permitting.
- Commercial:Behind-the-meter installations hedge against peso-denominated tariff volatility for industrial users in Córdoba and Rosario manufacturing belts. Law 27.424 net-metering provisions reduce offtake risk by enabling surplus electricity sales.
- Residential:Distributed generation frameworks unlock rooftop deployment for homeowners seeking energy cost stabilization.
- Industrial:Captive solar irrigation systems for wine and olive growers bypass grid interconnection queues entirely.
Capital deployment tilts toward Utility-Scale through auction dependence. Commercial applications are climbing fastest as tariff hedge economics improve.
End User:
Customer sophistication and balance sheet strength segment procurement risk profiles across the market.
- Energy Providers:YPF Energia Eléctrica SA and Genneia SA anchor utility-scale procurement through RenovAr auction participation and provincial offtake agreements. Their renewable pivots reshape generation portfolios away from fossil-fuel baseload planning.
- Businesses:Manufacturing and agricultural enterprises in Buenos Aires industrial corridors adopt ten-year power purchase agreements with guaranteed tariff escalators over direct asset ownership.
- Government:Provincial energy agencies in Mendoza and San Juan accelerate permitting timelines and property tax abatements to attract developer capital.
- Homeowners:Residential adopters leverage distributed generation law provisions for net-metering arrangements.
Energy Providers command the dominant share of auction-allocated capacity. Business segment procurement is expanding most quickly through energy service company intermediation.
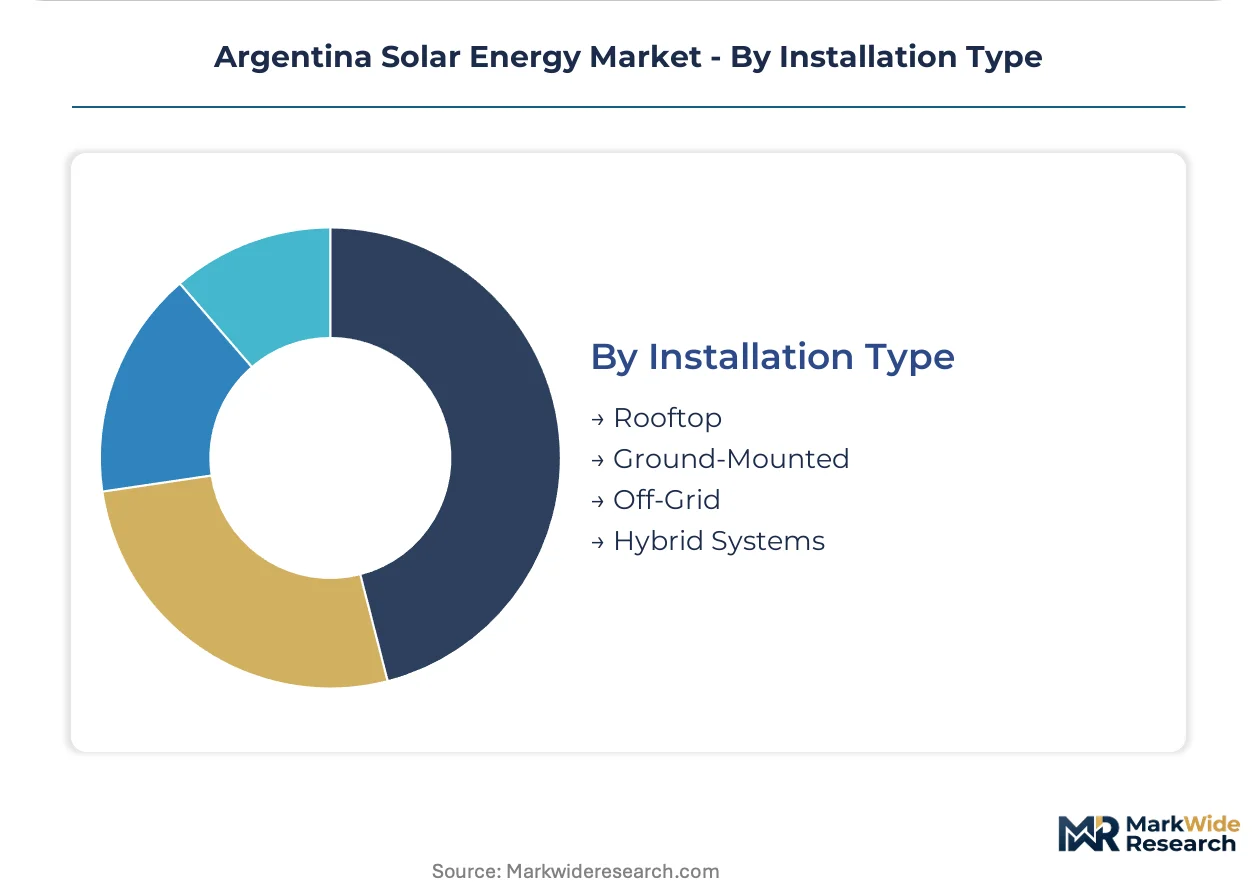
Installation Type:
Site constraints and grid access availability determine technical configuration choices.
- Ground-Mounted:Tracker-mounted arrays dominate utility-scale deployment across high-albedo northwestern provinces, automating yield optimization through single-axis tracking systems.
- Rooftop:Commercial and residential installations accelerate in Buenos Aires and Córdoba urban corridors where land scarcity precludes ground-mounted alternatives.
- Hybrid Systems:Solar-wind and solar-storage configurations navigate Patagonian grid interconnection bottlenecks while capturing complementary generation profiles.
- Off-Grid:Standalone photovoltaic-powered water pumping serves agricultural irrigation demand in remote wine-growing regions without transmission infrastructure.
Ground-Mounted systems absorb the majority of utility-scale capital. Hybrid Systems are gaining share fastest as RenovAr auction scoring rewards dispatchable renewable capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's solar development concentrates where provincial regulators have compressed permitting timelines and federal auction mechanisms guarantee dollar-indexed revenue streams. Developers migrate capital toward these regulatory-arbitrage corridors, bypassing jurisdictions with slower environmental review cycles.
Mendoza Province
High-albedo terrain and accelerated environmental permitting attract utility-scale developers seeking RenovAr auction qualification. The provincial government extends property tax abatements for projects above 10 MW. Tracker-mounted bifacial arrays dominate new capacity in the Uco Valley wine corridor.
San Juan Province
Untapped irradiance zones and streamlined provincial permitting offer first-mover positioning ahead of Mendoza saturation. The Secretariat of Energy's grid code enforcement remains consistent with federal standards. Ground-mounted installations concentrate in the Calingasta and Ullúm departments where land availability exceeds competing agricultural claims.
Buenos Aires Province
Industrial load centers in La Plata and Campana drive commercial rooftop demand for tariff hedge economics. Law 27.424 net-metering provisions enable surplus electricity sales for manufacturing facilities. Energy service companies intermediate ten-year power purchase agreements with guaranteed escalators for automotive and food processing plants.
Córdoba Province
Rosario manufacturing belt demand centers on behind-the-meter installations hedging peso-denominated utility volatility. The provincial energy agency coordinates with federal regulators on distributed generation interconnection standards. Commercial offtakers prefer power purchase agreement structures over direct asset ownership.
Patagonia Region
Sparse transmission infrastructure limits pure-play solar scaling despite excellent renewable resource quality. Provincial regulators in Neuquén and Río Negro prioritize hybrid solar-wind configurations that navigate grid interconnection bottlenecks. Developers with existing wind portfolios restructure auction submissions to capture RenovAr scoring premiums for dispatchable capacity.
Argentina Solar Energy Market Vendor Landscape
Strategic partnerships dominate the current landscape as module suppliers align with provincial offtakers and EPC contractors. The vendor base organizes around three distinct tiers: vertically integrated Chinese manufacturers with port-access advantages, Argentine energy incumbents pivoting from fossil-fuel portfolios, and specialized hybrid developers navigating Patagonian grid constraints. M&A activity and long-term supply agreements represent the primary competitive moves, with auction qualification driving alliance formation.
Among Chinese module manufacturers with landed cost advantages in Buenos Aires port corridors, Trina Solar Co. Ltd., LONGi Green Energy Technology Co., and JinkoSolar Holding Co. Ltd. exemplify the scale-driven archetype competing on conversion efficiency and manufacturing standardization. Within the Argentine incumbent tier, YPF Energia Eléctrica SA and Genneia SA occupy positions tied to provincial offtake agreements and captive project development. Canadian Solar Inc. represents the North American-Asian hybrid model with established logistics networks serving auction-dependent procurement cycles.
| Leading Market Players |
|---|
| Trina Solar Co. Ltd. |
| YPF Energia Eléctrica SA |
| Genneia SA |
| LONGi Green Energy Technology Co. |
| Empresa Mendocina De Energías A.P.E.M |
| Canadian Solar Inc. |
| JinkoSolar Holding Co. Ltd. |
| Pampa Energia |
| 360 Energy SA |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed provincial energy agencies in Mendoza and San Juan anchor project financing structures that compress EPC contractor margins while securing long-term offtake commitments. This ownership pattern concentrates pricing power with auction-qualified developers who can absorb Central Bank foreign exchange volatility, forcing module importers into peso-hedged contracting terms that raise landed costs for unqualified competitors.
Pricing Analysis
Distributor margin compression runs through Buenos Aires port corridors where vertically integrated Chinese manufacturers bypass traditional wholesale channels entirely. Project-based long-term offtake contracts dominate utility-scale procurement through RenovAr auction mechanisms, while commercial rooftop installations price on tariff-hedge value rather than pure generation economics. Price differentiation rests on module efficiency tier and provincial permitting speed rather than brand premium, with bifacial tracking systems commanding yield-based premiums in high-albedo zones. Cost compression in fixed-tilt installations is intensifying because tracker-mounted arrays automate yield gains without proportional land cost increases, making industrial offtakers in Córdoba the most price-sensitive segment while Mendoza utility-scale developers prioritize IRR certainty over upfront capital minimization.
Supply Chain Analysis
Regional distribution centers in Buenos Aires port zones operate on hub-and-spoke patterns that consolidate module imports before provincial forwarding to Mendoza and San Juan project sites. Manufacturing concentration draws from China, Vietnam, and Malaysia for crystalline silicon cells, with polysilicon and silver paste as critical input dependencies. Single-source vulnerability concentrates in inverter supply where European and Chinese producers dominate without qualified domestic alternatives. Distribution runs through EPC contractor networks that integrate procurement with installation crews to navigate Central Bank dollar-access restrictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's solar market compounds steadily as provincial regulators compete to attract auction-qualified capital through permitting acceleration and tax abatements. The RenovAr program's dollar-indexed revenue streams provide cash flow predictability that supports long-dated project finance.
For Market Incumbents: Extend hybrid configuration capabilities to capture RenovAr auction scoring premiums for dispatchable capacity, while consolidating relationships with provincial energy agencies ahead of Mendoza permitting saturation. YPF Energia Eléctrica SA and Genneia SA should deepen backward integration into energy storage to defend margins against pure-play photovoltaic developers facing interconnection queue delays. Priority investment in bifacial tracking O&M technician training addresses operational ramp-up bottlenecks that constrain asset utilization. For New Entrants and Emerging Players: Law 27.424 in Argentina opens a window for agricultural solar irrigation specialists to bypass grid interconnection queues entirely through captive demand structures. San Juan Province's untapped high-irradiance zones offer the most penetrable geography for first-mover utility-scale positioning ahead of Mendoza auction saturation. Energy service company intermediation for Córdoba and Rosario manufacturing belts provides the clearest go-to-market angle, as industrial offtakers prefer ten-year power purchase agreements with guaranteed escalators over direct asset ownership. For Investors and Strategic Acquirers: Provincial energy incumbents with existing provincial offtake agreements are the most active acquirer in this space, seeking to consolidate auction-allocated pipelines. The investment horizon favors developers with demonstrated RenovAr qualification track records and hybrid project execution capability. Acquisition targets should display secured land access in San Juan or Mendoza with environmental permits in process. Watch for Central Bank foreign exchange access rule relaxation as the signal indicating working capital squeeze abatement and accelerated equipment procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Configuration Expansion | Captures RenovAr auction scoring premiums for dispatchable evening peak capacity in Patagonia. |
| Provincial Permitting Acceleration | Compresses project development cycles in San Juan to secure first-mover positioning ahead of Mendoza saturation. |
| Energy Service Company Intermediation | Concentrates credit risk assessment with specialized financiers serving Córdoba industrial manufacturing belts. |
| Bifacial Module Technology Licensing | Enables yield optimization from high-albedo terrain without expanding land footprints in northwestern provinces. |
| Agricultural Solar Irrigation Deployment | Bypasses grid interconnection bottlenecks through captive demand from wine and olive growers in Uco Valley. |
Methodological Framework
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators grounded qualitative assessments of RenovAr auction mechanics and provincial permitting timelines. Secondary validation drew from Secretariat of Energy regulatory filings, provincial energy agency disclosures, Central Bank foreign exchange circulars, and project development databases tracking auction awards. Bottom-up capacity installation estimates triangulated against top-down addressable market calculations derived from irradiance mapping and transmission infrastructure assessments.
Segmented outputs across the projection horizon reflect technology bifurcation between photovoltaic and concentrated solar power, application scale from residential rooftop to utility-scale auction contracts, and regional regulatory clusters spanning Mendoza, San Juan, Buenos Aires, Córdoba, and Patagonian provinces. CAGRs were derived from econometric modeling of module cost decline curves, auction contract pricing trends, and provincial incentive program sustainability. Forecast inputs incorporated Central Bank dollar-access rule scenarios and grid interconnection queue clearance rates.
Revisions become necessary when foreign exchange access restrictions tighten beyond current levels, provincial permitting timelines extend due to environmental review backlogs, or transmission infrastructure investment lags renewable capacity additions in Patagonia. Forecasts reflect documented assumptions regarding RenovAr program continuity and provincial tax abatement renewal patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
AR Photovoltaic Glass Market