
 Asia-Pacific Rooftop Solar Market | 2026-2036
Asia-Pacific Rooftop Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Rooftop Solar Market Outlook
Commercial warehouse and logistics rooftop deployment is hardening as the fastest-expanding vertical across the Asia-Pacific. Trina Solar Limited leverages its high-efficiency monocrystalline module portfolio to anchor large-format projects across China's industrial belt. JinkoSolar Holding Co., Ltd. competes aggressively on manufacturing scale, sustaining cost leadership in utility-adjacent distributed installations. Sungrow Power Supply Co. Ltd differentiates through string inverter integration, dominating the power electronics layer for commercial rooftops in Southeast Asia.
Asia-Pacific rooftop solar encompasses photovoltaic systems mounted on building roofs for on-site electricity generation, typically employing silicon-based cells with conversion efficiencies ranging from 19% to 23% in commercial modules and grid-tied inverters synchronizing output with utility frequency. These installations offset retail electricity purchases for commercial and industrial facilities while reducing transmission losses through distributed generation proximity to load centers. Monocrystalline technology leads installed capacity due to superior space efficiency on constrained roof areas, while bifacial modules represent the fastest-growing technology segment as albedo-reflected gains improve yields across Australia's high-irradiance commercial zones. Grid-connected installations command the dominant share of new capacity, though hybrid configurations with battery storage are capturing margin pools as time-of-use arbitrage economics improve.
India's Ministry of New and Renewable Energy administers rooftop solar subsidies through state nodal agencies, while China's National Energy Agency sets provincial distributed generation quotas that directly shape developer pipelines. Australia's Clean Energy Regulator operates the Small-scale Renewable Energy Scheme, creating certificate-based revenue streams that reduce payback periods for commercial adopters. Japan's METI enforces grid interconnection standards and feed-in tariff transitions that now favor self-consumption models over full export. Stakeholders must monitor evolving net metering revisions across key states and provinces, as these tariff structures determine whether distributed solar retains economic advantage against centralized renewable procurement.
Market Dynamics
Provincial distributed generation quotas from China's National Energy Agency and India's PLI scheme for module manufacturing are compressing project timelines while bifacial module adoption accelerates yield optimization across Australia's commercial zones.
Growth Catalysts
- India's PLI Scheme:Production-linked incentives for domestic solar module manufacturing reduce import dependency and lower procurement costs for commercial installers across Maharashtra and Gujarat.
- Commercial Warehouse Deployment:Southeast Asia's logistics real estate sector is hardening rooftop photovoltaic specifications into standard lease agreements for fulfillment centers.
- Small-scale Renewable Energy Scheme:Australia's certificate-based revenue mechanism shortens payback periods for commercial adopters in Queensland and New South Wales.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang-based ingot production creates geographic concentration risk that amplifies input cost volatility for module assemblers.
- Grid Interconnection Standards:Japan's METI-enforced technical requirements for frequency synchronization create regulatory friction for distributed battery-hybrid configurations.
- Roof Structural Limitations:Load-bearing constraints on aging industrial stock in Vietnam's northern manufacturing belt restrict monocrystalline module density.
Strategic Opportunities
- Philippines Archipelago Deployment:Island grids with diesel dependence offer underpenetrated markets where solar-plus-storage displaces liquid fuel generation.
- String Inverter Integration:Power electronics convergence with module-level power electronics enables granular monitoring for commercial portfolios.
- Indonesia Net Metering Expansion:Pending regulatory tailwinds for distributed generation tariffs would unlock self-consumption economics for Java-based manufacturing.
Industry Challenges
- Electrical Engineering Talent Gap:Shortage of certified grid interconnection specialists delays commercial project commissioning across India's state nodal agencies.
- Hybrid System Integration Complexity:Battery inverter compatibility with legacy string configurations requires re-engineering of balance-of-system designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Rooftop Solar Market |
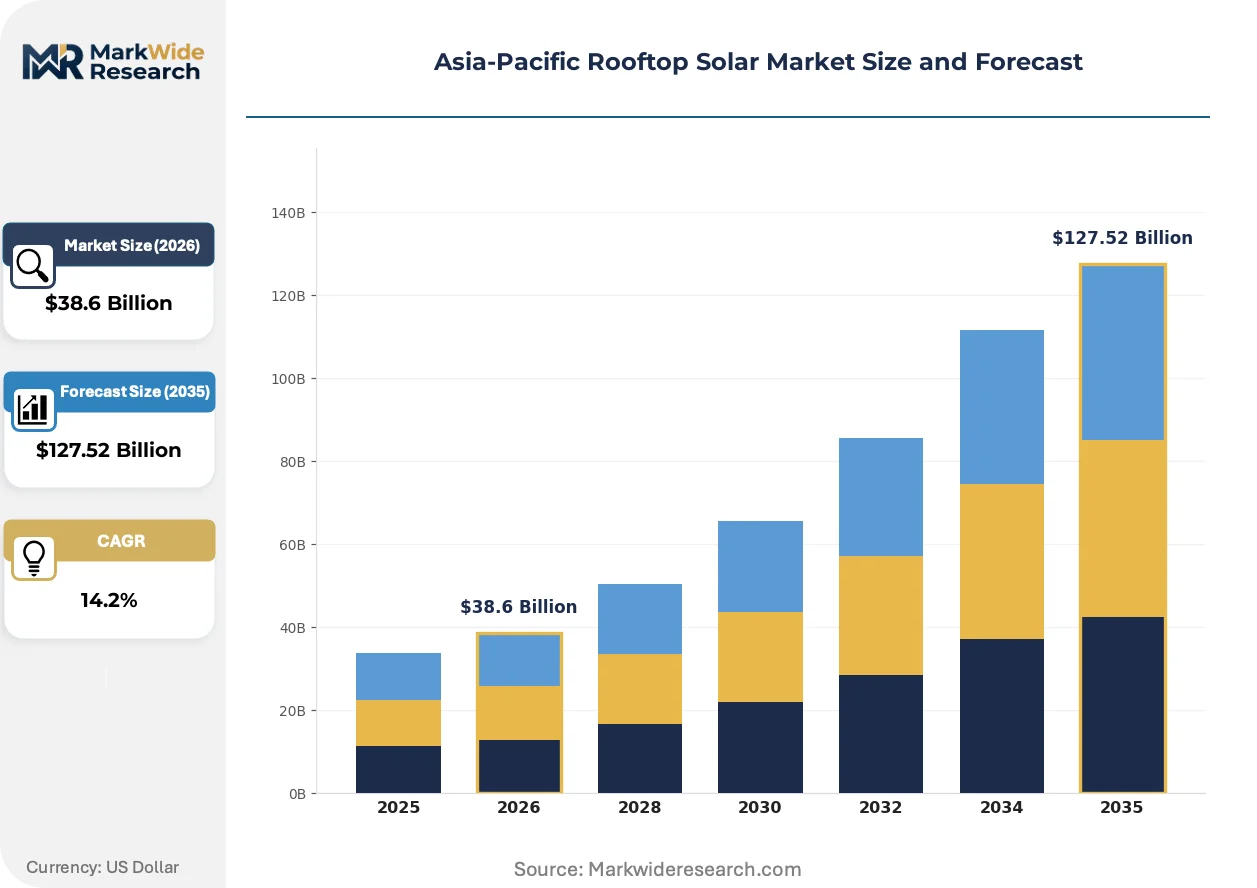
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial End User: Residential, Commercial, Industrial, Government Installation Type: Standalone, Grid-Connected, Off-Grid, Hybrid Inverter Type: String Inverter, Micro Inverter, Central Inverter, Power Optimizer |
| Companies Covered | Trina Solar Limited, Huawei Technologies Co., Ltd., JA Solar Holdings Co., Ltd., Suntech Power Holdings Co., Ltd., Tata Power Solar Systems Ltd, JinkoSolar Holding Co., Ltd., Sungrow Power Supply Co. Ltd, Yingli Green Energy Holding Co., Ltd., Canadian Solar Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Rooftop Solar Market Strategic Shifts
Bifacial photovoltaic modules and hybrid storage configurations are compressing levelized cost thresholds while procurement patterns fragment across direct developer contracts and energy service company arrangements.
Bifacial monocrystalline modules capture albedo-reflected irradiance from concrete and membrane roofing surfaces, boosting nameplate yields. Australian commercial developers in Queensland's high-irradiance zones are specifying bifacial glass-glass constructions for warehouse portfolios. This technology is expanding into Southeast Asian markets where reflective industrial roofing materials amplify rear-side gains.
China's National Energy Agency provincial quotas mandate distributed generation targets that reshape developer pipelines. Industrial belt provinces face binding capacity obligations that accelerate rooftop deployment on manufacturing facilities. Commercial real estate in Jiangsu and Zhejiang is responding by embedding photovoltaic specifications into green building certification requirements.
Direct power purchase agreements with commercial offtakers are displacing traditional utility-mediated procurement for large-format rooftop installations. Energy service companies in India are aggregating portfolios of small commercial rooftops into single offtake contracts. This pattern is most visible in Gujarat's textile processing clusters where aggregated demand pools reduce transaction costs.
Asia-Pacific Rooftop Solar Market Segmentation
Asia-Pacific rooftop solar segmentation reveals how technology choices, end-use requirements, and grid integration strategies fragment procurement patterns across India's manufacturing belt, Australia's commercial zones, and Southeast Asia's logistics corridors. Understanding these divisions exposes where module suppliers, inverter manufacturers, and project developers capture margin pools.
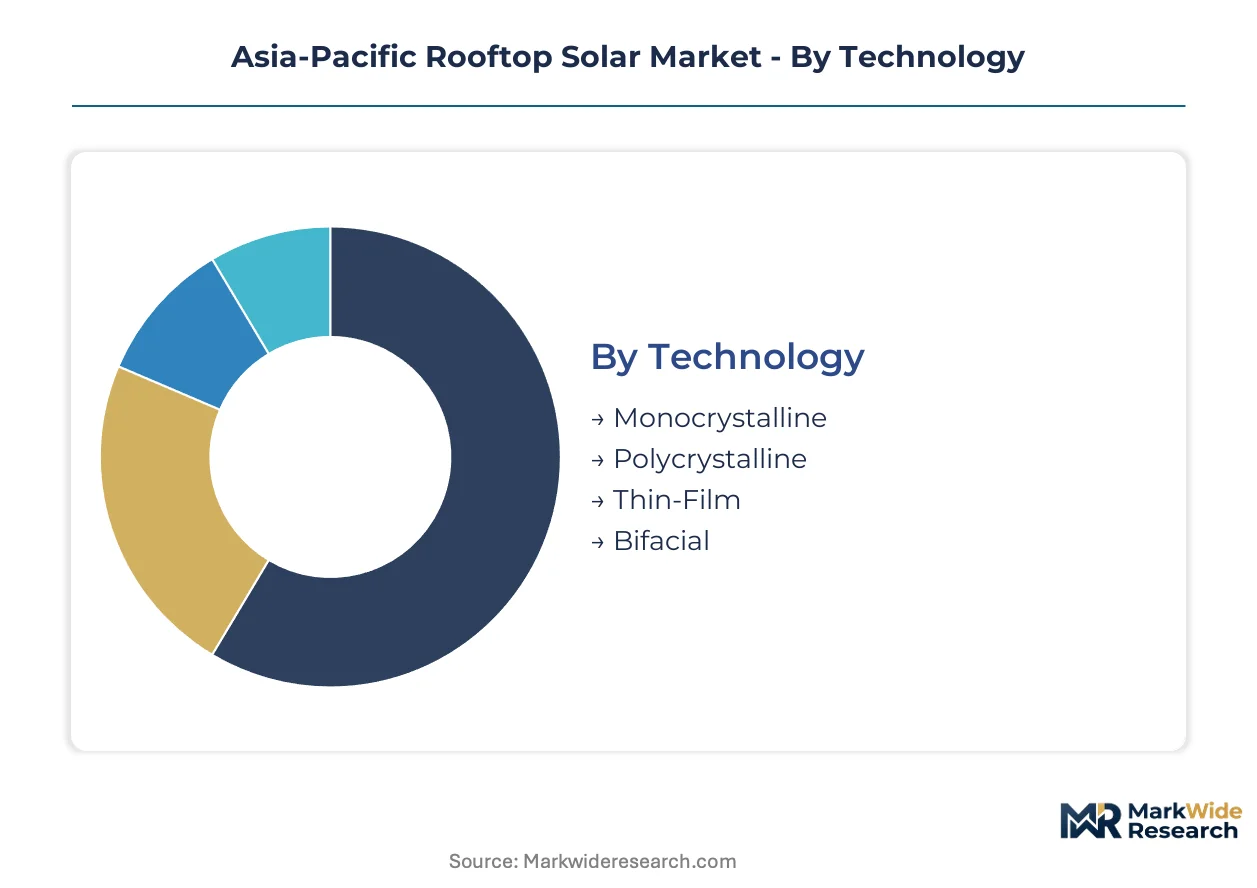
Technology:
Module technology concentration tilts heavily toward silicon-based architectures, with manufacturing scale and cell efficiency determining competitive position across China's industrial provinces and India's PLI-supported facilities.
- Monocrystalline:Single-crystal silicon cells deliver conversion efficiencies between 19% and 23% in commercial modules, making them the default specification for space-constrained industrial rooftops in Vietnam's northern manufacturing belt where load-bearing limits restrict array density.
- Bifacial:Glass-glass constructions capture albedo-reflected irradiance from concrete and membrane roofing surfaces, with Australian developers in Queensland's high-irradiance zones specifying these for warehouse portfolios where rear-side gains amplify total yield.
- Polycrystalline:Multi-crystal silicon cells trade efficiency for cost, finding residual demand in India's rural residential segment where price sensitivity outweighs space constraints.
- Thin-Film:Cadmium-telluride and CIGS technologies occupy niche applications with high temperature coefficients, deployed selectively across Southeast Asia's tropical commercial zones where heat degradation affects crystalline performance.
Today's leader: Monocrystalline. Tomorrow's challenger: Bifacial.
End User:
Demand concentration varies sharply by customer type, with procurement scale and offtake certainty shaping developer risk profiles and financing structures.
- Commercial:Warehouse and logistics real estate operators across Southeast Asia are hardening photovoltaic specifications into standard lease agreements, with fulfillment centers in Thailand and Indonesia driving aggregated portfolio deployments.
- Industrial:Manufacturing facilities in China's Jiangsu and Zhejiang provinces face binding distributed generation quotas from the National Energy Agency, accelerating rooftop deployment on textile processing and electronics assembly plants.
- Residential:Individual household installations concentrate in India's Gujarat and Maharashtra, where state nodal agencies administer MNRE subsidies and net metering frameworks determine payback economics.
- Government:Public building mandates in Australia's federal and state procurement channels create certificate-based revenue streams under the Small-scale Renewable Energy Scheme.
Commercial offtake dominates current pipelines; industrial quotas are expanding fastest.
Installation Type:
Grid integration architecture determines revenue model viability, with regulatory frameworks across Japan's METI jurisdiction and India's state electricity boards favoring specific configurations.
- Grid-Connected:Synchronized inverter output feeding utility networks commands dominant capacity share, though net metering revisions in key Indian states threaten economic advantage against centralized renewable procurement.
- Hybrid:Battery-coupled configurations capture margin pools as time-of-use arbitrage economics improve, with Japan's self-consumption tariff transitions and Australia's commercial demand charge management driving adoption.
- Standalone:Islanded systems without utility interconnection serve remote commercial loads across the Philippines archipelago where diesel displacement economics favor solar-plus-storage.
- Off-Grid:Fully autonomous installations persist in Indonesia's eastern islands beyond centralized grid extension, where microgrid developers aggregate agricultural processing and rural commercial demand.
Grid-connected retains volume leadership; hybrid configurations claim expanding margin share.
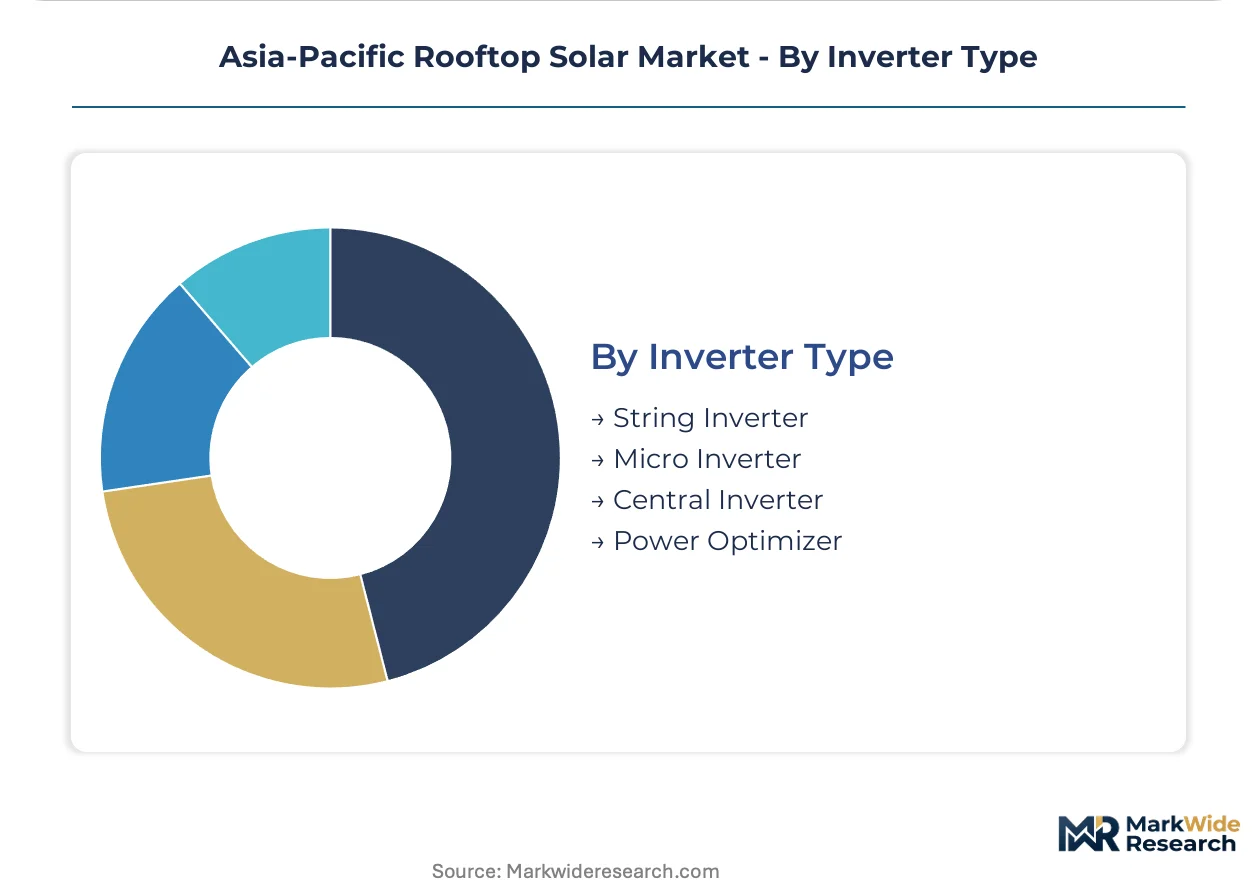
Inverter Type:
Power electronics selection shapes system monitoring granularity and fault tolerance, with string architectures dominating cost-sensitive commercial deployments while module-level electronics penetrate premium segments.
- String Inverter:Centralized DC-AC conversion units serve cost-optimized commercial rooftops across Southeast Asia, with Sungrow and Huawei capturing share through integrated power electronics and monitoring platforms.
- Micro Inverter:Module-level conversion maximizes yield from partially shaded or irregular roof geometries, finding adoption in Japan's dense urban commercial zones where building orientation varies.
- Central Inverter:Large-capacity units aggregate output from extensive commercial arrays, deployed across Australia's Queensland warehouse portfolios where uniform roof planes favor centralized architectures.
- Power Optimizer:Module-level DC conditioning with centralized inversion blends monitoring granularity with cost efficiency, gaining traction in India's aggregated commercial portfolios where Gujarat's textile clusters demand performance visibility.
String inverters anchor current procurement; power optimizers are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing module assembly capacity toward jurisdictions offering production-linked incentives and streamlined permitting, compressing procurement timelines for commercial developers across the Asia-Pacific.
China
Industrial belt provinces face binding distributed generation quotas from the National Energy Agency, mandating rooftop deployment on manufacturing facilities. The dual carbon goals framework accelerates photovoltaic specifications in green building certifications. Jiangsu and Zhejiang textile processing clusters embed solar requirements into lease agreements for export-oriented factories.
India
Maharashtra and Gujarat commercial installers leverage the PLI scheme to reduce module import dependency and capture domestic manufacturing scale. State nodal agencies administer MNRE subsidies while revising net metering frameworks. Textile processing clusters in Surat and Ahmedabad aggregate rooftop portfolios into single offtake contracts through energy service company arrangements.
Australia
Queensland and New South Wales warehouse developers specify bifacial glass-glass constructions to maximize albedo-reflected yields on concrete roofing surfaces. The Clean Energy Regulator's Small-scale Renewable Energy Scheme generates certificate-based revenue streams. High-irradiance commercial zones in Brisbane and Gold Coast drive hybrid battery configurations for demand charge management.
Vietnam
Northern manufacturing belt facilities confront load-bearing constraints on aging industrial stock that restrict monocrystalline array density. The national utility negotiates standardized power purchase terms for distributed commercial installations. Bac Ninh and Hai Phong electronics assembly plants accelerate rooftop deployment to offset retail electricity tariffs.
Japan
METI-enforced grid interconnection standards create regulatory friction for battery-hybrid configurations while favoring self-consumption models over full export. Feed-in tariff transitions redirect developer economics toward behind-the-meter optimization. Dense urban commercial zones in Osaka and Nagoya adopt module-level power electronics to maximize yield from irregular roof geometries.
Asia-Pacific Rooftop Solar Market Competitive Environment
Capacity expansion dominates the current landscape as module manufacturers scale ingot and wafer production to capture PLI-linked procurement pools. The vendor base stratifies across integrated silicon-to-module conglomerates, pure-play inverter specialists, and regional project developers. Three archetypes anchor competitive positioning: manufacturing-scale cost leaders, power electronics convergence players, and aggregated portfolio aggregators. Geographic expansion into Southeast Asian logistics corridors and technology licensing for bifacial glass-glass constructions represent the dominant competitive vectors.
Within the manufacturing-scale tier, Trina Solar Limited and JinkoSolar Holding Co., Ltd. exemplify integrated production architectures that anchor large-format project pipelines. Sungrow Power Supply Co. Ltd occupies a distinct position among power electronics specialists, converging string inverter platforms with module-level monitoring capabilities for commercial rooftop portfolios. These three entities represent the dominant competitive archetypes: silicon-to-module vertical integration, inverter-centric system integration, and software-layer differentiation.
| Leading Market Players |
|---|
| Trina Solar Limited |
| Huawei Technologies Co., Ltd. |
| JA Solar Holdings Co., Ltd. |
| Suntech Power Holdings Co., Ltd. |
| Tata Power Solar Systems Ltd |
| JinkoSolar Holding Co., Ltd. |
| Sungrow Power Supply Co. Ltd |
| Yingli Green Energy Holding Co., Ltd. |
| Canadian Solar Inc. |
| Others |
Value Chain & Pricing Dynamics
Certified grid interconnection specialists concentrated in India's Maharashtra and Gujarat industrial corridors command wage premiums that compress installer margins and widen spreads between premium turnkey deployments and economy-tier equipment-only transactions. Labor-cost differentials between these established solar manufacturing belts and Vietnam's emerging northern electronics assembly zone reshape procurement economics for commercial developers evaluating regional expansion.
Pricing Analysis
Distributor margins on string inverters and module-level power electronics absorb 12-18 percentage points before reaching commercial installers, while direct-to-OEM channels for utility-scale developers negotiate volume discounts off list. Three-tier pricing structure across premium efficiency-grade bifacial modules, standard monocrystalline portfolios, and residual polycrystalline inventory reflects certification tier and after-sales monitoring bundling. Cost compression in standard-tier modules is intensifying because China's provincial quota enforcement accelerates manufacturing scale. Industrial offtakers in Jiangsu and Zhejiang demonstrate lowest price sensitivity due to binding distributed generation mandates, while Vietnam's aging warehouse stock owners exhibit highest sensitivity as structural retrofit costs compound procurement decisions.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale commercial portfolio demand across Southeast Asia's logistics corridors, while regional distributors serve fragmented textile and electronics assembly installations. Polysilicon ingot production concentrates in Xinjiang and Inner Mongolia, with wafer slicing and cell assembly scaling across Jiangsu, Anhui, and India's PLI-supported Gujarat facilities. Raw material dependencies center on metallurgical-grade silicon, silver paste for cell metallization, and aluminum framing extrusions. Single-source vulnerability in Xinjiang-based polysilicon creates tariff exposure and forced labor compliance risk that module assemblers mitigate through supply chain auditing investments. Distribution runs through inverter-integrated system packages where Sungrow and Huawei consolidate power electronics and monitoring layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's PLI-subsidized module assembly and Australia's certificate-inflated commercial payback economics creates margin capture opportunities for developers with cross-border procurement capabilities. Divergent net metering revisions across Indian state electricity boards versus Australia's stable Small-scale Renewable Energy Scheme pricing generate regulatory-risk differentials that shape capital allocation.
For Market Incumbents: Acquire distributed generation project pipelines and grid interconnection permits in Maharashtra and Gujarat before state nodal agencies tighten licensing windows. Consolidate backward integration into silver paste and aluminum framing supply to offset raw material volatility from Xinjiang concentration risk. Defensive positioning requires preemptive certification investment for bifacial glass-glass modules ahead of Australian warehouse specification hardening. For New Entrants and Emerging Players: A 40-50% price-point gap between premium Sungrow-integrated monitoring packages and economy-tier string inverter configurations creates entry space for power electronics specialists with module-level optimization software. Target the Philippines archipelago's islanded commercial loads where diesel displacement economics bypass grid interconnection bottlenecks. White-space penetration demands solar-plus-storage EPC capabilities bundled with microgrid control software for Indonesian eastern islands beyond centralized grid extension. For Investors and Strategic Acquirers: Power utility strategic buyers are the most active acquirer in this space, pursuing distributed generation portfolios to meet renewable procurement mandates without greenfield development risk. Long-term viability over a 5-10 year horizon hinges on battery-hybrid configuration margins expanding as time-of-use arbitrage economics mature. Acquisition targets should display integrated EPC capabilities with state-level grid interconnection permits. Watch for Indonesia's pending net metering regulatory tailwinds as the signal indicating self-consumption market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Xinjiang supply concentration risk forces captive ingot sourcing or audited alternative supplier qualification. |
| Bifacial Module Certification Investment | Australian Clean Energy Regulator eligibility requirements drive warehouse portfolio specification compliance. |
| String Inverter Software Layer Development | Module-level monitoring granularity differentiates Sungrow and Huawei in Southeast Asia commercial tenders. |
| Philippines Solar-Plus-Storage EPC Buildout | Diesel displacement economics in island grids bypass METI-style interconnection friction for hybrid configurations. |
| India PLI-Linked Manufacturing Scale-Up | Maharashtra and Gujarat state nodal agency procurement preferences favor domestic module assembly capacity. |
Study Parameters
Coverage spans India, China, Australia, Vietnam, Japan, and Southeast Asia's logistics corridors, with primary inputs from each market's regulatory and commercial stakeholder base. The analysis combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation from IEA renewable energy statistics, FERC-style regulatory filings, and project development databases. Bottom-up installation forecasts triangulate against top-down provincial quota and national target aggregations.
Granularity-level modeling disaggregates capacity projections by module technology tier, end-use segment, grid integration architecture, and inverter power electronics category across the projection horizon. CAGRs derive from logistic diffusion curves fitted to historical deployment trajectories, adjusted for policy incentive phase-out schedules and manufacturing cost learning rates. Industry-specific inputs include China's National Energy Agency provincial distributed generation quota enforcement patterns and Australia's Small-scale Renewable Energy Scheme certificate price volatility.
The model assumes a particular technology adoption path; alternative pathways for bifacial glass-glass module penetration or battery-hybrid configuration economics would alter the outlook. Forecasts reflect documented assumptions regarding polysilicon supply concentration, net metering revision timelines, and grid interconnection standard evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Australia Solar Market