
 Smart Solar Tracker Market | 2026-2036
Smart Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Solar Tracker Market Insights
Software-defined performance optimization is repositioning how tracker vendors capture value, shifting revenue from hardware sales to recurring digital services. Nextracker leverages proprietary predictive algorithms to command premium positioning in utility-scale deployments across North America. Array Technologies anchors its competitiveness through a decentralized mechanical architecture that reduces installation labor and long-term O&M exposure. Soltec Power Holdings differentiates via geographic specialization in high-diffuse-irradiance climates where its tracking algorithms outperform standard models.
Smart solar trackers are electromechanical mounting structures that dynamically orient photovoltaic modules perpendicular to incoming solar radiation using sensor arrays, motor drives, and control logic, typically achieving 20-35% additional energy yield versus fixed-tilt configurations. Their primary commercial purpose is maximizing levelized cost of electricity reduction for ground-mounted solar assets. Single-axis systems dominate installed capacity due to superior cost-yield economics at utility scale, while dual-axis architectures retain niche relevance in concentrated solar power and high-direct-normal-irradiance zones. Active tracking with smart controls represents the fastest-expanding technology segment as machine learning-based prediction replaces reactive sensor feedback, concentrating margin pools in firmware and remote diagnostics.
The US Federal Energy Regulatory Commission and India's Central Electricity Authority both influence tracker procurement through grid interconnection standards and renewable purchase obligation enforcement, while the EU Green Deal's solar deployment targets accelerate CE-marked product certification requirements across member states. China's Ministry of Ecology and Environment dual carbon goals drive domestic tracker adoption through GB standard compliance mandates. Stakeholders must monitor evolving inverter-grid codes and tracker interoperability standards as distributed energy resource integration requirements tighten.
Market Dynamics
Machine learning-based predictive control is displacing reactive sensor feedback in tracker firmware, compressing hardware margins while expanding recurring revenue pools in remote diagnostics and performance optimization services.
Growth Catalysts
- Bifacial Module Pairing:Utility-scale developers in sun-belt regions are pairing bifacial photovoltaic modules with algorithm-driven single-axis trackers to maximize yield per acre and improve project IRR calculations.
- Domestic Content Bonus Structures:India's PLI scheme and US Inflation Reduction Act manufacturing credits are reshaping procurement economics for intelligent tracking systems in both markets.
- Grid Interconnection Standards:FERC Order 2023 and India's CEA renewable purchase obligation enforcement are mandating smarter inverter-tracker interoperability for utility-scale solar assets.
Market Restraints
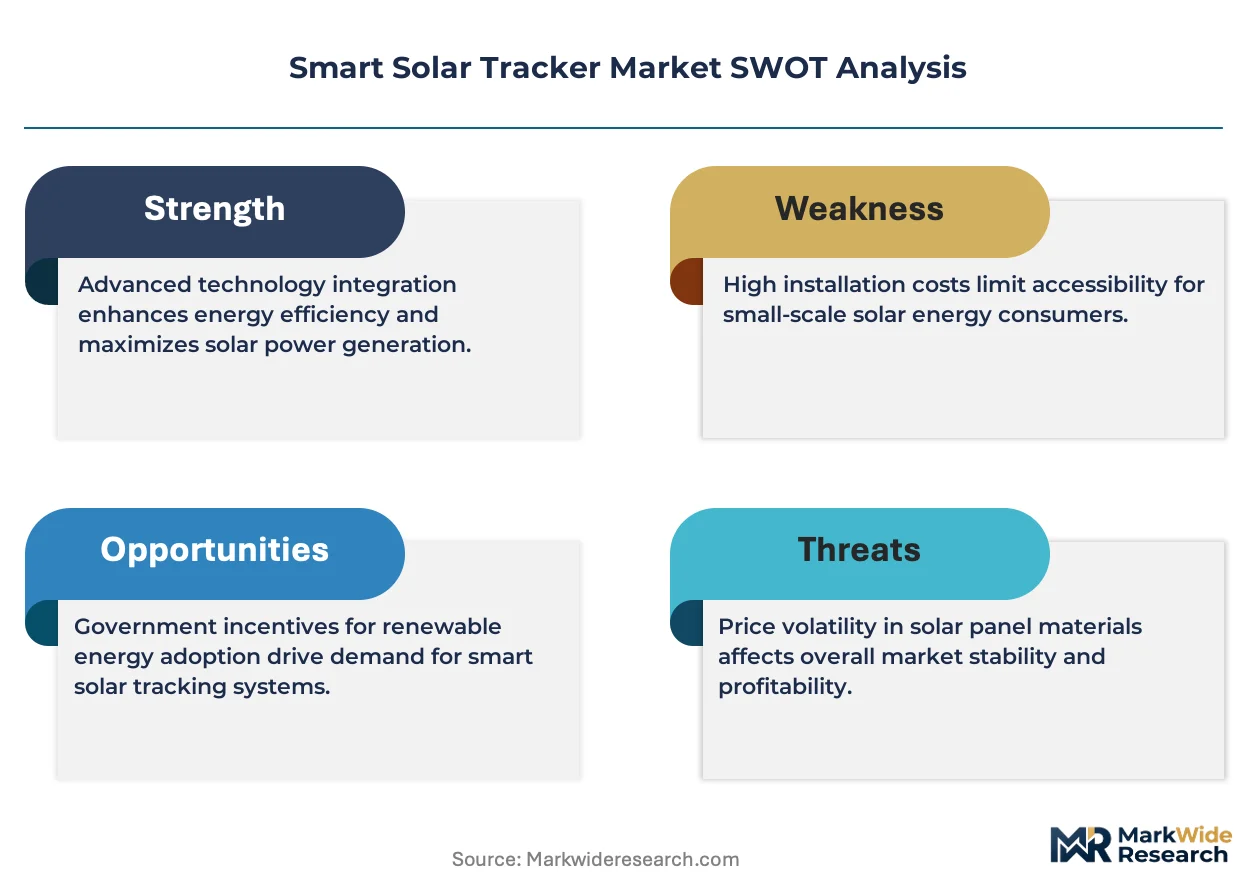
- Steel Input Volatility:Galvanized steel price swings directly impact tracker structural component costs, compressing vendor margins during procurement cycles.
- Supply Concentration Risk:Motor drive and controller electronics manufacturing concentrates in China, exposing non-Chinese tracker vendors to GB standard compliance delays and tariff exposure.
- Dual-Axis Technical Limitation:Complex mechanical maintenance requirements and inferior cost-yield economics versus single-axis systems restrict dual-axis architectures to concentrated solar power niches and high-direct-normal-irradiance zones.
Strategic Opportunities
- High-Diffuse-Irradiance Climates:Spain and other Mediterranean markets present underpenetrated demand for tracking algorithms optimized for cloudy conditions where standard models underperform.
- Distributed Energy Resource Integration:Tightening inverter-grid codes in Germany and California are creating demand for tracker-inverter communication protocols that enable virtual power plant participation.
- Software-Defined Services:Predictive maintenance subscriptions and yield optimization algorithms represent emerging revenue streams beyond hardware sales for tracker vendors with proprietary firmware capabilities.
Industry Challenges
- Embedded Systems Talent Gap:Firmware engineering for real-time motor control and machine learning inference at the edge remains scarce, slowing product development cycles.
- CE-Marking Certification Timeline:EU Green Deal solar deployment targets are accelerating product certification requirements, creating bottlenecks for non-European tracker manufacturers seeking market access.
- Legacy SCADA Integration:Utility-scale asset operators require seamless data exchange between new smart trackers and existing plant control systems, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Solar Tracker Market |
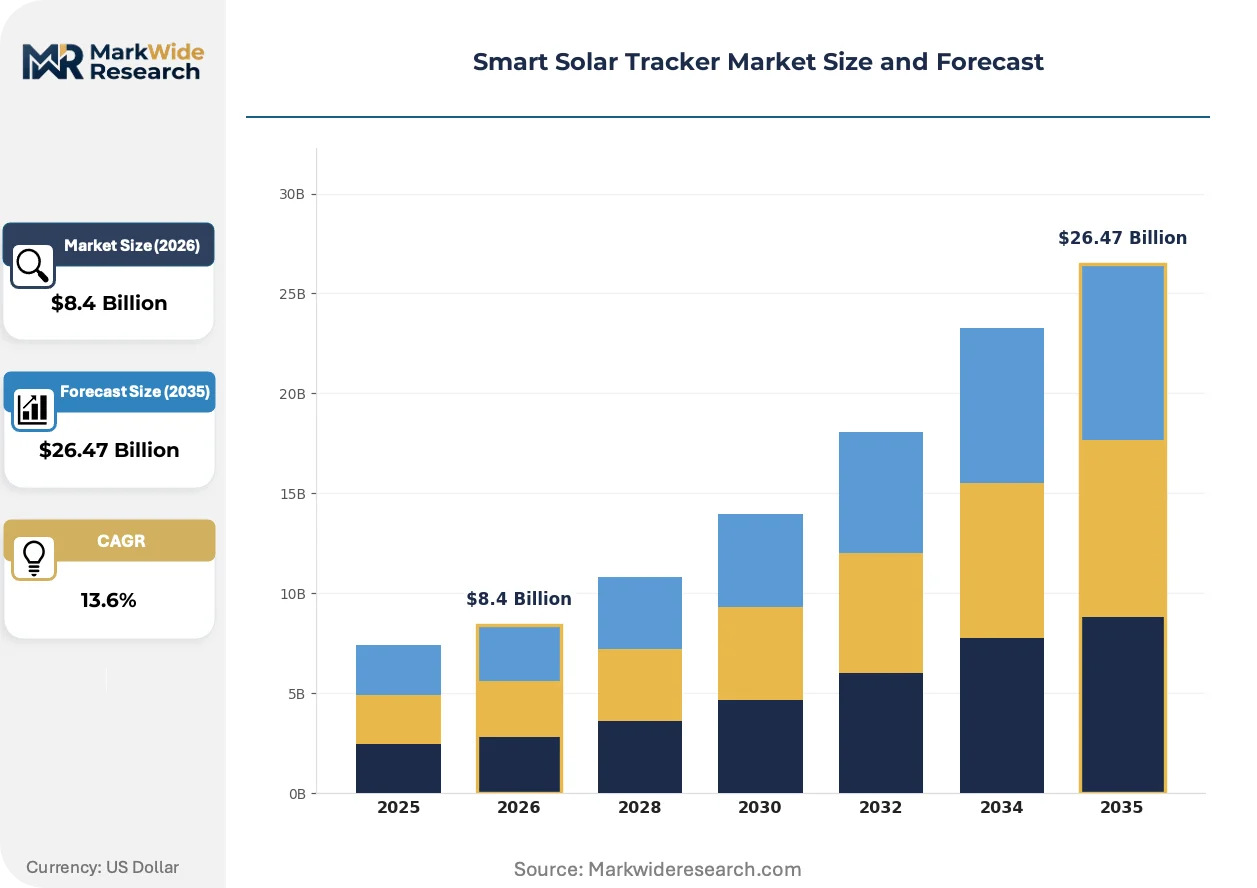
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axis, Dual Axis, Fixed Tilt, Others Application: Utility Scale, Commercial, Residential, Off-Grid Technology: Active Tracking, Passive Tracking, Hybrid Systems, Smart Controls End User: Energy Providers, Installation Companies, Property Developers, Government |
| Companies Covered | Nextracker, Array Technologies, Arctech Solar, Soltec Power Holdings, Trina Solar, PV Hardware, GameChange Solar, STI Norland, Convert Italia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Solar Tracker Market Trends and Innovations
Edge computing architectures are embedding directly into tracker control systems, enabling real-time optimization without cloud latency while creating new competitive battlegrounds in firmware intellectual property.
Self-calibrating sensor arrays are integrating machine learning models that predict solar position using weather data and astronomical algorithms rather than reactive light sensors. Nextracker and Array Technologies are deploying these systems across North American utility-scale installations. This convergence is integrating predictive analytics into hardware margins, forcing vendors to build recurring software revenue or face commoditization.
The EU AI Act's risk classification framework is imposing documentation and transparency requirements on automated decision systems in energy infrastructure. Tracker control algorithms that adjust module orientation based on predictive models now face conformity assessment obligations in member states. German and Spanish project developers are prioritizing CE-marked controllers with algorithmic audit trails to preempt regulatory friction.
Asset operators are unbundling tracker O&M contracts from EPC agreements, creating direct procurement relationships with specialized service providers. This disintermediation shifts vendor relationships from project developers to long-term asset owners in the United States and India. Yield guarantees and uptime-based service level agreements are replacing capital equipment warranties as the primary commercial mechanism in these markets.
Smart Solar Tracker Market Segmentation
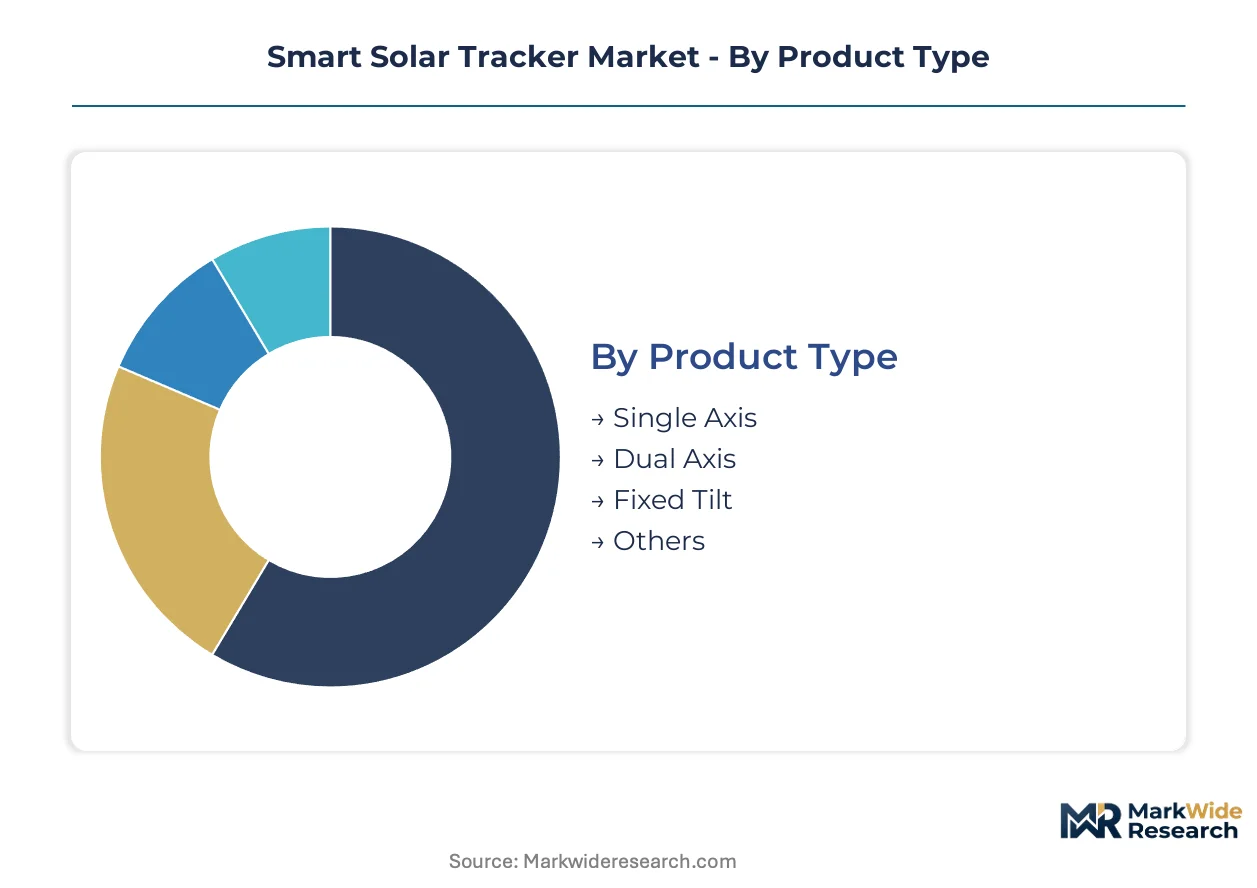
Smart solar tracker segmentation reveals how hardware economics, software capabilities, and procurement patterns concentrate margin pools across distinct product architectures and customer workflows. Understanding these divisions exposes where predictive algorithms and steel-intensive structures compete for capital allocation.
Product Type:
Supply concentration in motor drive manufacturing and structural steel fabrication shapes competitive positioning across tracker mechanical architectures, with Chinese controller suppliers and regional steel mills determining vendor cost structures.
- Single Axis:Electromechanical systems rotate modules along one horizontal axis, typically north-south, using linear actuators or torque tube drives. Utility-scale developers in India and the United States deploy these systems for their superior cost-yield economics at gigawatt-scale installations. Domestic content bonus structures under India's PLI scheme and the US Inflation Reduction Act are accelerating procurement of locally manufactured single-axis hardware.
- Dual Axis:Mechanisms adjust both azimuth and elevation angles to maintain perpendicular module orientation throughout the day. Concentrated solar power developers in Spain and high-direct-normal-irradiance zones utilize these systems despite complex maintenance requirements and inferior levelized cost metrics versus single-axis alternatives.
- Fixed Tilt:Stationary mounting structures hold modules at constant angles without tracking capability. Distributed commercial installers in markets with high labor costs favor these systems for their minimal O&M exposure and compatibility with rapid deployment timelines.
- Others:Emerging architectures include seasonal tilt-adjustable systems and floating solar trackers for reservoir installations.
Single Axis absorbs the bulk of installed capacity; Smart Controls integration is expanding most quickly as vendors embed predictive algorithms into hardware offerings.
Application:
Project scale determines procurement complexity, with gigawatt-scale developments demanding sophisticated inverter-tracker interoperability while smaller installations prioritize installation speed and minimal commissioning overhead.
- Utility Scale:Ground-mounted solar farms exceeding 20 megawatts utilize centralized tracker networks with SCADA integration and predictive maintenance protocols. India's Central Electricity Authority renewable purchase obligations and FERC Order 2023 interconnection standards mandate smarter inverter-tracker communication for these assets.
- Commercial:Rooftop and carport installations between 100 kilowatts and 5 megawatts balance yield optimization against structural loading constraints. California's Title 24 building energy codes and Germany's EEG feed-in tariff structures influence tracker specification in these segments.
- Residential:Small-scale ground-mount systems for single properties rarely justify tracking hardware costs given limited roof space and simpler fixed-tilt economics.
- Off-Grid:Remote industrial sites and rural electrification projects utilize trackers with battery-integrated control systems independent of grid synchronization requirements.
Utility Scale commands the dominant share of tracker revenue; Commercial applications are climbing the fastest as distributed energy resource integration requirements tighten across California and Germany.
Technology:
Firmware development cycles and embedded systems talent scarcity create capability gaps between reactive sensor-based systems and predictive machine learning architectures, concentrating margin pools in algorithm intellectual property.
- Active Tracking:Sensor arrays detect solar position and drive motor adjustments in real-time, representing the legacy technical foundation for tracker control systems. Spanish and Mediterranean markets continue deploying these systems where diffuse irradiance conditions challenge predictive models.
- Passive Tracking:Thermal or mechanical actuators respond to solar heating without electronic control, retaining relevance in off-grid applications with limited power availability.
- Hybrid Systems:Combinations of sensor feedback and astronomical prediction balance accuracy against hardware cost, serving mid-scale commercial installations.
- Smart Controls:Machine learning models process weather data and astronomical algorithms to predict optimal module orientation before sensor detection. The EU AI Act's risk classification framework now imposes conformity assessment obligations on these automated decision systems in member states.
Active Tracking retains the largest installed base; Smart Controls are gaining share fastest as Nextracker and Array Technologies deploy self-calibrating predictive systems across North American utility-scale installations.
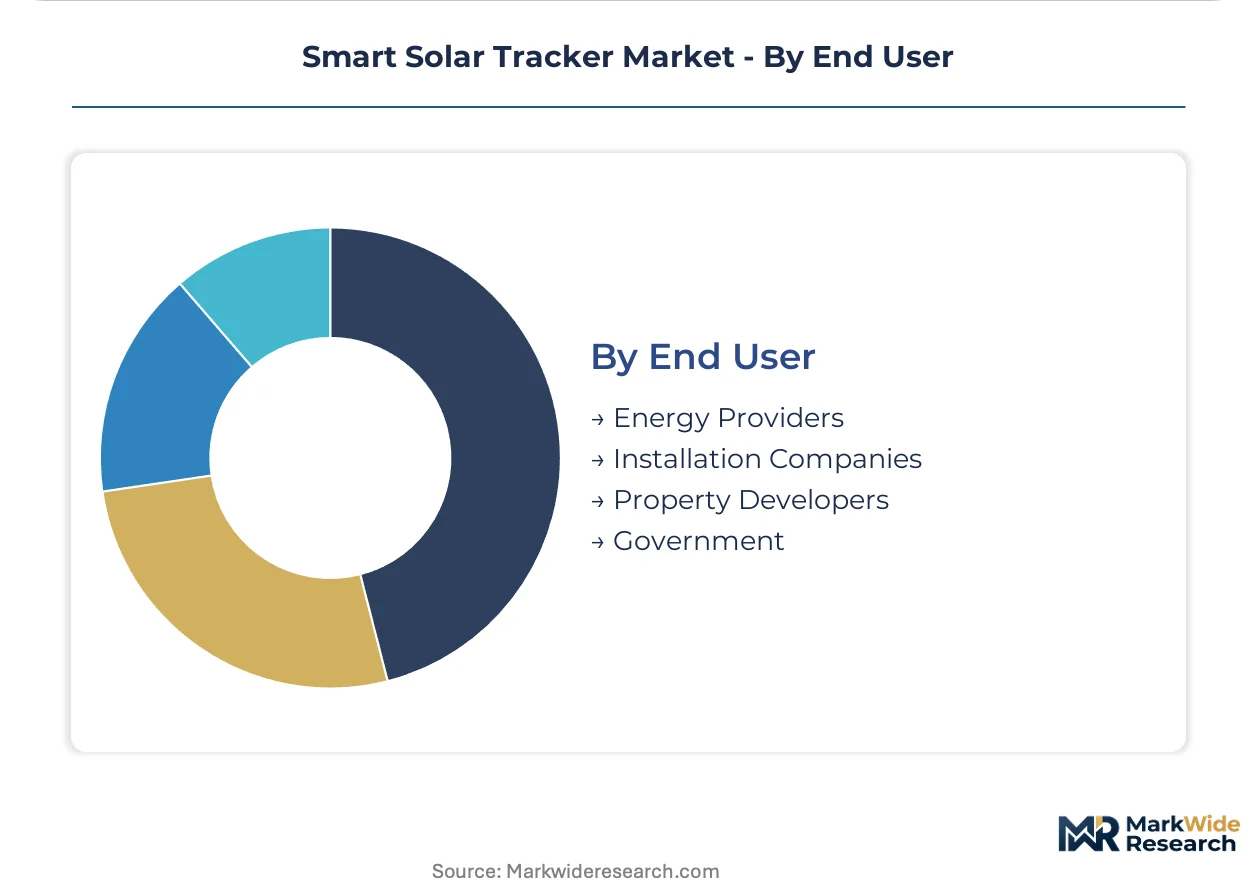
End User:
Procurement authority is shifting from engineering-procurement-construction contractors toward long-term asset operators, restructuring vendor relationships and commercial terms across customer categories.
- Energy Providers:Utility companies and independent power producers specify tracker systems for owned generation assets, prioritizing 25-year operational life and uptime-based service level agreements over capital equipment warranties.
- Installation Companies:EPC contractors select tracker hardware based on installation labor efficiency and supply chain reliability, with decentralized mechanical architectures reducing field assembly time.
- Property Developers:Real estate firms integrating solar into commercial and industrial projects prioritize rapid permitting compatibility and aesthetic integration with building envelopes.
- Government:Public procurement entities in India and the United States enforce domestic content requirements through PLI scheme compliance and Inflation Reduction Act manufacturing credits.
Energy Providers dominate procurement volume; Installation Companies are expanding their influence fastest as asset operators unbundle O&M contracts from EPC agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of motor drive and controller electronics for smart solar trackers, while the United States, India, and Spain consume the largest deployment volumes for utility-scale installations. This production-consumption divide shapes procurement strategies and regulatory compliance requirements across major markets.
United States
Utility-scale developers in Texas and California are procuring algorithm-driven single-axis trackers to maximize yield per acre under FERC Order 2023 interconnection standards. The Inflation Reduction Act's manufacturing credits are reshaping domestic content requirements for intelligent tracking systems. Arizona and Nevada solar clusters are deploying predictive control firmware to optimize bifacial module pairing in high-direct-normal-irradiance zones.
India
Gujarat and Rajasthan solar parks are expanding tracker deployments under the Central Electricity Authority's renewable purchase obligation enforcement. The PLI scheme is accelerating local manufacturing of tracker structural components and motor drives. Domestic content bonus structures are redirecting procurement toward Indian-certified vendors in the Maharashtra and Karnataka industrial corridors.
Spain
Andalusia and Extremadura concentrated solar power developers utilize dual-axis architectures despite complex maintenance requirements. The EU Green Deal's solar deployment targets are accelerating CE-marked product certification for tracker control systems. Mediterranean climate conditions in the Valencia region are driving demand for algorithms optimized for high-diffuse-irradiance performance.
China
Jiangsu and Zhejiang provinces concentrate manufacturing of motor drive electronics and controller systems for export markets. The Ministry of Ecology and Environment's dual carbon goals are driving domestic tracker adoption through GB standard compliance mandates. Yangtze River Delta industrial clusters are embedding edge computing architectures into tracker firmware for real-time optimization.
Germany
Bavaria and North Rhine-Westphalia commercial installers are specifying tracker-inverter communication protocols for virtual power plant participation. The EU AI Act's risk classification framework is imposing conformity assessment obligations on predictive control algorithms. Industrial zones around Stuttgart are prioritizing CE-marked controllers with algorithmic audit trails to preempt regulatory friction.
Smart Solar Tracker Market Competitive Landscape
Top-tier vendors anchor utility-scale procurement channels, while mid-tier specialists compete on installation labor efficiency and regional certification compliance. The market exhibits tiered concentration with firmware-capable incumbents commanding premium positioning against steel-intensive mechanical fabricators. Strategic archetypes include algorithm-driven predictive control developers, decentralized mechanical architecture specialists, and geographic climate optimization firms. Competitive moves center on backward integration into motor drive manufacturing and strategic partnerships for distributed energy resource interoperability.
Among North American firmware developers, Nextracker and Array Technologies exemplify the algorithm-driven tier, with the former representing predictive analytics capabilities and the latter anchoring decentralized mechanical architectures. Soltec Power Holdings occupies a position within the geographic specialization archetype, serving high-diffuse-irradiance markets where standard tracking models underperform. These three companies collectively illustrate how competitive positioning stratifies across software-defined services, mechanical engineering efficiency, and climate-specific algorithm development.
| Leading Market Players |
|---|
| Nextracker |
| Array Technologies |
| Arctech Solar |
| Soltec Power Holdings |
| Trina Solar |
| PV Hardware |
| GameChange Solar |
| STI Norland |
| Convert Italia |
| Others |
Pricing and Supply Chain Analysis
Galvanized steel coil prices transmit directly from Yangtze River Delta mills through three-tier pricing structures separating CE-certified European vendors from Indian PLI-compliant suppliers and unbranded mechanical fabricators. Motor drive controller costs from Jiangsu and Zhejiang manufacturers concentrate margin pressure on non-Chinese tracker vendors facing GB standard compliance delays and tariff exposure.
Pricing Analysis
Cost-down pressure on standard mechanical tiers accelerates because steel input volatility compresses vendor margins during procurement cycles. Project-based pricing dominates utility-scale deployments, with differentiation separating firmware-enabled predictive control systems from commodity torque-tube hardware. CE-marked controllers with algorithmic audit trails command premium positioning against uncertified alternatives. Utility-scale developers in India and the United States exhibit highest price sensitivity, while European asset operators prioritize regulatory compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for motor drives and controller electronics mandate qualification of both Chinese GB-standard suppliers and alternative vendors in South Korea and Taiwan. Tracker structural components draw from regional steel mills in India, the United States, and Spain, while semiconductor content for edge computing architectures feeds from Taiwan and South Korea fabrication. Tariff exposure on Chinese electronics creates supply chain risk for North American and European tracker vendors. Distribution runs through EPC contractor networks for utility-scale projects and direct procurement relationships with asset operators for O&M services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineering capacity for real-time motor control and machine learning inference at the edge functions as the binding constraint propping pricing for firmware-capable vendors. This talent scarcity protects margin pools in predictive analytics while exposing steel-intensive mechanical fabricators to commoditization.
For Market Incumbents: Lock in proprietary algorithm intellectual property through strategic hiring of firmware engineering talent in Germany and California. Deepen backward integration into motor drive manufacturing to reduce exposure to Chinese supply concentration and GB standard compliance delays. Defend against emerging mechanical fabricators by bundling predictive maintenance subscriptions with hardware sales.
For New Entrants and Emerging Players: Launch via specialized service provider channels targeting unbundled O&M contracts in the United States and India. Spain and Mediterranean markets present the most penetrable white-space for algorithms optimized for high-diffuse-irradiance climates where standard tracking models underperform. Prioritize CE-marking certification with algorithmic audit trails to preempt EU AI Act regulatory friction.
For Investors and Strategic Acquirers: FERC Order 2023 interconnection standard enforcement is the leading indicator that inverter-tracker interoperability capabilities will determine long-term vendor viability. Acquisition targets should display proprietary firmware stacks with virtual power plant communication protocols. The signal to watch is unbundling of O&M contracts from EPC agreements shifting procurement authority toward asset operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Drive Manufacturing | Reduces GB standard compliance exposure and tariff vulnerability for non-Chinese vendors. |
| Predictive Maintenance Subscription Launch | Creates recurring revenue streams beyond hardware sales for firmware-capable tracker vendors. |
| CE-Marking Certification with Algorithmic Audit Trails | Preempts EU AI Act conformity assessment obligations for automated tracking systems. |
| Virtual Power Plant Communication Protocol Development | Enables tracker participation in Germany and California distributed energy resource markets. |
| High-Diffuse-Irradiance Algorithm Specialization | Captures underpenetrated demand in Spain and Mediterranean markets where standard models underperform. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility-scale project developers, EPC procurement leads, tracker vendor engineering directors, and asset operator O&M managers. FERC Order 2023 documentation, India's CEA renewable purchase obligation filings, and EU Green Deal implementation reports provided regulatory validation. Customs records from India, the United States, and Spain tracked tracker component import flows. Bottom-up project pipeline analysis triangulated against top-down market sizing from steel consumption and motor drive shipment data.
Segment-level modeling applied distinct growth assumptions across single-axis and dual-axis mechanical architectures, active tracking versus smart controls technology tiers, and utility-scale versus commercial application segments. Project scale thresholds, inverter-tracker interoperability requirements, and domestic content bonus structures under India's PLI scheme and the US Inflation Reduction Act informed regional divergence. CAGRs derived from regression analysis of historical deployment data against steel price indices and module cost trajectories across the projection horizon.
Steel price volatility, GB standard compliance timeline delays, and embedded systems talent availability are the dominant revision risks to the outlook. Deviation in Chinese motor drive supply continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Indonesia Solar Energy Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Argentina Solar Energy Market