
 Gas Fixed Power Capacitors Sales Market | 2026-2036
Gas Fixed Power Capacitors Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Fixed Power Capacitors Sales Market Insights
High-voltage gas-filled specification tiers is bifurcating the competitive landscape between premium reliability providers and cost-optimized volume suppliers. ABB leverages its integrated power grid portfolio to anchor utility-scale substation contracts across European and North American markets. Siemens AG competes through technology leadership in smart capacitor systems with embedded monitoring capabilities. Guilin Power Capacitor dominates domestic procurement channels within China's state grid infrastructure.
Gas fixed power capacitors are passive electrical components utilizing pressurized gas dielectrics—typically sulfur hexafluoride or nitrogen blends—within sealed metal enclosures to store and release reactive power at voltages ranging from 1 kV to 800 kV. These devices compensate for inductive loads in transmission and distribution networks, stabilizing voltage profiles and improving power factor across industrial and utility installations. Oil-immersed capacitors retain the largest installed base among product types due to decades of proven performance in harsh outdoor substation environments, though dry-type variants are gaining share in urban indoor installations where fire safety and environmental containment drive specification changes. Smart capacitors within the technology dimension command expanding margin pools as grid operators prioritize real-time VAR control and predictive maintenance over passive fixed compensation.
Grid operators in the United States navigate FERC Order 2023 compliance requirements for reactive power support and voltage stability, while European utilities align capacitor procurement with EU Green Deal decarbonization timelines and F-Gas Regulation phase-down mandates for sulfur hexafluoride-intensive equipment. China's GB standards and dual carbon goals enforce progressively stricter efficiency benchmarks on new capacitor installations, constraining market access for non-compliant suppliers. Stakeholders must monitor evolving dielectric gas regulations and smart grid interoperability standards to align R&D roadmaps with procurement specification shifts.
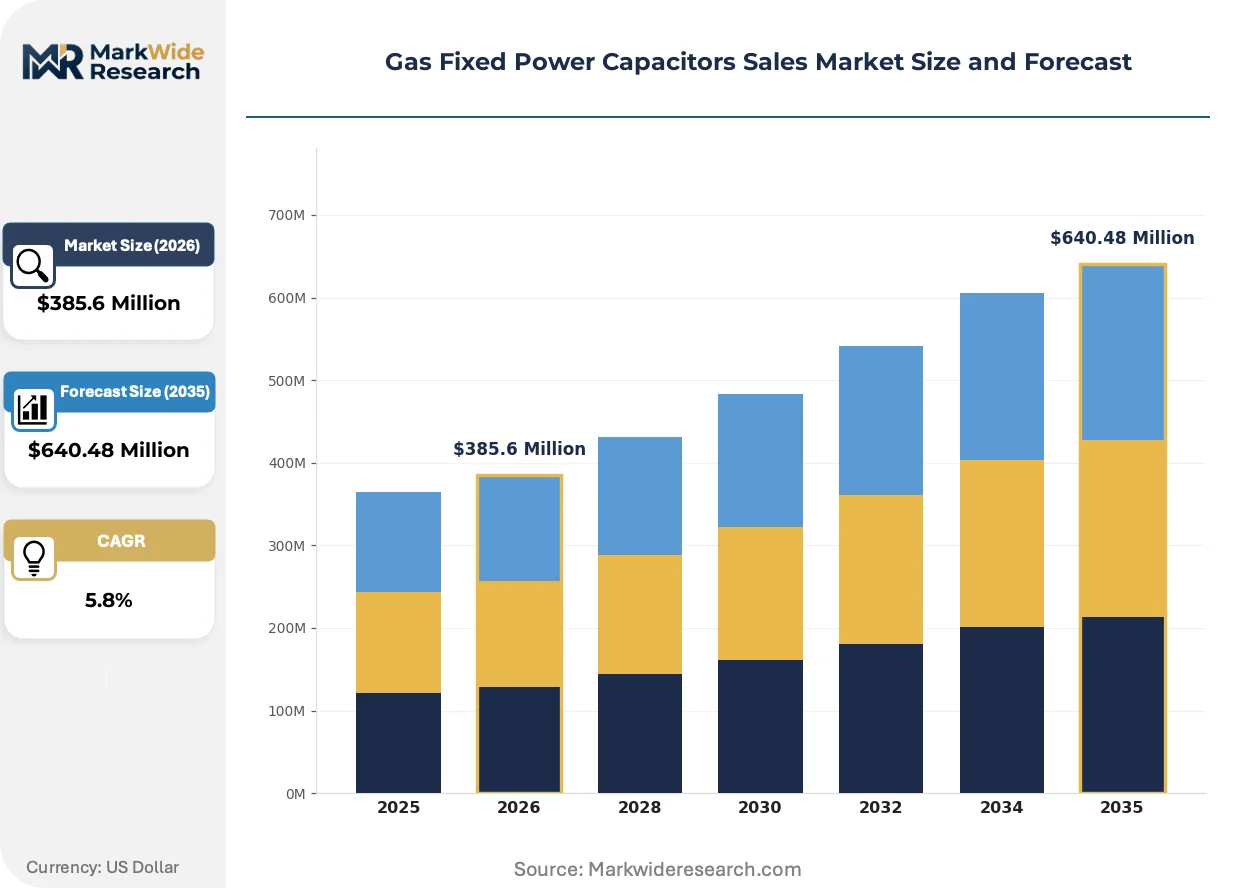
Market Dynamics
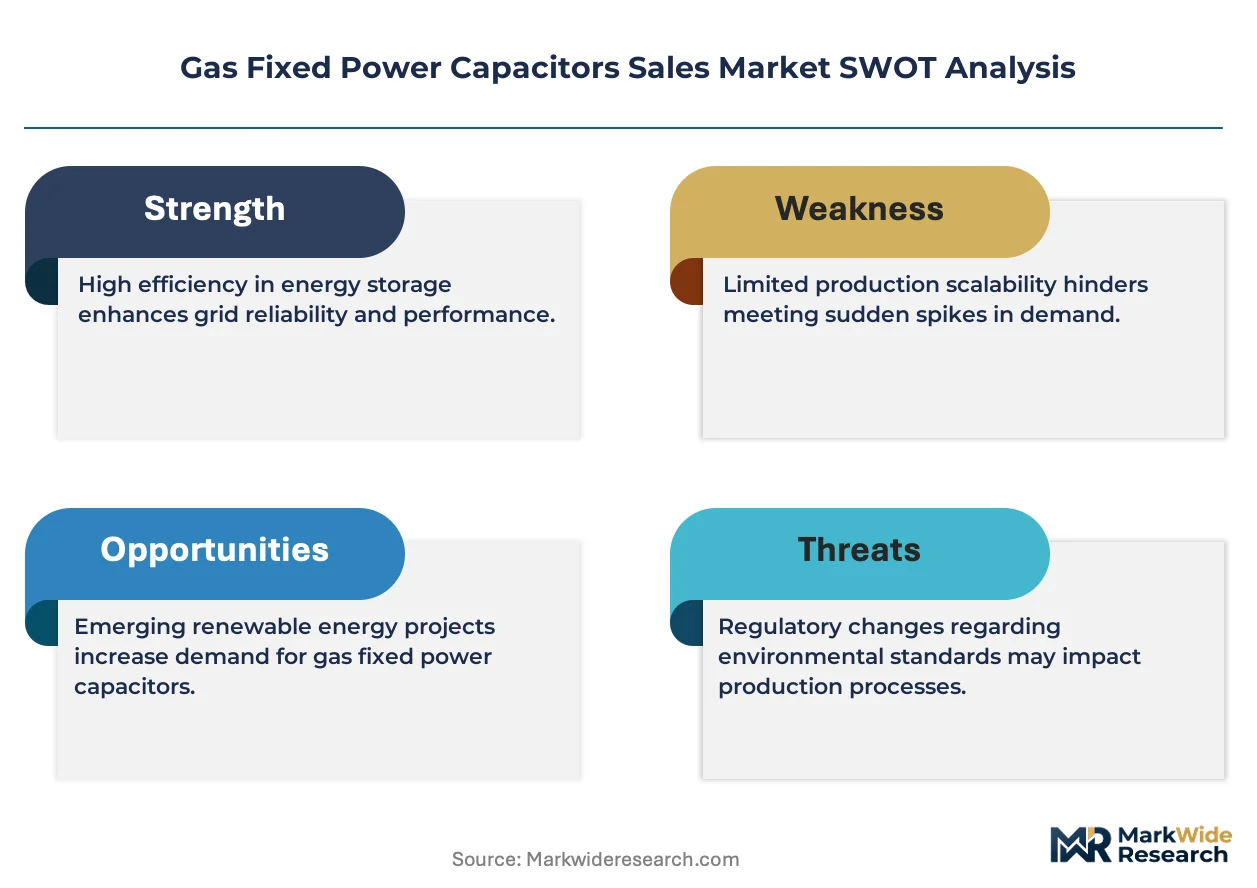
The gas fixed power capacitors market is undergoing fundamental restructuring as sulfur hexafluoride phase-down mandates under the EU F-Gas Regulation and China's dual carbon goals force dielectric gas transitions across utility procurement specifications. This regulatory compression is bifurcating supplier capabilities between compliant gas blend innovators and legacy SF6-dependent manufacturers.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:European utilities must replace sulfur hexafluoride-intensive capacitor banks with alternative gas dielectrics, creating mandatory replacement cycles across transmission substations in Germany, France, and Italy.
- Wind and solar intermittency compensation:Grid operators in India and China are deploying reactive power infrastructure to stabilize voltage fluctuations from renewable generation clusters, driving utility-scale capacitor procurement.
- Smart grid interoperability mandates:Embedded monitoring capabilities are becoming standard in capacitor specifications as operators prioritize real-time VAR control and predictive maintenance over passive compensation.
Market Restraints
- Alternative gas dielectric R&D costs:Nitrogen-fluorinated gas blends and vacuum interrupter technologies require substantial capital investment, constraining mid-tier suppliers from achieving regulatory compliance.
- Raw material concentration in China:Aluminum foil and polypropylene film supply chains concentrate within Chinese manufacturing zones, exposing procurement costs to export tariff volatility and logistics constraints.
- Technical performance gaps in SF6 substitutes:Alternative gas dielectrics currently exhibit lower dielectric strength and thermal conductivity than sulfur hexafluoride, limiting their deployment in ultra-high-voltage installations above 400 kV.
Strategic Opportunities
- Rural electrification in Southeast Asia:Vietnam, Indonesia, and the Philippines are expanding transmission infrastructure to connect remote renewable generation, creating demand for medium-voltage gas capacitor installations.
- Digital twin integration:Convergence of capacitor condition monitoring with grid digitalization platforms enables predictive asset management and service revenue streams for equipment suppliers.
- US IRA manufacturing incentives:Domestic content requirements and production tax credits are incentivizing localized capacitor assembly capacity to serve North American utility procurement.
Industry Challenges
- Dielectric gas handling certification:Field technicians require specialized training for SF6 recovery and alternative gas filling procedures, creating workforce bottlenecks during large-scale replacement programs.
- Legacy bank integration complexity:New smart capacitor installations must interface with decades-old protection relays and control systems, extending commissioning timelines and technical risk.
- Extended type-test durations:IEC 60871 and GB/T 11024 certification cycles for new gas formulations stretch 18-24 months, delaying product commercialization behind regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Fixed Power Capacitors Sales Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Immersed Capacitors, Dry-Type Capacitors, Hybrid Capacitors, Others End User: Utilities, Industrial Applications, Renewable Energy, Commercial Sector Installation Type: Indoor Installation, Outdoor Installation, Pole-Mounted, Substation Technology: Conventional Capacitors, Smart Capacitors, Active Harmonic Filters, Others |
| Companies Covered | ABB, Schneider Electric, Eaton, Vishay Intertechnology, TDK Electronics AG, Nissin Electric, Siemens AG, China XD, Guilin Power Capacitor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Fixed Power Capacitors Sales Market Trends and Innovations
Technology transitions and procurement model evolution are compressing traditional product lifecycles while elevating digital service components in supplier value propositions. Three forces dominate this transformation.
Dry-type gas-filled capacitor designs utilizing nitrogen-based dielectrics are supplanting oil-immersed units in urban indoor substations. European utilities in the Netherlands and Denmark are specifying these variants to eliminate fire risk and environmental containment burdens. The shift is compressing margins on conventional oil-type manufacturing while opening premium pricing tiers for gas-tight enclosure engineering.
China's GB standards enforcement through the State Administration for Market Regulation is tightening efficiency benchmarks on new capacitor installations. Domestic suppliers must now demonstrate loss tangent performance below 0.0003 to qualify for state grid procurement. This regulatory compression is accelerating R&D concentration among tier-one manufacturers while disqualifying legacy product lines from utility tenders.
Utility procurement departments are consolidating supplier relationships around integrated VAR compensation system providers rather than component vendors. State Grid Corporation of China and Power Grid Corporation of India are negotiating multi-year framework agreements covering capacitors, reactors, and control systems. This buyer concentration is visible across Asia-Pacific markets where transmission asset ownership centralizes under national grid operators.
Gas Fixed Power Capacitors Sales Market Segmentation
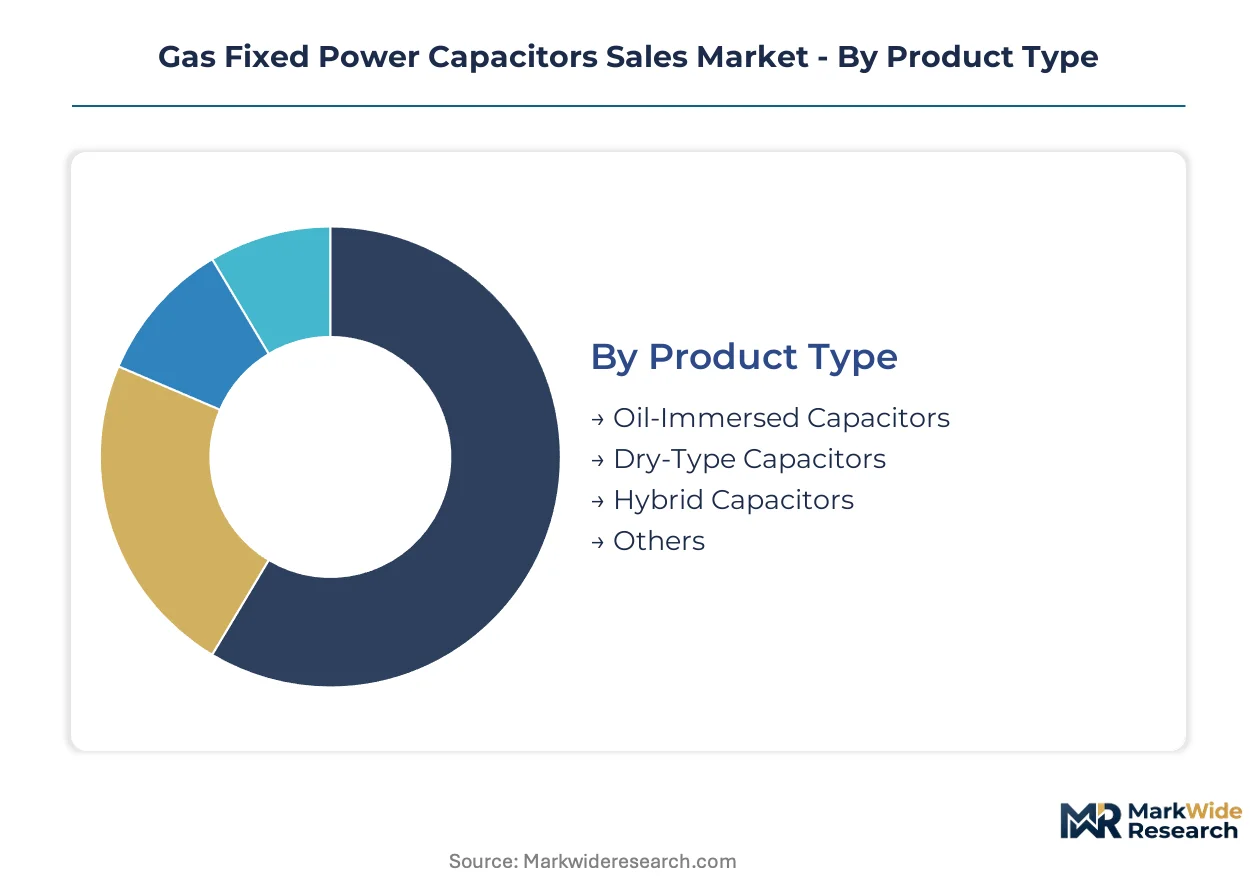
Gas fixed power capacitors fragment across dielectric medium, deployment environment, and intelligence tier. Procurement specifications diverge sharply between legacy utility infrastructure and emerging renewable integration projects.
Product Type:
EU F-Gas Regulation phase-down mandates and China's dual carbon goals enforce progressively stricter dielectric gas standards, bifurcating supplier capabilities between compliant gas blend innovators and legacy SF6-dependent manufacturers.
- Oil-Immersed Capacitors:These units utilize mineral oil or synthetic ester dielectrics within sealed tanks, delivering proven thermal management in harsh outdoor substation environments. Demand concentrates in German, French, and Italian transmission utilities executing mandatory replacement cycles under F-Gas Regulation deadlines. Thermal conductivity advantages sustain deployment in ultra-high-voltage installations above 400 kV where alternative gas dielectrics currently exhibit performance gaps.
- Dry-Type Capacitors:Nitrogen-based or dry resin-impregnated designs eliminate fire risk and environmental containment burdens in urban indoor installations. Netherlands and Denmark utilities specify these variants for densely populated substation zones. GB standards enforcement through China's SAMR tightens efficiency benchmarks, disqualifying legacy product lines from state grid procurement.
- Hybrid Capacitors:Combined dielectric systems optimize performance across variable load conditions.
- Others:Emerging solid-state and vacuum dielectric technologies address niche ultra-high-voltage applications.
Established volume favors Oil-Immersed Capacitors; emerging adoption favors Dry-Type Capacitors.
End User:
Customer procurement scale determines specification complexity, with national grid operators consolidating supplier relationships around integrated VAR compensation system providers.
- Utilities:State Grid Corporation of China and Power Grid Corporation of India negotiate multi-year framework agreements covering capacitors, reactors, and control systems. These buyers prioritize real-time VAR control and predictive maintenance capabilities in smart capacitor specifications. FERC Order 2023 compliance requirements in the United States mandate reactive power support and voltage stability investments across transmission operators.
- Industrial Applications:Steel mills, cement plants, and chemical facilities deploy capacitors for power factor correction and harmonic mitigation. India's CEA mandates industrial consumers above specified load thresholds install reactive power compensation equipment. Margin compression in commodity manufacturing constrains specification tiers toward cost-optimized volume suppliers.
- Renewable Energy:Wind and solar farm developers require dynamic reactive power infrastructure to stabilize voltage fluctuations from generation intermittency. Procurement concentrates in India and China where renewable cluster expansion outpaces grid reinforcement.
- Commercial Sector:Data centers and large retail facilities install capacitors behind-the-meter to manage power quality and demand charge optimization.
Utility procurement dominates absolute volume; Renewable Energy represents the steepest expansion trajectory.
Installation Type:
Physical deployment constraints dictate enclosure engineering requirements and dielectric medium selection.
- Indoor Installation:Dry-type gas-filled variants utilizing nitrogen-based dielectrics supplant oil-immersed units in urban substations where fire safety and environmental containment drive specification changes. European utilities in Denmark and the Netherlands lead this transition.
- Outdoor Installation:Oil-immersed capacitors retain preference for exposed substation environments due to decades of proven weather resistance and thermal performance.
- Pole-Mounted:Compact medium-voltage units serve rural distribution networks in Southeast Asian electrification programs across Vietnam, Indonesia, and the Philippines.
- Substation:High-voltage gas-filled specification tiers anchor utility-scale deployments across 1 kV to 800 kV ratings.
Outdoor Installation maintains installed base dominance; Indoor Installation gains specification share fastest.
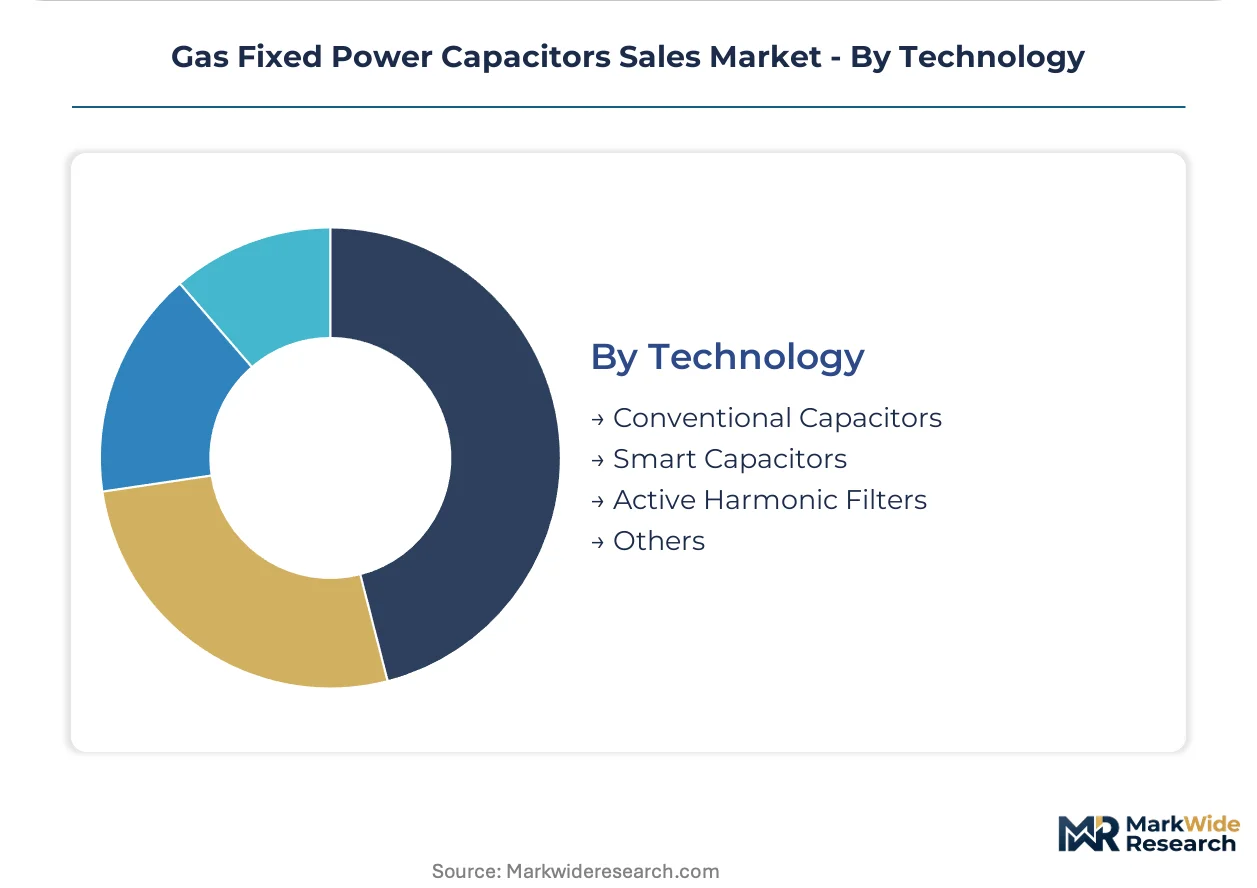
Technology:
Intelligence integration separates commodity component suppliers from system-level solution providers.
- Conventional Capacitors:Passive fixed compensation devices without embedded monitoring capabilities. These units face margin compression as procurement shifts toward predictive maintenance functionality.
- Smart Capacitors:Embedded monitoring systems enable real-time VAR control, condition assessment, and digital twin integration. Siemens AG competes through technology leadership in these systems. Grid operators prioritize these capabilities for predictive asset management and service revenue streams.
- Active Harmonic Filters:Power electronics-based solutions address power quality beyond reactive power compensation alone.
- Others:Hybrid compensation systems combining passive and active elements for complex industrial loads.
Conventional Capacitors retain replacement volume; Smart Capacitors command expanding margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France demonstrate the lowest price elasticity, accepting premium specifications under EU F-Gas Regulation mandates, while Southeast Asian utilities remain highly price-sensitive in rural electrification deployments.
China
State Grid Corporation executes massive capacitor bank replacements across 800 kV ultra-high-voltage corridors to meet dual carbon goals. SAMR enforces loss tangent benchmarks below 0.0003 through GB standards. Shandong Peninsula manufacturing clusters supply aluminum foil and polypropylene film to domestic capacitor fabricators.
Germany
TenneT and 50Hertz transmission operators mandate SF6-free capacitor installations under F-Gas Regulation phase-down schedules. ECHA chemical safety protocols govern alternative gas dielectric certification. Bavarian industrial zones host testing facilities for nitrogen-fluorinated blend validation.
India
Power Grid Corporation expands reactive power infrastructure along Rajasthan and Gujarat renewable energy zones to stabilize solar intermittency. CEA mandates industrial consumers above specified load thresholds install compensation equipment. Tamil Nadu substation clusters prioritize smart capacitor specifications with embedded monitoring.
United States
ERCOT and CAISO grid operators invest in voltage stability infrastructure to accommodate Texas and California wind-solar generation profiles. FERC Order 2023 compliance requirements mandate reactive power support investments. Midwest transmission corridors concentrate utility-scale capacitor procurement from domestic assembly facilities.
Vietnam
EVN accelerates rural electrification programs connecting remote Mekong Delta and Central Highlands generation to national transmission. The national power development plan prioritizes medium-voltage infrastructure expansion. Ho Chi Minh City industrial zones drive demand for compact pole-mounted capacitor units.
Gas Fixed Power Capacitors Sales Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Integrated power grid conglomerates anchor utility-scale substation contracts through portfolio breadth, while specialized capacitor manufacturers compete on dielectric gas innovation and price-optimized volume production. Three archetypes dominate: full-spectrum grid solution providers, regional procurement channel specialists, and component-focused volume suppliers. Competitive moves concentrate on alternative gas dielectric R&D partnerships and smart monitoring capability licensing.
Among integrated European industrials, ABB and Siemens AG occupy positions spanning utility-scale project bundling and smart system integration. Guilin Power Capacitor exemplifies the regional procurement specialist archetype, anchoring domestic channel access within China's state grid infrastructure. These three represent distinct competitive vectors: technology-integrated solutions, geographic channel control, and cost-optimized manufacturing scale.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Eaton |
| Vishay Intertechnology |
| TDK Electronics AG |
| Nissin Electric |
| Siemens AG |
| China XD |
| Guilin Power Capacitor |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation certification cycles and IEC 60871 type-test durations simultaneously gate supplier qualification tiers and stratify lifetime contract values across utility procurement channels. Buyers in Germany and France accept premium pricing for SF6-free installations while Southeast Asian utilities negotiate aggressively on pole-mounted medium-voltage units.
Pricing Analysis
Service revenue from predictive maintenance contracts and digital twin integration drives lifetime value differentiation across supplier portfolios. Three-tier pricing structure across premium smart systems, standard dry-type units, and economy oil-immersed configurations reflects certification grade and embedded monitoring capabilities. Cost compression in conventional passive capacitors is intensifying because procurement shifts toward VAR compensation system bundling. Industrial applications exhibit highest price sensitivity; European transmission utilities demonstrate lowest elasticity under regulatory mandate pressure.
Supply Chain Analysis
Shandong Peninsula aluminum foil and polypropylene film concentration anchors raw material access for domestic Chinese fabricators. Manufacturing draws from Chinese dielectric film production, German nitrogen-fluorinated gas blend R&D, and Indian transformer-grade steel fabrication. Single-source vulnerability in high-purity aluminum foil supply exposes procurement costs to export tariff volatility. Distribution runs through state grid tender platforms in China and India, direct utility contracting in Europe, and EPC channel partnerships in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart grid interoperability standards are transforming capacitor procurement from component transactions to platform-ecosystem relationships, with digital twin integration creating winner-take-most dynamics among integrated VAR compensation providers.
For Market Incumbents: Compound technology leadership in alternative gas dielectrics through R&D partnerships with Bavarian testing facilities and ECHA certification pathways. Lock in multi-year framework agreements with State Grid Corporation of China and Power Grid Corporation of India before procurement consolidates around integrated system providers. Prioritize backward integration into aluminum foil and polypropylene film production to defend margin position against raw material volatility.
For New Entrants and Emerging Players: Differentiate on nitrogen-based dry-type designs for urban indoor substations in Netherlands and Denmark where fire safety specifications create premium pricing tiers. Target Vietnam's rural electrification programs and Indonesia's medium-voltage distribution expansion where price-sensitive procurement favors cost-optimized volume production. Pursue joint venture structures with established EPC contractors to bypass direct utility qualification barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European industrial conglomerates seeking to monetize non-core power grid portfolios. Five-to-ten year viability hinges on regulatory compliance capabilities rather than manufacturing scale alone. Monitor ECHA alternative gas dielectric certification timelines as inflection indicator for supplier consolidation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Gas Dielectric R&D Partnership | ECHA certification pathways in Bavaria accelerate SF6-free product commercialization ahead of F-Gas deadlines. |
| Smart Capacitor Monitoring Platform Launch | Embedded VAR control capabilities capture premium pricing from TenneT and 50Hertz transmission operators. |
| Backward Integration into Dielectric Film Production | Captive polypropylene supply insulates margin structures from Shandong export tariff volatility. |
| Multi-Year Framework Agreement Negotiation | State Grid Corporation procurement consolidation favors integrated VAR system providers over component vendors. |
| Digital Twin Integration Partnership | Convergence with grid digitalization platforms enables predictive asset management service revenue streams. |
Research Methodology
A spread of perspectives from utility planning officers, EPC contractor procurement leads, capacitor manufacturing R&D directors, and aftermarket service heads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through IEC standards documentation, FERC Order 2023 regulatory filings, SAMR GB standards enforcement records, and customs trade data for aluminum foil and polypropylene film flows. Bottom-up unit economics triangulated against top-down transmission infrastructure investment forecasts across the analysis window.
Segmentation dimensions modeled include dielectric medium type, deployment environment, intelligence tier, end-use application, and regional regulatory framework cluster. CAGRs were derived from installed base replacement cycles, renewable integration project pipelines, and smart grid capital expenditure trajectories across the projection horizon. Industry-specific forecast inputs incorporated F-Gas Regulation phase-down schedules and China's dual carbon goal enforcement timelines.
Material uncertainties — alternative gas dielectric performance gaps above 400 kV, extended IEC 60871 certification cycles, and raw material export policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance deadlines and utility procurement specification evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Egypt Power EPC Market
Power Equipment
United Arab Emirates Power Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Deaerators Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
United States Power Rental Market
Power Equipment
France Power EPC Market
Power Equipment
Germany Power EPC Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Power Cables Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Wind Tunnel Fans Market