
 Building Integrated Photovoltaics Module Market | 2026-2036
Building Integrated Photovoltaics Module Market Size, Share, and Industry Trends Forecast 2026-2036
Building Integrated Photovoltaics Module Market Insights
The EU Green Deal's phased carbon-performance standards for buildings is decoupling BIPV module procurement from conventional solar economics across European commercial construction. AGC Inc. leverages its float-glass manufacturing scale to supply BIPV glazing at competitive unit costs, while Onyx Solar specializes in transparent photovoltaic glass for curtain-wall applications. Tesla Inc. anchors its position through integrated Solar Roof tiles that bundle generation with structural weatherproofing, reducing contractor coordination costs.
Building Integrated Photovoltaics Modules are photovoltaic elements manufactured to replace conventional building envelope materials—roofs, facades, skylights, or curtain walls—while generating electricity through semiconductor junctions, typically achieving 10-20% conversion efficiency depending on cell architecture. Crystalline silicon modules currently dominate commercial building applications where power density and proven bankability outweigh aesthetic constraints, while thin-film variants occupy niches demanding flexible substrates or semi-transparent visual properties. BIPV roof tiles represent a smaller but structurally distinct segment where product design must satisfy both IEC 61215 electrical standards and roofing-specific wind-load and water-shedding certifications.
EMA's MDR framework and the EU F-Gas Regulation shape product compliance pathways for BIPV modules containing fluorinated polymers, while REACH chemical restrictions influence encapsulant and backsheet material selections across the supply chain. Germany's KBA and France's national building regulators enforce divergent fire-safety classification protocols that fragment certification requirements for cross-border projects. Stakeholders must monitor how the EU AI Act's impending building-automation provisions could mandate predictive energy-management interfaces in next-generation BIPV installations.
Market Dynamics
The EU Green Deal's embodied-carbon thresholds for new construction are forcing commercial developers to treat BIPV modules as structural building materials rather than bolt-on solar equipment, collapsing the traditional procurement boundary between facade engineering and energy systems.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases in conventional HVAC systems pushes building operators toward electrified envelopes where BIPV facades displace gas-heating loads in German and French office developments.
- Heritage retrofit codes:Weight-restricted roof specifications in Italian and Spanish historic districts accelerate thin-film organic photovoltaic adoption where crystalline silicon exceeds structural limits.
- Building automation integration:Demand-side response protocols in Dutch smart-grid pilots create revenue stacking for BIPV-curtain-wall systems that modulate generation with HVAC load patterns.
Market Restraints
- Silicon supply concentration:Polysilicon refining capacity clusters in Xinjiang and Inner Mongolia expose module assemblers to forced-labor due-diligence compliance costs under German Supply Chain Due Diligence Act.
- Fire-safety classification fragmentation:Divergent KBA versus French CSTB testing protocols for roof-integrated systems force dual certification runs, extending time-to-market by 8-14 months for cross-border projects.
- Bankability gaps:Thin-film organic photovoltaics lack the 25-year performance warranties that institutional lenders require for commercial mortgage-backed financing, constraining deployment to self-funded developer balance sheets.
Strategic Opportunities
- CSRD disclosure mandates:Scope 3 emissions reporting requirements for EU-listed real estate investment trusts create pull-through demand for BIPV facades that reduce embodied carbon in new construction portfolios.
- Agrivoltaic building envelopes:Semi-transparent photovoltaic glass in Dutch greenhouse horticulture merges food production with on-site generation, opening a non-building construction vertical.
- Swiss building-energy codes:Canton-level net-zero mandates for commercial retrofits exceed EU baseline stringency, creating premium pricing tolerance for high-transparency BIPV skylight systems in Zurich and Geneva financial districts.
Industry Challenges
- Façade-engineering skill scarcity:BIPV installation requires technicians credentialed in both IEC 61215 electrical standards and CWCT curtain-wall testing protocols, a dual-certification pipeline that German and Austrian trade schools have only begun staffing.
- Encapsulant material compliance:REACH restrictions on perfluorinated compounds in backsheet polymers force reformulation cycles that delay product recertification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Integrated Photovoltaics Module Market |
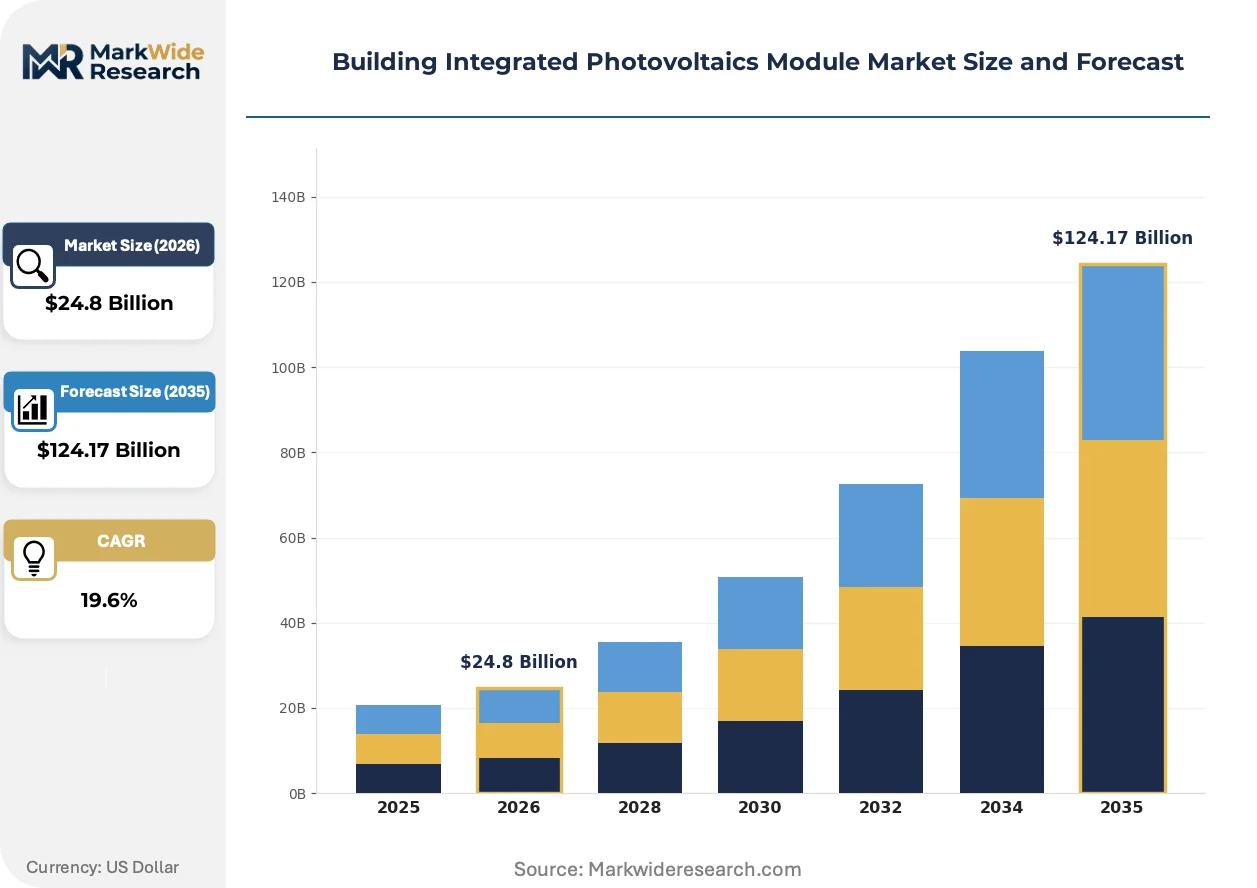
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $124.17 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Crystalline Silicon, BIPV Glass, BIPV Roof Tiles Application: Commercial Buildings, Residential Buildings, Industrial Facilities, Public Infrastructure Installation Type: New Construction, Retrofit, Modular Installation, Integrated Solutions End User: Architects, Contractors, Building Owners, Government Agencies |
| Companies Covered | AGC Inc., Onyx Solar, Heliatek GmbH, Canadian Solar Inc., Tesla Inc., First Solar, Solaria Corporation, Ertex Solartechnik GmbH, Hanergy Holding Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Integrated Photovoltaics Module Market Trends and Innovations
Perovskite-silicon tandem cell architectures are collapsing the efficiency gap between building-integrated and conventional rooftop modules, while regulatory pressure on embodied carbon accelerates material substitution in facade supply chains.
Tandem perovskite-silicon cells are rewriting the performance ceiling for semi-transparent glazing applications. German and Dutch commercial developers now specify 25%-plus conversion efficiency in curtain-wall tenders, a threshold that single-junction crystalline silicon cannot meet. This efficiency compression enables BIPV to displace high-performance low-E glass in premium office towers without sacrificing daylighting ratios.
France's RE2020 thermal regulation and Germany's GEG building energy code now mandate whole-life carbon accounting for new construction. These frameworks penalize high-embodied-carbon cladding systems while exempting BIPV facades from renewable energy surcharges. Dutch project developers respond by bundling BIPV into design-build contracts that transfer performance risk to envelope subcontractors.
Design-build procurement now dominates commercial BIPV deployment in Northern Europe. General contractors absorb technology selection and long-term generation risk, displacing the traditional architect-specifier channel. This consolidation concentrates buying power with Bouygues, Skanska, and Hochtief procurement desks in Paris, Stockholm, and Munich metropolitan clusters.
Building Integrated Photovoltaics Module Market Segmentation
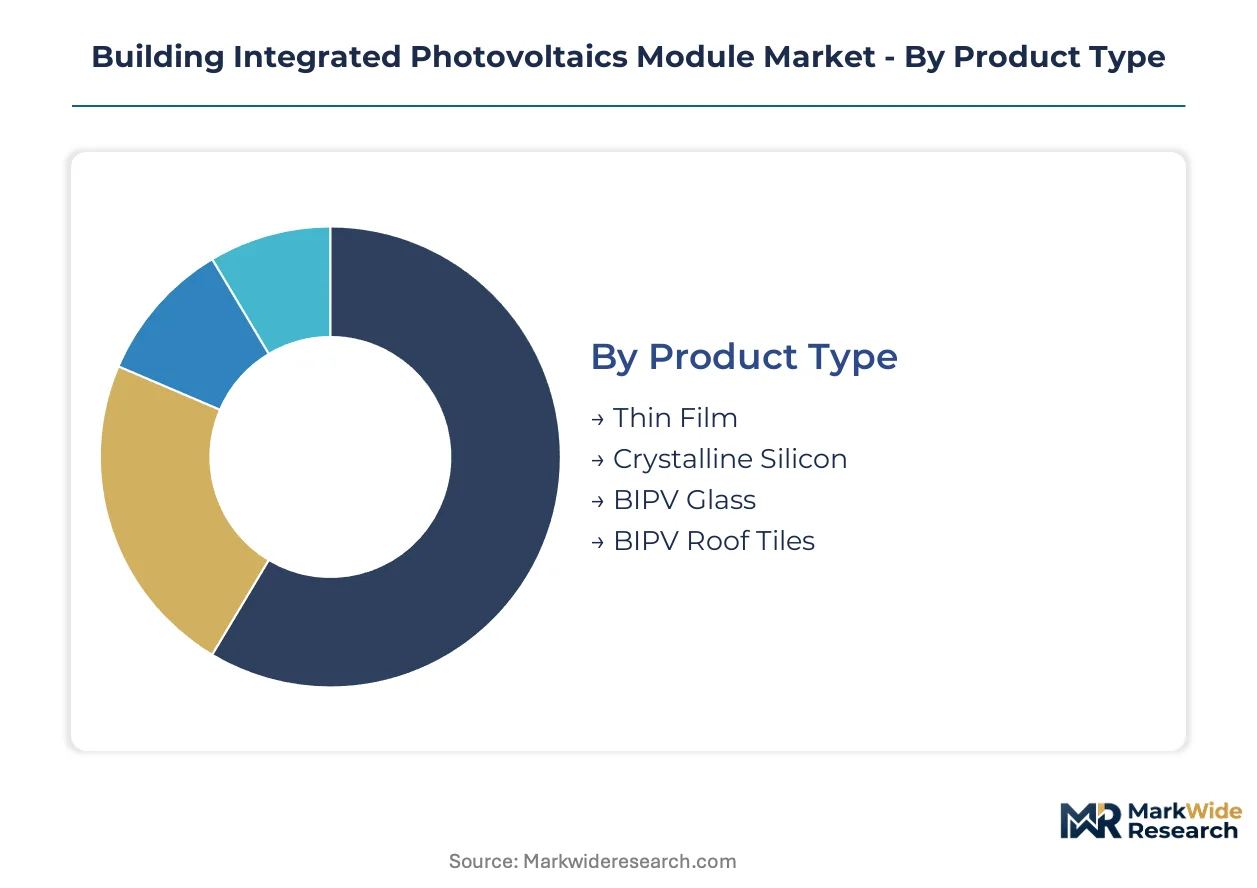
BIPV procurement collapses traditional boundaries between facade engineering and energy systems. Segmentation reveals where capital commitments concentrate and which technical configurations align with tightening embodied-carbon regulations.
Product Type:
Capital intensity varies sharply across cell architectures, with crystalline silicon requiring the heaviest manufacturing infrastructure and thin-film variants demanding specialized deposition equipment.
- Crystalline Silicon:Polycrystalline and monocrystalline cells bonded to glass substrates deliver 15-20% conversion efficiency in standard test conditions. German and Dutch commercial developers specify these modules for curtain-wall projects where power density outweighs visual transparency requirements.
- Thin Film:Cadmium telluride and copper indium gallium selenide layers sputtered onto flexible substrates achieve lower efficiency but reduced weight. Italian and Spanish heritage retrofit codes favor these systems where structural load limits exclude heavier alternatives.
- BIPV Glass:Transparent or semi-transparent photovoltaic glazing integrates generation into skylight and curtain-wall assemblies.
- BIPV Roof Tiles:Solar cells embedded in weatherproof roofing elements must satisfy both IEC 61215 electrical standards and roofing-specific wind-load certifications.
Crystalline silicon absorbs the bulk of installed capacity; thin film is expanding most quickly in weight-restricted applications.
Application:
Commercial building specifications dominate tender volumes, though residential deployment patterns differ sharply in financing structure and performance guarantees.
- Commercial Buildings:Office towers, retail centers, and hospitality structures account for the majority of facade-integrated capacity. RE2020 and GEG codes in France and Germany mandate whole-life carbon accounting that favors BIPV over conventional cladding.
- Residential Buildings:Single-family and multi-family housing applications concentrate in premium new construction segments. Tesla's Solar Roof tiles target this category with bundled weatherproofing and generation, though 25-year warranty requirements constrain thin-film penetration.
- Industrial Facilities:Warehousing and manufacturing structures with large roof spans favor high-power-density crystalline installations.
- Public Infrastructure:Transit stations, schools, and municipal buildings face distinct procurement protocols under EU public procurement directives.
Commercial buildings command the largest project scale; residential applications show the steepest expansion trajectory where integrated roofing products reduce contractor coordination costs.
Installation Type:
New construction allows seamless BIPV integration into design-build contracts, while retrofits face structural and aesthetic constraints that fragment technology selection.
- New Construction:Design-build procurement in Northern Europe bundles BIPV specification into envelope subcontractor responsibilities. Bouygues and Hochtief procurement desks in Paris and Munich metropolitan clusters concentrate buying power for this channel.
- Retrofit:Heritage-sensitive renovations in Italian historic districts accelerate organic photovoltaic adoption where crystalline silicon exceeds weight limits.
- Modular Installation:Prefabricated facade panels with integrated generation enable faster on-site assembly.
- Integrated Solutions:Turnkey packages combining BIPV with building automation and energy management systems.
New construction captures the majority of project value; retrofit installations are climbing the fastest as EU Green Deal embodied-carbon thresholds tighten for existing building stock.
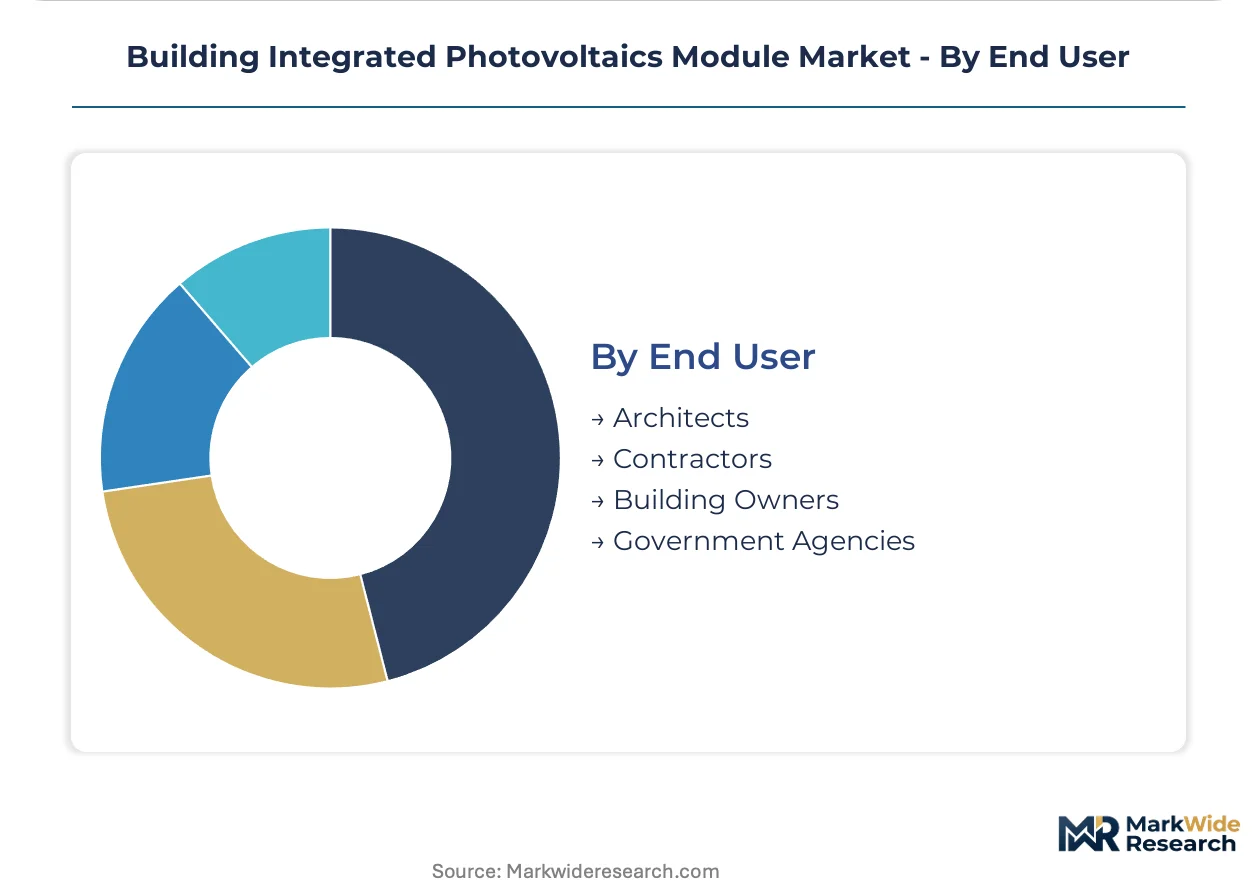
End User:
Procurement authority has shifted from architect-specifiers toward general contractor procurement desks, concentrating technical selection power with fewer decision nodes.
- Architects:Façade-engineering skill scarcity constrains specification capacity; German and Austrian trade schools have only begun staffing dual-certification pipelines in IEC 61215 electrical standards and CWCT curtain-wall testing protocols.
- Contractors:Design-build dominance transfers performance risk to envelope subcontractors who absorb technology selection and long-term generation guarantees.
- Building Owners:CSRD disclosure mandates for EU-listed real estate investment trusts create direct pull-through demand for embodied-carbon reduction.
- Government Agencies:Public procurement frameworks under EU directives shape tender specifications for infrastructure projects.
Contractors now control the majority of technical selection; building owners are gaining influence fastest through sustainability-linked financing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module assembly clusters in East Asia while deployment concentrates in European commercial construction. Germany and the Netherlands import crystalline silicon cells for facade integration. French and Italian project pipelines absorb thin-film variants for heritage-sensitive applications.
Germany
Commercial office towers in Frankfurt and Munich drive crystalline silicon curtain-wall specifications. The GEG building energy code mandates whole-life carbon accounting that exempts BIPV facades from renewable energy surcharges. The Rhine-Ruhr metropolitan cluster hosts envelope subcontractors bundling BIPV into design-build contracts for Hochtief procurement desks.
France
RE2020 thermal regulations penalize high-embodied-carbon cladding in Paris and Lyon commercial developments. The CSTB fire-safety classification protocol diverges from German KBA standards, forcing dual certification runs for cross-border projects. Bouygues procurement desks in the Île-de-France region concentrate technical selection power for facade-integrated systems.
Netherlands
Smart-grid demand-side response pilots in Amsterdam and Rotterdam create revenue stacking for BIPV-curtain-wall modulation. The EU F-Gas Regulation phasedown pushes building operators toward electrified envelopes. Dutch greenhouse horticulture in Westland deploys semi-transparent photovoltaic glass for agrivoltaic building envelopes.
Italy
Heritage retrofit codes in Rome and Florence restrict roof loads, accelerating organic photovoltaic adoption where crystalline silicon exceeds structural limits. Weight-restricted specifications favor thin-film flexible substrates for historic district renovations. Northern Italian industrial zones supply encapsulant materials subject to REACH perfluorinated compound restrictions.
Switzerland
Canton-level net-zero mandates for commercial retrofits in Zurich and Geneva exceed EU baseline stringency. Swissmedic-equivalent building regulators enforce premium pricing tolerance for high-transparency BIPV skylight systems. The Basel pharmaceutical corridor generates demand for facade-integrated generation in laboratory and office assets.
Building Integrated Photovoltaics Module Market Competitive Landscape
The competitive structure tilts toward glass-manufacturing incumbents with float-glass scale advantages. Crystalline silicon specialists and thin-film organic innovators occupy parallel technology lanes with limited overlap. Three archetypes dominate: integrated building-material conglomerates, pure-play photovoltaic glass specialists, and energy-system integrators bundling generation with structural weatherproofing. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with design-build procurement consolidation concentrating buying power with fewer envelope subcontractors.
Among glass-manufacturing incumbents, AGC Inc. exemplifies the scale-driven archetype through captive float-glass supply chains. Onyx Solar and Heliatek GmbH occupy positions within the specialization tier, representing transparent photovoltaic glass and organic thin-film variants respectively. Tesla Inc. anchors the energy-system integrator archetype, bundling roof tiles with generation and structural performance. These three companies collectively illustrate how procurement channel consolidation favors players controlling multiple value-chain stages.
| Leading Market Players |
|---|
| AGC Inc. |
| Onyx Solar |
| Heliatek GmbH |
| Canadian Solar Inc. |
| Tesla Inc. |
| First Solar |
| Solaria Corporation |
| Ertex Solartechnik GmbH |
| Hanergy Holding Group Limited |
| Others |
Pricing and Supply Chain Analysis
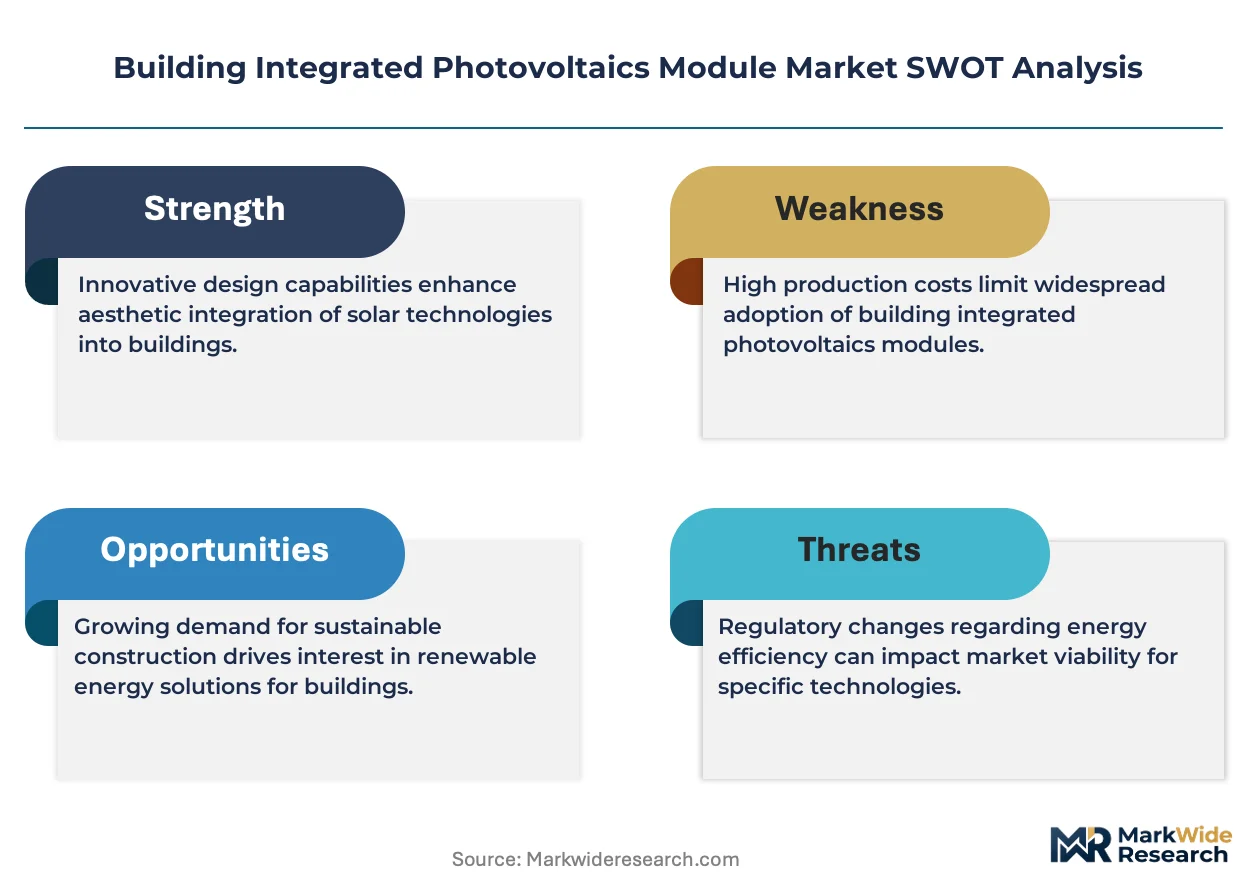
Design-build procurement consolidation across German and French commercial construction forces envelope subcontractors to absorb technology selection risk and long-term generation guarantees, compressing margins for module assemblers while rewarding glass-manufacturing incumbents with captive float-glass supply chains.
Pricing Analysis
Performance-guarantee pricing anchors BIPV module valuation, with crystalline silicon commanding premiums tied to IEC 61215 certification tier and bankable 25-year warranties that satisfy institutional lender requirements for commercial mortgage-backed financing. Three-tier pricing structure across premium certified, standard compliant, and economy uncertified levels separates facade-integrated systems by fire-safety classification and thermal performance. Pricing pressure stems from polysilicon refining concentration in Xinjiang and Inner Mongolia exposing assemblers to forced-labor due-diligence compliance costs under German Supply Chain Due Diligence Act. Building owners and contractors exhibit divergent sensitivity: REITs pursuing CSRD disclosure mandates prioritize embodied-carbon reduction over unit cost, while speculative developers in Southern European markets remain highly price-elastic.
Supply Chain Analysis
End-of-life module recovery and encapsulant material refurbishment flows remain underdeveloped across European BIPV installations, creating stranded asset risks as REACH restrictions on perfluorinated compounds force reformulation cycles. Polysilicon refining concentrates in China, module assembly clusters in Malaysia and Vietnam, and float-glass manufacturing anchors in Belgium and Germany. High-purity silicon metal, fluorinated polymer backsheet materials, and low-iron solar glass constitute critical input dependencies. Single-source vulnerability in polysilicon supply exposes assemblers to tariff exposure and forced-labor documentation requirements. Distribution runs through design-build procurement desks at Bouygues, Hochtief, and Skanska, concentrating buying power with envelope subcontractors who bundle BIPV specification into turnkey facade contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Façade-engineering skill scarcity constrains installation capacity, propping pricing power for dual-certified technicians and envelope subcontractors who control technical selection in consolidated procurement channels.
For Market Incumbents: Deepen backward integration into float-glass manufacturing to defend margin position against AGC Inc.'s scale advantages, while accelerating perovskite-silicon tandem cell R&D to capture premium specifications for 25%-plus efficiency curtain-wall tenders. Invest in dual-certification training pipelines with German and Austrian trade schools to alleviate technician scarcity that threatens deployment timelines. For New Entrants and Emerging Players: Perovskite-silicon tandem architectures offer a technology-first wedge into premium commercial glazing specifications where single-junction crystalline silicon cannot meet daylighting-ratio requirements. Target Swiss canton-level net-zero retrofit mandates in Zurich and Geneva financial districts, where premium pricing tolerance exceeds EU baseline stringency. Pursue agrivoltaic greenhouse horticulture partnerships in Dutch Westland as a non-building construction vertical with distinct procurement protocols. For Investors and Strategic Acquirers: The window for entry favors glass-manufacturing incumbents with captive float-glass supply chains and envelope subcontractors controlling design-build procurement channels. Long-term viability hinges on embodied-carbon accounting permanence in EU construction codes. Monitor German KBA and French CSTB fire-safety classification harmonization negotiations as an inflection indicator for cross-border certification cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Scale-Up | Enables 25%-plus efficiency specifications that displace high-performance low-E glass in premium office towers. |
| Dual-Certification Training Partnerships | Addresses technician scarcity in IEC 61215 electrical standards and CWCT curtain-wall testing protocols. |
| Float-Glass Capacity Expansion | Replicates AGC Inc.'s captive supply chain model to secure competitive unit costs in BIPV glazing. |
| Agrivoltaic Greenhouse Horticulture Partnerships | Opens non-building construction vertical in Dutch Westland merging food production with on-site generation. |
| Fire-Safety Classification Harmonization Lobbying | Reduces dual certification burden between German KBA and French CSTB protocols for cross-border projects. |
Research Methodology
Multi-period observation of BIPV tender volumes, embodied-carbon regulation implementation timelines, and design-build procurement contract structures anchored the trend analysis, supplemented by interviews with envelope subcontractor procurement managers, facade engineering consultants, glass-manufacturing supply chain directors, and commercial real estate sustainability officers. Secondary validation drew from EU Green Deal implementation documents, ECHA REACH restriction updates, German KBA and French CSTB fire-safety protocols, and CSRD disclosure guidance materials. Bottom-up project pipeline tracking across Frankfurt, Munich, Paris, Lyon, Amsterdam, and Rotterdam metropolitan clusters triangulated with top-down module production and trade flow analysis.
Input-output matrix modeling connected polysilicon refining capacity, float-glass manufacturing output, and certified technician supply to deployment forecasts across the projection horizon. Segmentation dimensions included cell architecture, application type, installation category, and end-user procurement authority. CAGRs derived from regression analysis of historical tender volumes against regulatory threshold implementation schedules, incorporating perovskite-silicon tandem efficiency improvement curves and EU F-Gas Regulation phasedown impacts on electrified envelope demand.
Several conditions sit outside the modeled scope, including unannounced revisions to EU AI Act building-automation provisions, abrupt REACH restrictions on alternative encapsulant chemistries, and geopolitical disruptions to polysilicon supply chains. Forecasts reflect documented assumptions about regulatory permanence and technology cost reduction trajectories. Practitioners should monitor German-French fire-safety protocol harmonization progress and perovskite stability certification milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market
Solar Power Systems
Solar Module Market