
 Off-Grid Solar Energy Market | 2026-2036
Off-Grid Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Grid Solar Energy Market Analytics
IEC 61215 certification for crystalline silicon terrestrial photovoltaic modules is unwinding competitive access for smaller assemblers in off-grid solar supply chains. Canadian Solar leverages vertically integrated wafer-to-module capacity to sustain cost leadership in emerging-market distributed projects. Greenlight Planet anchors its position through pay-as-you-go financing platforms that control last-mile customer relationships across East Africa. Schneider Electric differentiates through integrated energy management systems that combine solar generation with storage and smart load control.
Off-grid solar energy systems comprise photovoltaic arrays, electrochemical storage, power conditioning electronics, and load management hardware configured to operate independently from centralized grid infrastructure. These systems typically employ 12V or 24V DC architectures with 50–200Wp panel ratings and 20–100Ah lithium-ion or lead-acid battery banks to deliver reliable electricity to unelectrified or intermittently served locations. The product type dimension shows batteries capturing expanding margin pools as lithium-ion chemistries displace lead-acid in premium installations, while inverters represent the fastest-growing component category as hybrid system architectures gain traction. End user segmentation reveals agricultural pumping and cold chain applications outpacing basic residential lighting in revenue intensity, though residential volumes remain dominant in absolute unit terms.
Lighting Global quality standards and the World Bank's Scaling Solar program shape product certification requirements and concessional finance availability for off-grid solar deployment in target countries. India's Ministry of New and Renewable Energy implements the PM-KUSUM scheme through CEA technical specifications that mandate domestic content for agricultural solar pumps, while Kenya's Rural Electrification Authority operates under Energy Regulatory Authority rules governing mini-grid tariffs and licensing. Stakeholders must monitor evolving battery recycling mandates and carbon border adjustment mechanisms that will reshape component sourcing economics and end-of-life liability structures.
Market Dynamics
Lithium-ion battery chemistry improvements are decomposing the cost-performance tradeoffs that historically constrained off-grid solar deployment in remote agricultural and residential segments.
Growth Catalysts
- PM-KUSUM Scheme:India's agricultural pump electrification mandate under CEA specifications is pulling demand for DC solar pumping systems through domestic content requirements.
- Kenya Rural Electrification Authority:Mini-grid licensing frameworks and standardized tariff structures are accelerating private capital deployment into pay-as-you-go solar home systems.
- Lithium iron phosphate (LFP) cathodes:Improved cycle life and thermal stability are extending battery bank replacement intervals from three to eight years in premium installations.
Market Restraints
- Cobalt and lithium carbonate volatility:Raw material price swings in the DRC and Chilean supply chains are compressing margins for battery pack assemblers serving price-sensitive African markets.
- IEC 61215 certification costs:Third-party testing and factory audit requirements are excluding smaller module assemblers from Lighting Global quality-verified procurement pools.
- Diesel generator substitution:Backup power systems remain entrenched in commercial cold chain and telecom tower applications where load reliability requirements exceed solar-plus-storage duty cycles.
Strategic Opportunities
- Nigeria's Solar Power Naija initiative:Five million solar home system connections by rural electrification agencies are creating last-mile financing partnerships for PAYGO platforms.
- Agricultural cold chain integration:Solar-powered refrigeration units are penetrating post-harvest storage networks where grid extension timelines exceed five years.
- Blockchain-enabled energy trading:Peer-to-peer electricity exchange protocols are converging with smart meter infrastructure to enable village-scale mini-grid autonomy.
Industry Challenges
- Battery recycling infrastructure:End-of-life lithium-ion collection and black mass processing capabilities remain undeveloped across sub-Saharan Africa, creating future liability exposure for original equipment suppliers.
- Field technician certification:Standardized training programs for DC system installation and fault diagnosis are fragmented across national vocational frameworks, constraining service network scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Grid Solar Energy Market |
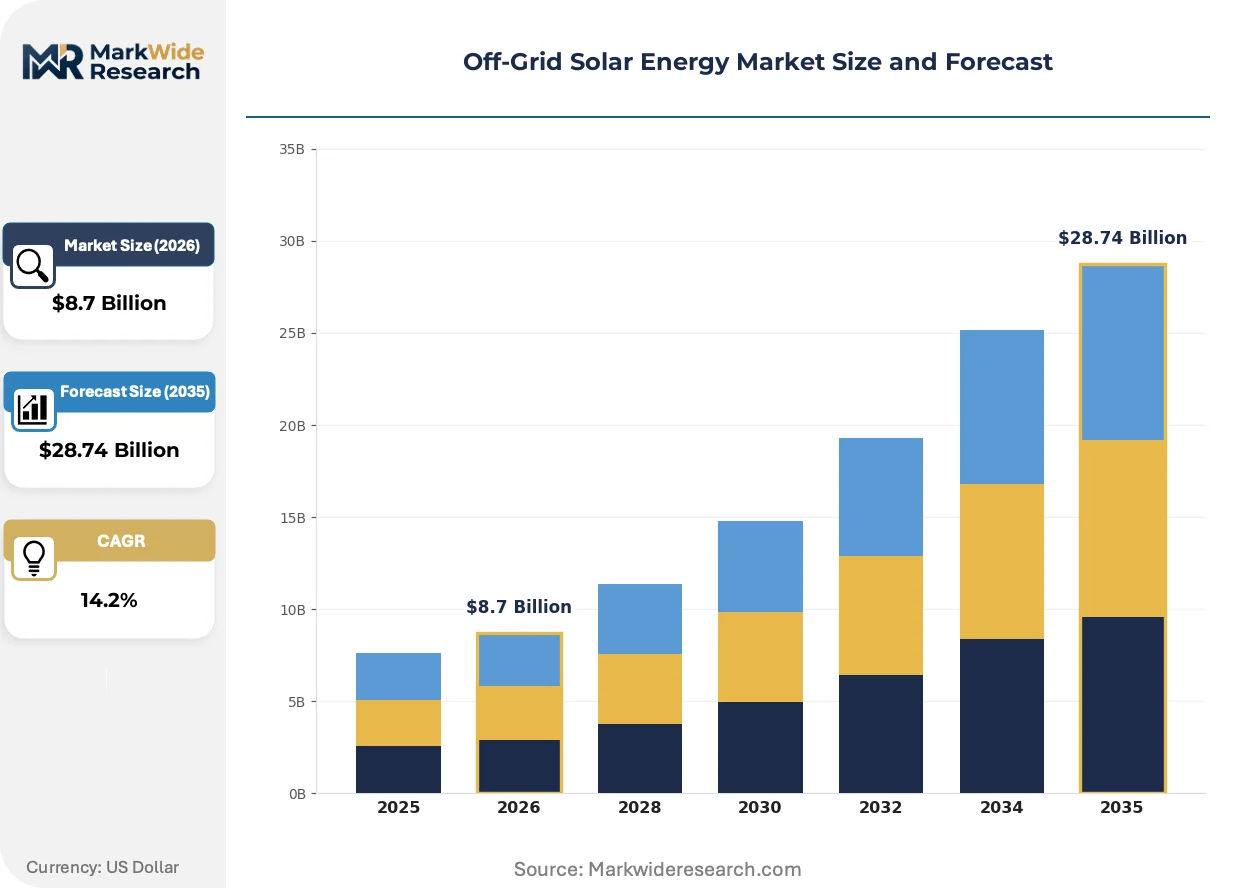
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Batteries, Inverters, Charge Controllers End User: Residential, Commercial, Industrial, Agricultural Installation Type: Standalone, Hybrid, Portable, Fixed Application: Lighting, Water Pumping, Heating, Refrigeration |
| Companies Covered | Canadian Solar, Schneider Electric, SMA Solar Technology, Greenlight Planet, JinkoSolar Holding, SunPower Corporation, ABB, Delta Electronics, Engie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Grid Solar Energy Market Evolving Landscape
Modular system architectures and digital financing platforms are compressing deployment timelines and reshaping customer acquisition economics across unelectrified regions.
Perovskite-silicon tandem cell research is decomposing the efficiency ceiling that has constrained polycrystalline modules in low-light tropical conditions. Agricultural irrigation cooperatives in Kenya are piloting these higher-wattage panels for daytime pumping loads. The technology is decomposing the panel surface area requirements for fixed-roof residential installations, reducing mounting hardware and transport costs.
EU Battery Regulation mandatory carbon footprint declarations are forcing supply chain documentation from cell manufacturers serving African and South Asian markets. Industrial consequence includes accelerated migration from virgin cobalt to recycled content and synthetic graphite alternatives. East African distributors are responding by sourcing from Chinese cell producers with verified lifecycle assessment data.
Customer acquisition through mobile money integration is replacing cash-and-carry hardware sales in rural Kenya and Nigeria. PAYGO platforms are capturing end-user payment history data that enables credit scoring for productive use appliance financing. This behavioral shift is most visible in dairy cold chain and small milling operations where revenue-linked repayment schedules align with harvest cycles.
Off-Grid Solar Energy Market Segmentation
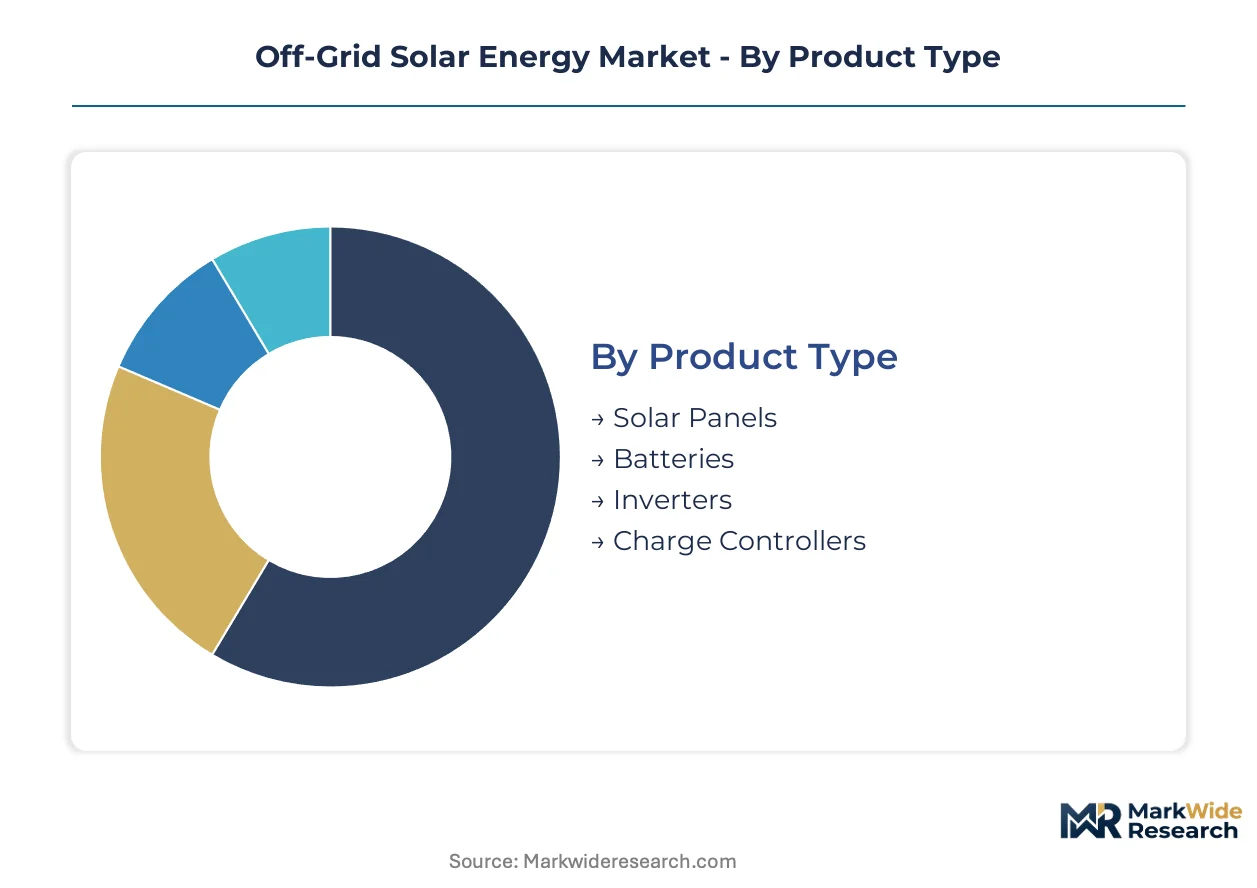
Segmentation reveals how technology choices, user economics, and deployment constraints fragment the off-grid solar value chain. Each dimension carries distinct margin profiles and channel access requirements that reshape competitive positioning.
Product Type:
Solar panels move through Lighting Global-verified procurement pools, batteries flow via PAYGO platform partnerships, and inverters reach customers through integrated system bundlers.
- Solar Panels:Crystalline silicon modules rated 50–200Wp dominate unelectrified residential installations. Kenya's Rural Electrification Authority and India's MNRE channel subsidized volumes through certified vendor lists, while uncertified assemblers face IEC 61215 exclusion.
- Batteries:Lithium-ion banks with LFP cathodes displace lead-acid in premium agricultural and commercial cold chain applications. Extended cycle life from three to eight years reduces replacement frequency for Nigerian Solar Power Naija beneficiaries.
- Inverters:Power conditioning electronics bridge DC generation with AC loads in hybrid architectures.
- Charge Controllers:MPPT and PWM variants regulate battery charging profiles across standalone installations.
Solar panels dominate installed base. Batteries are where expansion concentrates.
End User:
Cost tiers separate basic lighting customers from productive-use adopters, with revenue intensity climbing sharply across the spectrum.
- Residential:Solar home systems with 12V or 24V DC architectures serve unelectrified households through PAYGO financing. East African mobile money integration enables credit-scored appliance upgrades beyond basic lighting.
- Agricultural:Solar-powered irrigation pumps and cold chain units command premium pricing aligned with harvest revenue cycles. Kenya's agricultural cooperatives pilot higher-wattage panels for daytime pumping loads.
- Commercial:Small milling operations and retail shops adopt revenue-linked repayment schedules.
- Industrial:Telecom towers and processing facilities require hybrid backup where solar duty cycles fall short.
Residential volumes anchor unit shipments. Agricultural applications are climbing the fastest.
Installation Type:
Volume concentration favors fixed rooftop systems, while portability unlocks nomadic and emergency use cases with distinct logistics requirements.
- Standalone:Fully independent systems without grid connection serve permanently off-grid locations.
- Hybrid:Grid-interactive configurations with battery backup address intermittently served areas.
- Portable:Mobile units serve pastoral communities and disaster response where fixed infrastructure is impractical.
- Fixed:Permanent rooftop or ground-mounted arrays capture the majority of rural electrification program deployment.
Fixed systems dominate installed base. Hybrid configurations are gaining share fastest.
Application:
Customer maturity varies sharply across use cases, with lighting representing established demand and refrigeration capturing emerging margin pools.
- Lighting:Basic LED illumination remains the entry-point application for solar home system adoption. PAYGO platforms in Nigeria and Kenya built initial customer relationships through lighting-as-a-service models.
- Refrigeration:Solar-powered cold chain units penetrate post-harvest storage networks where grid extension timelines exceed five years. Dairy cooperatives in Kenya link repayment schedules to milk revenue cycles.
- Water Pumping:DC solar pumps under India's PM-KUSUM scheme displace diesel irrigation across agricultural states.
- Heating:Thermal applications remain nascent outside institutional cooking and water heating installations.
Lighting dominates installed base. Refrigeration is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rural electrification mandates across sub-Saharan Africa and South Asia are channeling concessional finance toward decentralized solar deployment. National agencies in Kenya, Nigeria, and India prioritize last-mile connectivity through standardized procurement frameworks. These programs concentrate demand in agricultural corridors where grid extension timelines exceed economic viability.
Kenya
Pay-as-you-go solar home systems penetrate the Rift Valley through mobile money-enabled repayment schedules. The Rural Electrification Authority operates under Energy Regulatory Authority licensing rules that standardize mini-grid tariffs for private capital. Kisumu and Mombasa anchor distribution networks where agricultural cooperatives pilot higher-wattage panels for daytime irrigation loads.
Nigeria
The Solar Power Naija initiative targets five million connections through rural electrification agency procurement. Central Bank of Nigeria intervention facilities provide naira-denominated credit lines for local assembly operations. Kano and Lagos corridor distributors source lithium-ion battery packs from Chinese cell producers with verified carbon footprint documentation under EU Battery Regulation compliance pathways.
India
PM-KUSUM scheme mandates displace diesel pumps across Maharashtra and Gujarat agricultural belts. Central Electricity Authority technical specifications enforce domestic content requirements for solar pumping systems. Tamil Nadu and Karnataka manufacturing clusters capture module assembly volumes through backward integration into cell and wafer production.
Ethiopia
Ethiopian Electric Utility rural electrification programs prioritize standalone systems in Somali and Afar pastoral regions. Ministry of Water and Energy directives channel development finance toward productive use applications. Addis Ababa anchors import logistics for battery and electronics components serving highland agricultural zones.
Tanzania
Rural Energy Agency mini-grid tenders attract private operators to Lake Victoria fishing communities. Energy and Water Utilities Regulatory Authority frameworks govern standardized connection charges and lifeline tariffs. Dodoma and Mwanza distribution hubs coordinate field technician networks for DC system installation and maintenance.
Off-Grid Solar Energy Market Competitive Landscape
Listed leaders compete with private specialists across financing platform and integrated system architectures. The vendor base fragments between crystalline silicon module producers, lithium-ion battery pack assemblers, and pay-as-you-go platform operators. Three archetypes dominate: vertically integrated wafer-to-module manufacturers, last-mile financing specialists controlling customer relationships, and integrated energy management providers combining generation with storage and load control. Capacity expansion in cell manufacturing and strategic partnerships with mobile money operators represent the dominant competitive moves.
Within the integrated energy management tier, Schneider Electric exemplifies the European multinational archetype combining power electronics with smart load control. Canadian Solar occupies a position representing Chinese-listed module producers with captive wafer capacity. Greenlight Planet anchors the private specialist archetype through pay-as-you-go financing platforms that control last-mile customer relationships across East African markets.
| Leading Market Players |
|---|
| Canadian Solar |
| Schneider Electric |
| SMA Solar Technology |
| Greenlight Planet |
| JinkoSolar Holding |
| SunPower Corporation |
| ABB |
| Delta Electronics |
| Engie |
| Others |
Value Network & Pricing Analysis
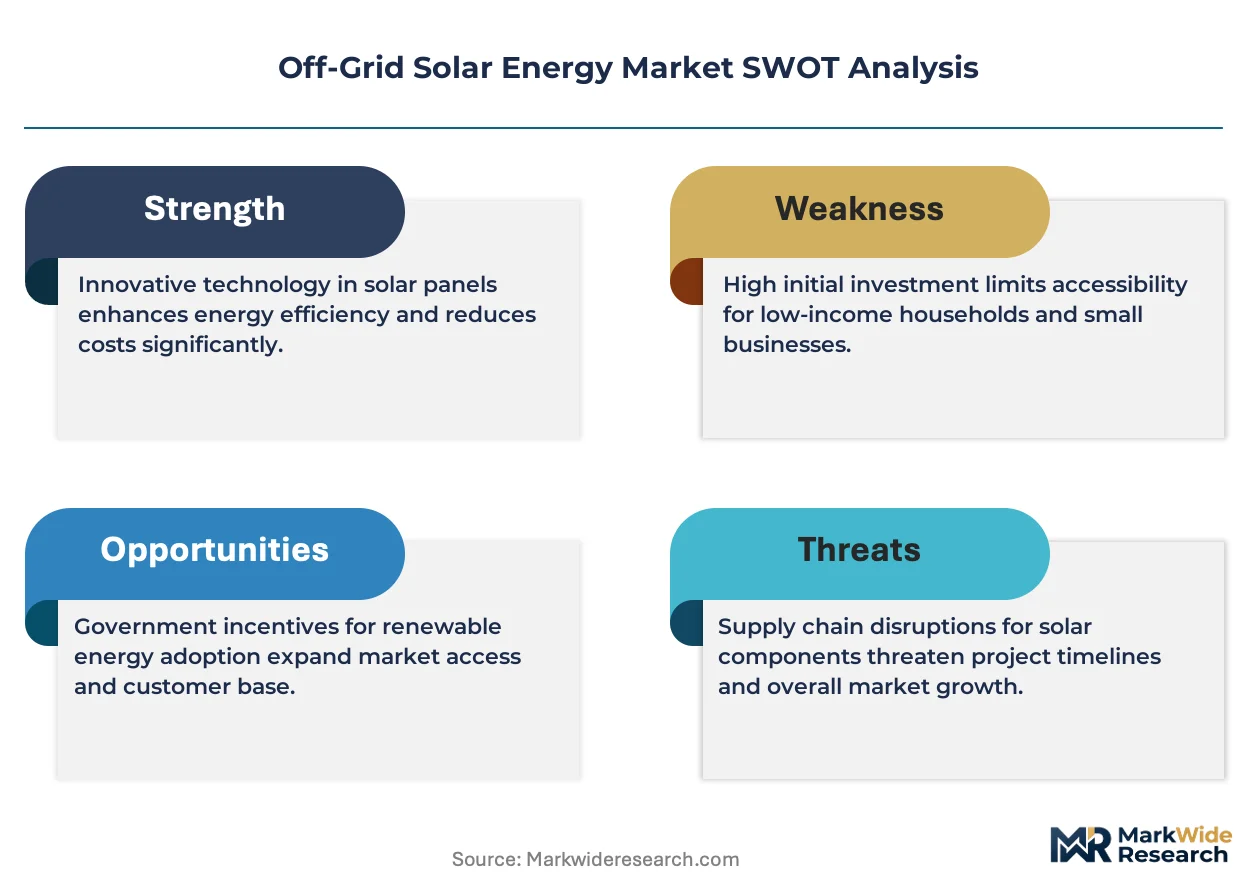
IEC 61215 certification gates both supply qualification and price differentiation simultaneously, excluding uncertified module assemblers from Lighting Global procurement pools while enabling certified vendors to command premiums for verified reliability in Kenyan and Nigerian rural electrification programs.
Pricing Analysis
Certification level creates the primary spread across the value chain, with Lighting Global-verified modules commanding 15-25% premiums over uncertified alternatives in Kenyan PAYGO channels. Three-tier pricing structure separates premium LFP battery banks with eight-year cycle life from standard lithium-ion and economy lead-acid alternatives. Cost compression in entry-level residential systems is intensifying because Chinese cell producers with verified carbon footprint documentation are flooding Nigerian distributor channels. Agricultural pumping customers exhibit lowest price sensitivity due to harvest-linked revenue cycles, while basic lighting households in Ethiopia remain most cost-constrained.
Supply Chain Analysis
China anchors wafer and cell production for crystalline silicon modules, while South Korea and Japan supply precision power electronics for hybrid inverter architectures. The value chain draws from Chilean lithium carbonate, DRC cobalt, and Malaysian semiconductor packaging for battery management systems. Single-source vulnerability concentrates in Chinese LFP cathode active material, where any export restriction would cascade through East African PAYGO platform inventory. Distribution runs through Nairobi and Lagos hub-and-spoke networks that coordinate last-mile technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Off-grid solar incumbents face sustained substitution pressure from diesel generator retention in commercial cold chain and telecom tower applications where load reliability requirements exceed current solar-plus-storage duty cycles.
For Market Incumbents: Shield margin pools in agricultural cold chain by deepening backward integration into LFP battery pack assembly and securing exclusive PAYGO platform partnerships in Kenya's Rift Valley. Diesel generator substitution in Nigerian telecom towers represents the most acute threat requiring hybrid system architecture investment.
For New Entrants and Emerging Players: Anchor in Ethiopia's Somali and Afar pastoral regions where standalone portable systems serve nomadic communities outside fixed infrastructure economics. Blockchain-enabled peer-to-peer energy trading protocols offer the most penetrable white-space for village-scale mini-grid autonomy without incumbent financing platform entrenchment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across lithium-ion battery pack assembly as Chinese cell producers expand verified lifecycle assessment capacity. Long-term viability favors platform operators controlling last-mile customer payment data over pure hardware manufacturers. Watch for EU Battery Regulation carbon border enforcement as the signal indicating margin compression for non-compliant supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LFP Cell Manufacturing | Captures margin pools in premium agricultural installations with eight-year replacement cycles. |
| PAYGO Platform Partnership Expansion | Locks last-mile customer relationships through mobile money-integrated repayment schedules in Kenya. |
| Lighting Global Certification Investment | Unlocks access to World Bank Scaling Solar concessional finance and national procurement pools. |
| Carbon Footprint Documentation Compliance | Preserves EU Battery Regulation market access for Chinese cell suppliers serving African distributors. |
| Agricultural Cold Chain System Bundling | Aligns revenue-linked repayment with harvest cycles for dairy cooperatives in Kenya and Nigeria. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including Rural Electrification Authority procurement officers, PAYGO platform credit risk managers, lithium-ion battery pack assemblers, and agricultural cooperative irrigation specialists. Secondary validation drew from CEA technical specifications, Energy Regulatory Authority licensing frameworks, Lighting Global quality verification databases, and IEC certification registries. Bottom-up unit shipment modeling triangulated against top-down concessional finance disbursement tracking.
Across the analysis window, the forecasting framework modeled product type segmentation by component margin profile, end user segmentation by revenue intensity tier, installation type by grid-interaction architecture, and application by customer maturity stage. CAGRs were derived from regression analysis of historical deployment velocities against rural electrification agency target trajectories. Key inputs included lithium carbonate price volatility indices and mobile money penetration rates by national corridor.
Material uncertainties — raw material price swings in Chilean and DRC supply chains, battery recycling mandate enforcement timelines, and carbon border adjustment mechanism scope expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions about PAYGO platform default rates and national electrification agency procurement continuity. Recalibration cycles align with material shifts in concessional finance availability and lithium-ion chemistry cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Solar Module Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Residential Solar Energy Market