
 Liquid Metal Battery Market | 2026-2036
Liquid Metal Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Metal Battery Market Foresight
Utility procurement is hardening as the dominant demand vector for liquid metal batteries, displacing earlier pilot-phase reliance on research grants. Ambri Inc. leverages its calcium-antimony chemistry platform to anchor long-duration storage deployments in the southwestern United States. Sumitomo Electric Industries sustains manufacturing scale advantages through integrated magnesium sourcing and in-house electrode production. NGK Insulators competes via established sodium-sulfur expertise that translates into liquid metal thermal management capabilities.
Liquid metal batteries electrochemically store energy through molten metal electrodes separated by molten salt electrolytes, operating at elevated temperatures to maintain metallic liquidity and ionic conductivity. The architecture eliminates solid-state degradation mechanisms, enabling decade-scale cycle life for grid-scale buffering. Sodium-based batteries dominate current deployment volumes due to abundant feedstock availability and established supply chains. Energy storage systems applications command the deepest margin pools, while grid stabilization represents the fastest-growing segment as transmission operators procure inertia-equivalent services. Advanced electrode coatings differentiate performance tiers across product categories.
The US Federal Energy Regulatory Commission's Order 841 mandates storage participation in wholesale markets, while the EPA's power plant rules indirectly accelerate zero-emission peaking capacity procurement. China's Ministry of Ecology and Environment enforces dual carbon compliance timelines that force provincial grid operators into long-duration storage contracting. Stakeholders must monitor evolving chemistry-specific safety standards and thermal runaway testing protocols as scale-up outpaces codified certification frameworks.
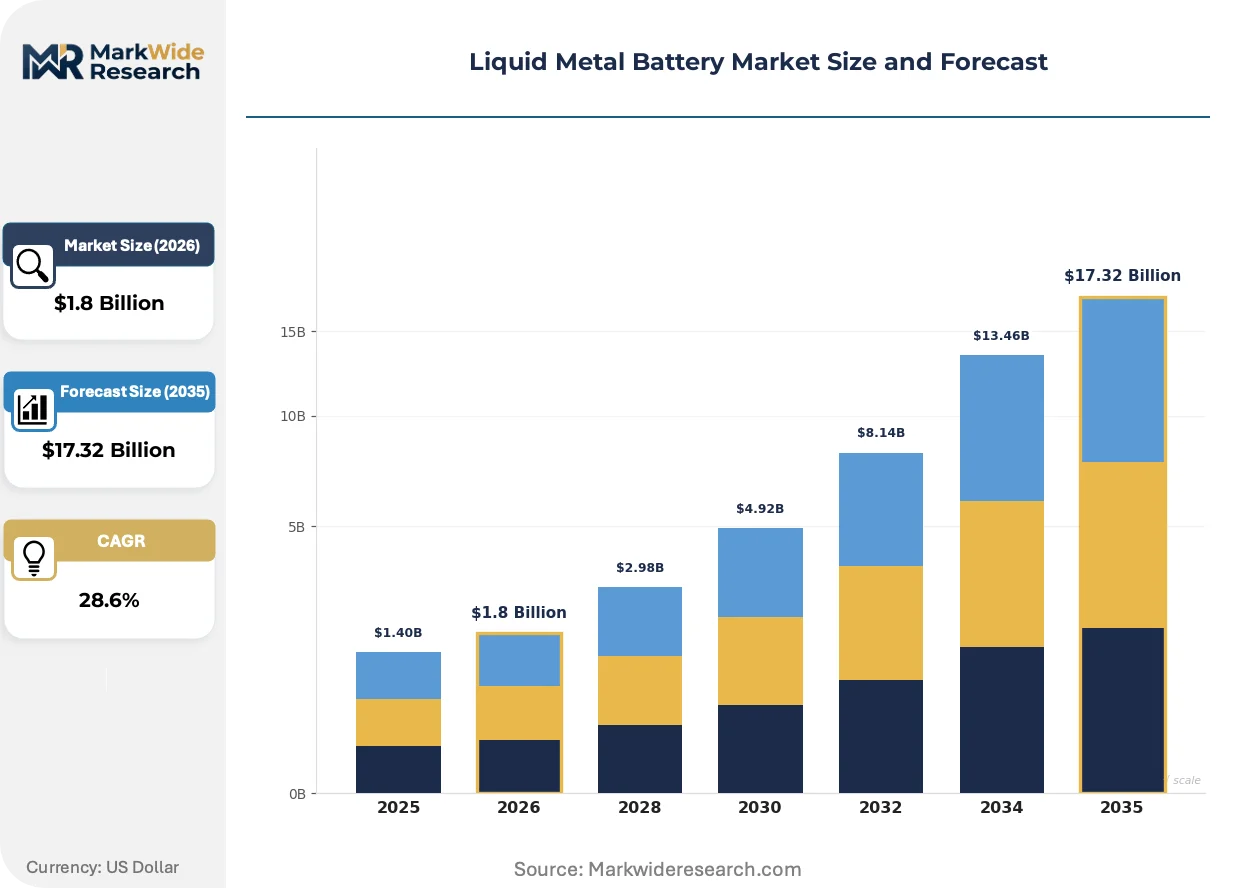
Market Dynamics
Utility-scale procurement mandates are compressing technology validation timelines as grid operators in California, Germany, and China's Gansu province issue multi-gigawatt-hour tenders for 8-12 hour discharge duration. This demand acceleration is forcing chemistry platforms from pilot demonstration into commercial manufacturing scale before full certification maturity.
Growth Catalysts
- US Inflation Reduction Act storage tax credits:The investment tax credit structure de-risks front-of-meter deployments for independent power producers and vertically integrated utilities seeking long-duration assets.
- Renewable curtailment economics:Wind and solar penetration above 40% annual share in high-renewable grids creates negative pricing hours that liquid metal batteries arbitrage through multi-cycle daily operation.
- Molten salt electrolyte stability:The elimination of solid-electrolyte interphase degradation enables 15-20 year operational life without capacity fade, reducing levelized cost of storage against lithium-ion alternatives.
Market Restraints
- Calcium-antimony feedstock concentration:Antimony refining capacity concentrates in China and Tajikistan, exposing electrode manufacturers to export quota volatility and geopolitical supply disruption.
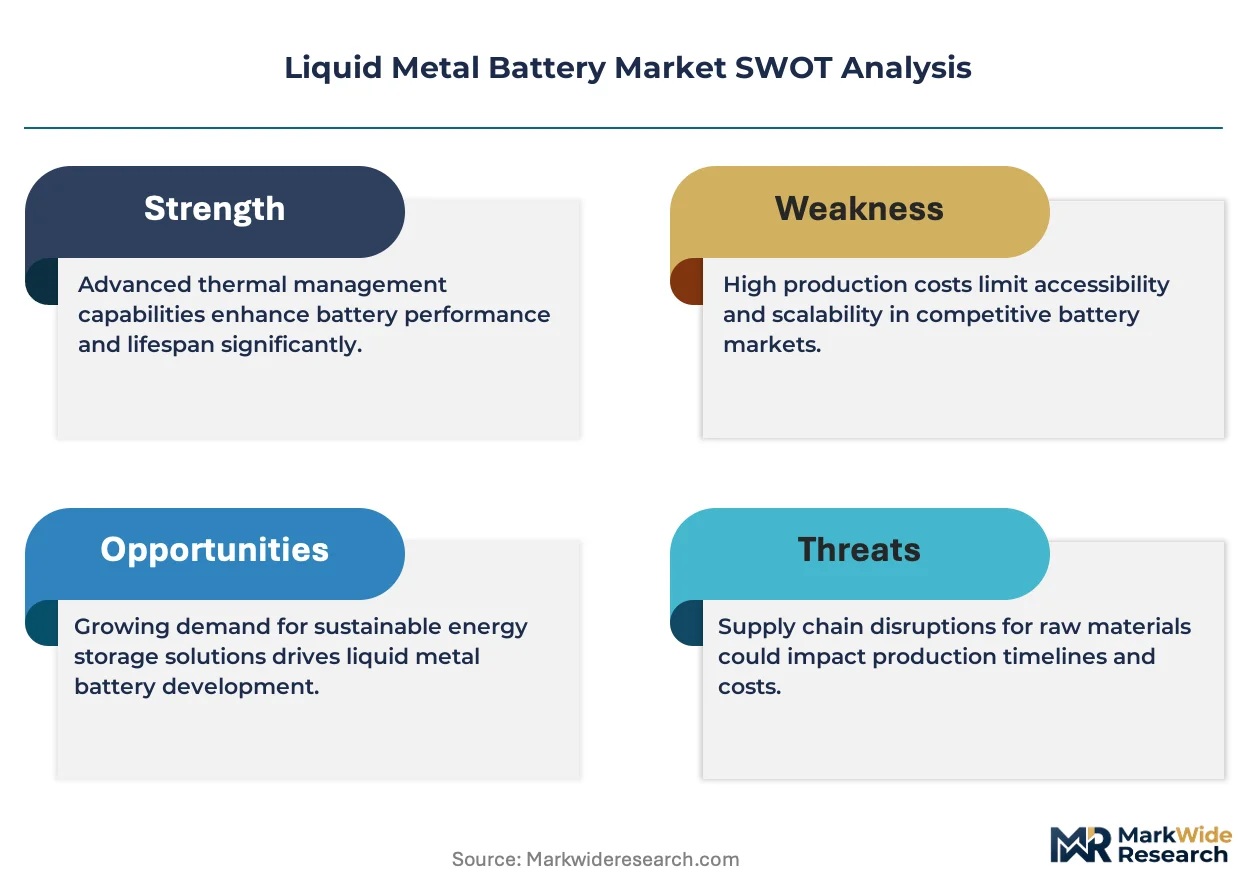
- Thermal management capex intensity:Maintaining 450-550°C operating temperatures requires integrated heating systems and insulation subsystems that add 15-20% to installed system cost versus ambient-temperature alternatives.
- Sodium-sulfur substitution threat:NGK Insulators' established sodium-sulfur technology competes for identical grid-scale applications with comparable duration and lower perceived technology risk.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:The production-linked incentive framework subsidizes domestic manufacturing of non-lithium storage technologies, creating localized supply chain incentives for sodium-based liquid metal platforms.
- Behind-the-meter industrial microgrids:Data centers and semiconductor fabs in Taiwan and South Korea seek island-capable storage for power quality and outage protection, opening 100-500 MWh unit demand.
- Electrode coating technology convergence:Atomic layer deposition techniques from solid-state battery manufacturing transfer to liquid metal systems, enabling corrosion-resistant electrode architectures that extend cycle life.
Industry Challenges
- High-temperature sealing engineering talent scarcity:Molten metal containment requires specialized materials science expertise in refractory ceramics and thermal expansion matching that outpaces university pipeline output.
- UL 9540A thermal runaway certification timelines:Fire safety testing protocols designed for lithium-ion systems require adaptation for liquid metal chemistries, creating 12-18 month approval delays for utility interconnect queues.
- Legacy SCADA integration complexity:Grid operators' existing energy management systems lack native protocols for high-temperature battery telemetry, forcing custom middleware development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Metal Battery Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum-Based Batteries, Sodium-Based Batteries, Gallium-Based Batteries, Other Metal Batteries Technology: Thermal Management Systems, Automated Mixing, Advanced Electrode Coatings, Self-Healing Technologies Application: Energy Storage Systems, Electric Vehicles, Grid Stabilization, Backup Power Solutions End User: Utilities, Manufacturing, Transportation, Commercial Enterprises |
| Companies Covered | Ambri Inc., Sumitomo Electric Industries, NGK Insulators, EaglePicher Technologies, Liquid Metal Battery Corporation, Pellion Technologies, Altris AB, Japan Metals & Chemicals, Lockheed Martin Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Metal Battery Market Shifts & Advancements
Electrode material innovations and thermal system integration advances are compressing the cost-performance gap between liquid metal batteries and conventional lithium-ion storage. These developments reshape competitive positioning across duration-segmented procurement categories.
Calcium-antimony electrode chemistry is expanding into utility-scale duration segments previously dominated by lithium iron phosphate. Southwestern US utilities now specify calcium-antimony systems for 8-hour discharge requirements in solar-plus-storage hybrids. The chemistry's raw material abundance and simplified supply chain is expanding into cost-sensitive procurement evaluations that previously excluded liquid metal options.
China's Ministry of Ecology and Environment dual carbon enforcement timelines mandate provincial grid operators contract long-duration storage equivalent to 10% of renewable capacity additions. Provincial state grid subsidiaries in Gansu and Xinjiang now issue tenders specifying 6-10 hour duration minimums. Domestic battery manufacturers are responding with sodium-based liquid metal platforms optimized for high-temperature desert operation.
Buyer preference is consolidating around performance-guaranteed service contracts rather than equipment-only procurement. Independent power developers in Texas and California now require 20-year availability warranties with liquidated damages clauses. This contract structure favors integrated manufacturers with captive electrode production over assembly-only market entrants lacking operational track records.
Liquid Metal Battery Market Segmentation
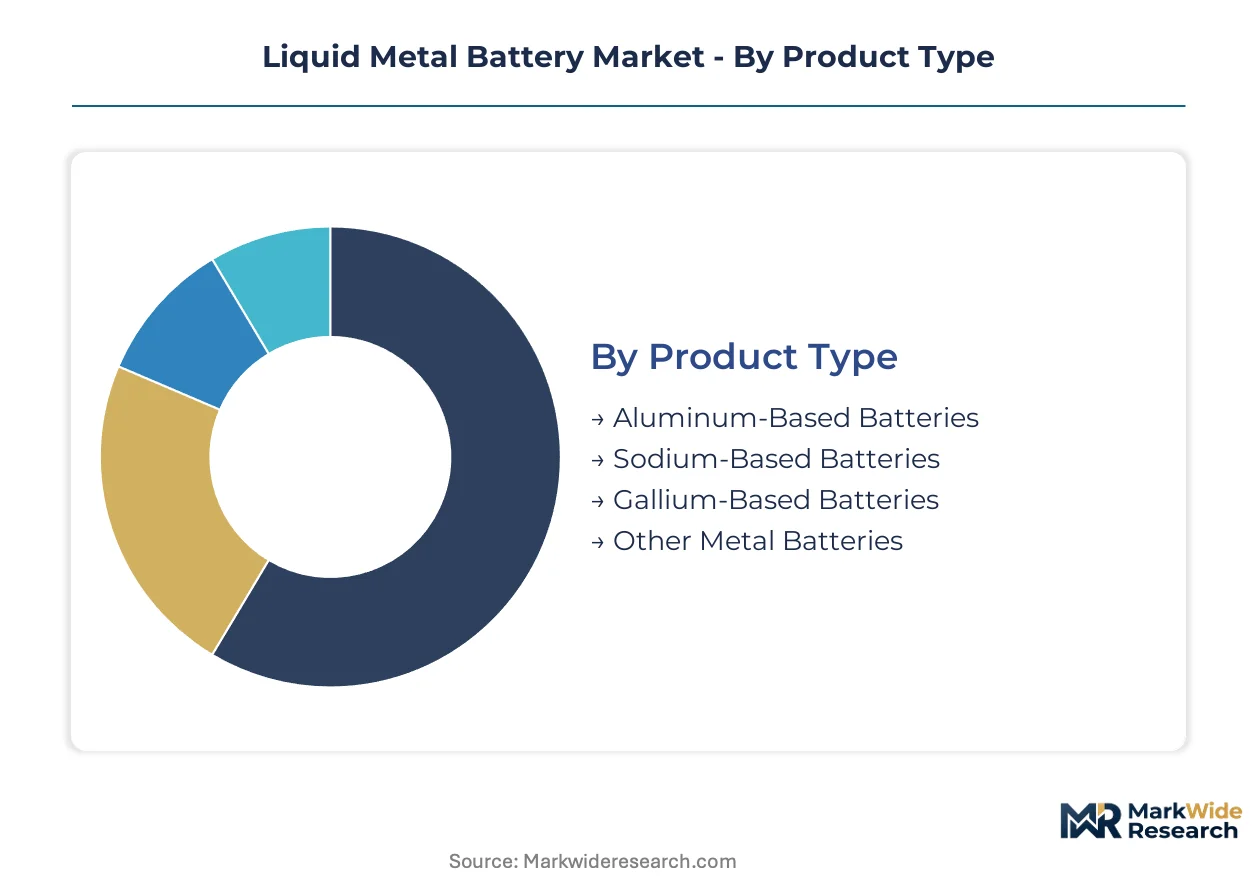
Liquid metal battery segmentation reveals how chemistry choices, thermal engineering, and procurement patterns split demand across distinct commercial pathways. Each category captures different buyer priorities — from raw material security to discharge duration specifications to integration complexity.
Product Type:
Cost tiers separate buyers seeking abundant feedstock security from those prioritizing energy density or specialized thermal properties.
- Sodium-Based Batteries:Molten sodium electrodes paired with molten salt electrolytes leverage established supply chains and desert-adapted thermal profiles. Procurement concentrates in China's Gansu province and Xinjiang region where state grid subsidiaries specify 6-10 hour duration minimums under dual carbon enforcement timelines.
- Aluminum-Based Batteries:Aluminum anode chemistries operate at lower temperature ranges than sodium alternatives, reducing insulation capex intensity. Southwestern US utilities specify these systems for 8-hour solar-plus-storage hybrids where simplified thermal management improves project returns.
- Gallium-Based Batteries:Low-melting-point gallium enables ambient-startup operation without extended pre-heating cycles, suited to backup power applications requiring immediate response.
- Other Metal Batteries:Calcium-antimony and magnesium-based experimental platforms target utility-scale duration segments with raw material abundance advantages.
Sodium-based platforms lead volumes today; aluminum-based chemistries are gaining share fastest in cost-sensitive procurement evaluations.
Technology:
Application maturity determines whether buyers invest in proven thermal infrastructure or emerging electrode innovations.
- Thermal Management Systems:Integrated heating and insulation subsystems maintain 450-550°C operating temperatures through refractory ceramic containment and thermal expansion matching. California and Texas grid operators mandate these systems for multi-gigawatt-hour tenders where 15-20 year operational life underwrites financing structures.
- Advanced Electrode Coatings:Atomic layer deposition techniques from solid-state battery manufacturing transfer to liquid metal architectures, enabling corrosion-resistant electrodes that extend cycle life. Taiwan and South Korean data center operators specify coated electrodes for 100-500 MWh industrial microgrid units demanding power quality guarantees.
- Automated Mixing:Precision molten metal homogenization systems reduce electrode degradation through controlled alloy distribution during charge cycling.
- Self-Healing Technologies:Electrode reconstruction mechanisms autonomously repair micro-fractures during thermal cycling, targeting segments where maintenance access is constrained.
Thermal management systems anchor current deployment volumes; advanced electrode coatings are climbing the fastest as performance-guaranteed service contracts displace equipment-only procurement.
Application:
Discharge duration requirements and revenue stack complexity split buyers across grid-scale buffering, mobility, and reliability applications.
- Energy Storage Systems:Front-of-meter installations arbitrage renewable curtailment through multi-cycle daily operation in grids exceeding 40% wind and solar penetration. Independent power producers in Texas and California now require 20-year availability warranties with liquidated damages clauses for these assets.
- Grid Stabilization:Transmission operators procure inertia-equivalent services from liquid metal batteries to replace retiring synchronous condensers. Germany's transmission system operators specify these systems for frequency response contracts as renewable displacement accelerates.
- Electric Vehicles:High-temperature startup latency and thermal management mass penalties currently constrain automotive adoption to heavy-duty segments with predictable duty cycles.
- Backup Power Solutions:Island-capable configurations serve semiconductor fabs and critical infrastructure requiring outage protection independent of grid status.
Energy storage systems dominate current revenue pools; grid stabilization represents the steepest expansion trajectory as transmission operators face inertia shortfalls.
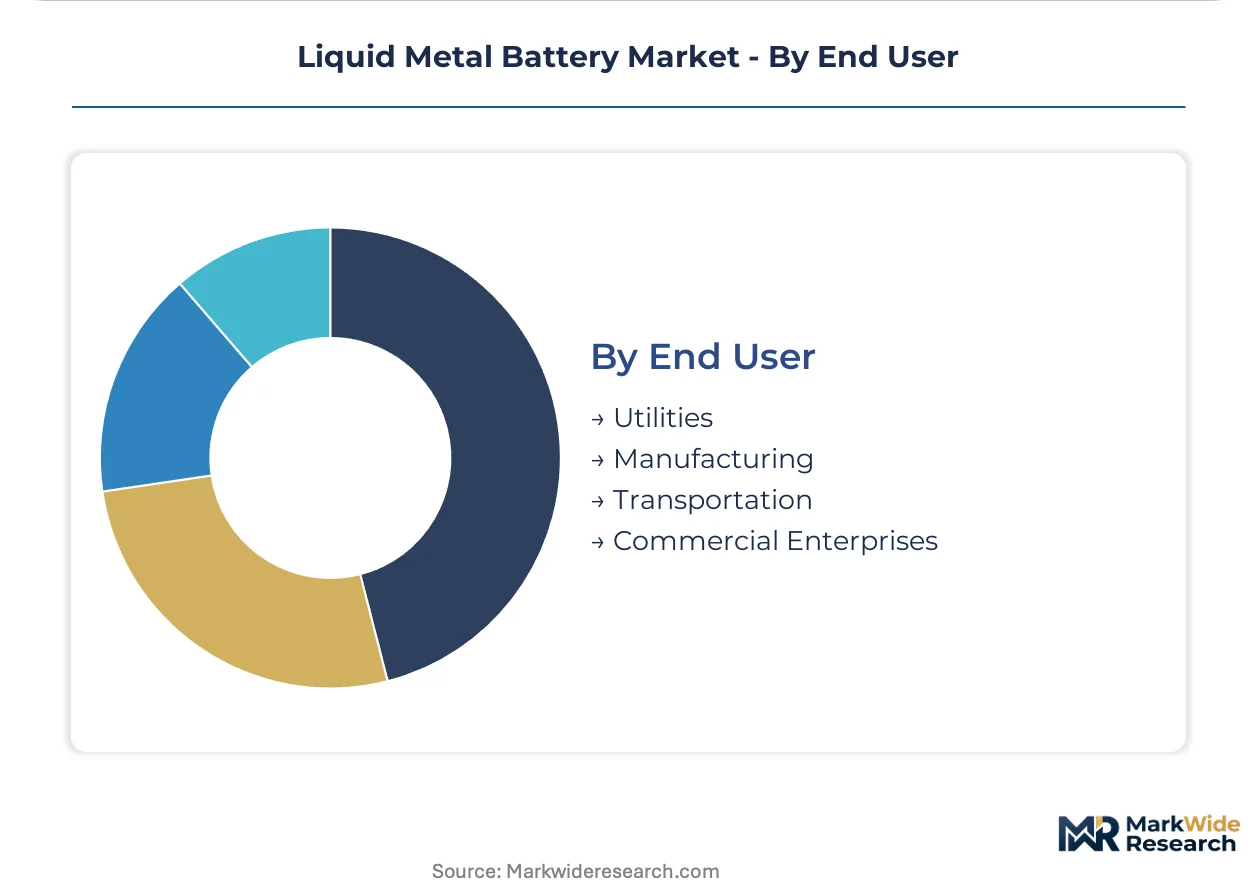
End User:
Procurement scale and technical sophistication separate institutional buyers from commercial adopters navigating integration complexity.
- Utilities:Vertically integrated and independent power producers deploy utility-scale systems through mandated storage procurement equivalent to 10% of renewable capacity additions. China's provincial state grid subsidiaries and US independent system operators drive tender volumes through FERC Order 841 market participation rules.
- Manufacturing:Semiconductor fabs and heavy industrial facilities specify behind-the-meter liquid metal storage for power quality and demand charge management.
- Transportation:Rail and maritime operators evaluate liquid metal systems for electrified corridors where charging infrastructure constraints favor high-energy-density alternatives.
- Commercial Enterprises:Data centers and distributed energy users seek island-capable configurations with standardized SCADA integration protocols.
Utilities command the deepest procurement volumes; manufacturing end users are expanding most quickly as power quality requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting liquid metal battery manufacturing toward jurisdictions where thermal management compliance costs and feedstock access create operational advantages. The Inflation Reduction Act's storage tax credits and China's dual carbon enforcement timelines are accelerating divergent deployment patterns across major economies.
United States
Southwestern utilities in California, Arizona, and Texas drive procurement for 8-12 hour solar-plus-storage hybrids. FERC Order 841 mandates storage participation in wholesale markets, enabling independent power producers to capture capacity payments. The California Independent System Operator's multi-gigawatt-hour tenders concentrate demand in the Imperial Valley and Central Valley renewable zones.
China
Provincial grid operators in Gansu and Xinjiang contract long-duration storage equivalent to 10% of renewable capacity additions under MEE dual carbon timelines. State grid subsidiaries specify sodium-based platforms for high-temperature desert operation. Manufacturing clusters in the Yangtze River Delta and Shandong Peninsula integrate electrode production with domestic magnesium and sodium feedstock refining.
Germany
Transmission system operators procure inertia-equivalent services to replace retiring synchronous condensers as renewable displacement accelerates. The EU Green Deal and national coal phase-out regulations force 6-10 hour storage contracting in northern wind corridors. Industrial demand concentrates in North Rhine-Westphalia's Ruhr industrial cluster and Bavaria's manufacturing belt.
India
The PLI scheme for advanced chemistry cells subsidizes domestic manufacturing of non-lithium storage technologies. State electricity boards in Gujarat and Rajasthan issue tenders for grid-scale buffering as solar penetration exceeds 30% in western states. Manufacturing incentives target Tamil Nadu and Karnataka for electrode and thermal subsystem assembly.
Japan
METI funding for long-duration storage R&D supports pilot deployments in Hokkaido's wind-rich northern grid. Industrial microgrid demand from semiconductor fabs in Kyushu and data centers in the Tokyo metropolitan area creates behind-the-meter opportunities. Domestic manufacturers leverage established sodium-sulfur thermal management expertise for liquid metal platform adaptation.
Liquid Metal Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electrode producers commanding premium positioning in performance-guaranteed procurement. The vendor base concentrates around three to five chemistry platforms rather than fragmenting across dozens of variants. Chemistry-locked specialists, diversified industrial conglomerates, and research-spinout ventures constitute the primary strategic archetypes. Capacity expansion and captive electrode production represent the dominant competitive moves as buyers prioritize 20-year availability warranties.
Within the chemistry-specialist tier, Ambri Inc. and Liquid Metal Battery Corporation exemplify venture-backed platforms commercializing calcium-antimony systems for utility-scale duration segments. Sumitomo Electric Industries occupies a position among diversified industrial conglomerates with integrated magnesium sourcing and in-house electrode production capabilities. NGK Insulators anchors the established technology adaptation segment, translating sodium-sulfur thermal management expertise into liquid metal system architectures.
| Leading Market Players |
|---|
| Ambri Inc. |
| Sumitomo Electric Industries |
| NGK Insulators |
| EaglePicher Technologies |
| Liquid Metal Battery Corporation |
| Pellion Technologies |
| Altris AB |
| Japan Metals & Chemicals |
| Lockheed Martin Energy |
| Others |
Supply & Pricing Matrix
Antimony electrode feedstock originating in Chinese and Tajikistan refining operations flows through tiered pricing structures that penalize non-integrated buyers. Thermal management subsystem costs cascade downstream to utility procurement evaluations, compressing margins for assembly-only vendors while rewarding captive electrode producers.
Pricing Analysis
Distributor margins for thermal management subsystems widen pricing spreads between integrated manufacturers and assembly-only entrants. Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation anchored in UL 9540A certification status and 20-year availability warranty backing. Cost compression in standard-tier systems is intensifying because sodium-sulfur substitution threats force liquid metal vendors to absorb thermal management capex premiums. Independent power producers exhibit highest price sensitivity, while transmission operators prioritizing inertia-equivalent services demonstrate lowest sensitivity.
Supply Chain Analysis
Regional distribution centers for refractory ceramic containment systems cluster in China's Yangtze River Delta and Germany's Ruhr industrial corridor. Antimony refining concentrates in China and Tajikistan, while magnesium electrode feedstock draws from Shandong Peninsula integrated operations. Single-source vulnerability in antimony export quotas exposes electrode manufacturers to geopolitical disruption. Distribution runs through project-direct EPC contractor channels for utility-scale deployments, bypassing traditional battery distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid metal battery market functions as a geographic-arbitrage play where US Inflation Reduction Act storage tax credits offset thermal management capex intensity unavailable to European competitors facing EU carbon border adjustment exposure.
For Market Incumbents: Hedge against sodium-sulfur substitution by deepening captive electrode production in southwestern US manufacturing clusters. Secure long-term antimony offtake agreements before Tajikistan export quota tightening. Prioritize UL 9540A certification investment to compress utility interconnect queue timelines. For New Entrants and Emerging Players: Industrial microgrid operators at Taiwan semiconductor fabs represent underserved buyer archetypes seeking island-capable storage with immediate-response capabilities. Penetrate behind-the-meter segments through atomic layer deposition coating partnerships transferred from solid-state battery manufacturing. Pursue India's PLI scheme manufacturing incentives for sodium-based platform localization. For Investors and Strategic Acquirers: Roll-up economics work for electrode-coating technology specialists because performance-guaranteed service contracts displace equipment-only procurement and reward operational track records. Five-to-ten year viability hinges on chemistry-locked platforms achieving manufacturing scale before certification maturity. Monitor FERC Order 841 implementation depth across US independent system operators as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Electrode Production | Ambri and Sumitomo anchor 20-year warranty credibility through in-house calcium-antimony and magnesium electrode control. |
| Thermal Management Integration | Refractory ceramic containment expertise from sodium-sulfur adaptation enables NGK Insulators' liquid metal platform entry. |
| Atomic Layer Deposition Licensing | Corrosion-resistant electrode coatings from solid-state battery manufacturing transfer to extend cycle life in desert deployments. |
| PLI Scheme Manufacturing Localization | India's production-linked incentives subsidize domestic sodium-based platform assembly for Gujarat grid-scale tenders. |
| Performance-Guaranteed Service Contracts | Texas IPPs now require liquidated damages clauses that favor integrated manufacturers over assembly-only market entrants. |
Research Methodology
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation from FERC filings, EIA project databases, IEA long-duration storage reports, and state renewable portfolio standard documentation. Bottom-up and top-down triangulation cross-checks electrode manufacturing capacity announcements against utility tender award volumes.
Bottom-up modeling of chemistry-specific manufacturing costs and top-down demand aggregation from renewable curtailment economics across high-penetration grids anchor the analytical framework. Segmentation dimensions include electrode chemistry type, thermal management architecture, discharge duration tier, and regional regulatory framework. CAGRs derive from utility procurement pipeline analysis and technology cost curve trajectories. Forecast inputs incorporate FERC Order 841 market participation rules and China's MEE dual carbon enforcement timelines.
Underlying measurement precision varies by segment; utility-scale procurement volumes carry tighter precision than emerging behind-the-meter industrial microgrid categories. Forecasts reflect assumptions around thermal runaway certification timeline compression and antimony supply quota stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
US Solar Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
China Battery Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Molten Salt Battery Market
Batteries
Dry Cell Battery Market
Batteries
DMC for Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Hybrid Flow Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
Home Inverter Battery Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Asia-Pacific Battery Market