
 Europe Concentrated Solar Power Market | 2026-2036
Europe Concentrated Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Concentrated Solar Power Market Insights
Multi-source engineering procurement is consolidating across European CSP developers as project scale and thermal storage complexity rise. Abengoa SA leverages its Seville engineering heritage to sustain EPC competitiveness for parabolic trough installations. Acciona SA anchors its position through integrated development capabilities spanning site acquisition to grid connection. Engie SA differentiates by controlling hybrid CSP-PV project pipelines that optimize capacity factor economics.
Concentrated Solar Power harnesses mirrors or lenses to focus direct normal irradiance onto a receiver, heating transfer fluid—typically synthetic oil or molten salt—to temperatures exceeding 550°C for thermal-electric conversion or storage. Parabolic trough technology dominates installed European capacity due to decades of operational maturity and bankable performance data. Solar Tower configurations represent the fastest-expanding product type as higher temperature ceilings unlock superior thermal storage efficiency. Thermal Energy Storage integration increasingly determines project viability, allowing CSP plants to dispatch electricity during evening peak demand windows when PV output collapses.
The EU Green Deal and REPowerEU framework shape national auction design, with Spain's Ministry for Ecological Transition and Demographic Challenge and the European Investment Bank conditioning financing on molten salt storage duration thresholds. CE marking and the EU's F-Gas Regulation constrain heat transfer fluid selection, steering developers toward lower-GWP alternatives. Stakeholders must monitor how the EU AI Act and forthcoming grid codes affect automated heliostat field control systems and dispatch optimization algorithms.
Market Dynamics
Dispatchability requirements under the EU Green Deal are forcing molten salt thermal storage into every new CSP project design, transforming auction economics and EPC contracting structures across Spain and Portugal.
Growth Catalysts
- REPowerEU targets:Spain's Ministry for Ecological Transition has redirected national subsidy frameworks toward dispatchable renewables, mandating storage duration thresholds that favor CSP over standalone PV.
- Extremadura cluster:Solar resource intensity exceeding 2,200 kWh/m² annually and available degraded land converge to reduce site acquisition costs for utility-scale developments.
- Molten salt technology:Operational maturity across 15+ years of Spanish plant data has de-risked thermal storage integration for project financiers.
Market Restraints
- Input cost volatility:Nitrate salt prices fluctuate with agricultural fertilizer demand cycles, exposing EPC contractors to raw material margin compression.
- Supply concentration:Heliostat mirror manufacturing concentrates in Chinese glass suppliers, creating geopolitical exposure for European developers.
- Technical limitation:Direct normal irradiance requirements above 2,000 kWh/m² annually restrict viable sites to Mediterranean latitudes, capping addressable geography.
Strategic Opportunities
- Portugal's Alentejo region:Underdeveloped grid interconnection capacity and favorable irradiance profiles offer first-mover advantages for hybrid CSP-PV configurations.
- Industrial heat offtake:Cement and steel producers in southern Spain are piloting CSP-derived process heat contracts, diversifying revenue beyond electricity sales.
- EU AI Act compliance:Automated heliostat field control systems that meet algorithmic transparency requirements will qualify for accelerated permitting in Spanish renewable auctions.
Industry Challenges
- Specialized welding certification:ASME Section IX-qualified technicians for high-pressure steam systems remain scarce across Iberian EPC labor pools, extending construction timelines.
- Grid code synchronization:Spanish transmission operator Red Eléctrica de España is revising inertia requirements that demand upgraded synchronous condensers at CSP connection points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Concentrated Solar Power Market |
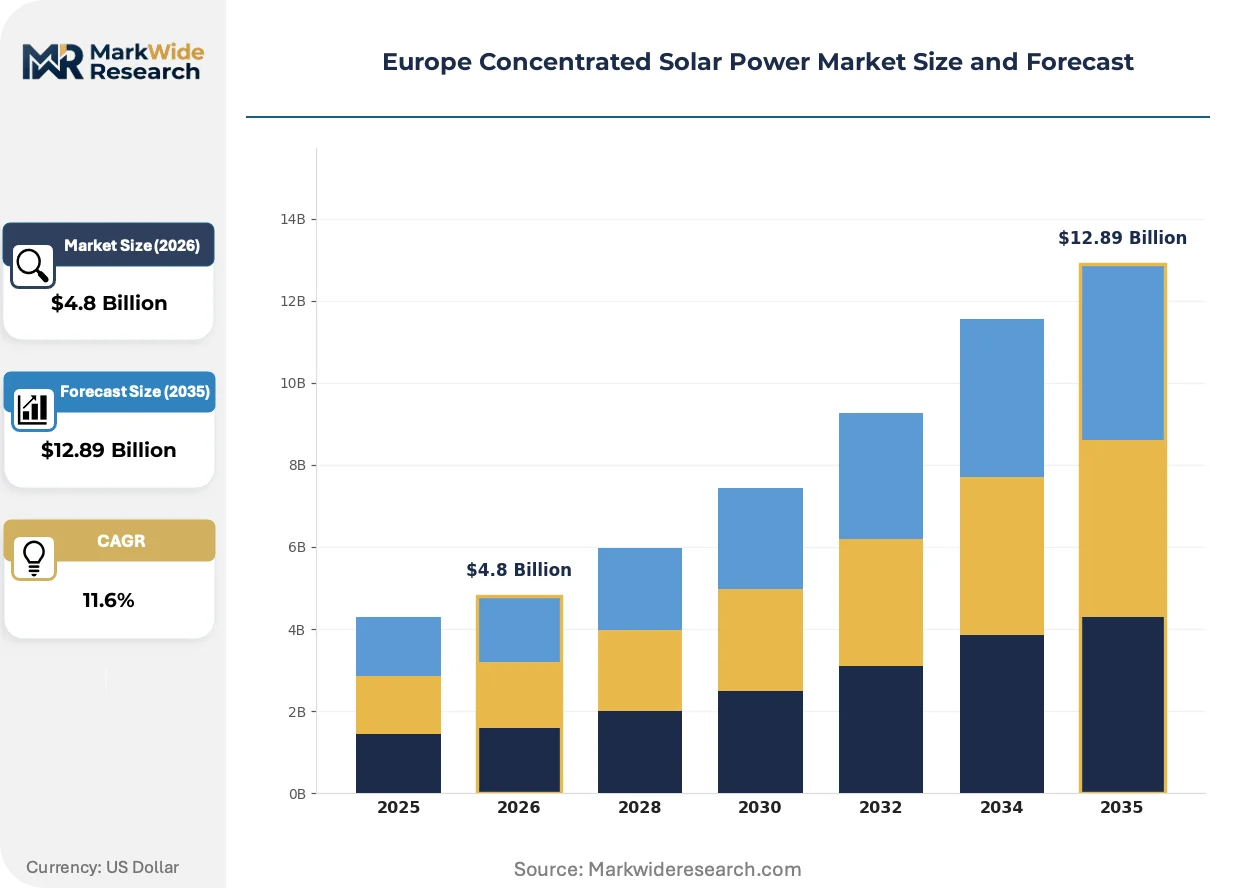
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabolic Trough, Solar Tower, Fresnel Collector, Dish Stirling Technology: Thermal Energy Storage, Hybrid Systems, Grid Connected, Off-Grid End User: Utilities, Commercial, Industrial, Government Deployment: Onshore, Offshore, Rural, Urban |
| Companies Covered | Abengoa SA, Acciona SA, Engie SA, Torresol Energy, Suncnim, Masdar, Aalborg CSP, ACWA Power, Siemens Energy, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Concentrated Solar Power Market Trends and Innovations
Technology trajectories in European CSP are converging on higher-temperature thermodynamic cycles and algorithmic field optimization, while regulatory frameworks harden around storage mandates and carbon accounting.
Solid particle receiver technology is expanding into the 700°C+ temperature regime, enabling supercritical CO₂ Brayton cycles that boost plant efficiency by 8-12 percentage points. German research institutes and Spanish engineering firms are co-developing pilot installations. This thermal ceiling expansion is compressing the levelized cost gap between CSP and combined-cycle gas turbines for evening dispatch.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon heat transfer fluids, compelling developers to retrofit existing parabolic trough plants with lower-GWP synthetic oils or molten salt alternatives. ECHA guidance on persistent organic pollutants is tightening compliance timelines. Spanish operators with legacy synthetic oil infrastructure face accelerated depreciation schedules and replacement capex planning.
Utility procurement teams are unbundling EPC contracts from long-term O&M agreements, forcing developers to compete on construction cost discipline rather than lifecycle performance guarantees. This disintermediation is most visible in Spanish auctions, where independent asset managers now separately tender construction and 25-year service contracts. Portuguese project sponsors are adopting similar structures to attract infrastructure fund capital.
Europe Concentrated Solar Power Market Segmentation
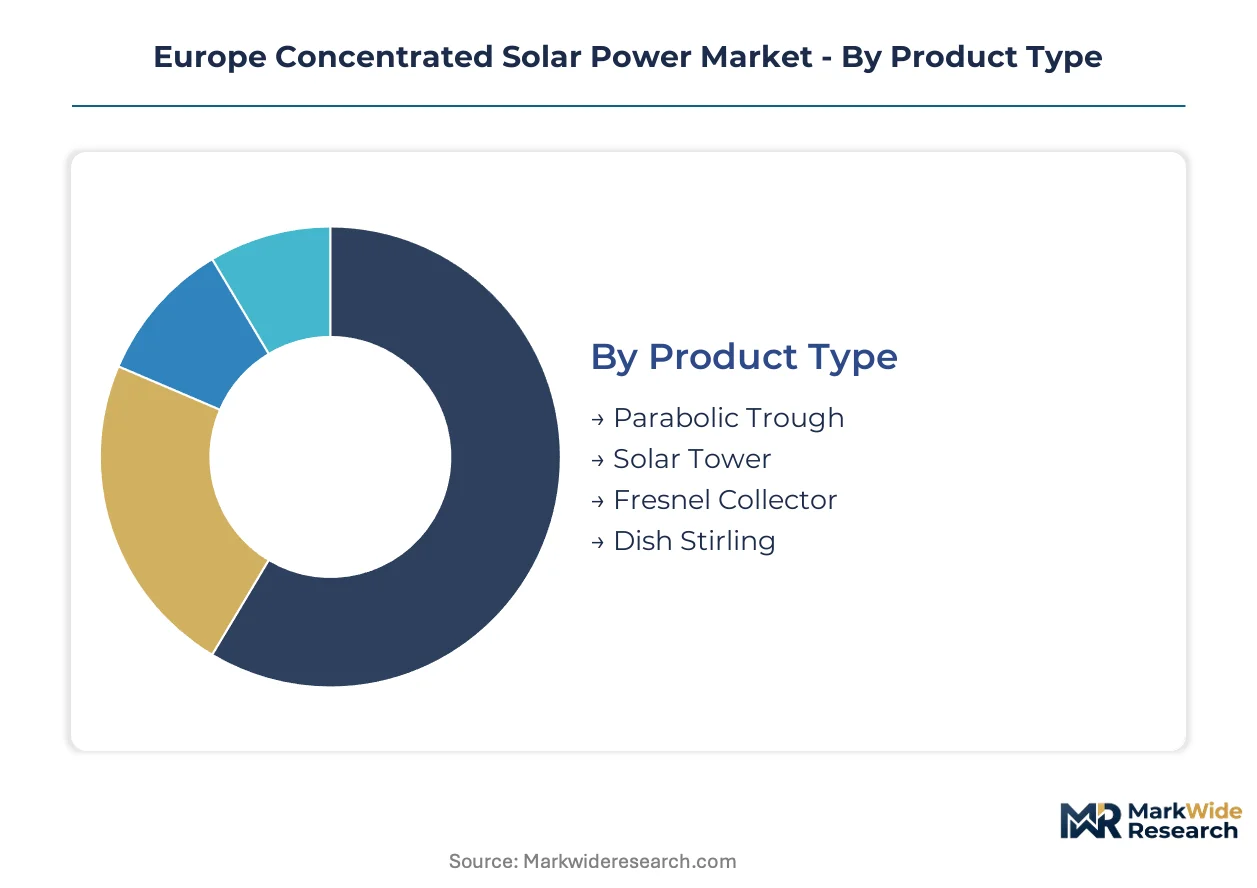
Technology segmentation in the European CSP market reveals distinct integration depths. Some configurations operate as standalone thermal-electric plants, while others embed within hybrid renewable portfolios or industrial heat networks. Understanding these structural positions clarifies where capital deployment concentrates and which segments capture policy support.
Product Type:
Standalone thermal-electric plants dominate utility-scale procurement, while embedded configurations serve industrial process heat and distributed generation.
- Parabolic Trough:Curved mirrors track the sun along a single axis, focusing irradiance onto receiver tubes containing synthetic oil or molten salt. Spanish utilities in Extremadura and Andalusia favor this technology for its 30-year operational track record and bankable performance data under EU Green Deal financing conditions.
- Solar Tower:Heliostat fields concentrate sunlight onto a central receiver atop a tower, achieving temperatures above 550°C. Developers in Spain's Almería province are expanding tower deployments for superior thermal storage efficiency, though Chinese heliostat supply concentration creates procurement risk.
- Fresnel Collector:Flat or slightly curved mirrors arranged in parallel rows concentrate light onto fixed linear receivers. Industrial heat offtakers in southern Spain pilot this lower-cost configuration for cement and steel process applications.
- Dish Stirling:Parabolic dish mirrors focus irradiance onto a Stirling engine receiver at the focal point. Remote off-grid installations in rural Portugal test this technology for distributed generation where grid extension proves uneconomical.
Volume placements concentrate in Parabolic Trough; the faster expansion belongs to Solar Tower.
Technology:
Cost-tier differentiation separates premium integrated storage systems from baseline grid-connected configurations lacking dispatchability.
- Thermal Energy Storage:Molten salt tanks retain heat for 8-15 hours, enabling evening electricity dispatch when PV output collapses. Spain's Ministry for Ecological Transition mandates minimum storage durations in renewable auctions, embedding this technology into new project economics.
- Hybrid Systems:CSP-PV configurations combine thermal storage with photovoltaic generation to optimize capacity factors. Portuguese developers in Alentejo pursue hybrid designs to attract infrastructure fund capital through improved revenue predictability.
- Grid Connected:Plants synchronize with transmission networks under Red Eléctrica de España grid codes. Synchronous condenser upgrades address revised inertia requirements for CSP connection points.
- Off-Grid:Standalone installations serve isolated industrial facilities or remote communities without transmission access. Rural deployments in Iberian agricultural zones test this model for irrigation pumping and processing.
Revenue premiums attach to Thermal Energy Storage; Hybrid Systems are climbing the fastest as auction design evolves.
End User:
Application-specific requirements drive specification divergence between bulk electricity procurement and industrial process integration.
- Utilities:Iberian electric utilities dominate procurement volume, contracting EPC firms for utility-scale plants with 25-year power purchase agreements. Spanish auction frameworks condition financing on storage thresholds that favor dispatchable CSP over variable renewables.
- Industrial:Cement and steel producers in southern Spain pilot CSP-derived process heat contracts, diversifying revenue beyond electricity sales into thermal offtake agreements.
- Commercial:Distributed installations serve hotels, data centers, and agricultural processing facilities with moderate thermal loads. Urban deployment constraints limit addressable sites.
- Government:Public sector procurement supports research installations and demonstration projects, particularly German-Spanish collaborations on solid particle receiver technology.
Contract volume concentrates in Utilities; Industrial applications are gaining share fastest as heat decarbonization pressures mount.
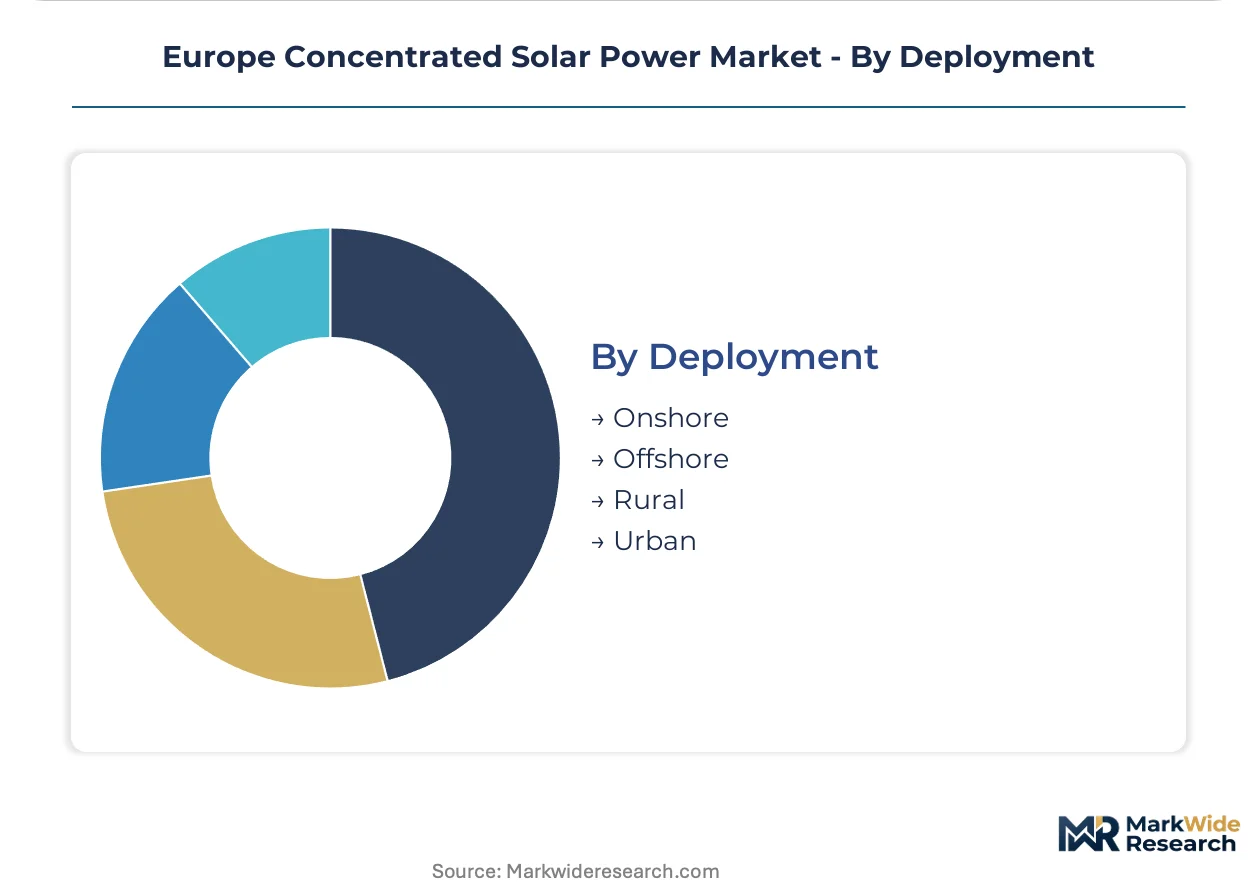
Deployment:
Geographic and infrastructure context determines project viability, with rural onshore sites offering cost advantages over constrained urban or offshore alternatives.
- Onshore:Land-based installations across Spain's degraded agricultural zones and Portugal's Alentejo region leverage available terrain and high direct normal irradiance. Site acquisition costs in Extremadura fall below urban benchmarks.
- Rural:Remote deployments minimize land-use conflicts and grid congestion. Available interconnection capacity in underdeveloped Portuguese regions offers first-mover positioning for project sponsors.
- Urban:Space-constrained installations face higher land costs and shadowing effects. Limited applicability restricts this segment to demonstration projects and small-scale commercial heating.
- Offshore:Floating CSP concepts remain pre-commercial, with no operational European capacity. Technical challenges of marine mirror maintenance and salt corrosion suppress near-term development.
Development activity concentrates in Onshore; Rural deployments are expanding most quickly as grid interconnection investments lag generation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extremadura's degraded agricultural land and 2,200 kWh/m² annual irradiance anchor European CSP development. The region's available terrain and established grid infrastructure concentrate project pipelines across Iberia.
Spain
Spanish utilities in Extremadura and Andalusia scale molten salt storage installations for evening dispatch. The Ministry for Ecological Transition mandates storage duration thresholds in renewable auctions under REPowerEU. Seville engineering clusters sustain EPC competitiveness for parabolic trough deployments.
Portugal
Portuguese developers target Alentejo's underdeveloped grid interconnection for hybrid CSP-PV configurations. National energy regulators align auction design with Iberian electricity market integration. First-mover sponsors secure available transmission capacity before infrastructure investments lag generation growth.
Italy
Italian industrial heat offtakers in Sicily pilot CSP-derived process heat for cement production. The national renewable energy plan channels subsidies toward dispatchable solar technologies under EU Green Deal implementation. Enel Green Power evaluates tower configurations in Sardinia's high-irradiance zones.
Germany
German research institutes co-develop solid particle receiver technology exceeding 700°C with Spanish engineering partners. Federal funding for supercritical CO₂ Brayton cycles advances efficiency gains. Stuttgart and Munich technical universities anchor pilot installation programs.
France
French engineering groups supply heliostat control systems and thermal storage components to Iberian projects. The national low-carbon strategy prioritizes industrial heat decarbonization over utility-scale electricity generation. Provence-Alpes-Côte d'Azur hosts demonstration installations for concentrated solar process heat.
Europe Concentrated Solar Power Market Competitive Landscape
Global majors compete with regional champions across engineering procurement and thermal storage integration. Spanish and French utilities anchor project development through integrated capabilities from site acquisition to grid connection. Three archetypes dominate: engineering heritage firms leveraging Seville technical clusters, diversified energy majors controlling hybrid renewable pipelines, and specialized thermal storage integrators. Competitive moves concentrate on unbundling EPC from O&M contracts and securing molten salt supply agreements.
Among Spanish engineering specialists, Abengoa SA and Acciona SA exemplify heritage-driven EPC positioning rooted in Andalusian solar development. Engie SA represents the diversified utility archetype with hybrid CSP-PV project control. These three anchors illustrate how competitive advantage separates construction cost discipline from lifecycle performance guarantees in auction-driven procurement.
| Leading Market Players |
|---|
| Abengoa SA |
| Acciona SA |
| Engie SA |
| Torresol Energy |
| Suncnim |
| Masdar |
| Aalborg CSP |
| ACWA Power |
| Siemens Energy |
| Others |
Pricing and Supply Chain Analysis
Captive molten salt production anchors both supply security and pricing power for European developers bidding into Spanish renewable auctions. EPC contractors with backward integration into thermal storage manufacturing command margin premiums over rivals dependent on spot nitrate salt markets.
Pricing Analysis
Warranty unbundling from construction contracts is compressing EPC margins as asset managers separately tender 25-year O&M agreements. Three-tier pricing structure across integrated EPC-O&M, construction-only, and service-only levels reflects divergent risk appetites. Cost compression in the construction-only tier is intensifying because fertilizer demand cycles drive nitrate salt volatility. Industrial heat offtakers show highest price sensitivity, while utility procurement teams prioritize dispatchability guarantees over upfront capex.
Supply Chain Analysis
Single-source vulnerability sits with Chinese heliostat mirror manufacturers, exposing European developers to geopolitical disruption. Manufacturing concentrates in China, Spain, and Germany across the component stack. Raw material dependencies span low-iron glass, nitrate salts, and high-grade steel for receiver tubing. Tariff exposure on Chinese glass imports threatens project cost structures. Distribution runs through EPC-led turnkey contracting with utility offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME-certified welding labor scarcity props pricing for qualified EPC contractors across Iberian project pipelines. This supply-constrained dynamic favors incumbents with established training pipelines and certification maintenance programs.
For Market Incumbents: Deepen captive molten salt supply agreements to insulate margins from agricultural fertilizer demand cycles. Secure ASME Section IX-qualified technician pipelines through vocational partnerships in Extremadura and Andalusia. Emerging hybrid CSP-PV developers threaten pure-play thermal storage positioning without integrated development capabilities.
For New Entrants and Emerging Players: Digital-channel route through algorithmic heliostat control software offers lowest capital barrier to CSP project participation. Target Portugal's Alentejo region for first-mover grid interconnection positioning. Pursue industrial heat offtake contracts with cement and steel producers seeking process heat decarbonization pathways.
For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure fund acquisitions of operational assets with contracted revenue streams. Long-term viability hinges on storage duration mandates persisting under REPowerEU implementation. Monitor Spanish auction design evolution as inflection indicator for thermal storage premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Molten Salt Storage Integration | Spain's Ministry for Ecological Transition mandates minimum durations that embed dispatchability premiums into project economics. |
| Hybrid CSP-PV Development | Portuguese sponsors in Alentejo attract infrastructure capital through improved capacity factor predictability. |
| ASME Certification Investment | Qualified welding labor scarcity extends construction timelines for uncertified EPC contractors. |
| Industrial Heat Offtake Contracting | Cement and steel producers in southern Spain diversify CSP revenue beyond electricity sales. |
| Algorithmic Field Control Systems | EU AI Act compliance accelerates permitting for transparent automated heliostat optimization. |
Research Methodology
Independent corroboration across EPC project developers, utility planning officers, and molten salt suppliers underwrites the qualitative findings. Primary interviews engaged IPP development teams, Red Eléctrica de España grid operators, and thermal storage component manufacturers. Secondary validation drew from IEA renewable energy databases, European Investment Bank project finance disclosures, and Spanish auction registry filings. Bottom-up project pipeline enumeration triangulates against top-down REPowerEU target allocations.
Rate-of-change decomposition separates capacity addition trajectories from storage duration evolution and hybrid configuration penetration across the analysis window. Segmentation dimensions span technology type, storage integration depth, end-use application, and deployment geography. CAGRs derive from modeled project commissioning schedules and auction award volumes. Forecast inputs incorporate direct normal irradiance mapping and grid interconnection queue data.
The model holds under sustained REPowerEU subsidy frameworks; deviation in auction storage mandate relaxation or nitrate salt supply disruption would shift capacity deployment trajectories. Forecasts reflect documented assumptions on policy continuity and component supply elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Vietnam Solar Energy Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Residential Solar Energy Market