
 Floating Photovoltaics (FPV) Market | 2026-2036
Floating Photovoltaics (FPV) Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Photovoltaics (FPV) Market Foresight
Chinese module manufacturers is realigning floating solar supply chains toward integrated floating platform production. Sungrow Power Supply leverages its power conversion expertise to anchor hybrid FPV deployment across Asia. Ciel & Terre International specializes in floating structure engineering and competes on mooring system reliability. JinkoSolar Holding extends its terrestrial panel dominance into bifacial floating configurations.
Floating photovoltaics denotes solar arrays mounted on buoyant platforms that deploy across water bodies, typically using high-density polyethylene floats with corrosion-resistant aluminum frames to generate electricity while reducing water evaporation and algae growth. Mono-crystalline panels lead installed capacity due to superior efficiency in space-constrained floating environments, while bifacial panels represent the fastest-growing product category as they capture reflected light from water surfaces. Hydropower reservoirs command the largest application share because existing grid infrastructure and water management permits streamline project execution, whereas mining pits offer emerging margin pools where land remediation funding intersects with renewable energy development.
Japan's METI feed-in tariff framework and grid interconnection standards shape project economics for domestic FPV developers, while China's MEE water quality regulations and dual carbon goals restrict conventional ground-mounted alternatives on protected watersheds. The EU Green Deal and F-Gas Regulation constrain synthetic float materials in European installations, pushing demand toward recycled polymer substitutes. Stakeholders must monitor evolving national water rights frameworks that determine lease structures and environmental impact thresholds for floating solar deployment.
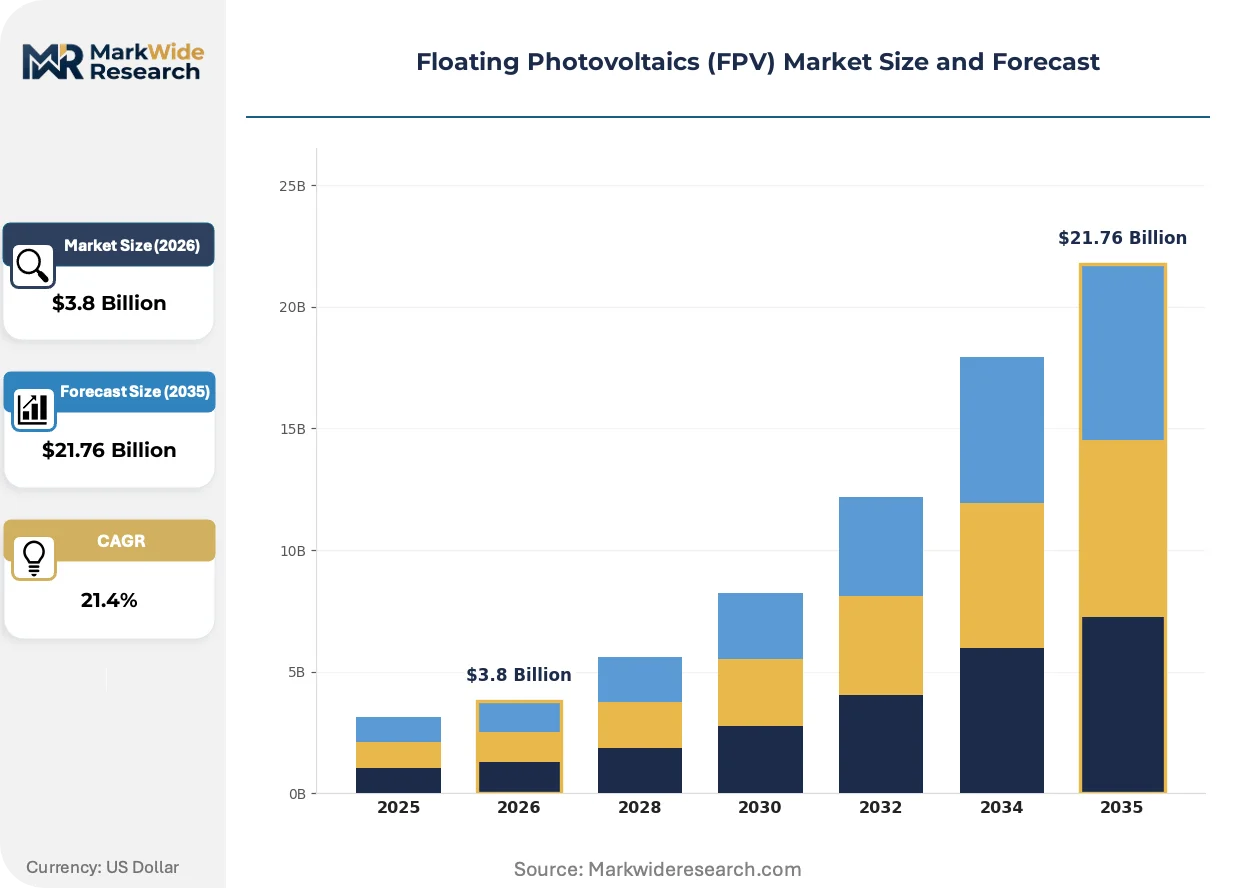
Market Dynamics
Utility-scale power producers are repositioning capital toward floating solar arrays on hydropower reservoirs, driven by streamlined permitting and existing grid infrastructure that collapses project development timelines versus greenfield ground-mounted alternatives.
Growth Catalysts
- Dual carbon goals:China's MEE water protection standards restrict conventional ground-mounted solar on protected watersheds, accelerating FPV project approvals as the compliant alternative for renewable capacity additions.
- Feed-in tariff frameworks:Japan's METI pricing mechanisms and grid interconnection standards create investable project economics for domestic developers targeting reservoir-based installations.
- Hydropower reservoir integration:Existing water management permits and transmission infrastructure at dam sites compress execution risk for hybrid solar-hydro developments across East Asia.
Market Restraints
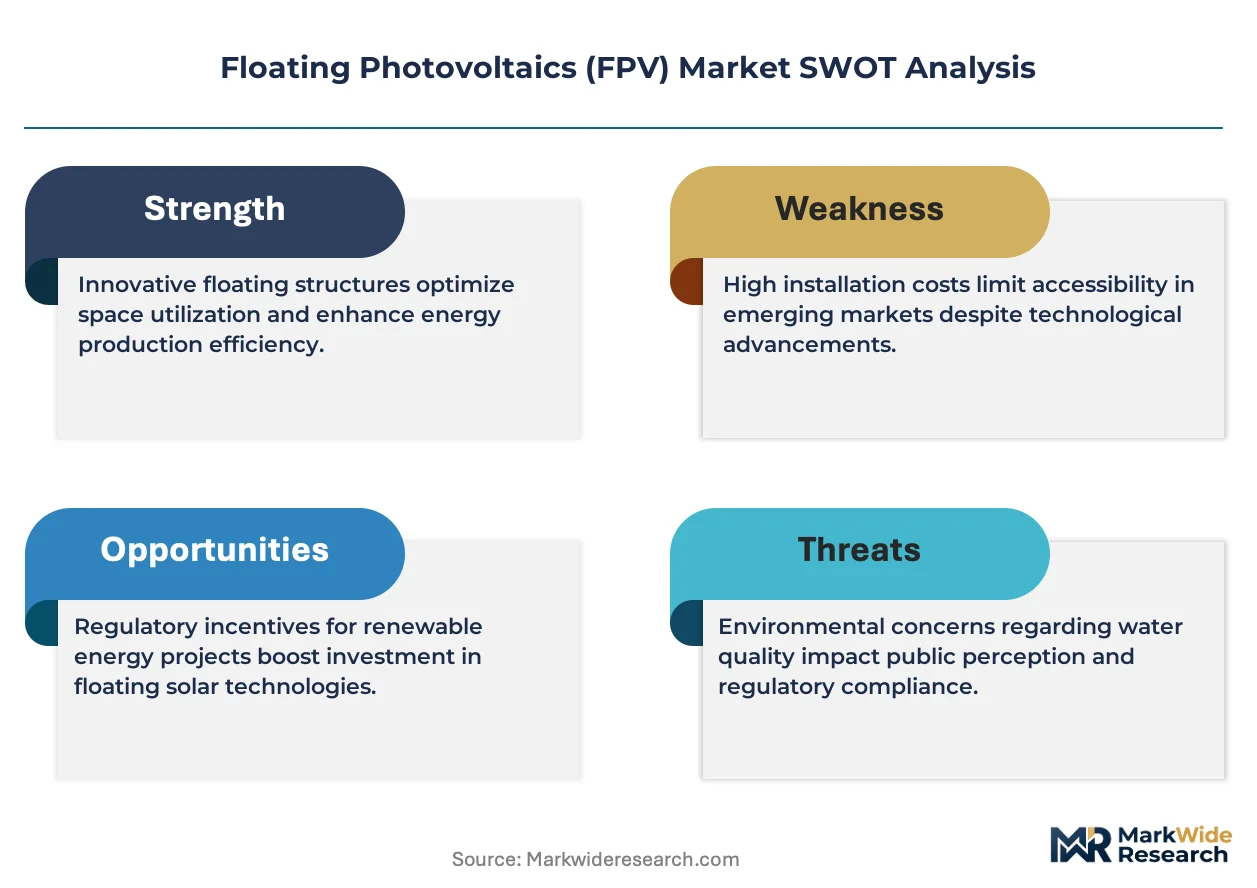
- High-density polyethylene input volatility:Float platform costs fluctuate with petrochemical feedstock prices, exposing project returns to oil market swings without long-term polymer supply contracts.
- Mooring system engineering concentration:Specialized anchoring expertise clusters among European and Japanese engineering firms, creating bottleneck risk for rapid capacity scaling in emerging markets.
- F-Gas Regulation material constraints:The EU's synthetic polymer restrictions push float manufacturers toward recycled substitutes with unproven long-term degradation profiles in aquatic environments.
Strategic Opportunities
- Mining pit remediation:Abandoned extraction sites in Germany and Poland combine land remediation funding streams with renewable energy development, creating margin pools unavailable to conventional solar.
- Bifacial panel convergence:Dual-sided photovoltaic cells capturing reflected light from water surfaces are reshaping system design standards for floating installations.
- PLI scheme manufacturing support:India's production-linked incentive framework for solar module manufacturing is attracting integrated floating platform assembly capacity to serve South Asian reservoir projects.
Industry Challenges
- Marine engineering talent scarcity:Project developers face compressed timelines recruiting professionals with combined expertise in photovoltaic system design and hydrodynamic mooring analysis.
- Water rights lease complexity:Multi-stakeholder negotiations with reservoir operators, irrigation authorities, and environmental regulators extend permitting timelines beyond standard solar development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Photovoltaics (FPV) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $21.76 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono-crystalline Panels, Poly-crystalline Panels, Thin-Film Modules, Bifacial Panels Application: Hydropower Reservoirs, Irrigation Ponds, Mining Pits, Drinking Water Reservoirs Deployment: Standalone Systems, Hybrid Systems, Grid-Connected Systems, Off-Grid Systems End User: Power Producers, Water Management Authorities, Agricultural Cooperatives, Environmental Agencies |
| Companies Covered | Kyocera Corporation, Canadian Solar, Ciel & Terre International, Swimsol, JinkoSolar Holding, Sungrow Power Supply, Sharp Corporation, SPG Solar, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Photovoltaics (FPV) Market Shifts & Advancements
Technology convergence between floating platform engineering and advanced photovoltaic cell architectures is compressing system cost curves while regulatory pressure on water body protection reshapes where solar capacity can be added.
Corrosion-resistant aluminum frame systems paired with high-density polyethylene floats are unifying structural durability with installation modularity. Hydropower operators across Japan and South Korea are specifying these integrated platforms for reservoir retrofits. The technology is unifying what were separate procurement streams—marine engineering and solar EPC—into single-contractor turnkey arrangements that reduce interface risk.
The EU F-Gas Regulation and accompanying Green Deal sustainability criteria are constraining virgin synthetic polymer use in float manufacturing. European project developers now specify recycled-content platforms to secure construction permits. German and Dutch installers report extended material qualification timelines as certification bodies validate alternative polymer formulations against twenty-year aquatic degradation standards.
Aggregated procurement by state-owned hydropower utilities is consolidating what were fragmented developer-led project pipelines. China's State Grid and Korea Water Resources Corporation now contract directly with integrated platform manufacturers, compressing distributor margins. South Korea's K-water procurement framework exemplifies this concentration, with multi-hundred-megawatt tenders replacing site-by-site developer auctions.
Floating Photovoltaics (FPV) Market Segmentation
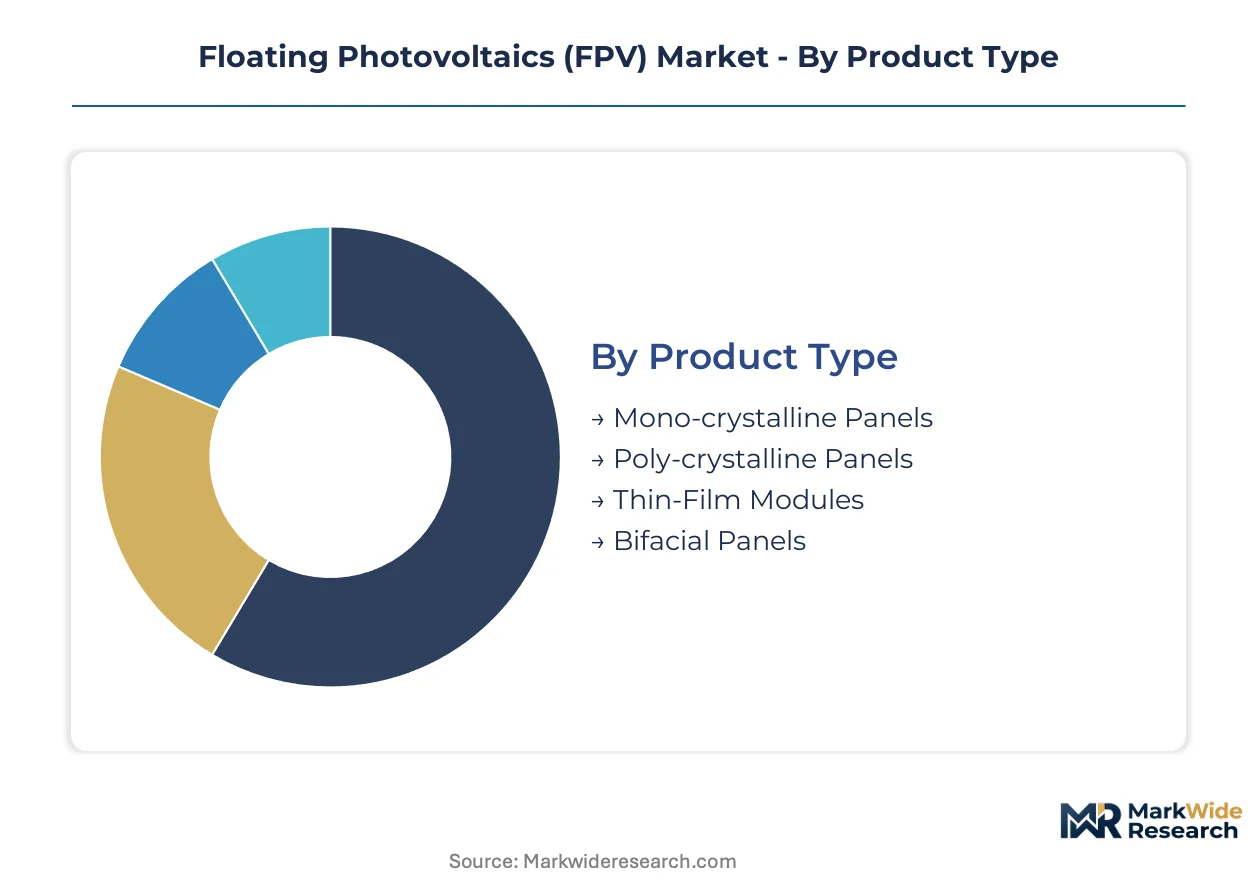
Floating photovoltaic systems fragment across four structural dimensions that determine procurement patterns and project economics. Product type and application geography drive capital allocation decisions, while deployment configuration and end-user category shape contracting structures and financing terms.
Product Type:
Buyers differentiate primarily by efficiency requirements and space constraints rather than upfront cost alone.
- Mono-crystalline Panels:Silicon ingots sliced from single crystals deliver conversion efficiencies above 20% in space-constrained floating environments. Japanese reservoir developers specify these for METI feed-in tariff projects where land availability is restricted.
- Bifacial Panels:Dual-sided cells capture direct irradiance plus reflected light from water surfaces, boosting yield by 5-20% depending on albedo conditions. South Korean K-water tenders increasingly mandate bifacial configurations for new hydropower reservoir installations.
- Poly-crystalline Panels:Multi-crystal silicon structures offer lower unit costs for budget-constrained irrigation pond deployments in India.
- Thin-Film Modules:Cadmium telluride and CIGS technologies provide flexibility and reduced weight for small-scale off-grid drinking water reservoir applications.
Volume sits with mono-crystalline configurations; growth tilts toward bifacial architectures.
Application:
Site selection determines permitting complexity, grid access economics, and environmental review timelines.
- Hydropower Reservoirs:Existing transmission infrastructure and water management permits collapse development timelines versus greenfield alternatives. China's State Grid and Korea Water Resources Corporation aggregate procurement across dam sites.
- Mining Pits:Abandoned extraction sites in Germany and Poland combine land remediation funding with renewable energy development, creating margin pools unavailable to conventional solar.
- Irrigation Ponds:Agricultural water bodies in India and Southeast Asia serve dual-use energy and evaporation-reduction purposes for farming cooperatives.
- Drinking Water Reservoirs:Stringent water quality requirements limit float material options to certified food-grade polymers, extending qualification timelines in EU jurisdictions under F-Gas Regulation.
Installed capacity concentrates at hydropower reservoirs; mining pit applications are climbing the fastest.
Deployment:
System architecture selection hinges on grid proximity, storage integration, and hybrid energy pairing.
- Hybrid Systems:Solar generation paired with existing hydropower infrastructure enables shared transmission and complementary generation profiles. Sungrow Power Supply anchors deployment across Asian reservoir projects.
- Grid-Connected Systems:Direct interconnection to utility networks dominates utility-scale procurement by state-owned power producers in China and South Korea.
- Standalone Systems:Islanded configurations serve remote irrigation and mining pit applications without existing electrical infrastructure.
- Off-Grid Systems:Battery-coupled deployments support isolated drinking water treatment facilities in rural geographies.
Procurement volumes favor hybrid configurations; standalone systems are expanding most quickly in emerging markets.
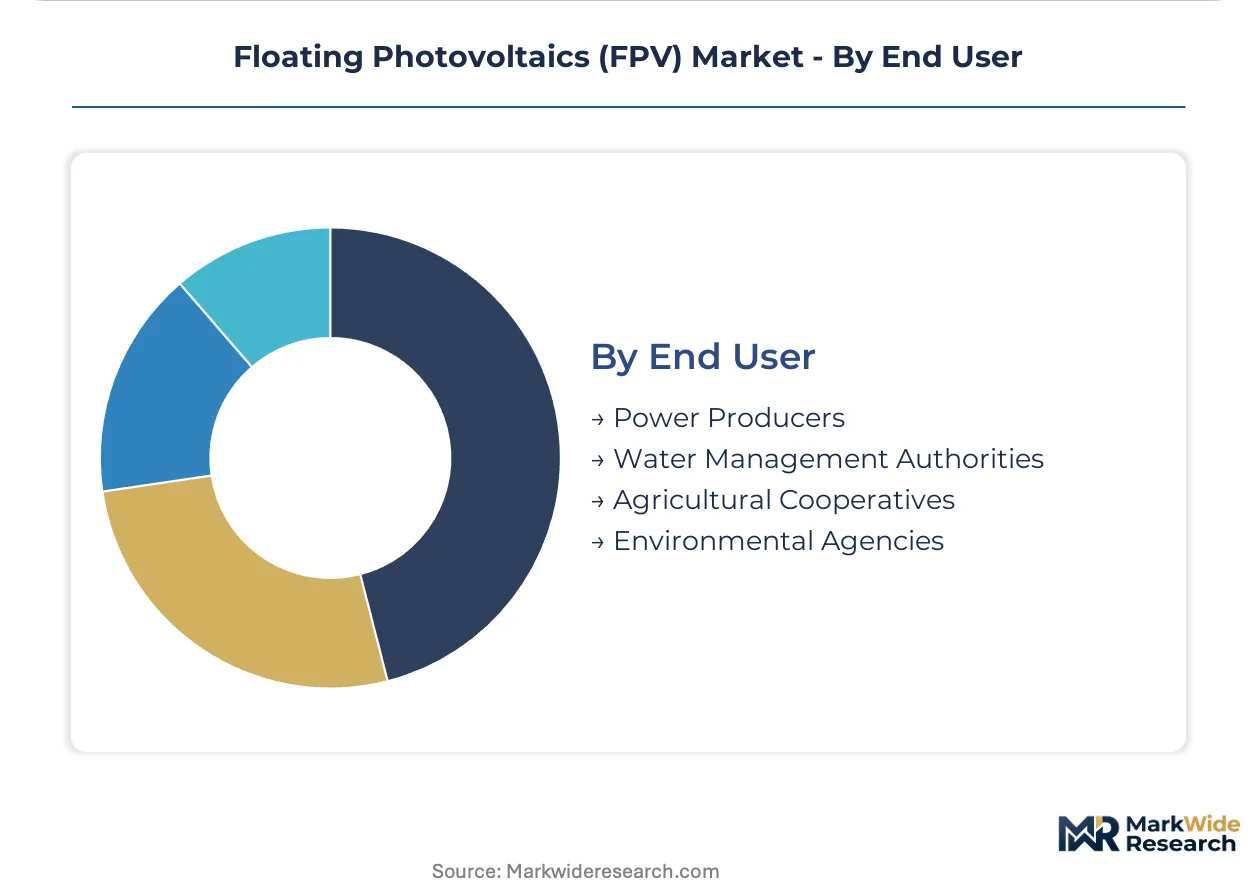
End User:
Contracting authority determines lease structures, environmental liability allocation, and payment security.
- Power Producers:State-owned utilities and independent power developers drive utility-scale procurement with long-term power purchase agreements. Aggregated tenders by K-water and China's State Grid consolidate what were fragmented developer pipelines.
- Water Management Authorities:Reservoir operators in Japan and South Korea specify floating solar as water evaporation control infrastructure with secondary energy revenue.
- Agricultural Cooperatives:Farming collectives in India deploy small-scale systems on irrigation ponds under PLI scheme manufacturing support.
- Environmental Agencies:Regulators in EU member states mandate floating solar on remediation sites to satisfy Green Deal sustainability criteria.
Contract flow concentrates with power producers; agricultural cooperatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-density polyethylene feedstock availability clusters near petrochemical complexes in East Asia and the Middle East, anchoring float platform manufacturing capacity. Project development concentrates where hydropower infrastructure intersects with renewable energy procurement mandates.
China
State Grid Corporation aggregates multi-hundred-megawatt tenders across hydropower reservoirs in Sichuan and Yunnan provinces. MEE water protection standards restrict ground-mounted solar on protected watersheds, accelerating FPV approvals as the compliant alternative. Yangtze River Delta manufacturers supply integrated floating platforms to domestic dam operators.
Japan
METI feed-in tariff frameworks create investable project economics for reservoir-based installations in Kanto and Kansai regions. Grid interconnection standards shape developer capital allocation toward hybrid solar-hydro configurations. Kyushu prefecture hosts concentrated engineering expertise for marine mooring system design.
South Korea
K-water procurement frameworks replace site-by-site developer auctions with centralized multi-hundred-megawatt tenders. K-water specifies bifacial panel configurations for new hydropower reservoir retrofits. Seoul Capital Area engineering firms anchor mooring system specialization for rapid capacity scaling.
Germany
Abandoned lignite mining pits in Lusatia combine land remediation funding with renewable energy development under EU Green Deal criteria. F-Gas Regulation constraints push float manufacturers toward recycled polymer substitutes with extended qualification timelines. North Rhine-Westphalia installers report certification delays for alternative polymer formulations.
India
PLI scheme manufacturing support attracts integrated floating platform assembly capacity to serve South Asian reservoir projects. Agricultural cooperatives in Gujarat and Maharashtra deploy small-scale systems on irrigation ponds under state-level water conservation mandates. Tamil Nadu engineering clusters develop corrosion-resistant aluminum frame systems for tropical aquatic environments.
Floating Photovoltaics (FPV) Market Competitive Landscape
Global majors compete with regional champions across platform engineering and power conversion integration. The vendor base spans integrated energy conglomerates, specialized marine engineering firms, and photovoltaic panel manufacturers extending into floating configurations. Three archetypes dominate: power electronics specialists leveraging conversion expertise, floating structure engineers competing on mooring reliability, and terrestrial panel leaders adapting bifacial technology for aquatic deployment. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure polymer supply contracts and marine engineering talent.
Among the integrated platform tier, Sungrow Power Supply and Ciel & Terre International exemplify divergent strategic positions. Sungrow occupies a position anchored in power conversion expertise applied to hybrid FPV deployment. Ciel & Terre represents specialized floating structure engineering with concentration on mooring system reliability. JinkoSolar Holding sits within the panel manufacturer archetype, extending terrestrial bifacial dominance into floating configurations. These three firms illustrate how supply chain control points fragment across electrical engineering, marine infrastructure, and photovoltaic cell manufacturing.
| Leading Market Players |
|---|
| Kyocera Corporation |
| Canadian Solar |
| Ciel & Terre International |
| Swimsol |
| JinkoSolar Holding |
| Sungrow Power Supply |
| Sharp Corporation |
| SPG Solar |
| Trina Solar |
| Others |
Supply & Pricing Matrix
K-water's aggregated procurement frameworks and China's State Grid multi-hundred-megawatt tenders are compressing distributor margins and forcing float manufacturers toward direct-contracting models that reshape pricing power across the value chain.
Pricing Analysis
Warranty and mooring-system engineering bundles separate premium-tier suppliers from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service intensity. Cost compression in standard tiers is intensifying because recycled polymer qualification timelines extend project development cycles. Agricultural cooperatives in India exhibit highest price sensitivity, while state-owned hydropower utilities in South Korea prioritize reliability over unit cost.
Supply Chain Analysis
Freight costs for high-density polyethylene floats scale nonlinearly with distance from Yangtze River Delta and Middle Eastern petrochemical clusters. Manufacturing concentrates in China, South Korea, and Germany. Raw material flows draw from virgin polymer feedstocks and recycled-content substitutes. Single-source vulnerability sits with specialized marine engineering talent pools in Japan and South Korea. Distribution runs through state-owned utility procurement frameworks and EPC contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine engineering talent scarcity props pricing for integrated platform providers, creating supply-constrained conditions that favor incumbent capacity holders.
For Market Incumbents: Anticipate bifacial panel specification mandates from K-water and China's State Grid by securing backward integration into corrosion-resistant aluminum frame production. Defensive consolidation around mooring system engineering firms in Kyushu and Seoul Capital Area clusters mitigates talent bottleneck risk. Prioritize certification investment for recycled polymer formulations ahead of EU F-Gas Regulation enforcement. For New Entrants and Emerging Players: Capture mining pit remediation opportunities in Germany's Lusatia region where land remediation funding intersects with renewable energy development. Poland's abandoned extraction sites offer parallel white-space penetration. Agricultural irrigation pond deployments in India's Gujarat and Maharashtra states provide lowest barrier-to-entry segment. Go-to-market through state-level water conservation mandate alignment accelerates permit acquisition. For Investors and Strategic Acquirers: The window for entry favors integrated platform manufacturers with captive polymer supply and marine engineering capabilities. Long-term viability hinges on hybrid solar-hydro project pipelines anchored to state-owned utility procurement. Acquisition target archetype: specialized floating structure engineers with proven mooring system reliability records. Signal to watch: K-water tender bifacial panel share thresholds as inflection indicator for technology convergence velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive high-density polyethylene sourcing insulates margins from petrochemical feedstock volatility. |
| Marine Engineering Talent Acquisition | Kyushu and Seoul Capital Area expertise clusters anchor mooring system reliability differentiation. |
| Recycled Polymer Certification Investment | EU F-Gas Regulation compliance unlocks German and Dutch construction permit pipelines. |
| Hybrid System Platform Integration | Sungrow's power conversion expertise demonstrates shared transmission infrastructure capture. |
| State-Owned Utility Direct Contracting | K-water and State Grid aggregation eliminates distributor margin layers. |
Research Methodology
Multi-period observation of K-water tender specifications, State Grid procurement volumes, and MEE approval timelines anchored the trend analysis, supplemented by interviews with hydropower utility planning officers, floating platform EPC contractors, marine mooring engineers, and polymer procurement specialists. Secondary validation drew from FERC filings, IEA renewable energy databases, EU Green Deal implementation reports, and customs trade data for high-density polyethylene float imports. Bottom-up project pipeline aggregation triangulated against top-down utility capacity announcements.
Segment-weighting across product type, application geography, deployment configuration, and end-user category shaped the analytical framework. Modeled dimensions included panel efficiency tier, reservoir type, hybrid versus standalone architecture, and contracting authority structure. CAGRs derived from utility procurement schedule aggregation and manufacturing capacity expansion announcements. Industry-specific forecast inputs incorporated MEE water protection standard enforcement trajectories and METI feed-in tariff revision patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polymer feedstock price volatility, marine engineering talent migration, and national water rights framework evolution. Forecasts reflect documented assumptions about regulatory enforcement intensity and state-owned utility capital allocation priorities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Global Photovoltaic Glass Market