
 US Solar Carport Market | 2026-2036
US Solar Carport Market Size, Share, and Industry Trends Forecast 2026-2036
US Solar Carport Market Insights
Market Dynamics
Educational institutions is restructuring procurement priorities for covered parking infrastructure across the United States. SunPower leverages its distributed generation expertise to capture premium commercial installations in high-irradiance states. DSD Renewables anchors its growth through engineering-procurement-construction capabilities that reduce soft costs for institutional buyers. Solaire Generation specializes in architecturally integrated structures that command price premiums in municipal and university segments.
Technology and Segmentation
A solar carport consists of an elevated photovoltaic array mounted on a structural canopy above parking spaces, typically engineered with steel or aluminum framing to achieve wind loads of 90-120 mph and integrated electrical routing through column conduits. Its primary commercial purpose is dual-use land optimization, generating renewable electricity while providing weather protection for vehicles in surface parking environments. Custom Solutions dominate margin pools due to engineering complexity and site-specific structural requirements, while Smart Structures represent the fastest-expanding category as module-level power electronics and EV charging integration become standard specifications. Ground-Mounted installations retain volume leadership though Multi-Use configurations incorporating battery storage and vehicle-to-grid capability are displacing conventional designs in forward-leaning utility territories.
Regulatory Environment
The Investment Tax Credit administered by the IRS and domestic content provisions within the Inflation Reduction Act shape procurement economics by rewarding projects utilizing American-manufactured steel and photovoltaic components. NHTSA parking structure safety guidelines and state-level building codes in California and Florida enforce seismic and wind-load engineering standards that filter out undercapitalized installers. Stakeholders must monitor evolving interpretations of domestic content thresholds and interconnection queue reforms as these determine project viability timelines more than module price fluctuations.
Market Dynamics
The IRA's domestic content bonus provisions are rewiring procurement economics for steel and module sourcing, forcing developers to requalify supply chains mid-project to capture the full 10 percentage point credit uplift.
Growth Catalysts
- California's Title 24 Building Energy Efficiency Standards:Mandates solar-ready construction for new parking structures, creating baseline demand that other states emulate.
- EV charging integration:School districts and municipal fleets prioritize carports with DC fast-charging infrastructure to qualify for NEVI program funding.
- Southwest irradiance corridors:Arizona, Nevada, and New Mexico combine high solar resource with expansive surface parking at airports and retail centers.
Market Restraints
- Structural steel price volatility:Galvanized steel framing represents 35-45% of installed costs, exposing projects to commodity swings that compress developer margins.
- Domestic module supply concentration:Limited US cell and wafer capacity forces reliance on Southeast Asian assembly, complicating IRA bonus qualification.
- Interconnection queue delays:FERC Order 2023 reforms remain unevenly implemented, stretching project energization timelines in congested utility territories.
Strategic Opportunities
- Texas municipal procurement:Deregulated power markets and absence of statewide net metering create behind-the-meter arbitrage opportunities for carport-plus-storage configurations.
- FEMA hazard mitigation grants:Carports engineered to 120 mph wind loads qualify for resilience funding, opening federal disaster preparedness budgets.
- Vehicle-to-grid convergence:Bidirectional charging hardware integration positions carports as grid assets eligible for utility capacity contracts.
Industry Challenges
- Structural engineering specialization:Fewer than 200 licensed professionals nationwide possess combined solar PV and parking structure seismic design expertise, creating bidding bottlenecks.
- Utility interconnection standardization:Divergent technical requirements across 3,000+ US electric utilities force repetitive redesign cycles that erode project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Solar Carport Market |
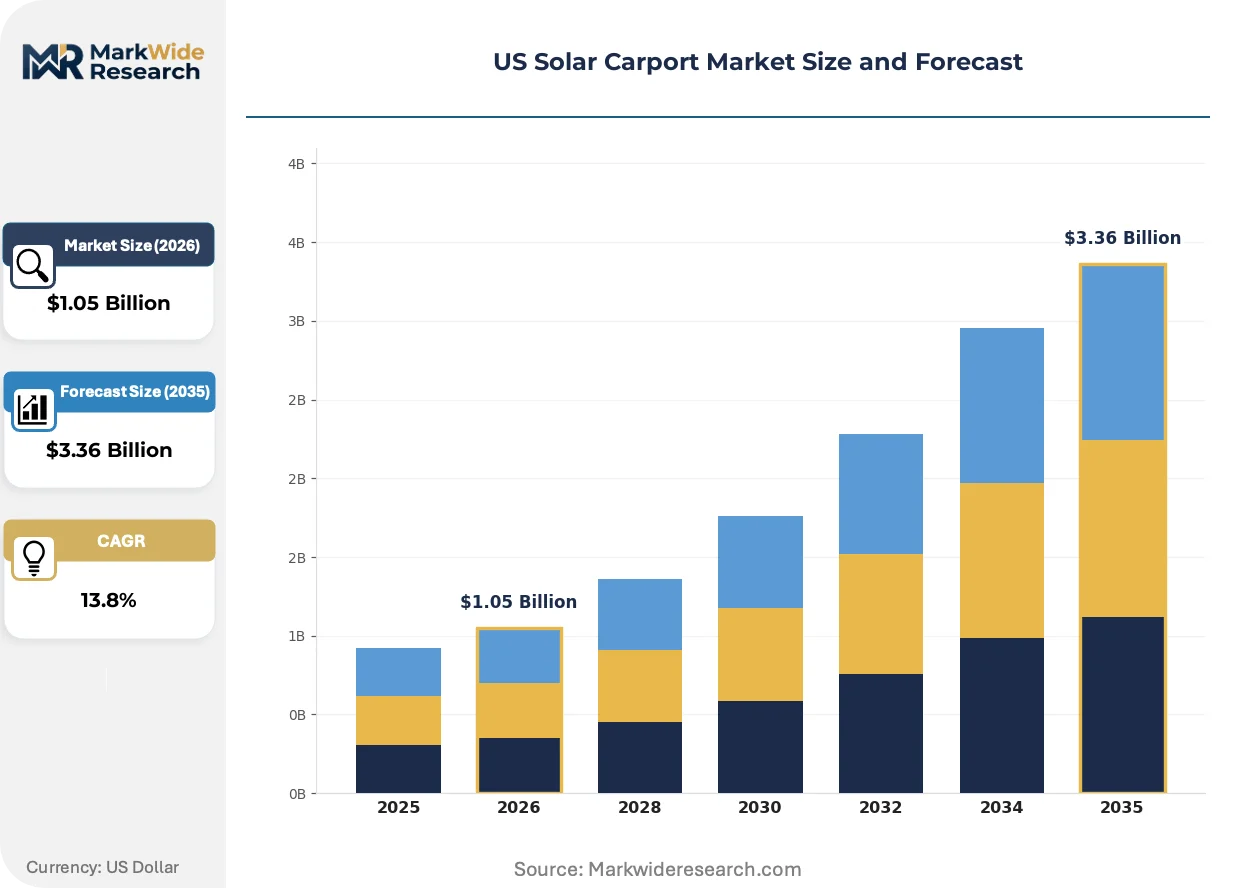
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Solutions, Standard Kits, Integrated Systems, Smart Structures Installation Type: Ground-Mounted, Rooftop, Multi-Use, Temporary Structures End User: Commercial, Residential, Government, Educational Institutions Material: Aluminum, Steel, Polymer, Composite |
| Companies Covered | Envision Solar, Solaire Generation, SunPower, DSD Renewables, Quest Renewables, SolarDock, Borrego Solar, Solar Optimum, Pivot Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Solar Carport Market Trends and Innovations
Hardware standardization and software-defined energy management are collapsing the traditional boundary between static infrastructure and grid-interactive assets. Developers now specify carports as programmable load nodes rather than passive generation.
Prefabricated steel canopy systems with integrated cable management and pre-wired junction boxes are modularizing project delivery. EPC contractors in Texas and Florida are adopting these kits to compress installation schedules from 12 weeks to 6 weeks. The shift is compressing soft costs and allowing smaller regional installers to compete for institutional contracts previously dominated by national firms.
The IRA's domestic content safe harbor guidance from the Treasury Department is reshaping sourcing protocols. Projects must now document American-made steel through mill certificates and track module assembly location to capture bonus credits. California school districts are responding by requiring domestic content attestations in RFP technical specifications, effectively pre-filtering bidder pools.
Power purchase agreement structures are displacing direct ownership for public sector buyers. Municipalities in Arizona and Colorado are signing 20-25 year solar service contracts that bundle carport construction, maintenance, and energy output into single monthly payments. This shift transfers performance risk to private capital while preserving budget predictability for facilities managers.
US Solar Carport Market Segmentation
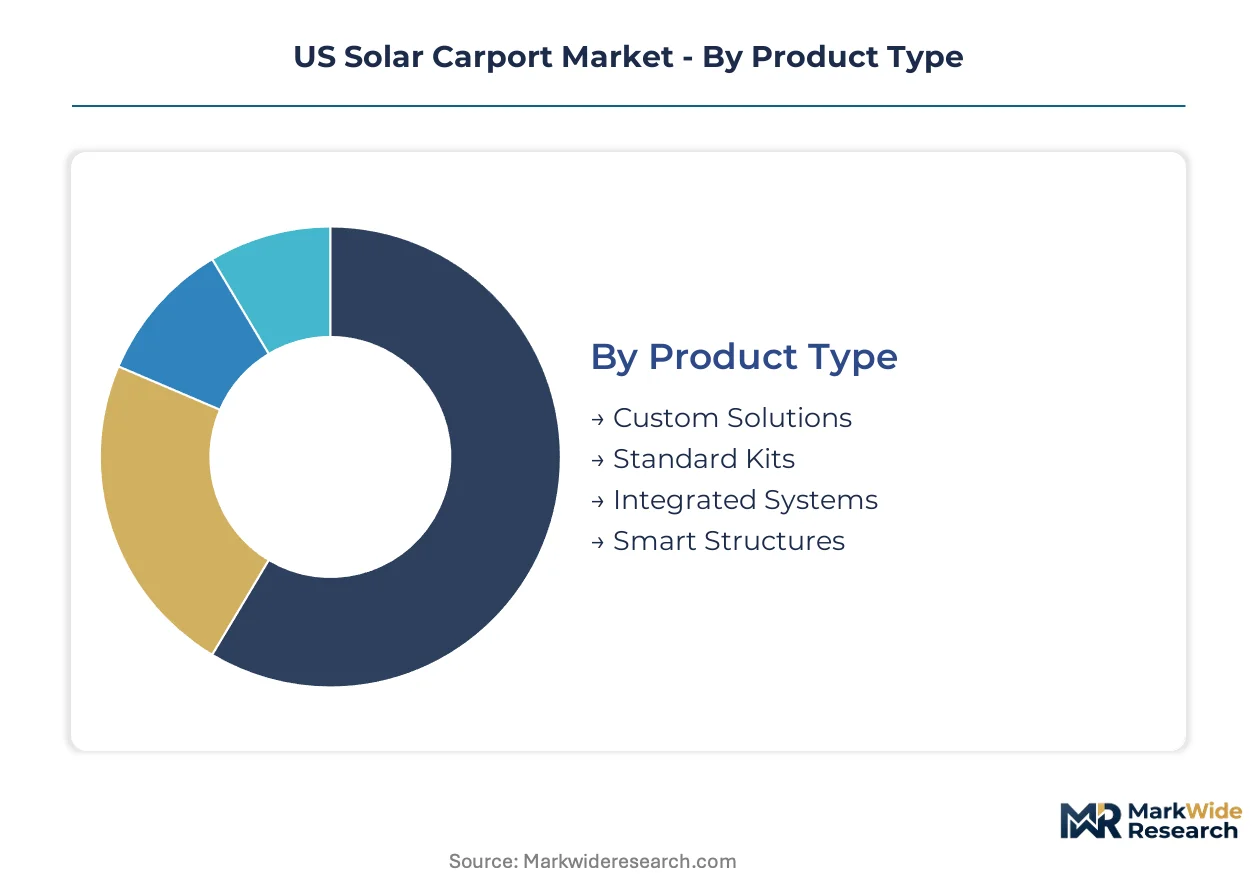
Segmentation in the US solar carport market reveals how procurement priorities diverge across institutional buyers, material specifications, and integration complexity. Understanding these divides exposes where margin pools concentrate and which technical configurations align with federal incentive structures.
Product Type:
Buyers weighing total cost of ownership against customization needs drive product selection, with engineering complexity and site constraints determining premium capture potential.
- Custom Solutions:Engineered-to-order steel or aluminum framing systems designed for specific wind loads, seismic zones, and architectural requirements. California school districts and Arizona municipal fleets commission these for NEVI-funded EV charging integration, accepting 20-30% cost premiums for site-specific structural validation.
- Smart Structures:Canopy systems with embedded module-level power electronics, battery storage racking, and bidirectional EV charging hardware. Texas deregulated utilities and Colorado campuses are specifying these for grid-interactive revenue streams, though supply chain documentation for IRA domestic content bonuses complicates procurement.
- Standard Kits:Pre-engineered canopy packages with fixed dimensions and limited electrical integration options.
- Integrated Systems:Bundled offerings combining carport structure, PV modules, and single-inverter architecture.
Custom Solutions leads on scale; Smart Structures leads on momentum.
Installation Type:
Site availability and grid interconnection economics determine installation approach, with dual-use configurations gaining preference where land values or utility rate structures reward complexity.
- Ground-Mounted:Surface parking canopies on driven pile or concrete pier foundations, dominating volume across retail centers and airport long-term parking. Southwest states with expansive surface lots and high solar irradiance favor these for straightforward permitting and standardized structural engineering.
- Multi-Use:Configurations incorporating battery storage enclosures, vehicle-to-grid hardware, and stormwater management systems. Florida municipalities and Texas independent school districts are specifying these for FEMA hazard mitigation grant eligibility and behind-the-meter arbitrage.
- Rooftop:Elevated structures mounted on existing parking garages or mixed-use buildings.
- Temporary Structures:Ballasted or anchored systems designed for relocation, serving construction sites and event venues.
Ground-Mounted dominates installed base; Multi-Use climbs the fastest as storage economics improve.
End User:
Capital availability and incentive access create distinct procurement patterns across ownership structures, with public sector buyers prioritizing risk transfer and private entities focusing on depreciation capture.
- Educational Institutions:K-12 districts and universities leveraging covered parking for utility cost reduction and student transportation electrification. California Title 24 compliance mandates and IRA direct pay provisions for tax-exempt entities are accelerating procurement timelines in this segment.
- Government:Federal, state, and municipal fleets pursuing carport-plus-storage configurations. Arizona and Colorado municipalities are signing 20-25 year solar service agreements that bundle construction, maintenance, and energy output, transferring performance risk to private capital.
- Commercial:Retail centers, office parks, and healthcare facilities with surface parking assets.
- Residential:Single-family and multi-family developments with dedicated parking structures.
Educational Institutions leads on near-term pipeline; Government leads on contract duration innovation.
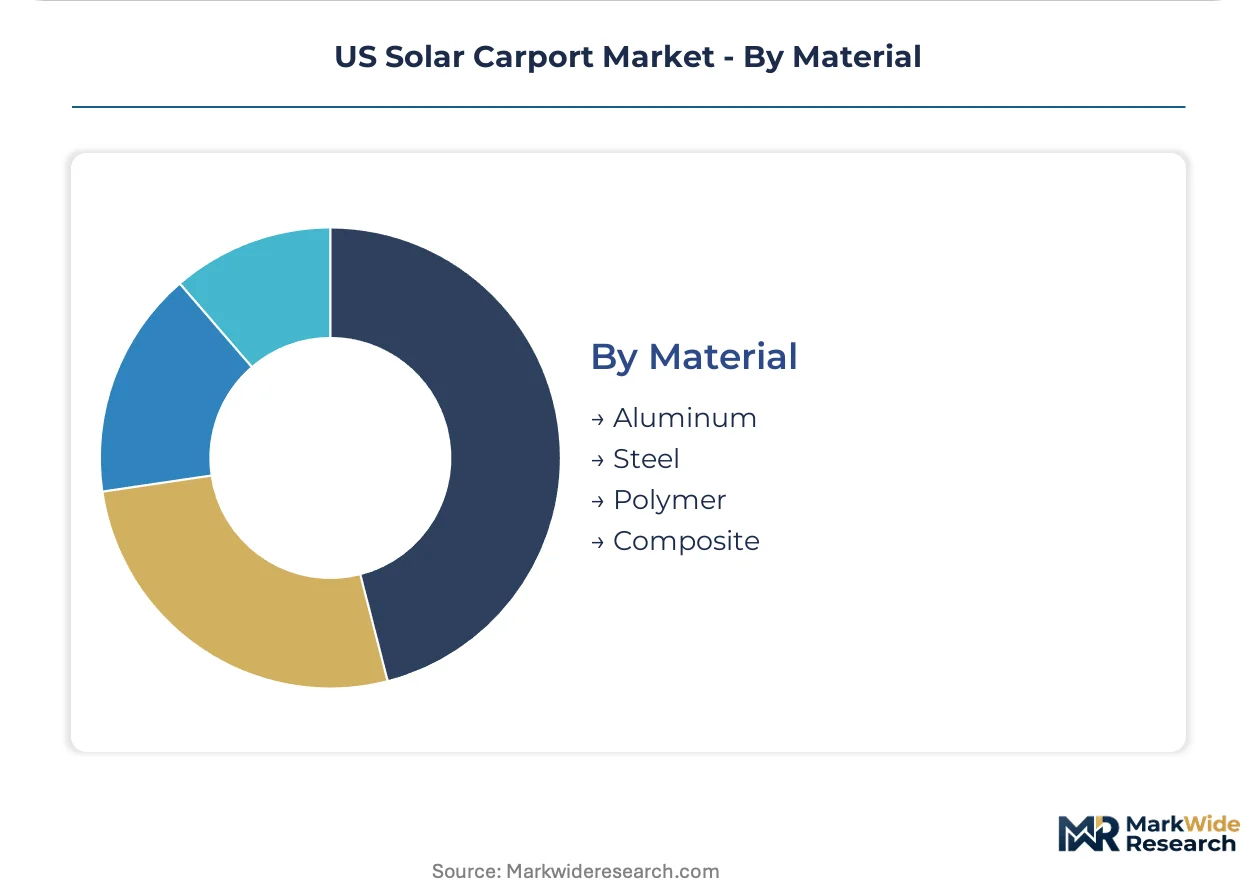
Material:
Domestic content bonus qualification and structural engineering specialization requirements are reshaping material specification, with mill certificate documentation now standard in public RFPs.
- Steel:Galvanized structural sections achieving 90-120 mph wind loads, representing 35-45% of installed costs. California school districts are requiring domestic mill certificates to satisfy IRA domestic content safe harbor guidance, filtering bidder pools to suppliers with traceable US sourcing.
- Aluminum:Corrosion-resistant framing for coastal Florida and Gulf Coast installations, commanding price premiums for salt-air durability. Miami-Dade County building code compliance drives specification here.
- Polymer:Reinforced composite columns and canopy elements for lightweight applications.
- Composite:Hybrid material systems combining fiber reinforcement with metallic connection points.
Steel leads on volume; Aluminum leads on margin expansion in coastal zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developers are relocating engineering talent and procurement operations toward states with streamlined interconnection procedures and domestic content bonus clarity, exploiting cost-of-compliance gaps that stretch project viability timelines.
California
School districts in Los Angeles and San Diego counties are accelerating covered parking procurement to satisfy Title 24 solar-ready mandates for new construction. The California Energy Commission enforces these standards through building permit approvals, filtering out developers lacking seismic engineering capabilities. Sacramento-area installers are consolidating prefabrication facilities to compress delivery schedules for institutional buyers.
Texas
Deregulated power markets in ERCOT territory enable behind-the-meter arbitrage for carport-plus-storage configurations at municipal fleet depots. The Texas Commission on Environmental Quality administers alternative fuel infrastructure grants that subsidize EV charging integration. Dallas-Fort Worth airport authorities are specifying multi-use canopies with battery enclosures to capture resilience funding and peak-shaving revenue.
Arizona
High solar irradiance in Maricopa County drives ground-mounted volume for retail centers and healthcare campuses seeking utility cost reduction. The Arizona Corporation Commission oversees renewable energy standards that municipal utilities must satisfy through distributed generation. Phoenix-area engineering firms are specializing in 120 mph wind-load designs that qualify for FEMA hazard mitigation grants.
Florida
Miami-Dade and Broward counties are specifying aluminum-framed coastal installations to satisfy salt-air durability requirements in hurricane-prone zones. The Florida Building Commission enforces wind-load standards that exceed national baselines, creating barriers for out-of-state installers. Orlando municipal fleets are bundling carport construction with 20-year solar service agreements to transfer performance risk.
Colorado
University campuses in Boulder and Denver are prioritizing smart structures with bidirectional charging hardware for grid-interactive revenue streams. The Colorado Public Utilities Commission oversees net metering reforms that reward behind-the-meter storage dispatch. Front Range installers are qualifying for IRA domestic content bonuses through traceable steel sourcing from regional mills.
US Solar Carport Market Competitive Landscape
Strategic partnerships dominate the current landscape as engineering-procurement-construction firms ally with module suppliers and steel fabricators to secure domestic content documentation. The vendor base clusters around three archetypes: integrated EPC operators with in-house structural engineering, specialized canopy fabricators focusing on architectural integration, and regional installers leveraging prefabricated kits to compress soft costs. Capacity expansion and portfolio diversification represent the primary competitive vectors, with developers adding storage integration capabilities and EV charging hardware to standard offerings.
Among the named players, SunPower occupies a position exemplifying distributed generation expertise applied to premium commercial installations, while DSD Renewables anchors the EPC-integrated archetype through engineering capabilities that reduce institutional procurement friction. Solaire Generation sits within the architectural specialization tier, representing design-forward approaches that command price premiums in municipal and university segments where aesthetic compliance drives specification.
| Leading Market Players |
|---|
| Envision Solar |
| Solaire Generation |
| SunPower |
| DSD Renewables |
| Quest Renewables |
| SolarDock |
| Borrego Solar |
| Solar Optimum |
| Pivot Energy |
| Others |
Pricing and Supply Chain Analysis
Prefabricated steel canopy systems with integrated electrical routing are collapsing installation timelines while simultaneously concentrating procurement leverage among domestic fabricators with mill certificate documentation capabilities. This production-method transition rewards EPC contractors who qualify for IRA domestic content bonuses while squeezing margin pools for installers lacking traceable supply chain relationships.
Pricing Analysis
Distributor margins on galvanized steel framing systems range between 12-18 percent, with direct-to-institutional contracts commanding steeper discounts for volume commitments above 500 kW. Pricing stratifies across custom-engineered, smart-integrated, and standard kit tiers, with wind-load certification grade and EV charging hardware bundling as primary differentiation drivers. Cost compression in standard kit configurations is intensifying because regional prefabricators are bypassing national distributors to serve Texas and Florida school districts directly. Municipal procurement officers exhibit highest price sensitivity, while university facilities managers prioritize architectural integration over per-watt economics.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian module assembly for IRA bonus qualification, forcing developers to maintain dual-qualified supplier relationships despite capacity constraints. Domestic steel production centers on Indiana, Ohio, and Pennsylvania mills, while aluminum extrusion for coastal applications draws from Tennessee and South Carolina facilities. Supply chain risk centers on tariff exposure for imported cells and wafers. Distribution runs through EPC-integrated direct fulfillment to institutional buyers, bypassing traditional electrical supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the US solar carport market rests on prefabrication-driven soft cost reduction and premium capture from grid-interactive smart structures. The shift toward domestic content compliance is filtering bidder pools toward vertically integrated fabricators.
For Market Incumbents: Deploy in-house structural engineering certification to defend against emerging regional prefabricators. Consolidate mill relationships in Indiana and Ohio to secure domestic content documentation for California school district RFPs. Add battery storage integration capabilities to standard offerings before Texas municipal procurement shifts exclusively to carport-plus-storage specifications. For New Entrants and Emerging Players: Bidirectional charging hardware integration offers a technology-first wedge into Colorado university campuses and Arizona municipal fleets where grid-interactive revenue streams justify premium pricing. Target Florida coastal installations with aluminum-framed corrosion-resistant designs that satisfy Miami-Dade County building codes. Pursue FEMA hazard mitigation grant eligibility as a go-to-market angle for 120 mph wind-load engineering validation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional installers with prefabrication capabilities but limited balance sheet scale to capture IRA direct pay provisions for tax-exempt entities. Long-term viability favors EPC operators with captive steel sourcing and module supplier relationships that survive domestic content safe harbor scrutiny. Watch interconnection queue reform implementation pace as the signal for project energization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Steel Sourcing Certification | IRA bonus qualification requires mill certificates from Indiana, Ohio, or Pennsylvania producers. |
| Prefabrication Facility Consolidation | Sacramento-area and Dallas-Fort Worth hubs compress delivery schedules for institutional buyers. |
| Battery Storage Integration | ERCOT behind-the-meter arbitrage and FEMA resilience funding expand addressable project budgets. |
| Structural Engineering Specialization | Seismic and wind-load expertise filters California and Florida procurement to qualified bidders. |
| Power Purchase Agreement Structuring | 20-25 year solar service contracts transfer performance risk from Arizona municipalities to private capital. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with EPC project developers, utility interconnection planners, school district facilities directors, steel fabrication procurement managers, and IRA tax credit advisory specialists with secondary validation against FERC interconnection queue data, EIA distributed generation statistics, California Energy Commission building permit records, and Treasury Department domestic content guidance documents. Bottom-up project pipeline aggregation and top-down incentive expenditure analysis were triangulated to verify market sizing.
Segment-weighting applied product type, installation configuration, end-user category, and material specification dimensions across the modeling period. CAGRs were derived from fitted trend analysis of historical procurement volumes and projected incentive uptake curves. Forecast inputs incorporated IRA direct pay utilization rates for tax-exempt entities and Title 24 compliance mandate implementation pace in California counties.
The model holds under sustained IRA credit extension and interconnection queue reform implementation; deviation in structural steel commodity volatility or domestic module supply disruption would shift project viability timelines. Forecasts reflect documented assumptions about incentive continuity and regulatory interpretation stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Concentrated Photovoltaic System Market