
 United States Smoothie Market | 2026-2036
United States Smoothie Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smoothie Market Intelligence
Premium-grade ingredient specifications is reorganizing competitive dynamics in the United States smoothie landscape. Smoothie King leverages its extensive franchise footprint to sustain nationwide presence while emphasizing functional nutrition claims. Tropical Smoothie Cafe anchors its position through rapid unit expansion across suburban markets. Bolthouse Farms differentiates via captive agricultural supply chains that control raw produce quality from field to bottle.
A smoothie is a blended beverage typically comprising fruit, vegetables, liquid bases, and optional protein or supplement additives, processed through high-shear blending to achieve homogeneous texture without enzymatic degradation of heat-sensitive micronutrients. Its primary commercial purpose is delivering convenient, nutrient-dense refreshment aligned with wellness-oriented consumption patterns. Fruit smoothies dominate volume due to established palatability and lower ingredient costs, while protein smoothies capture disproportionate margin pools as fitness-oriented consumers accept higher price points for functional benefits. Online retailers represent the fastest-growing distribution channel as cold-chain logistics improve and subscription models reduce customer acquisition friction.
FDA nutrition labeling mandates, USDA organic certification standards, and state-level health department food safety codes collectively shape product formulation, sourcing transparency, and operational compliance burdens across the industry. The FDA's added sugar disclosure requirements are accelerating reformulation investments toward naturally sweetened profiles using whole fruit rather than concentrated juices. Stakeholders must monitor evolving FDA guidance on nutrient content claims and emerging state-level packaging waste regulations that could reshape single-serve container economics.
Market Dynamics
FDA's added sugar disclosure mandate is compressing formulation timelines across the United States smoothie industry. Brands face 24-month reformulation windows to maintain shelf placement as retailers enforce compliance ahead of enforcement dates.
Growth Catalysts
- USDA Organic Certification:Premium positioning through certified organic supply chains attracts health-focused consumers willing to pay ingredient-grade premiums.
- Post-Workout Nutrition Habits:Fitness enthusiasts now prioritize whole-food recovery formats over synthetic protein isolates, expanding addressable occasions.
- Cold-Chain Logistics Modernization:Refrigerated last-mile delivery networks enable direct-to-consumer subscription models previously uneconomical at scale.
Market Restraints
- Fresh Produce Input Volatility:Weather-driven strawberry and banana price swings compress gross margins during off-season procurement cycles.
- California Supply Concentration:Seventy percent of domestic leafy green sourcing clusters in Central Valley counties exposed to drought and labor disruption.
- High-Pressure Processing Bottleneck:Limited HPP tolling capacity constrains clean-label shelf-stable product launches.
Strategic Opportunities
- Texas and Florida Expansion:Underpenetrated Sun Belt metros with year-round warm climates support drive-through smoothie unit economics.
- Functional Ingredient Convergence:Adaptogen and nootropic blending creates differentiated SKUs targeting cognitive performance seekers.
- IRA Clean Energy Incentives:Solar-powered production facilities qualify for federal tax credits reducing operational carbon footprints.
Industry Challenges
- Food Safety Modernization Act Compliance:Preventive controls qualified individual hiring lags behind FDA inspection frequency increases.
- Legacy ERP Integration:Batch-level traceability systems require costly middleware to connect with existing inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smoothie Market |
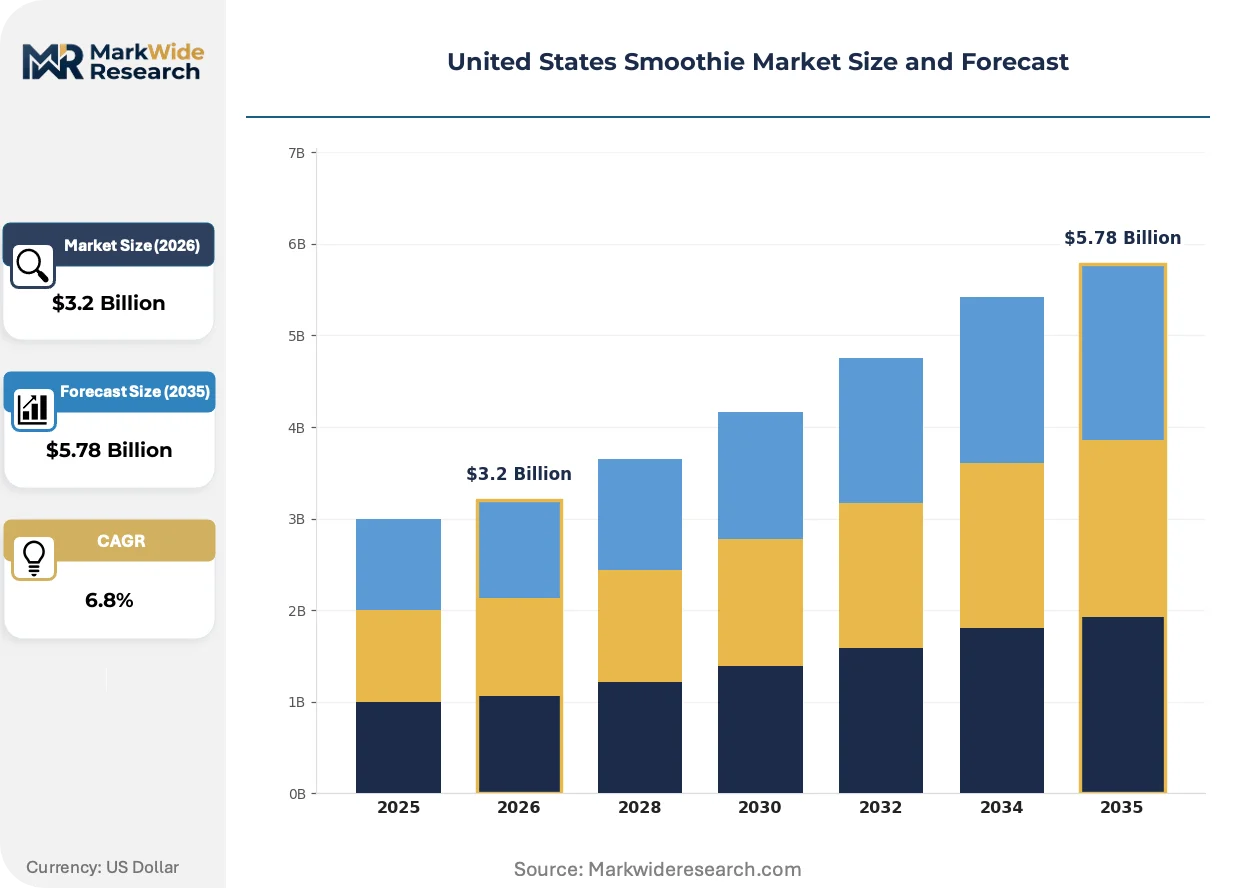
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Smoothies, Green Smoothies, Protein Smoothies, Detox Smoothies Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Cafes Price Tier: Premium, Mid-Range, Economy, Discount Customer Type: Fitness Enthusiasts, Health-Conscious Consumers, Students, Professionals |
| Companies Covered | Smoothie King, Jamba, Tropical Smoothie Cafe, Bolthouse Farms, Barfresh Food Group, Suja Juice, Maui Wowi Hawaiian Coffees & Smoothies, The Coca-Cola Company, PepsiCo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smoothie Market Strategic Shifts & Innovations
Whole-fruit sweetening protocols are replacing concentrated juice bases across premium smoothie formulations. This shift responds to clean-label scrutiny while preserving viscosity and mouthfeel.
High-pressure processing is supplanting thermal pasteurization in refrigerated smoothie manufacturing. Cold-pressed juice specialists and emerging DTC brands are adopting HPP at 40% annual equipment investment rates. This technology is supplanting conventional hot-fill lines by preserving enzyme activity and extending refrigerated shelf life without chemical preservatives.
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing recipe transparency. Reformulation investments now prioritize whole fruit matrices over juice concentrates to minimize declared added sugar content. Protein smoothie SKUs face the steepest compliance costs as existing formulations rely heavily on flavored protein isolates with masking syrups.
Subscription-based replenishment is displacing impulse convenience store purchases among core smoothie consumers. Digital-native brands capture recurring revenue through customizable flavor rotations delivered weekly. This pattern concentrates in coastal metropolitan markets where delivery density supports frozen logistics economics.
United States Smoothie Market Segmentation
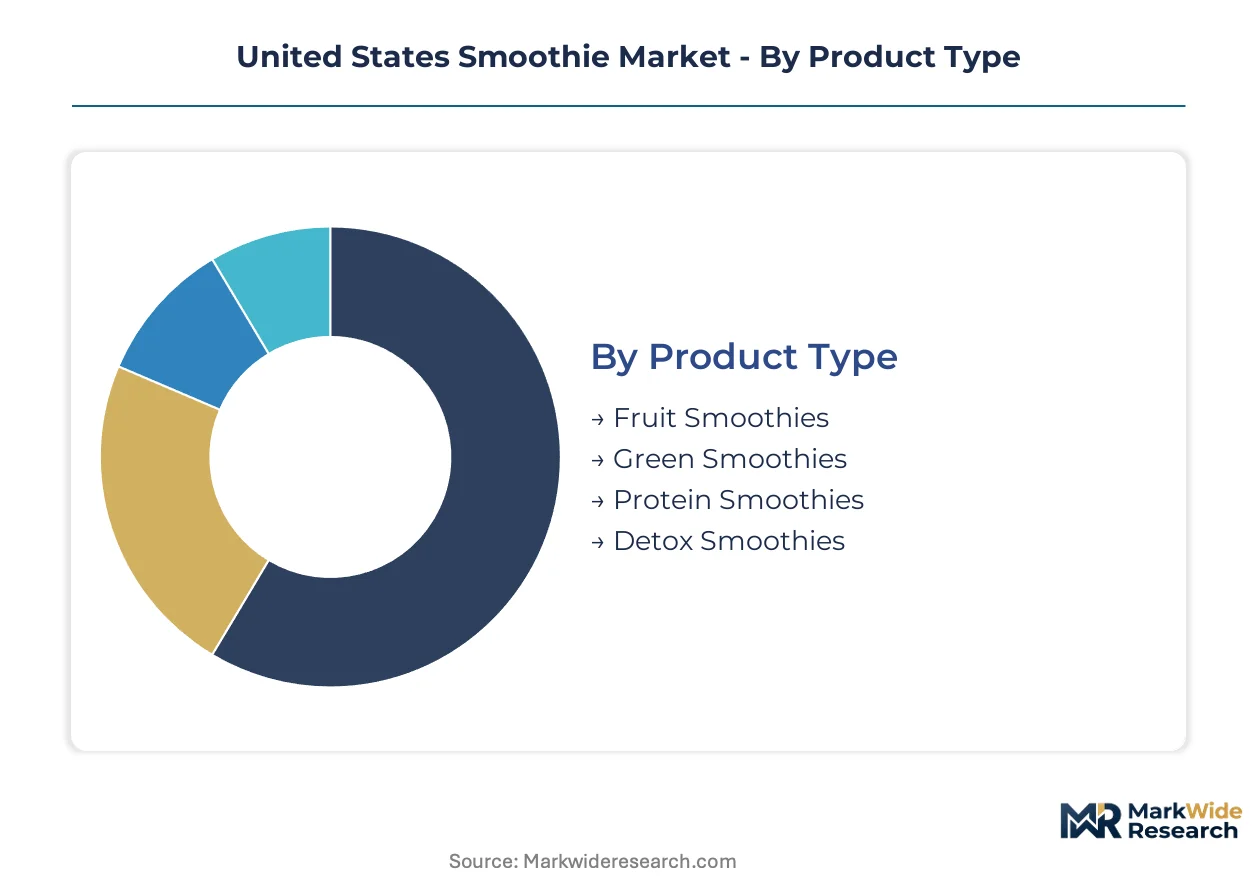
Smoothie market segmentation reveals distinct procurement patterns across consumption occasions and retail formats. Category boundaries increasingly blur as functional ingredients penetrate traditional fruit-based formulations. Understanding these divides enables targeted positioning against specific nutrition missions and channel economics.
Product Type:
Domestic consumption concentrates in fruit-forward formulations, while protein-fortified variants show stronger traction in export-adjacent coastal markets with fitness tourism density.
- Fruit Smoothies:Blended beverages relying on whole fruit bases—strawberry, banana, mango—delivering natural sweetness without declared added sugars. Demand clusters in California and Florida retail corridors where year-round produce access supports fresh-daily production models. FDA labeling mandates accelerate reformulation toward whole-fruit matrices to minimize added sugar declarations.
- Protein Smoothies:Functional formulations incorporating whey, plant, or collagen protein isolates targeting post-workout recovery occasions. Fitness enthusiasts in Texas and Arizona metro areas drive disproportionate volume through gym-adjacent retail and subscription replenishment. Reformulation costs spike as brands remove flavored protein syrups to comply with added sugar disclosure rules.
- Green Smoothies:Vegetable-dominant blends featuring spinach, kale, and celery with minimal fruit masking. Health-conscious consumers in Pacific Northwest urban cores sustain regional production kitchens.
- Detox Smoothies:Limited-ingredient formulations emphasizing activated charcoal, chlorophyll, or herbal extracts. Niche demand concentrates in Los Angeles and Miami wellness retail circuits.
Fruit smoothies command the established base. The steepest expansion runs through protein smoothies.
Distribution Channel:
Channel selection directly determines margin structure and cold-chain investment requirements, with digital-native routes demanding fundamentally different logistics architecture than brick-and-mortar placement.
- Supermarkets:Mass-market refrigerated cases in Kroger, Whole Foods, and regional chains drive volume through promotional pricing and impulse placement. Grocery buyers in suburban Sun Belt counties increasingly stock grab-and-go formats with extended shelf life from high-pressure processing.
- Online Retailers:Direct-to-consumer subscription models and frozen delivery services bypass retail margin extraction. Cold-chain logistics modernization enables weekly replenishment economics in Northeast and West Coast metropolitan corridors with sufficient delivery density.
- Health Food Stores:Independent and regional chains like Sprouts Farmers Market curate premium and organic-certified SKUs. Localized procurement from Central Valley produce suppliers supports freshness claims.
- Cafes:Made-to-order blending in dedicated smoothie shops and coffeehouse menus captures immediate-consumption occasions. Drive-through unit economics prove viable in Texas and Florida expansion markets with year-round warm weather.
Supermarkets anchor volume throughput. Online retailers are gaining share fastest through subscription lock-in.
Price Tier:
Premium positioning requires organic certification and clean-label transparency, while economy tiers compete on volume efficiency and conventional produce sourcing.
- Premium:USDA organic certification, high-pressure processing, and functional ingredient fortification justify price multiples. Coastal metropolitan consumers in San Francisco and New York demonstrate sustained willingness to pay ingredient-grade premiums for supply chain transparency.
- Mid-Range:Conventional produce with selective organic flagship SKUs balances accessibility and margin. Suburban family households in Midwest metro areas drive consistent replenishment patterns.
- Economy:Conventional fruit bases and thermal pasteurization minimize unit costs for price-sensitive bulk purchasing. Discount retailers and institutional foodservice channels concentrate demand.
- Discount:Value-positioned offerings with juice concentrate bases and minimal protein fortification. Convenience store impulse purchases and student-oriented campus retail sustain placement.
Premium tiers capture margin concentration. Economy segments face compression from input volatility.
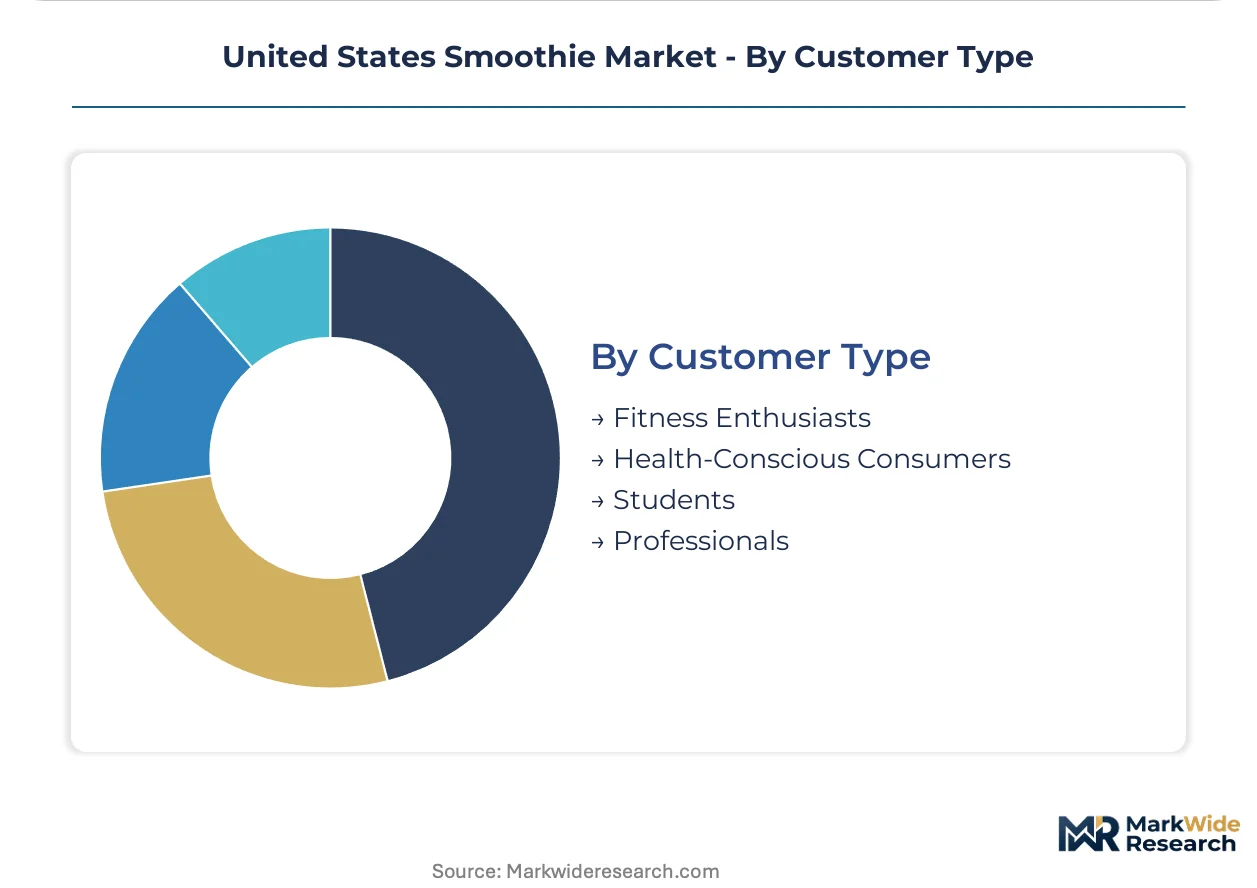
Customer Type:
Occasion-based segmentation aligns formulation complexity with specific nutrition missions, from athletic performance to workplace convenience.
- Fitness Enthusiasts:Protein-focused consumers prioritizing post-workout recovery with whole-food formats over synthetic isolates. Gym membership density in Colorado and Arizona correlates with highest per-capita consumption.
- Health-Conscious Consumers:Clean-label seekers emphasizing organic certification and minimal processing. Parental households in Pacific Northwest and Northeast urban cores drive pediatric-friendly formulation demand.
- Students:Price-sensitive demand for meal-replacement convenience on campuses with limited kitchen access. University town retail clusters in Midwest and Southeast sustain seasonal volume patterns.
- Professionals:Time-constrained urban workers seeking breakfast substitution and afternoon energy without coffee dependency. Downtown business district grab-and-go locations in Chicago and Seattle capture commute-adjacent occasions.
Fitness enthusiasts drive the steepest category expansion. Health-conscious consumers provide the stable revenue foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States smoothie market operates as a net importer of tropical fruit concentrates while exporting high-pressure processed finished goods to Canada and Mexico. Domestic production clusters in states with year-round produce access and cold-chain infrastructure density.
California
Central Valley leafy green cultivation supplies seventy percent of domestic smoothie-grade spinach and kale to manufacturers. FDA's Food Safety Modernization Act preventive controls enforcement intensifies audit frequency for Salinas Valley processing facilities. Los Angeles and San Francisco metro areas sustain the nation's highest per-capita consumption through premium juice bar density and subscription delivery penetration.
Texas
Dallas-Fort Worth and Houston drive-through smoothie unit economics benefit from extended warm-weather seasons and suburban sprawl patterns. State health department food safety codes mandate HACCP documentation for mobile blending operations. Austin's fitness tourism corridor anchors protein smoothie demand through gym-adjacent retail placement.
Florida
Miami and Tampa Bay metropolitan markets concentrate detox and functional ingredient demand among wellness tourism circuits. State agricultural extension programs promote domestic strawberry cultivation to reduce import dependency from Mexico. Orlando's theme park hospitality sector institutionalizes smoothie placement in resort foodservice contracts.
New York Metro
Manhattan and Brooklyn digital-native subscription brands capture recurring revenue through customizable weekly replenishment models. New York State Department of Agriculture and Markets enforces Grade A pasteurized milk standards for dairy-based protein formulations. Cold-chain logistics providers cluster in New Jersey distribution corridors serving Northeast metropolitan delivery density.
Pacific Northwest
Seattle and Portland health-conscious consumers sustain regional green smoothie production kitchens emphasizing organic certification. Oregon Department of Agriculture organic certification programs support supply chain transparency claims. Portland's food startup incubator ecosystem seeds emerging adaptogen-blending specialists targeting cognitive performance positioning.
United States Smoothie Market Key Industry Players
Listed beverage conglomerates compete with private franchise operators across unit expansion velocity and formulation agility dimensions. The vendor base stratifies into three tiers: captive agricultural supply chains, rapid-service franchise networks, and digital-native direct-to-consumer specialists. Dominant competitive moves include cold-chain logistics partnerships and USDA organic certification acquisition.
Within the franchise network tier, Smoothie King and Tropical Smoothie Cafe exemplify national footprint strategies through suburban drive-through penetration. Bolthouse Farms occupies a position representing captive agricultural integration from field to bottle. These three anchors illustrate divergent paths to market presence: franchise scalability versus upstream supply control versus retail shelf placement.
| Leading Market Players |
|---|
| Smoothie King |
| Jamba |
| Tropical Smoothie Cafe |
| Bolthouse Farms |
| Barfresh Food Group |
| Suja Juice |
| Maui Wowi Hawaiian Coffees & Smoothies |
| The Coca-Cola Company |
| PepsiCo |
| Others |
Cost & Logistics Intelligence
Fourteen-day frozen fruit inventory cycles concentrate procurement leverage among Central Valley handlers, amplifying their pricing power during off-season supply gaps while pressuring reformulation economics for brands locked into fresh-only claims.
Pricing Analysis
Fitness enthusiasts anchor subscription-based pricing structures across premium protein formulations. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified SKUs from conventional produce lines and juice-concentrate economy tiers. Cost compression in economy tiers is intensifying because thermal pasteurization brands face HPP-equipped competitor encroachment. Students demonstrate highest price sensitivity, while health-conscious consumers in coastal metros accept ingredient-grade premiums.
Supply Chain Analysis
Just-in-time leafy green procurement dominates California production kitchens, though strategic stockpiling of frozen tropical fruit buffers Mexican import volatility. Supply draws from Mexico, Costa Rica, and Ecuador for banana and mango inputs; domestic strawberry sourcing clusters in Central Valley and Florida counties. Single-source vulnerability runs through seventy percent domestic spinach cultivation concentrated in Salinas Valley drought corridors. Distribution feeds through refrigerated third-party logistics networks terminating in supermarket dairy cases and direct-to-consumer frozen last-mile providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States smoothie market sits in post-pandemic wellness cyclical recovery, justified by fitness membership rebounds driving protein smoothie occasion expansion.
For Market Incumbents: Fortify HPP tolling capacity through captive equipment investments or exclusive tolling agreements, defending against emerging DTC brands exploiting clean-label shelf-life advantages. Deepen backward integration into Central Valley organic acreage to secure supply during FDA Food Safety Modernization Act audit intensification.
For New Entrants and Emerging Players: USDA organic certification fast-track through Oregon Department of Agriculture programs unlocks premium positioning in Pacific Northwest green smoothie white space. Target Texas drive-through suburban corridors where Tropical Smoothie Cafe and Smoothie King unit density remains below California benchmarks. Launch gym-adjacent micro-kitchen partnerships with boutique fitness operators to bypass retail slotting fees.
For Investors and Strategic Acquirers: Long-term, this sits as a functional nutrition convergence play because adaptogen and nootropic ingredient blending creates defendable SKU differentiation against commodity fruit competitors. Acquisition target archetype: regional HPP-equipped production facilities with existing cold-chain distribution partnerships. Watch FDA enforcement discretion on added sugar disclosure timelines as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | HPP equipment deployment extends refrigerated shelf life without thermal degradation of enzyme activity. |
| USDA Organic Certification Acquisition | Organic supply chain transparency commands ingredient-grade premiums in coastal metropolitan markets. |
| Direct-to-Consumer Subscription Launch | Weekly replenishment models bypass retail margin extraction and build recurring revenue foundations. |
| Functional Ingredient Convergence | Adaptogen and nootropic blending targets cognitive performance seekers with differentiated positioning. |
| Cold-Chain Logistics Partnership | Refrigerated last-mile networks enable frozen delivery economics in Northeast and West Coast corridors. |
Research Approach
Cross-validation between franchise operations executives and FDA regulatory affairs specialists anchors the qualitative findings on reformulation timelines. Primary interviews with smoothie brand R&D directors, cold-chain logistics providers, supermarket category buyers, and USDA organic certification auditors combined with secondary validation through FDA guidance documents, USDA agricultural statistics, and Nielsen retail audit data. Bottom-up unit economics modeling and top-down category sizing triangulate volume estimates.
Sensitivity analysis on input cost volatility and subscription churn rates shapes the projection framework. Segmentation dimensions span product type, distribution channel, price tier, and customer occasion across the modeling period. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points. Forecast inputs include strawberry price index movements and HPP equipment installation rates.
Decision-makers should treat outputs as directional under stable FDA enforcement timelines and temperate produce growing seasons; material deviation would warrant model refresh. Revision becomes warranted when drought severity in Central Valley growing regions crosses thresholds triggering supply allocation protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Soft Serve Premix Market
Beverages
Cold Pressed Juice Market
Beverages
Caffeine-Based Drinks Market
Beverages
Solid Beverages Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Fusion Beverages Market
Beverages
Sparkling Juice Drinks Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Herb Infused Water Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Ginger Beer Market
Beverages
Packaged Cactus Water Market
Beverages
Asia-Pacific Vinegar Market
Beverages
Sparkling Water Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Fruit Juices and Nectars Market