
 Canada Fruits and Vegetables Market | 2026-2036
Canada Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Fruits and Vegetables Market Outlook
The Canadian Agricultural Partnership's sustainability benchmarks for greenhouse gas reduction is repositioning procurement priorities across the produce supply chain. Mastronardi Produce Ltd leverages its Leamington greenhouse network to sustain year-round tomato and pepper output. Red Sun Farms anchors its vertical integration model through controlled-environment agriculture across southwestern Ontario. Cavendish Farms competes in the processed segment with frozen potato and vegetable capacity rooted in Atlantic Canada.
Canada fruits and vegetables encompass fresh and processed edible plant products sold through retail, food service, and institutional channels, with fresh items requiring cold-chain maintenance between zero and four degrees Celsius to preserve organoleptic quality and safety. The sector serves nutritional, culinary, and industrial processing purposes across domestic consumption and export markets. Fresh vegetables dominate volume throughput through supermarket and wholesale channels, while processed fruits command margin premiums in institutional and remote-region food service. Online retail represents the fastest-growing distribution vector as logistics platforms reduce spoilage rates through predictive inventory routing.
Health Canada enforces the Safe Food for Canadians Regulations requiring preventive control plans and lot traceability, while the Canadian Food Inspection Agency administers grade standards and phytosanitary certification for cross-border movement. The Canada Agricultural Partnership funds greenhouse energy efficiency retrofits, directly shaping capital deployment in controlled-environment production. Provincial organic certification programs in British Columbia and Quebec create tiered market access thresholds that filter supplier participation. Stakeholders must monitor evolving federal plastic packaging regulations alongside provincial extended producer responsibility frameworks to anticipate compliance cost trajectories.
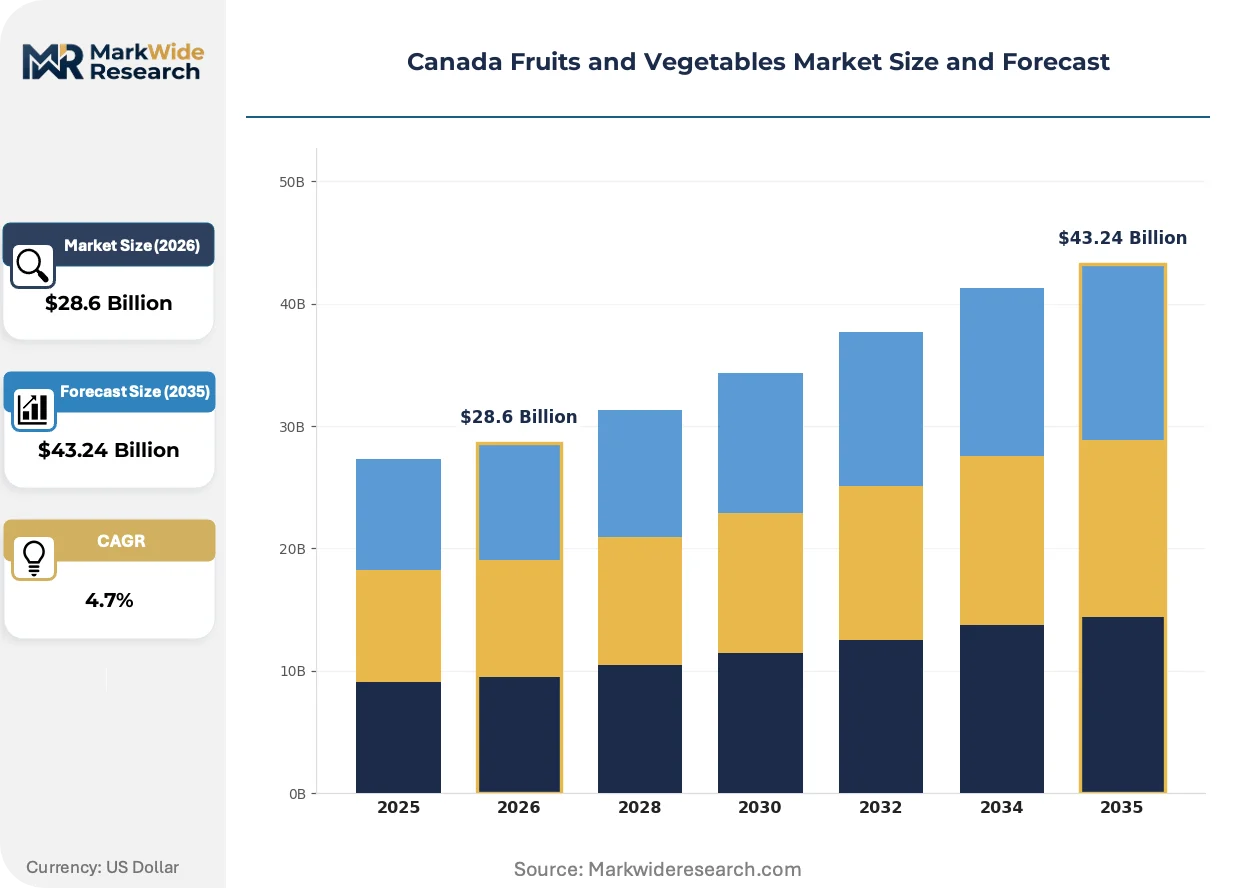
Market Dynamics
Controlled-environment agriculture is concentrating production capacity within Ontario's greenhouse corridor while Health Canada's Safe Food for Canadians Regulations tighten traceability mandates across domestic supply chains.
Growth Catalysts
- Energy Efficiency Retrofits:The Canadian Agricultural Partnership funds greenhouse gas reduction upgrades across southwestern Ontario facilities. Controlled-environment operators deploy these incentives to expand year-round tomato and pepper output.
- Food Service Localization:Institutional buyers and restaurant chains prioritize domestic sourcing contracts. Procurement teams specify Ontario-grown produce to reduce transportation spoilage and meet sustainability procurement targets.
- Cold-Chain Logistics Modernization:Predictive inventory routing platforms now maintain zero-to-four-degree Celsius integrity through last-mile delivery. Supermarket and wholesale channels report reduced waste rates as routing algorithms optimize perishable handling.
Market Restraints
- Seasonal Production Geography:Fresh vegetable volume concentrates in Ontario's Leamington-Kingsville corridor during winter months. Atlantic Canada and Prairie provinces lack comparable greenhouse infrastructure for year-round supply.
- Phytosanitary Certification Friction:The Canadian Food Inspection Agency administers grade standards and cross-border documentation that delay shipments to US food service buyers. Export-oriented processors face inspection bottlenecks at key border crossings.
- Input Cost Volatility:Natural gas and electricity prices for greenhouse heating fluctuate with provincial utility rate structures. Energy-intensive controlled-environment operators cannot pass full cost swings to fixed-price retail contracts.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:Provincial plastic packaging regulations in British Columbia and Quebec create compliance thresholds that filter supplier participation. Early adopters of biodegradable packaging secure preferred retail shelf placement.
- Online Retail Channel Expansion:Direct-to-consumer platforms reduce spoilage through demand-predictive fulfillment. Urban centers in Toronto, Vancouver, and Montreal show highest adoption velocity for subscription produce boxes.
- Organic Certification Tiering:British Columbia and Quebec operate distinct provincial organic programs that command price premiums. Producers holding multiple provincial certifications access broader retail distribution networks.
Industry Challenges
- Preventive Control Plan Documentation:Safe Food for Canadians Regulations mandate lot traceability systems that small-scale growers struggle to implement. Compliance timelines compress as enforcement deadlines approach.
- Integrated Pest Management Expertise:Controlled-environment agriculture requires specialized biological control knowledge that agricultural colleges have not scaled to meet industry demand. Labor shortages in entomology and crop science constrain expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Fruits and Vegetables Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fruits, Fresh Vegetables, Processed Fruits, Processed Vegetables Distribution Channel: Supermarkets, Local Markets, Online Retail, Wholesale Packaging Type: Bags, Boxes, Trays, Bulk Customer Type: Retail Consumers, Food Service, Hospitals, Caterers |
| Companies Covered | Mastronardi Produce Ltd, Red Sun Farms, Cavendish Farms, McCain Foods Limited, GoodLeaf Farms, Oppy, Fresh Direct, Bonduelle Canada, Driscoll's Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Fruits and Vegetables Market Strategic Shifts
Automation and data-driven cultivation systems are reshaping how Canadian producers manage yield consistency, labor allocation, and energy consumption across greenhouse and field operations.
Sensor-networked climate control is modularizing greenhouse management into discrete, software-governed zones. Large-scale operators in Ontario deploy these systems to customize temperature, humidity, and CO2 levels for specific tomato and pepper varietals. The technology is modularizing capital deployment, allowing phased facility expansion without full environmental system replacement.
Health Canada's Safe Food for Canadians Regulations now mandate preventive control plans with documented hazard analysis for all licensed produce facilities. Processors and packers must maintain electronic traceability records accessible within 24 hours of regulatory request. Fresh vegetable distributors serving institutional channels have invested most heavily in ERP system upgrades to meet documentation standards.
Food service procurement teams now specify origin-verified produce in contract tenders. Restaurant chains and institutional buyers substitute direct supplier relationships for traditional wholesale intermediaries. This pattern concentrates most visibly in Ontario and Quebec, where provincial traceability programs provide audit-ready certification that satisfies procurement compliance departments.
Canada Fruits and Vegetables Market Segmentation
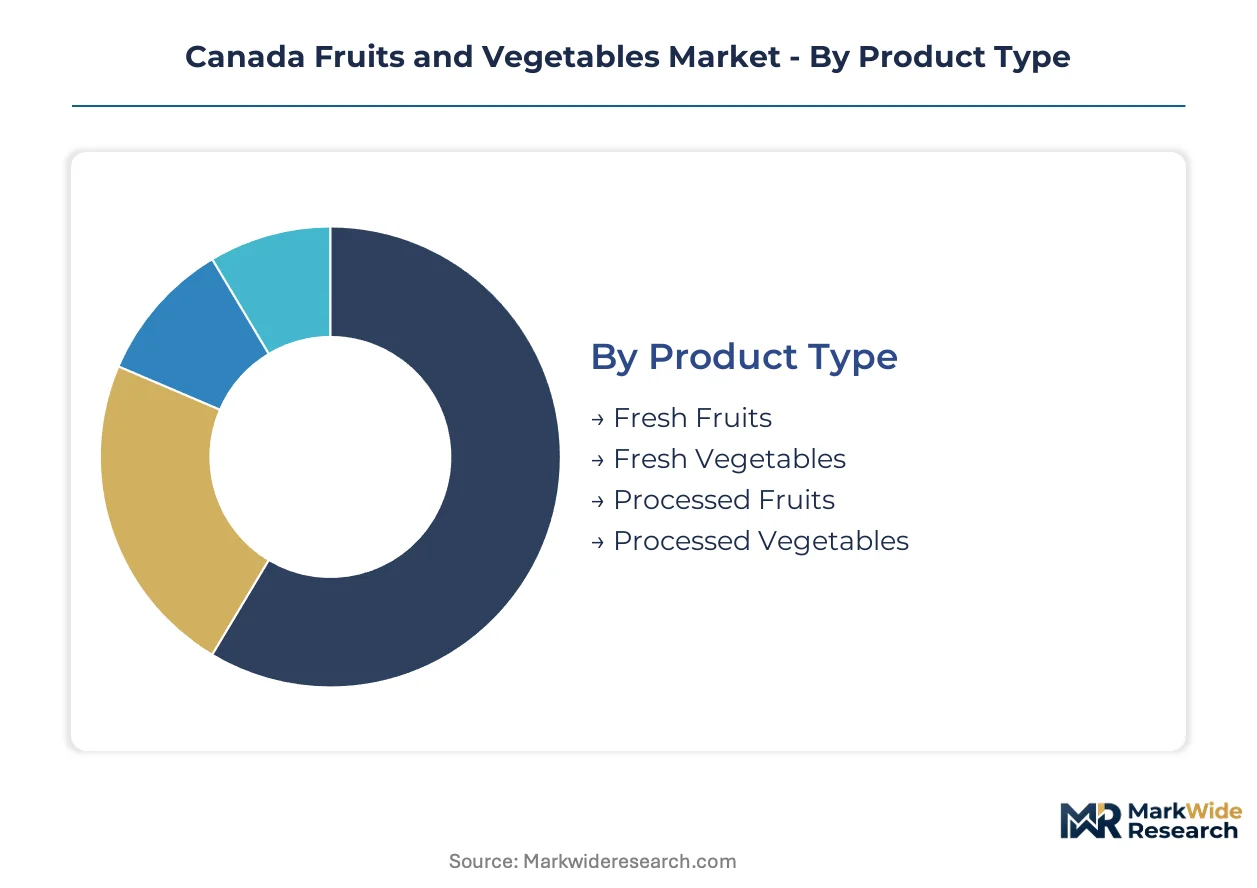
Segmentation reveals how procurement priorities diverge across Canadian produce channels. Food service buyers prioritize traceability-compliant supply chains while retail consumers respond to packaging sustainability mandates. Understanding these splits enables targeted positioning across Ontario's greenhouse corridor and national distribution networks.
Product Type:
Standalone fresh categories dominate volume throughput while processed segments embed into institutional and remote-region supply chains with longer shelf-life requirements.
- Fresh Vegetables:Cold-chain dependent products requiring zero-to-four-degree Celsius maintenance from Ontario's Leamington-Kingsville greenhouses through supermarket and wholesale channels. Demand concentrates in food service localization contracts where institutional buyers specify domestic sourcing to meet sustainability procurement targets.
- Fresh Fruits:Perishable items with compressed handling windows driving investment in predictive inventory routing platforms. British Columbia's Okanagan Valley and Ontario's Niagara Peninsula anchor domestic apple and tender fruit supply for retail consumers prioritizing origin verification.
- Processed Vegetables:Frozen and canned products with extended shelf stability serving remote-region institutions and Atlantic Canada processing capacity.
- Processed Fruits:Shelf-stable and frozen formats commanding margin premiums in hospital and caterer channels where storage flexibility outweighs fresh organoleptic quality.
Volume placements concentrate in Fresh Vegetables; the faster expansion belongs to Processed Fruits as institutional buyers prioritize storage resilience.
Distribution Channel:
Cost-tier stratification separates capital-intensive modern retail from fragmented traditional channels with divergent compliance burdens.
- Supermarkets:Multi-banner chains with centralized procurement specifying preventive control plan documentation under Safe Food for Canadians Regulations. ERP system investments concentrate here to meet electronic traceability mandates.
- Online Retail:Direct-to-consumer platforms with demand-predictive fulfillment reducing spoilage through algorithmic inventory routing. Toronto, Vancouver, and Montreal show highest adoption velocity for subscription produce boxes.
- Wholesale:Intermediary-dependent channel facing displacement as food service buyers build direct supplier relationships.
- Local Markets:Farmer-direct sales with limited lot traceability infrastructure vulnerable to enforcement timeline compression.
Margin capture concentrates in Supermarkets; the steepest expansion trajectory belongs to Online Retail as logistics platforms mature.
Packaging Type:
Application-driven requirements separate retail-facing formats from food service and institutional bulk handling with divergent regulatory exposure.
- Bags:Flexible polyethylene formats facing provincial extended producer responsibility thresholds in British Columbia and Quebec. Early biodegradable material adopters secure preferred retail shelf placement.
- Trays:Rigid PET and pulp-molded structures standard for fresh vegetable presentation in supermarket produce departments.
- Boxes:Corrugated and reusable plastic containers dominating wholesale and food service volume movement.
- Bulk:Unpackaged formats constrained by retail food safety display requirements and institutional procurement specifications.
Procurement volume concentrates in Bags; the fastest share gain belongs to Trays as pulp-molded alternatives displace petroleum-based formats.
Customer Type:
Volume scale separates high-throughput institutional buyers from fragmented retail consumption with inverse sensitivity to traceability documentation.
- Food Service:Restaurant chains and institutional buyers substituting direct supplier relationships for wholesale intermediaries. Origin-verified produce specifications concentrate in Ontario and Quebec where provincial traceability programs provide audit-ready certification.
- Retail Consumers:Supermarket-dependent households with accelerating online platform adoption in major urban centers.
- Hospitals:Healthcare institutions prioritizing processed fruit and vegetable categories for inventory stability and nutritional consistency.
- Caterers:Event-service operators with seasonal demand volatility and compressed procurement windows favoring flexible wholesale relationships.
Revenue concentration sits with Food Service; the most rapid demand scaling belongs to Retail Consumers through subscription platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leamington anchors Canadian produce volume through its greenhouse corridor, where year-round tomato and pepper cultivation supplies domestic food service and retail channels. Provincial regulatory frameworks and federal sustainability incentives concentrate capital deployment across southwestern Ontario.
Ontario
Food service localization contracts and institutional procurement specifications drive demand for traceable domestic produce. Health Canada's Safe Food for Canadians Regulations mandate preventive control plans that large-scale greenhouse operators have implemented through ERP system upgrades. The Leamington-Kingsville corridor hosts the densest concentration of controlled-environment agriculture facilities in North America.
Quebec
Provincial organic certification programs command price premiums in retail and institutional channels. The Canadian Agricultural Partnership funds greenhouse energy efficiency retrofits across Montérégie and Lanaudière production zones. Montreal's food service procurement teams specify origin-verified produce through direct supplier relationships that bypass traditional wholesale intermediaries.
British Columbia
Extended producer responsibility frameworks for plastic packaging create compliance thresholds that filter supplier participation in retail channels. The Okanagan Valley anchors domestic apple and tender fruit supply for origin-conscious consumers. Vancouver's urban demand accelerates adoption of direct-to-consumer subscription produce platforms.
Atlantic Canada
Processed vegetable capacity serves remote-region institutions with frozen potato and vegetable formats. The Canadian Food Inspection Agency administers grade standards that delay cross-border shipments to US food service buyers. Prince Edward Island's processing facilities compete on storage resilience rather than fresh organoleptic quality.
Alberta
Natural gas price volatility constrains greenhouse heating economics for controlled-environment operators. Provincial utility rate structures prevent full cost pass-through to fixed-price retail contracts. Calgary and Edmonton's food service buyers rely on Ontario greenhouse supply during winter production gaps.
Canada Fruits and Vegetables Market Competitive Environment
The competitive structure tilts toward vertically integrated greenhouse operators with year-round production capacity. Large-scale controlled-environment facilities dominate fresh vegetable throughput, while processed segment players compete on frozen and shelf-stable formats. Two strategic archetypes prevail: integrated greenhouse networks with direct retail relationships, and diversified processors with institutional contract concentration. Capacity expansion and direct procurement partnerships represent the dominant competitive moves as food service buyers bypass wholesale intermediaries.
Among Ontario-based greenhouse operators, Mastronardi Produce Ltd and Red Sun Farms exemplify the integrated production archetype through their Leamington corridor facilities. Cavendish Farms anchors the processed segment position from its Atlantic Canada base. These three companies represent the structural split between fresh controlled-environment supply and frozen vegetable processing capacity.
| Leading Market Players |
|---|
| Mastronardi Produce Ltd |
| Red Sun Farms |
| Cavendish Farms |
| McCain Foods Limited |
| GoodLeaf Farms |
| Oppy |
| Fresh Direct |
| Bonduelle Canada |
| Driscoll's Canada |
| Others |
Value Chain & Pricing Dynamics
Backward integration into controlled-environment production anchors pricing power for Ontario greenhouse operators serving food service and retail channels. Mastronardi Produce Ltd and Red Sun Farms leverage captive supply from their Leamington corridor facilities to command origin-verified premiums under Health Canada's Safe Food for Canadians Regulations.
Pricing Analysis
Yield-based pricing anchors contracts between greenhouse operators and institutional buyers, with per-kilogram rates tied to defect-free throughput and season-adjusted volume commitments. Certification premiums stratify across provincial organic programs in British Columbia and Quebec, separating price tiers by audit rigor rather than commodity grade alone. Cost compression in processed vegetable segments runs through natural gas price volatility that Atlantic Canada processors cannot fully pass to fixed-price retail contracts. Food service buyers show lowest price sensitivity, prioritizing lot traceability and origin verification over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Toronto, Montreal, and Vancouver anchor hub-and-spoke patterns that consolidate Ontario greenhouse output for national retail deployment. Supply concentrates in Canada for fresh greenhouse vegetables, with secondary sourcing from Mexico and the United States for tender fruit categories outside domestic growing seasons. Natural gas, biological control agents, and specialized greenhouse glazing constitute critical input dependencies with concentrated supplier bases. Single-source vulnerability in entomology-derived pest management solutions threatens expansion timelines for controlled-environment operators. Distribution runs through temperature-controlled trucking networks with zero-to-four-degree Celsius integrity mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's Safe Food for Canadians Regulations erect a compliance moat that rewards early ERP system adopters while filtering marginal growers from institutional procurement channels.
For Market Incumbents: Deepen direct supplier relationships with food service chains to displace wholesale intermediaries before competitors replicate origin-verified certification. Invest in modular sensor-networked climate zones across Leamington corridor expansions to sustain yield premiums. Counter input cost volatility through long-term natural gas hedging structures anchored in provincial utility rate frameworks. For New Entrants and Emerging Players: The price-point gap between premium certified-organic and economy conventional tiers opens white-space opportunity in mid-market subscription produce boxes for Toronto and Vancouver urban households. Target biodegradable packaging compliance ahead of British Columbia and Quebec extended producer responsibility enforcement deadlines. Enter through direct-to-consumer platforms with demand-predictive fulfillment rather than competing for supermarket shelf placement. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified agribusiness conglomerates seeking controlled-environment production capacity. Long-term viability favors operators with multi-provincial organic certification and proven ERP traceability infrastructure. Watch for enforcement timeline compression on Safe Food for Canadians Regulations as the inflection signal separating compliant assets from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Traceability System Deployment | Health Canada's 24-hour documentation mandate requires electronic lot tracking for licensed facilities. |
| Greenhouse Energy Efficiency Retrofit | Canadian Agricultural Partnership funding accelerates payback periods for gas-reduction upgrades. |
| Direct-to-Consumer Platform Launch | Algorithmic inventory routing in Toronto and Vancouver reduces spoilage rates below wholesale benchmarks. |
| Biodegradable Packaging Transition | British Columbia and Quebec extended producer responsibility frameworks filter non-compliant suppliers from retail. |
| Provincial Organic Certification Stacking | Multi-jurisdiction organic credentials unlock broader distribution networks with tiered price premiums. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with greenhouse operations managers, food service procurement directors, supermarket category buyers, and Canadian Food Inspection Agency compliance officers validated volume assumptions. Health Canada Safe Food for Canadians Regulations documentation, provincial organic program standards, and Canadian Agricultural Partnership disbursement records supplied segmentation parameters. Bottom-up facility capacity modeling and top-down consumption estimates were triangulated against cold-chain logistics provider throughput disclosures.
Granularity-level modeling operated at the provincial production zone, distribution channel, and customer-type intersection. Segmentation dimensions included product freshness category, packaging format, and certification tier across the projection horizon. CAGRs were derived from trend extrapolation of historical volume flows and policy-driven capacity expansion schedules. Energy price sensitivity inputs and greenhouse gas reduction incentive trajectories shaped scenario-weighted outputs.
Inputs from regulatory agencies and industry associations were available through the study window; gaps in real-time greenhouse energy cost data introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions on enforcement timing and incentive continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Dates Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Europe Olive Market
Fruits and Vegetables
Fresh Apricots Market