
 Ginger Beer Market | 2026-2036
Ginger Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Ginger Beer Market Intelligence
Direct-to-consumer subscription box models are repositioning ginger beer from a simple retail purchase to a curated home-bar experience. Fever-Tree Drinks Plc leverages its premium brand identity to dominate the mixer category in upscale retail and on-premise channels. Meanwhile, Reed’s Inc. differentiates through its use of fresh ginger and a craft-brewed positioning. Fentimans Ltd sustains its market presence with botanically brewed beverages and heritage branding.
Ginger beer is a non-alcoholic or low-alcohol carbonated beverage brewed and fermented from ginger root, sugar, and yeast. Its characteristic spicy flavor, derived from gingerols in the ginger, makes it a popular standalone drink and a key ingredient in cocktails. The non-alcoholic product type commands the largest market share, but craft and alcoholic variants are gaining traction. The food service distribution channel represents a high-margin segment, driven by cocktail mixing applications.
Food safety and labeling regulations from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) govern ingredient transparency and health claims. In markets like India, standards set by the FSSAI dictate permissible additives and sugar content, influencing product formulation for market access. Navigating the diverse international standards for sugar content and natural flavorings is a critical decision point for brands seeking to expand their geographic footprint.
Market Dynamics
The convergence of consumer demand for clean-label products and the premiumization of cocktail culture in the food service channel is the central force shaping the ginger beer market, influencing everything from ingredient sourcing to brand positioning.
Growth Catalysts
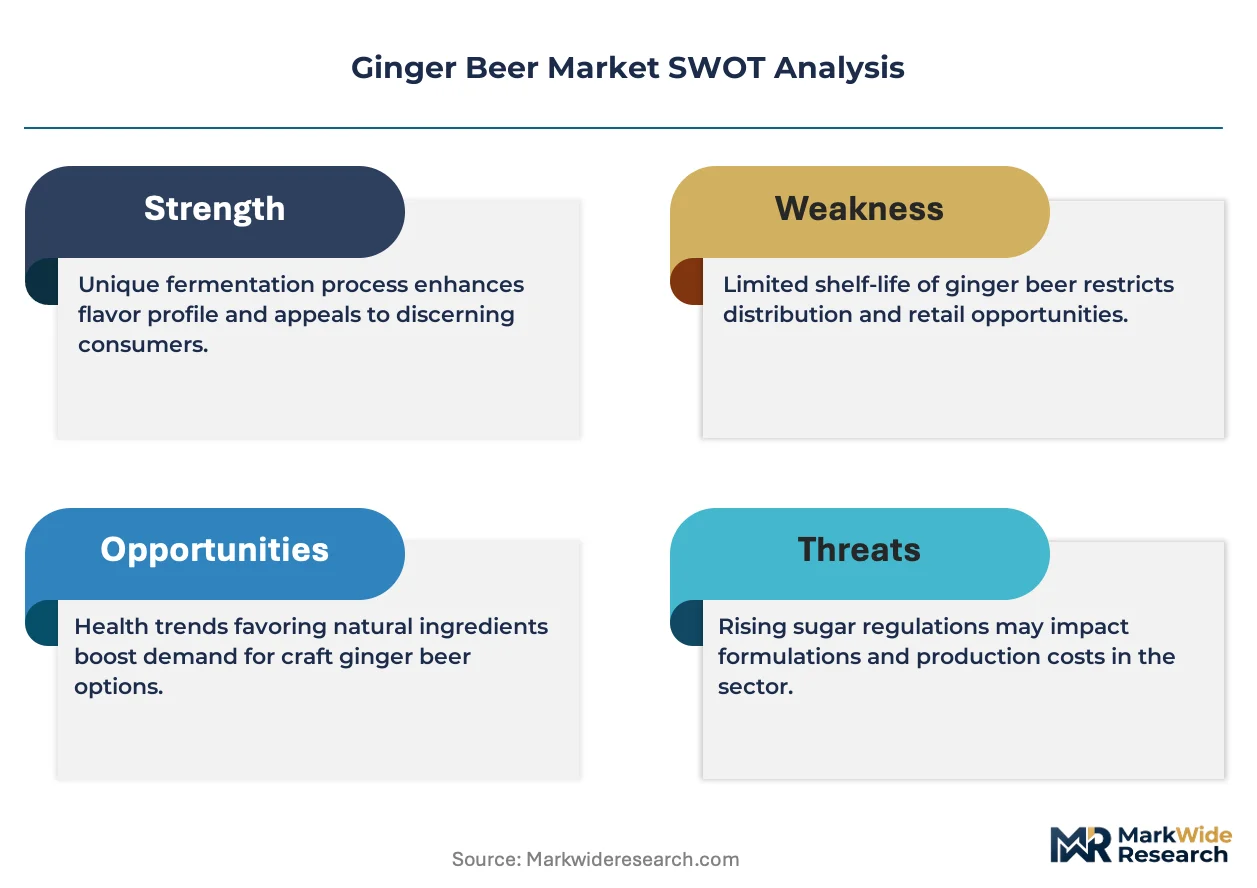
- Cocktail Culture Expansion:The rising popularity of ginger-based cocktails like the Moscow Mule in bars and restaurants, particularly in metropolitan areas of the United States and the United Kingdom, drives high-margin sales through the food service channel.
- Health and Wellness Trends:A consumer pivot towards beverages perceived as healthier, featuring natural ingredients and lower sugar content, benefits ginger beer's positioning as a natural, non-alcoholic alternative to traditional soft drinks.
- FSSAI Standards in India:Regulations from the Food Safety and Standards Authority of India (FSSAI) governing permissible additives and sugar levels are creating a structured market for compliant, quality-assured ginger beer products, encouraging new brand entry.
Market Restraints
- Ginger Price Volatility:The market is exposed to agricultural risks and price fluctuations of fresh ginger root, a key raw material whose supply can be affected by weather, crop diseases, and geopolitical issues in producing countries.
- Substitution from Craft Beverages:Ginger beer faces competition from a growing array of other craft sodas, kombuchas, and flavored sparkling waters that also appeal to consumers seeking premium, non-alcoholic drink options.
- Regulatory Compliance Complexity:Brands face challenges navigating divergent international standards for sugar content, natural flavorings, and labeling, such as those set by the U.S. FDA and the European Food Safety Authority (EFSA).
Strategic Opportunities
- Geographic Market Penetration:There is significant opportunity for expansion beyond the core markets of the US and UK into continental Europe and Asia-Pacific, where cocktail culture and demand for premium non-alcoholic drinks are emerging.
- Direct-to-Consumer Channels:Developing subscription box models and e-commerce platforms allows brands to bypass traditional retail and build direct relationships with consumers, offering a curated home-bar experience.
- Product Line Extensions:Innovation in alcoholic and functional variants, such as hard ginger beers or versions fortified with probiotics and other wellness ingredients, can capture new consumer segments and usage occasions.
Industry Challenges
- Ingredient Sourcing Consistency:Maintaining a consistent flavor profile and spice level, which depends on the gingerol content of ginger root, presents a significant quality control challenge across different harvest seasons and suppliers.
- Brand Differentiation in a Crowded Field:As the market grows, new entrants face the challenge of establishing a unique brand identity and securing shelf space in competitive retail and on-premise environments.
- Complex Distribution Logistics:Gaining access to and managing relationships with a fragmented network of food service distributors and major retail chains requires significant operational resources and investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ginger Beer Market |
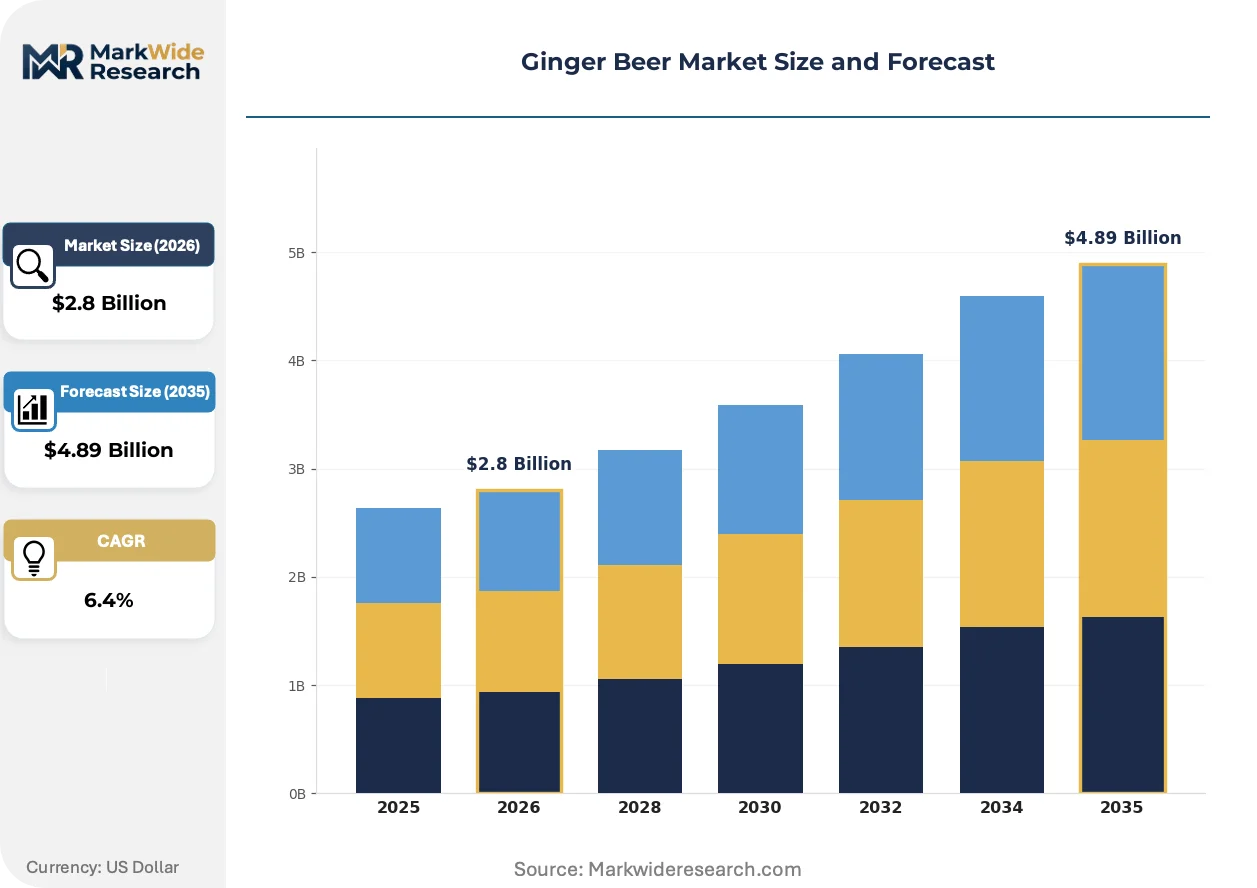
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Craft, Alcoholic, Non-Alcoholic Flavor Profile: Spicy, Sweet, Citrus, Herbal Packaging Type: Bottle, Can, Keg, Draft Distribution Channel: Retail, Online, Food Service, Wholesalers |
| Companies Covered | Fentimans Ltd, Barritt’s Beverages International Ltd, Fever-Tree Drinks Plc, Maine Root, Q Mixers, Bundaberg Brewed Drinks Pty Ltd, Gosling Brothers Limited, Ginger People, Reed’s Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ginger Beer Market Strategic Shifts & Innovations
The market's evolution is defined by a fusion of artisanal production values with mainstream consumer health consciousness. This dynamic is pushing innovation in both product formulation and the channels used to reach a more discerning customer base.
Botanical brewing, a traditional fermentation process, is being refined with modern quality controls to create more complex and consistent flavor profiles. Premium and craft-focused brands are widely adopting these methods to justify a higher price point in upscale retail and on-premise channels. This focus on artisanal production is absorbing the market share of simpler, artificially flavored ginger ales, reframing the category around authenticity.
European Food Safety Authority (EFSA) regulations on health claims and the definition of "natural" ingredients are becoming more stringent. This compels manufacturers targeting the EU to provide greater transparency in labeling and scientific validation for any wellness-related marketing. The clean-label, non-alcoholic segment is most affected, prompting reformulations to ensure full compliance and maintain market access.
A significant shift in consumer behavior involves the embrace of direct-to-consumer (D2C) subscription services for curated beverage selections. This model disintermediates traditional retail, enabling craft brands to cultivate a loyal following by delivering a specialized home-bar experience directly to enthusiasts. The trend is most advanced in urban centers throughout the United States and the United Kingdom, where e-commerce penetration and cocktail culture are deeply intertwined.
Ginger Beer Market Segmentation
Understanding the distinct segments within the ginger beer market is crucial for brands seeking to optimize product development and market penetration strategies. This granular analysis allows companies to tailor offerings precisely to consumer preferences and distribution channel requirements, maximizing commercial impact.
Product Type:
The product type segmentation highlights how consumer preferences are driving an upgrade cycle from basic formulations to more sophisticated craft and alcoholic variants.
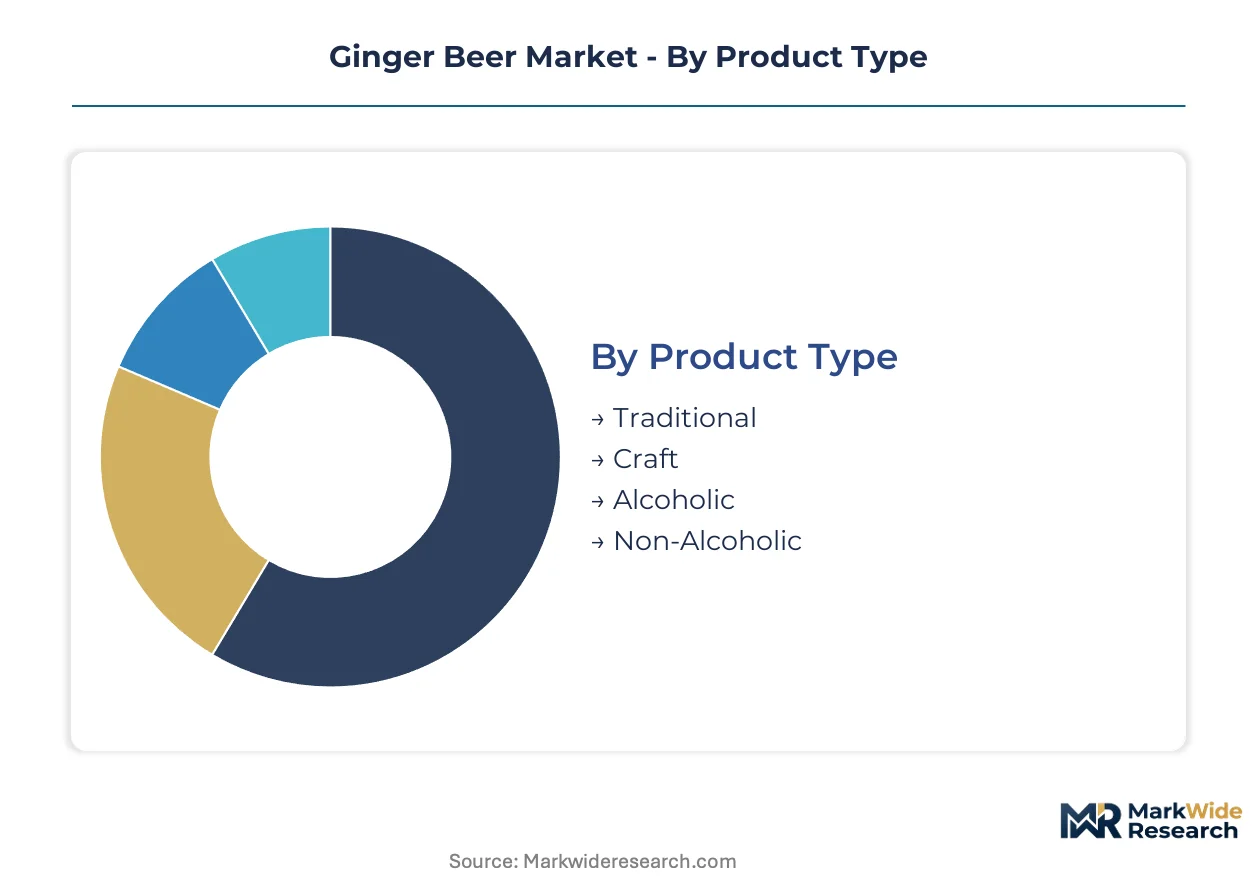
- Non-Alcoholic:This segment comprises traditional carbonated ginger beverages, often brewed and fermented, containing no alcohol. It commands the largest market share, serving as a popular standalone drink and a foundational mixer in global metropolitan areas like New York and London.
- Craft:Craft ginger beer emphasizes artisanal production methods, premium ingredients, and distinct flavor profiles, often positioning itself as a higher-quality alternative to mass-produced options. Demand for craft variants is strong in specialty food stores and upscale restaurants across the United States and the United Kingdom.
- Traditional:Traditional ginger beer refers to classic formulations, often characterized by a strong ginger kick and a balanced sweetness. These products appeal to consumers seeking authentic and familiar taste experiences.
- Alcoholic:This segment includes hard ginger beers, which contain an alcoholic content typically ranging from 4% to 8% ABV, appealing to consumers seeking alcoholic beverage alternatives.
Non-Alcoholic ginger beer sits at the top of the volume ranking, with Craft variants climbing the fastest.
Flavor Profile:
Flavor profile segmentation reflects diverse application needs, ranging from standalone consumption to complex cocktail mixing.
- Spicy:Characterized by a pronounced ginger kick from higher concentrations of gingerols, this profile is highly sought after for authentic ginger beer experiences and robust cocktail mixing. The spicy profile is critical for classic cocktails like the Moscow Mule, driving its popularity in bars and restaurants.
- Citrus:Citrus-infused ginger beers incorporate notes of lemon, lime, or orange, offering a brighter, more refreshing taste that broadens consumer appeal. This flavor profile is particularly popular in warmer climates and for lighter, fruit-forward mixed drinks.
- Sweet:Sweet ginger beer formulations typically contain higher sugar content, appealing to consumers who prefer a less intense ginger flavor. This profile often targets a broader, more mainstream consumer base.
- Herbal:Herbal variants integrate botanicals such as mint, rosemary, or elderflower, providing complex and aromatic flavor dimensions.
Spicy profiles contribute significantly to high-margin cocktail applications, while Sweet flavors maintain broad consumer appeal.
Packaging Type:
Packaging type differentiation often aligns with various cost tiers, influencing both consumer perception and distribution logistics.
- Bottle:Glass bottles are widely used for premium and craft ginger beer brands, conveying a sense of quality and traditional craftsmanship. This packaging type dominates in on-premise venues and specialty retail, particularly in European markets.
- Can:Aluminum cans offer convenience, portability, and protection from light, making them popular for grab-and-go consumption and outdoor events. The can format is gaining traction in both retail and online channels, especially in the US.
- Keg:Kegs are primarily utilized in the food service sector, allowing for draft ginger beer service in bars, pubs, and restaurants. This format supports high-volume dispensing and reduces packaging waste.
- Draft:Draft systems provide freshly poured ginger beer, enhancing the consumer experience in hospitality settings.
Bottles remain prevalent for premium offerings, while Cans are increasingly preferred for their convenience and portability.
Distribution Channel:
Distribution channel analysis reveals how ginger beer reaches consumers, with varying degrees of volume and market reach.
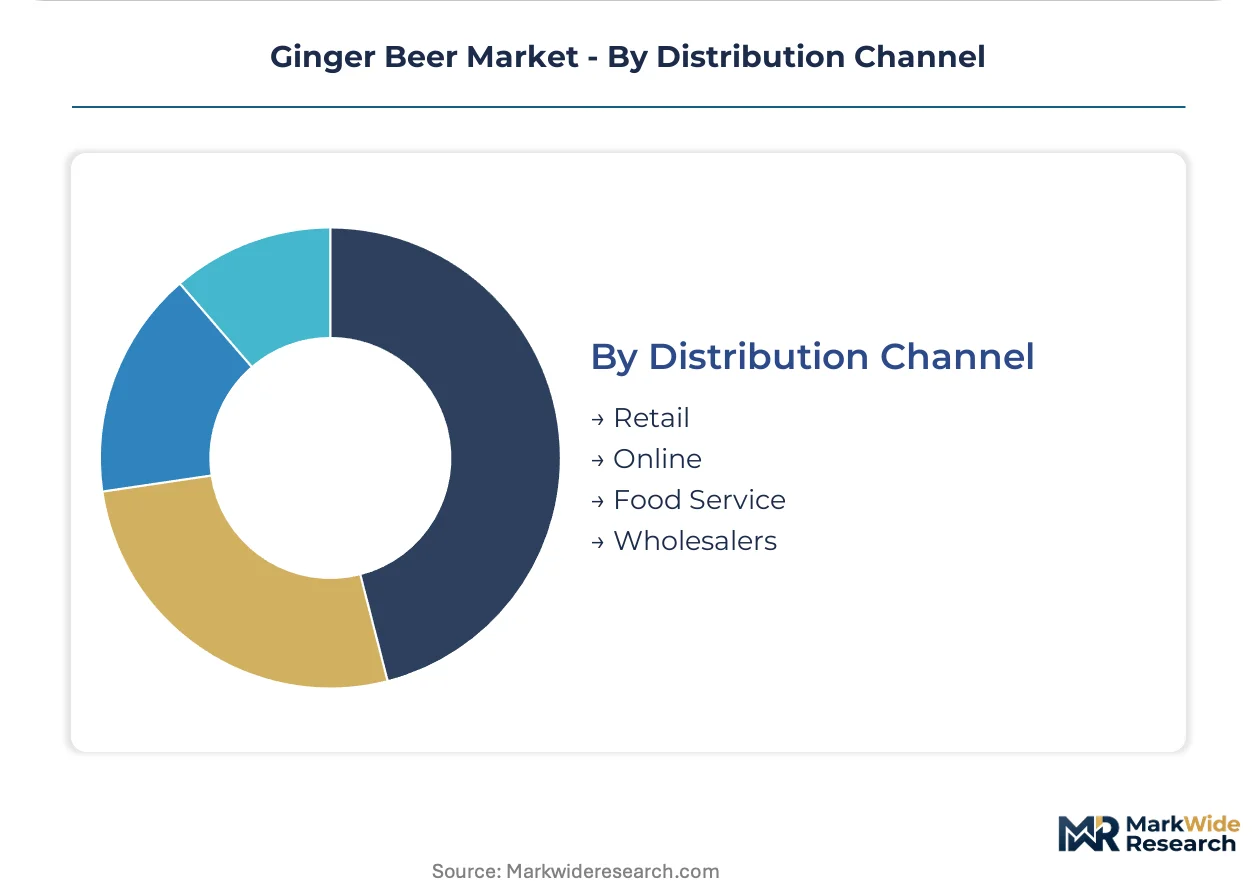
- Food Service:This channel includes restaurants, bars, cafes, and hotels, where ginger beer is primarily sold as a standalone beverage or a key cocktail ingredient. The food service segment represents a high-margin opportunity, particularly in urban centers of the United Kingdom and the United States.
- Retail:The retail channel encompasses supermarkets, convenience stores, and specialty food shops, providing broad consumer access to ginger beer products. This channel is crucial for brand visibility and volume sales across global markets.
- Online:E-commerce platforms and direct-to-consumer subscription services facilitate direct sales to consumers, offering convenience and access to a wider range of craft and niche brands. Online sales are expanding rapidly in regions with high internet penetration.
- Wholesalers:Wholesalers act as intermediaries, distributing ginger beer products from manufacturers to various retail and food service outlets.
Food Service represents a strategic focus for premium brands, while Retail ensures widespread consumer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States leads in cocktail culture-driven ginger beer consumption, the United Kingdom exhibits a strong preference for premium, on-premise mixer applications. Both markets showcase significant demand for natural and clean-label formulations. This regional diversity underscores varied consumer preferences and regulatory landscapes across key geographies.
United States
The United States market sees high demand for ginger beer, driven by the enduring popularity of cocktails like the Moscow Mule. U.S. FDA regulations ensure ingredient transparency, impacting product labeling and formulation. Major metropolitan areas such as New York and Los Angeles are centers for craft ginger beer consumption.
United Kingdom
United Kingdom consumers increasingly seek premium ginger beer for both upscale retail and home-bar experiences. Post-Brexit, EFSA standards continue to influence product formulation, particularly for natural claims. London's dynamic bar scene remains a significant driver for high-margin, on-premise sales.
India
India's market for ginger beer is structured by a growing cocktail culture and the entry of new compliant brands. FSSAI standards dictate permissible additives and sugar content, influencing local product development. Urban centers like Mumbai and Delhi are witnessing a rise in demand for quality-assured ginger beer products.
Germany
German consumers are increasingly drawn to ginger beer as a premium non-alcoholic option within the craft beverage segment. The EU Green Deal pushes manufacturers towards sustainable sourcing and transparent labeling practices. Berlin's innovative food and beverage scene actively integrates botanically brewed ginger beer into its offerings.
Australia
Australian demand for ginger beer is boosted by its suitability for warmer climates and outdoor social events. Food Standards Australia New Zealand (FSANZ) governs ingredient and labeling requirements, ensuring product safety. Sydney and Melbourne's hospitality sectors are adopting craft ginger beer for a variety of mixed drinks.
Ginger Beer Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a market structure that exhibits both consolidation among premium players and fragmentation within regional craft offerings. The competitive environment features large beverage conglomerates, niche craft brewers, and emerging direct-to-consumer brands. These archetypes often differentiate through ingredient sourcing, unique flavor profiles, or targeted distribution channels. Companies pursue strategic partnerships to expand their market reach and engage in product line extensions to capture new consumer segments.
On the premium-tier vector, Fever-Tree Drinks Plc exemplifies a brand leveraging its strong identity to dominate the mixer category in upscale retail and on-premise channels. Fentimans Ltd, a UK-based company, sustains its market presence through botanically brewed beverages and heritage branding. Reed’s Inc., a US-based entity, occupies a position focused on differentiating through its use of fresh ginger and a craft-brewed identity, appealing to consumers seeking authentic taste experiences. These entities collectively anchor the market's premium and craft segments.
| Leading Market Players |
|---|
| Fentimans Ltd |
| Barritt’s Beverages International Ltd |
| Fever-Tree Drinks Plc |
| Maine Root |
| Q Mixers |
| Bundaberg Brewed Drinks Pty Ltd |
| Gosling Brothers Limited |
| Ginger People |
| Reed’s Inc. |
| Others |
Cost & Logistics Intelligence
Premium cocktail bars and upscale restaurants, concentrated in metropolitan areas, drive a value-based pricing model for ginger beer. This buyer concentration allows premium brands to command higher prices, influencing ingredient sourcing decisions.
Pricing Analysis
Capacity additions in ginger-producing regions are reshaping price floors for raw materials, influencing final product costs. The market employs a tiered pricing structure, differentiating between premium and craft offerings. Brand reputation and the use of fresh, natural ingredients drive significant price differentiation. Pricing pressure stems from the volatility of fresh ginger prices, while food service channels exhibit lower price sensitivity compared to mainstream retail consumers.
Supply Chain Analysis
Dual-sourcing requirements for key ingredients are becoming more common among large ginger beer brands to mitigate risk. The supply of fresh ginger root primarily draws from India, China, and Nigeria, with other key raw material dependencies including sugar and specialized yeast strains. A structural risk is the commodity price volatility of ginger, directly impacting production costs and brand margins. Distribution runs through a fragmented network of food service distributors and major retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market acts as a regulatory compounder, driven by standards like those from the FSSAI in India, which encourage quality-assured products. These regulations reinforce consumer trust and demand for transparently formulated ginger beer.
For Market Incumbents: Lock in high-margin food service distribution channels through exclusive partnerships and brand visibility initiatives. Deepen product line extensions into alcoholic and functional ginger beer variants to counter craft beverage substitution. Invest in certification for natural ingredients and transparent labeling to meet evolving consumer health and wellness trends. Maintaining consistent flavor profiles through R&D is also critical for brand loyalty.
For New Entrants and Emerging Players: Direct-to-consumer subscription models offer a technology-first wedge to establish brand loyalty and bypass traditional retail gatekeepers. Target expansion into underpenetrated urban centers across continental Europe and Asia-Pacific, where cocktail culture is emerging. Focus on developing functional variants, such as probiotic-fortified ginger beer, to capture health-conscious segments. A go-to-market angle emphasizing a curated home-bar experience resonates with discerning consumers.
For Investors and Strategic Acquirers: Large beverage conglomerates are the most active acquirers in this space, seeking to diversify premium portfolios. The market shows long-term viability over the next 5-10 years, particularly in the premium mixer category. Acquisition targets should include niche craft brewers with strong regional distribution or unique botanical formulations. The signal to watch is regulatory harmonization for clean-label claims across major international markets, indicating clearer expansion pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Direct-to-Consumer Channels | This initiative builds direct relationships with consumers and offers a curated home-bar experience. |
| Develop Alcoholic Ginger Beer Variants | Capturing new consumer segments seeking alcoholic beverage alternatives drives market diversification. |
| Invest in Sustainable Ginger Sourcing | Meeting EU Green Deal consumer expectations for transparent and ethically sourced ingredients enhances brand appeal. |
| Target Asia-Pacific Market Entry | Emerging cocktail culture and demand for premium non-alcoholic drinks provide significant growth opportunities. |
| Enhance Botanical Brewing R&D | Refining traditional fermentation processes creates more complex and consistent flavor profiles for discerning palates. |
Research Approach
Bottom-up cocktail mixing applications modeling reconciled against top-down ginger root production tracking forms the analytical core of this study. The approach combines primary interviews with brand managers, food service buyers, and ingredient suppliers, validated by secondary research. Secondary sources include U.S. FDA, EFSA, and FSSAI regulatory documents, alongside trade association reports and company annual filings. This triangulation ensures robust data integrity and comprehensive market understanding.
Historical trendline analysis of consumption patterns and production volumes underpins the forecast framework across the analysis window. Segmentation dimensions modeled include product type, flavor profile, packaging type, distribution channel, and regional adoption patterns. Compound annual growth rates were derived from historical growth rates and future market drivers. Key industry-specific forecast inputs include consumer preferences for clean-label products and the expansion of global cocktail culture.
The model holds under stable ginger supply and consistent regulatory enforcement; deviation in geopolitical issues or agricultural disruptions would shift the outlook. Forecasts reflect assumptions regarding consumer preferences and market dynamics. Deviation in these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Beverage Dispenser Market
Beverages
Oat Based Beverages Market
Beverages
Fruit Water Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
United States Smoothie Market
Beverages
Foaming Creamer Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Beverages Market
Beverages
Fruit Vinegar Market
Beverages
Global Bottled Water Market
Beverages
Hydration Infusers Market
Beverages
Chocolate Malt Drink Market
Beverages
Global Beverage Emulsion Market
Beverages
Middle East Energy Drinks Market
Beverages
Sparkling Water Market
Beverages
US and Canada Tonic Water Market