
 Solid Beverages Market | 2026-2036
Solid Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Beverages Market Analysis
A capital-intensity divergence between automated freeze-drying infrastructure and conventional spray-drying operations is rotating competitive advantage toward players with proprietary extraction technologies. Nestlé leverages its integrated supply chain from bean sourcing to retail shelf placement. JDE Peet's anchors European market presence through heritage brand portfolios and licensed café systems. Starbucks competes via direct-to-consumer subscription channels and licensed product extensions into grocery retail.
Solid beverages encompass dehydrated or concentrated drink formulations—typically achieving moisture content below five percent through spray-drying, freeze-drying, or extrusion—that reconstitute with water to deliver coffee, tea, cocoa, or flavored refreshment. Functional parameters include solubility rates, particle size distribution, and shelf stability measured in months under ambient storage. Instant Coffee dominates value contribution due to established extraction patents and premium single-origin positioning, while Powdered Drinks capture volume through tropical flavor variants targeting price-sensitive demographics. Single-Serve Pouches concentrate margin pools through portion-controlled convenience and reduced per-use waste.
FDA GRAS determinations govern novel ingredient introductions in the US, while the EU Green Deal's packaging directives mandate recyclability thresholds that reshape material selection across European supply chains. China's SAMR enforces GB standards for food additive thresholds and labeling accuracy, affecting import eligibility for multinational brands. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between reformulating for compliance or regionalizing production footprints.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing material transitions across European supply chains, compressing margins for legacy plastic-dependent producers while advantaging compostable-format specialists.
Growth Catalysts
- Outdoor Recreation Demand:Camping and adventure tourism operators in the US and Germany are adopting lightweight, shelf-stable beverage formats for remote logistics.
- REACH Compliance Incentives:European manufacturers reformulating toward plant-based binders gain preferential shelf placement through retailer sustainability scorecards.
- Freeze-Drying Patent Expiry:Open-source process knowledge is democratizing premium texture replication previously locked behind proprietary extraction systems.
Market Restraints
- Arabica Price Volatility:Brazilian frost cycles and Colombian labor disruptions transmit directly into instant coffee input cost instability.
- Single-Origin Supply Concentration:Ethiopian and Vietnamese bean sourcing corridors face climate-induced yield compression and export quota uncertainty.
- Solubility Floor:Aggressive particle size reduction below 50 microns degrades flavor retention, capping quality improvements for economy-tier spray-dried products.
Strategic Opportunities
- India Convenience Retail:Modern trade expansion in Mumbai and Bangalore creates first-mover positioning for sachet-format functional beverages targeting transit commuters.
- Dual Carbon Alignment:China's MEE carbon intensity benchmarks reward low-energy freeze-drying retrofits with tax credit eligibility and state procurement preference.
- Direct-to-Institutional Channels:Airline catering and corporate pantry services are bypassing traditional wholesale tiers through vertically integrated beverage programs.
Industry Challenges
- Flavor Chemist Scarcity:Formulation expertise for heat-stable natural extracts concentrates in Swiss and Japanese research clusters, inflating recruitment costs.
- Compostable Certification Lag:Industrial compostability validation under ASTM D6400 and EN 13432 extends commercialization timelines by 14-18 months.
- Legacy Spray-Drying Stranding:Capital-intensive conventional assets face accelerated obsolescence as energy efficiency standards tighten across EU member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Beverages Market |
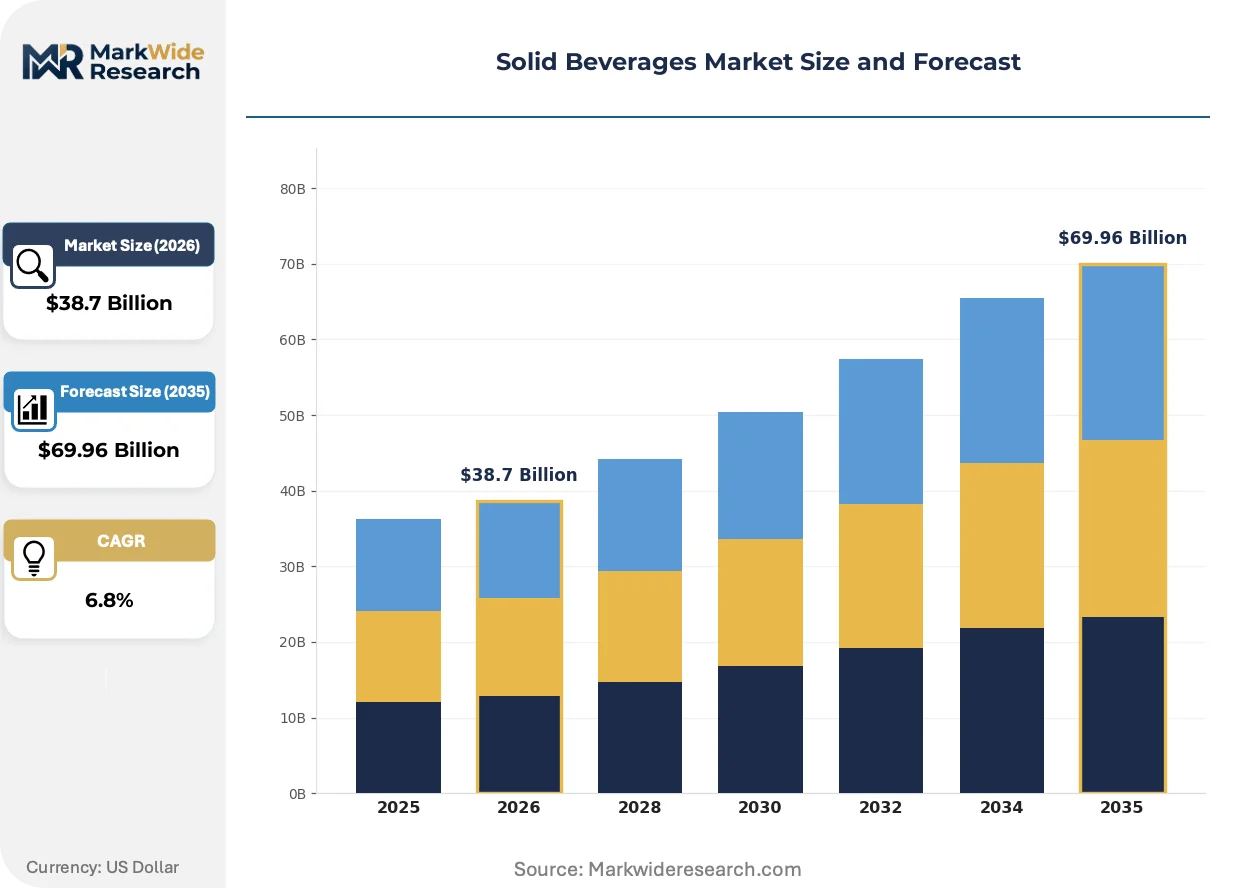
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Coffee, Tea Tablets, Powdered Drinks, Nutritional Bars Material: Plant-Based, Dairy, Sugar Substitutes, Artificial Flavors Packaging Type: Bags, Cans, Boxes, Single-Serve Pouches Application: On-the-Go Consumption, Home Brewing, Café Preparation, Medical Use |
| Companies Covered | Keurig Dr Pepper, JDE Peet’s, Nestlé, Suntory Beverage & Food, Danone, The Coca-Cola Company, Starbucks, Monster Beverage, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Beverages Market Emerging Trajectories
Dehydration technology convergence with precision fermentation is unlocking novel ingredient matrices, while regulatory packaging mandates and shifting procurement authority are restructuring competitive entry points.
Microencapsulation of volatile aromatic compounds is miniaturizing flavor protection architectures, enabling cold-water solubility without heat-activated release mechanisms. Specialty coffee roasters in Melbourne and Copenhagen are adopting these formats for private-label instant lines. The technology is miniaturizing the sensory gap between reconstituted and fresh-brewed products, compressing premiumization timelines for mid-tier brands.
The EU Green Deal's Single-Use Plastics Directive is mandating recyclability thresholds above 70% for beverage packaging placed on European markets. This forces multilaterial film substitution with paper-based barrier laminates or industrially compostable biopolymers. Powdered drink manufacturers serving German and French retail channels are accelerating pilot lines for home-compostable sachet formats to maintain listing eligibility.
Authority over beverage procurement is migrating from centralized food-service contracts to individual workplace managers and hospitality operators. Subscription-based replenishment platforms are displacing traditional broadline distributor relationships in US and UK office segments. This shift concentrates supplier selection power with facility managers who prioritize SKU consolidation and waste reduction metrics over legacy brand recognition.
Solid Beverages Market Segmentation
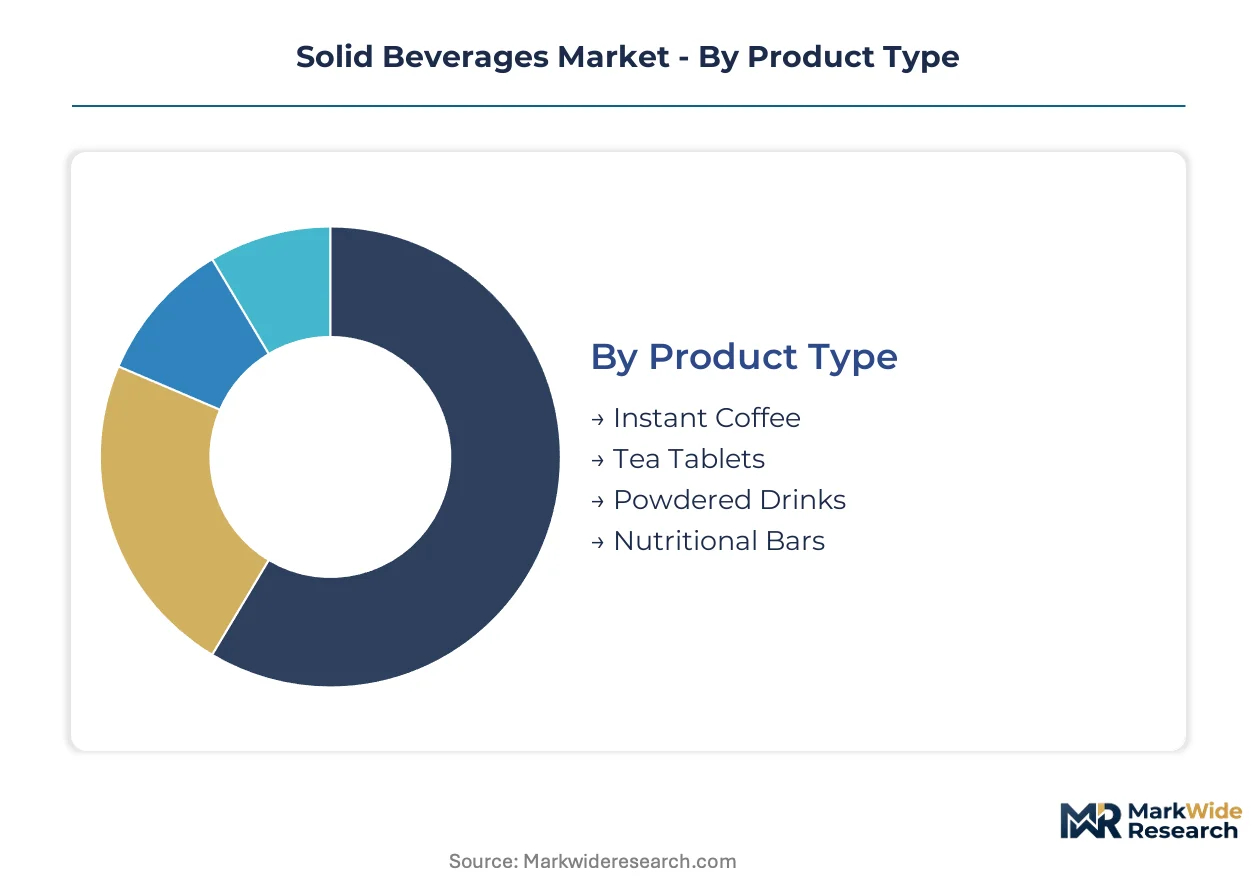
Solid beverages fragment across formulation chemistry, material sourcing, and consumption occasion. Each dimension carries distinct regulatory exposure and margin architecture that shapes competitive positioning.
Product Type:
FDA GRAS determinations in the US and China's GB standards create divergent compliance burdens across formulation categories.
- Instant Coffee:Dehydrated coffee extracts achieve moisture content below five percent through spray-drying or freeze-drying processes. Patent-protected extraction systems in Switzerland and Japan concentrate formulation expertise, while Brazilian frost cycles transmit directly into input cost instability for commodity-grade products.
- Powdered Drinks:Tropical flavor variants target price-sensitive demographics through high-volume sachet distribution. Convenience-store networks in China and modern trade expansion in India concentrate demand for fruit-flavored and functional formulations with vitamin fortification.
- Tea Tablets:Compressed tea extracts enable precise dosing for hospitality and airline catering applications. Cold-water solubility specifications differentiate premium offerings from economy-tier compression formats.
- Nutritional Bars:Meal-replacement formulations integrate protein isolates with shelf-stable binding systems. Sports nutrition channels and corporate pantry services drive adoption for portion-controlled energy delivery.
Established volume favors Instant Coffee; emerging adoption favors Nutritional Bars.
Material:
REACH compliance incentives in Europe and China's dual carbon goals are rotating procurement toward plant-derived inputs.
- Plant-Based:Oat, coconut, and pea protein bases replace dairy solids in vegan-positioned formulations. German and French retail sustainability scorecards grant preferential shelf placement to plant-binder certifications.
- Dairy:Milk powder and whey concentrates retain cost advantages in Southeast Asian and Middle Eastern markets where lactose tolerance is higher and cold-chain infrastructure is limited.
- Sugar Substitutes:Stevia and monk fruit extracts face China's SAMR enforcement of GB additive thresholds. Reformulation timelines extend commercialization by 8-12 months for import-dependent brands.
- Artificial Flavors:Heat-stable synthetic compounds dominate economy-tier production in price-sensitive African and South Asian markets where natural extract costs are prohibitive.
Plant-Based materials are climbing the fastest; Artificial Flavors retain residual share in emerging markets.
Packaging Type:
The EU Green Deal's Single-Use Plastics Directive mandates recyclability thresholds above 70%, forcing material transitions across European supply chains.
- Single-Serve Pouches:Multilaterial films face substitution pressure from paper-based barrier laminates and industrially compostable biopolymers. German powdered drink manufacturers pilot home-compostable formats to maintain retail listing eligibility.
- Bags:Flexible packaging dominates bulk instant coffee distribution to food-service and industrial channels. Lightweight formats reduce logistics costs for camping and adventure tourism operators in the US and Germany.
- Cans:Aerosol and pressurized containers protect volatile aromatic compounds in specialty coffee and cocoa formulations. Premium positioning in Melbourne and Copenhagen supports higher unit economics.
- Boxes:Rigid cartons concentrate in gift and subscription channels where unboxing experience drives perceived value. Direct-to-consumer platforms in the US and UK favor SKU consolidation in multi-serve formats.
Single-Serve Pouches command margin concentration; Bags retain volume leadership in institutional channels.
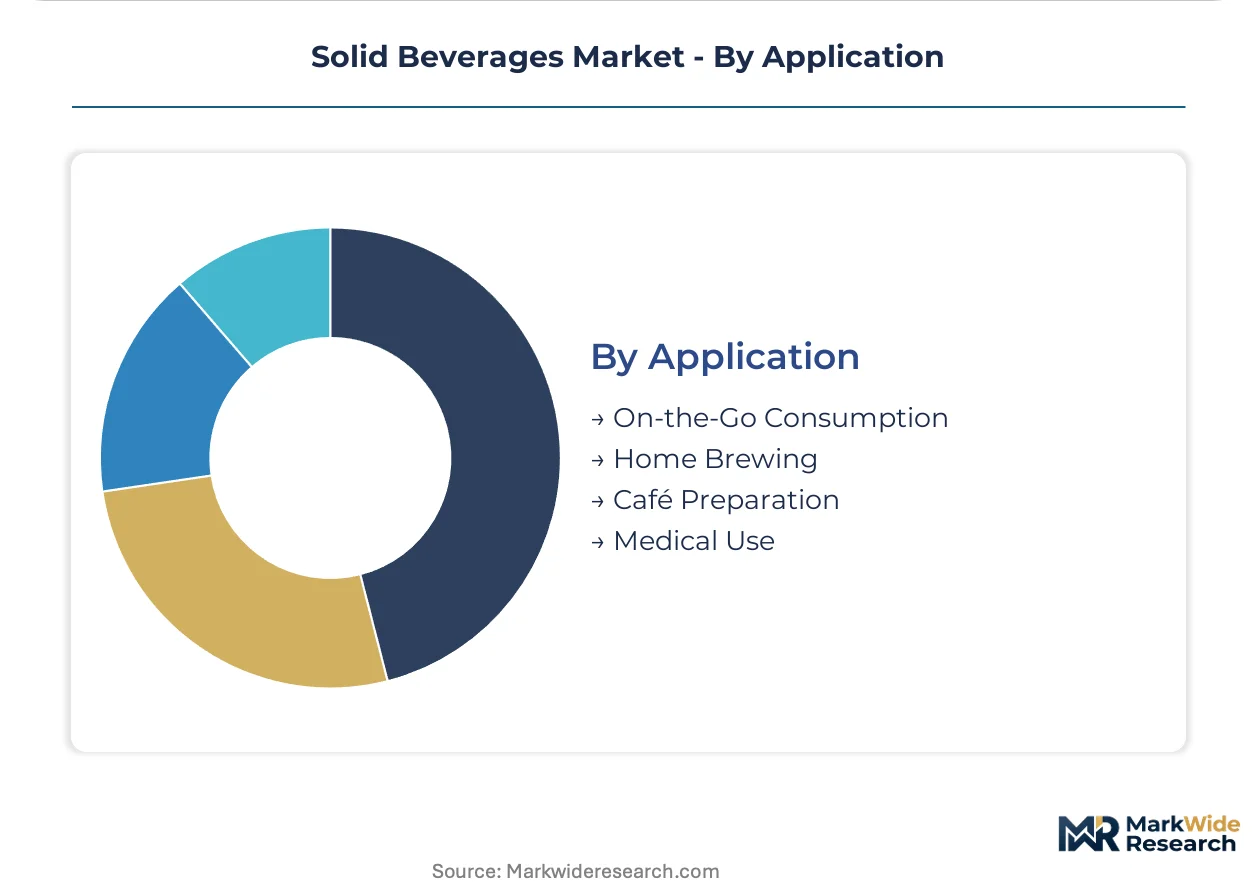
Application:
Procurement authority migration from centralized contracts to individual workplace managers is restructuring distribution economics.
- On-the-Go Consumption:Transit commuters in Mumbai and Bangalore drive sachet-format adoption for functional beverages. Modern trade expansion creates first-mover positioning for brands with cold-water solubility specifications.
- Home Brewing:Subscription-based replenishment platforms displace traditional broadline distributors in US and UK office segments. Facility managers prioritize waste reduction metrics over legacy brand recognition.
- Café Preparation:Licensed café systems and heritage brand portfolios anchor European market presence. JDE Peet's leverages this channel for premium single-origin positioning.
- Medical Use:Enteral nutrition and therapeutic hydration formulations face FDA medical food regulations distinct from conventional GRAS pathways. Hospital procurement concentrates supplier selection with specialized compliance capabilities.
Home Brewing shows steepest expansion trajectory; Medical Use carries highest regulatory barrier but defensible margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese consumers favor instant coffee sachets for urban café culture, while German and US buyers prioritize compostable single-serve formats for outdoor recreation. This consumption-mix differential shapes divergent regulatory compliance burdens and supply chain configurations across major markets.
United States
Camping and adventure tourism operators drive lightweight, shelf-stable beverage adoption for remote logistics. FDA GRAS determinations govern novel ingredient introductions, affecting functional formulation timelines. Pacific Northwest specialty coffee roasters pilot cold-water solubility microencapsulation for private-label instant lines.
Germany
REACH compliance incentives rotate procurement toward plant-based binders with preferential retailer sustainability scorecards. The EU Green Deal's Single-Use Plastics Directive mandates recyclability thresholds above 70% for packaging materials. Bavarian powdered drink manufacturers accelerate pilot lines for home-compostable sachet formats.
China
Urban café culture and convenience-store distribution networks concentrate volume for instant coffee and powdered drink sachets. SAMR enforces GB standards for food additive thresholds and labeling accuracy, affecting import eligibility. Yangtze River Delta manufacturing clusters scale low-energy freeze-drying retrofits to meet MEE carbon intensity benchmarks.
India
Modern trade expansion in Mumbai and Bangalore creates first-mover positioning for sachet-format functional beverages targeting transit commuters. FSSAI regulations govern food safety standards for fortified drink formulations. Karnataka-based distribution networks prioritize cold-water solubility specifications for tropical climate conditions.
Japan
Precision fermentation convergence with dehydration technology concentrates in Tokyo and Osaka research clusters. METI standards influence energy efficiency requirements for manufacturing equipment. Kanto region flavor chemists command premium recruitment costs for heat-stable natural extract formulation expertise.
Solid Beverages Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage rotating toward players with proprietary extraction technologies and compostable-format capabilities. The structure compresses margins for legacy plastic-dependent producers while advantaging freeze-drying specialists. Three archetypes dominate: vertically integrated beverage conglomerates, heritage brand portfolio holders, and direct-to-consumer platform operators. M&A activity targets extraction technology assets, while capacity expansion concentrates in low-carbon manufacturing jurisdictions.
Within the integrated conglomerate tier, Nestlé and PepsiCo exemplify scale-driven supply chain control from ingredient sourcing through retail placement. JDE Peet's occupies a position among heritage brand specialists leveraging European licensed café systems. Starbucks represents the direct-to-consumer archetype through subscription channels and grocery retail product extensions.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| JDE Peet's |
| Nestlé |
| Suntory Beverage & Food |
| Danone |
| The Coca-Cola Company |
| Starbucks |
| Monster Beverage |
| PepsiCo |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Brazilian coffee cooperatives and European freeze-drying operators lock in both arabica supply access and eighteen-month price visibility against frost-cycle volatility. These arrangements transfer input risk to processors while securing volume commitments for plantation renewal programs.
Pricing Analysis
Contract-based long-term offtake dominates premium freeze-dried segments, while spot-market arabica purchases govern economy-tier spray-dried production. Price differentiation rests on extraction technology tier and single-origin certification grade. Cost compression in commodity instant coffee is intensifying because Brazilian frost cycles and Colombian labor disruptions transmit directly into input instability. Economy-tier sachet buyers in Southeast Asia exhibit highest price sensitivity; licensed café systems in Europe show lowest.
Supply Chain Analysis
Inventory cycles spanning nine to fourteen months from bean harvest through retail shelf placement create working capital intensity that favors balance-sheet-strong incumbents. Manufacturing concentrates in Brazil, Vietnam, and China's Yangtze River Delta. Raw material flows draw from Ethiopian highland arabica, Vietnamese robusta, and German plant-protein isolates. Single-origin supply concentration presents structural vulnerability to climate-induced yield compression. Distribution runs through convenience-store networks in China and modern trade channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where EU Green Deal packaging mandates and China's SAMR additive thresholds create multi-year compliance barriers that freeze out undercapitalized challengers.
For Market Incumbents: Secure freeze-drying patent portfolios and compostable-format certification ahead of EU recyclability deadlines. Nestlé's integrated bean-to-shelf supply chain demonstrates how upstream control neutralizes arabica price volatility. Invest in Yangtze River Delta manufacturing retrofits to capture China's MEE carbon credit eligibility.
For New Entrants and Emerging Players: Anchor in India's sachet-format functional beverage segment, where modern trade expansion in Mumbai and Bangalore creates first-mover positioning before JDE Peet's heritage portfolio penetrates. Cold-water solubility specifications for tropical climates offer technical differentiation against spray-dried incumbents.
For Investors and Strategic Acquirers: Compostable-format specialists with ASTM D6400 validation command scarcity premiums as EU packaging directives compress legacy plastic-dependent margins. Watch for freeze-drying patent expiry timelines as inflection indicators for process-technology acquisition windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Captures premium texture replication as open-source process knowledge democratizes. |
| Compostable Packaging Certification | Secures EU retail listing eligibility under Single-Use Plastics Directive thresholds. |
| Backward Integration into Bean Sourcing | Neutralizes Brazilian frost-cycle volatility through cooperative offtake arrangements. |
| Direct-to-Consumer Platform Launch | Displaces broadline distributors as workplace procurement authority decentralizes. |
| Plant-Based Binder Reformulation | Unlocks preferential shelf placement through German retailer sustainability scorecards. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs records, Nielsen retail audit data, and SEC 10-K filings from beverage conglomerates. Interviews with freeze-drying equipment engineers, convenience-store category buyers, plant-protein procurement leads, and flavor chemists in Swiss and Japanese research clusters inform operational assumptions. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis.
Segmentation dimensions modeled include formulation chemistry, material sourcing, packaging format, and application occasion across the projection horizon. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Arabica futures curves and EU carbon credit pricing feed into cost-structure projections.
Material uncertainties — Brazilian frost severity, EU compostability certification timelines, and SAMR enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption curves and regulatory implementation schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Pineapple Juice Market
Beverages
Smoothies Market
Beverages
Citrus Water Market
Beverages
Middle East Energy Drinks Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Caffeine Mint Market
Beverages
Vegetable Juice Market
Beverages
Beverage Cooler Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
Fruit Juices and Nectars Market
Beverages
Bottled Deep Ocean Water Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Detox Drinks Market
Beverages
Europe Coconut Water Market