
 Fusion Beverages Market | 2026-2036
Fusion Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Fusion Beverages Market Analysis
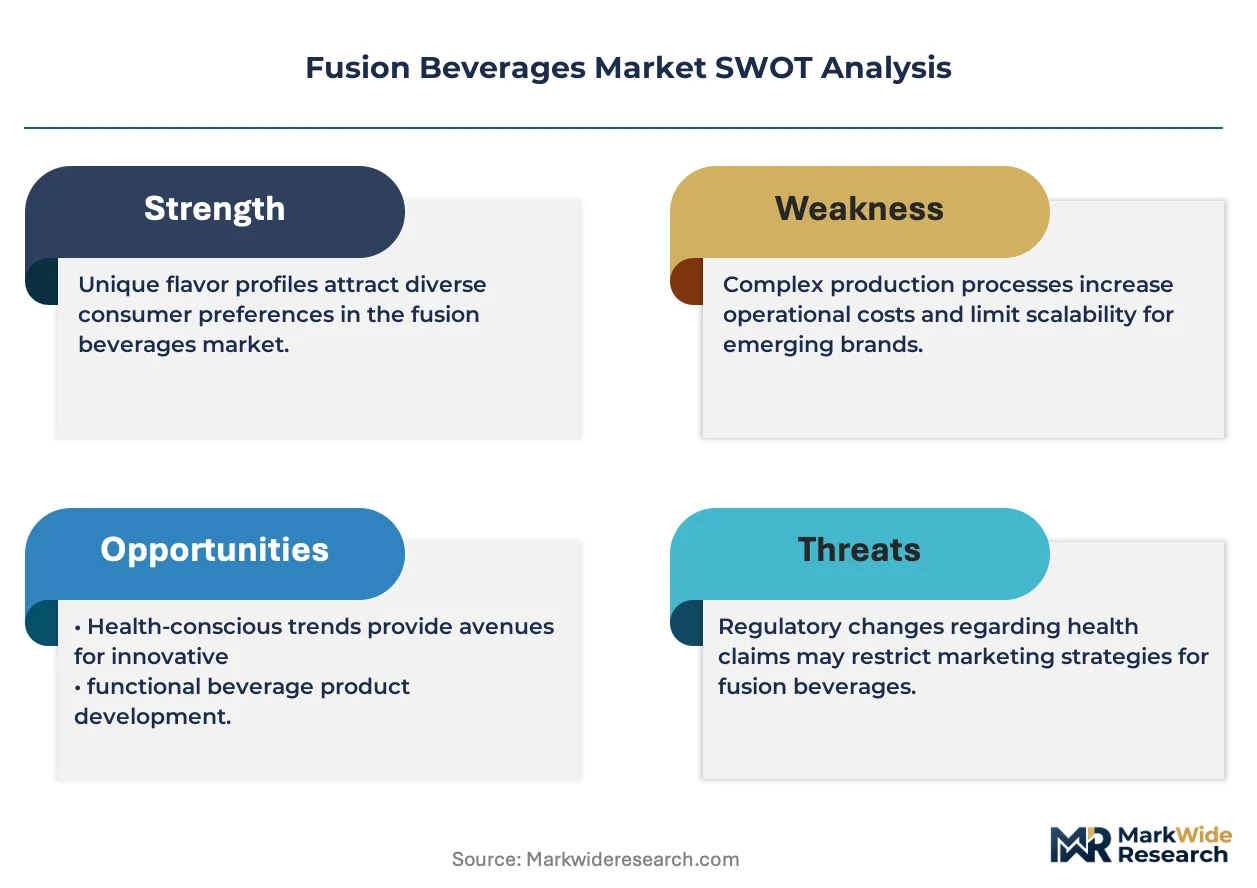
The premium functional beverage tier is pivoting toward clinically validated ingredients and transparent supply chains, while commodity fusion drinks compete on flavor novelty alone. PepsiCo leverages its distribution scale to dominate shelf space in convenience stores. Nestlé differentiates through specialized nutrition science pipelines. Red Bull GmbH anchors energy-positioned fusion lines with caffeine-alternative botanical formulations.
Fusion beverages combine two or more distinct drink categories—such as tea-coffee hybrids, fruit-protein waters, or fermented-juice blends—through co-processing or sequential infusion, typically containing 5-15% functional additives and stabilized via cold aseptic filling to preserve bioactive compounds. Their commercial purpose centers on delivering multiple consumption benefits within a single serving occasion. Sparkling tea and kombucha segments lead margin pools due to fermentation complexity and probiotic positioning. Energy drinks sustain volume leadership through athlete and busy professional targeting. Online retailers represent the fastest-growing channel as subscription models capture recurring health conscious consumers.
FDA governs health claim substantiation and GRAS status for novel ingredients in the United States, while EFSA mandates pre-market authorization for functional claims across European Union member states. These frameworks elevate compliance costs but simultaneously filter out unsubstantiated entrants, concentrating demand among validated formulations. Stakeholders must monitor evolving caffeine caps and sugar taxation thresholds as jurisdictions tighten metabolic health standards.
Market Dynamics
Clean label mandates from EFSA and FDA are forcing reformulation across the entire fusion beverage spectrum, compressing legacy additive portfolios while elevating cold aseptic filling infrastructure investment.
Growth Catalysts
- Functional Hydration Science:Clinically validated bioactive compounds—adaptogens, nootropics, and postbiotics—are pulling R&D investment from pharmaceutical pipelines into beverage co-processing facilities.
- Sugar Taxation Cascades:Tiered excise duties in the United Kingdom, France, and South Africa are accelerating zero-sugar fermentation protocols that preserve mouthfeel without caloric load.
- Cold Aseptic Filling:This stabilization technology preserves heat-sensitive probiotics and vitamins, unlocking shelf-stable kombucha and protein-tea hybrids for mass retail distribution.
Market Restraints
- Novel Ingredient GRAS Burden:FDA substantiation timelines for new botanical extracts stretch 18-24 months, freezing smaller innovators out of functional positioning.
- Aluminum Can Concentration:Three North American suppliers control 70% of printed beverage can capacity, creating input bottlenecks during seasonal demand spikes.
- Fermentation Complexity:Scalable SCOBY and kefir grain cultivation requires controlled-temperature infrastructure that commodity producers cannot replicate profitably.
Strategic Opportunities
- German Pharmacy Channel:Regulatory recognition of medical foods creates a reimbursed distribution path for clinical-grade hydration beverages targeting diabetic and renal patient populations.
- Subscription Direct-to-Consumer:Recurring revenue models bypass slotting fee barriers in consolidated retail, capturing lifetime value from wellness-focused households.
- Precision Fermentation Convergence:Integration of synthetic biology with traditional brewing is enabling novel bioactive molecules—rare cannabinoids, tailored peptides—at beverage-scale cost structures.
Industry Challenges
- Flavor Stability Expertise:Protein-hydration hybrids suffer from chalking and off-notes during shelf life, requiring cross-functional teams bridging food science and packaging engineering.
- Multi-Jurisdiction Labeling:Divergent EFSA health claim authorization and FDA structure-function claim rules force SKU fragmentation, complicating pan-Atlantic supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fusion Beverages Market |
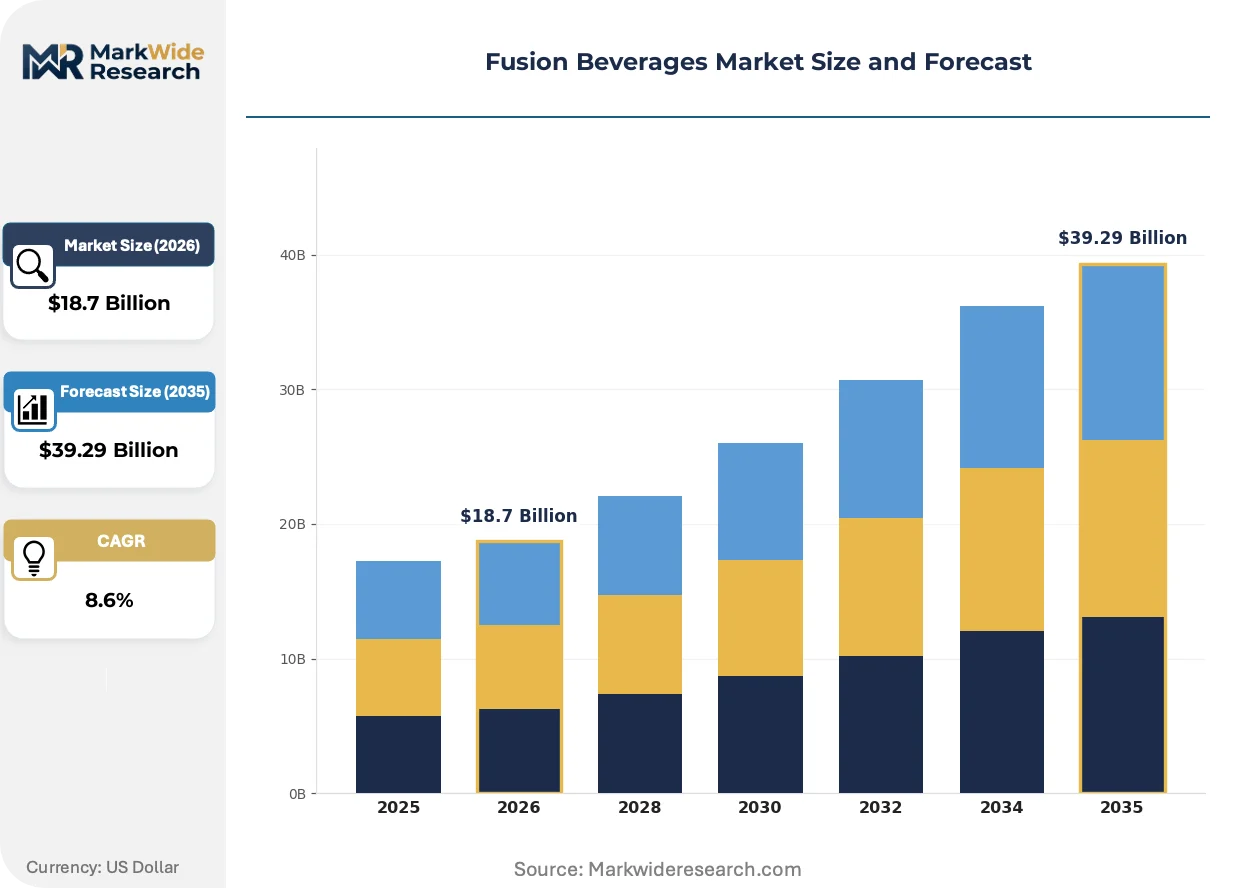
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Water, Sparkling Tea, Kombucha, Energy Drinks End User: Health Conscious Consumers, Millennials, Athletes, Busy Professionals Distribution Channel: Online Retailers, Supermarkets, Convenience Stores, Health Food Stores Packaging Type: Glass Bottles, Cans, PET Bottles, Tetra Paks |
| Companies Covered | PepsiCo, The Coca-Cola Company, Nestlé, Monster Beverage Corporation, Red Bull GmbH, Danone, Liquid Fusion, Keurig Dr Pepper, Campbell Soup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fusion Beverages Market Emerging Trajectories
Formulation science is pivoting from flavor-first novelty toward bioavailability-engineered delivery systems, while distribution infrastructure races to match perishable-probiotic logistics with ambient retail expectations.
Precision fermentation is expanding into the core production stack for functional fusion beverages. This biotechnology platform synthesizes rare bioactives—custom terpenes, optimized enzymes, and strain-specific postbiotics—at fermentation-scale economics. Specialty nutrition brands in Scandinavia and California are adopting these inputs fastest, compressing the traditional agricultural extraction supply chain for premium-tier positioning.
EFSA's 2025 tightened guidance on probiotic health claims is forcing substantiation through human intervention trials rather than in-vitro data alone. This regulatory elevation is filtering out generic culture blends and concentrating market access among formulations with documented strain-specific efficacy. German and Dutch producers are responding by vertically integrating clinical research partnerships into product development pipelines.
Health-conscious households are compressing their beverage repertoires toward multi-benefit occasions rather than single-function purchases. This behavioral consolidation is displacing standalone energy shots and basic flavored waters with hybrid offerings—sparkling tea-protein combinations, fermented fruit-electrolyte blends—that deliver hydration, microbiome support, and sustained alertness in one serving. The shift is most visible in urban coastal markets of the United States and Australia, where refrigerator space constraints and wellness expenditure concentration coincide.
Fusion Beverages Market Segmentation
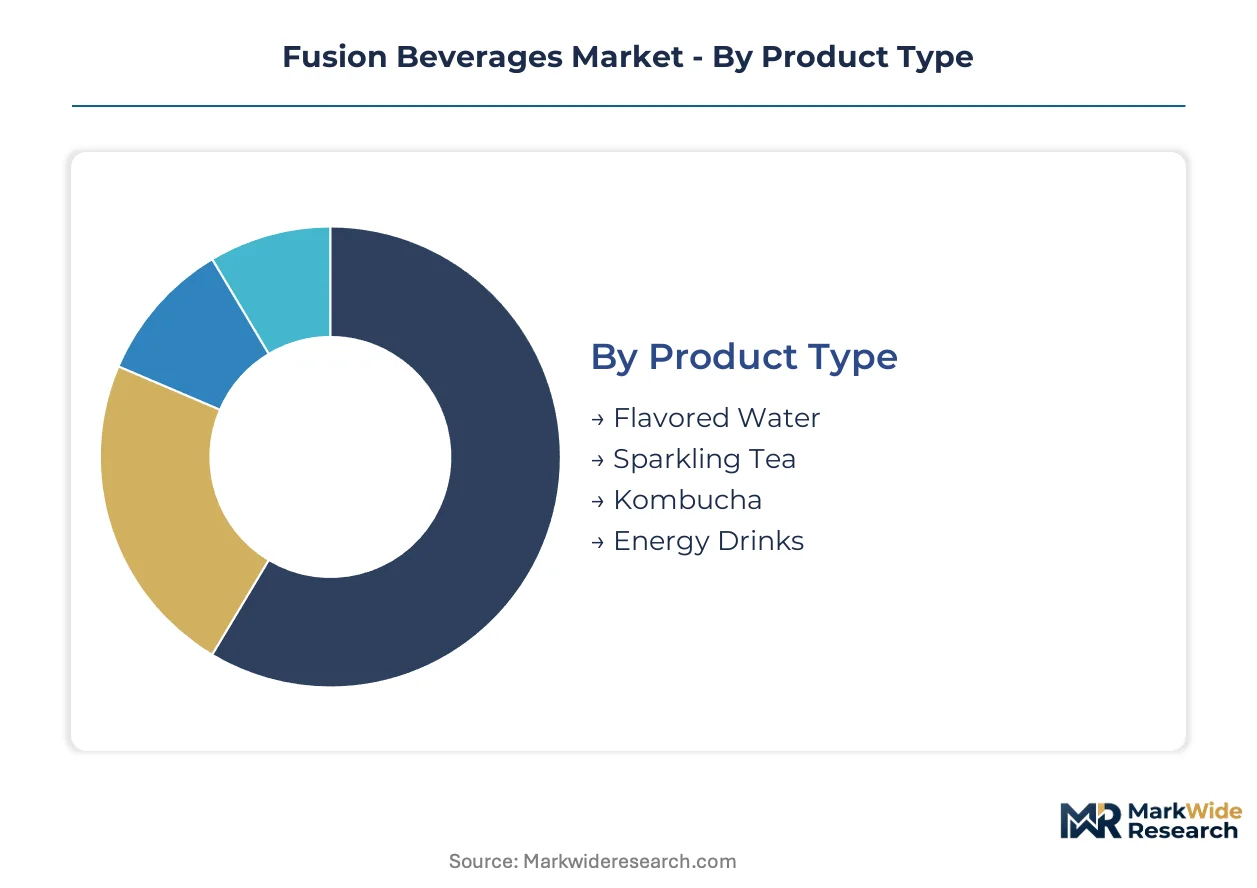
Fusion beverage segmentation reveals how formulation complexity, purchase occasion, and channel infrastructure create distinct margin pools. Understanding these divides exposes where cold aseptic filling investments and probiotic stabilization technologies concentrate competitive advantage.
Product Type:
Buyers differentiate primarily by functional benefit intensity versus refreshment priority, with fermentation complexity and bioactive density driving price tolerance.
- Flavored Water:Simple fruit-herb infusions with minimal functional additives, stabilized through standard pasteurization. Demand clusters in United States suburban supermarkets where household bulk purchasing prioritizes low-calorie refreshment over clinical efficacy.
- Sparkling Tea:Carbonated tea bases with adaptogen or nootropic fortification, requiring pressure-resistant packaging and precise CO2 dosing. Coastal United States cities and Australian metro areas show strongest uptake among professionals seeking afternoon alertness without coffee's acidity.
- Kombucha:Fermented tea with live SCOBY cultures, demanding cold chain or cold aseptic filling for shelf stability. German pharmacy channel recognition and Scandinavian subscription models validate its premium positioning.
- Energy Drinks:Caffeine-forward formulations with botanical alternatives, optimized for immediate effect duration. Athletes and shift workers in United States convenience stores sustain volume leadership despite sugar taxation pressure.
Energy drinks lead volumes today; kombucha is gaining share fastest.
End User:
Purchase frequency and willingness to pay for clinically validated ingredients separate these groups.
- Health Conscious Consumers:Households prioritizing clean label certification and transparent supply chains, often maintaining 4-6 SKU beverage repertoires. United Kingdom and France sugar taxation has accelerated their migration toward zero-sugar fermentation protocols.
- Millennials:Urban cohorts compressing consumption occasions into multi-benefit hybrids, accepting subscription pricing for personalized nutrition. Their refrigerator space constraints in dense coastal markets favor sparkling tea-protein combinations.
- Athletes:Performance-focused buyers demanding electrolyte-protein fusion with rapid gastric emptying. Sports nutrition retail and team bulk procurement create distinct channel requirements.
- Busy Professionals:Time-constrained purchasers prioritizing portability and immediate functional signaling. Convenience store placement and grab-and-go packaging specifications dominate their selection criteria.
Busy professionals sustain the highest per-capita consumption; health conscious consumers show the steepest expansion trajectory.
Distribution Channel:
Slotting fee structures and cold chain capabilities determine which formulations reach each endpoint.
- Online Retailers:Subscription platforms capturing recurring revenue from wellness-focused households, bypassing retail consolidation barriers. Direct feedback loops enable rapid formulation iteration.
- Supermarkets:Mass retail requiring ambient-stable SKUs and promotional slotting investments. United States chains dominate volume through PepsiCo and Nestlé distribution scale.
- Convenience Stores:Impulse-driven channel favoring energy drinks and single-serve formats with immediate consumption signaling. Red Bull GmbH anchors shelf space through athlete targeting.
- Health Food Stores:Curated assortment rewarding probiotic complexity and clinical substantiation. EFSA-compliant German and Dutch producers leverage this channel for premium positioning.
Supermarkets anchor current volume; online retailers are climbing the fastest.
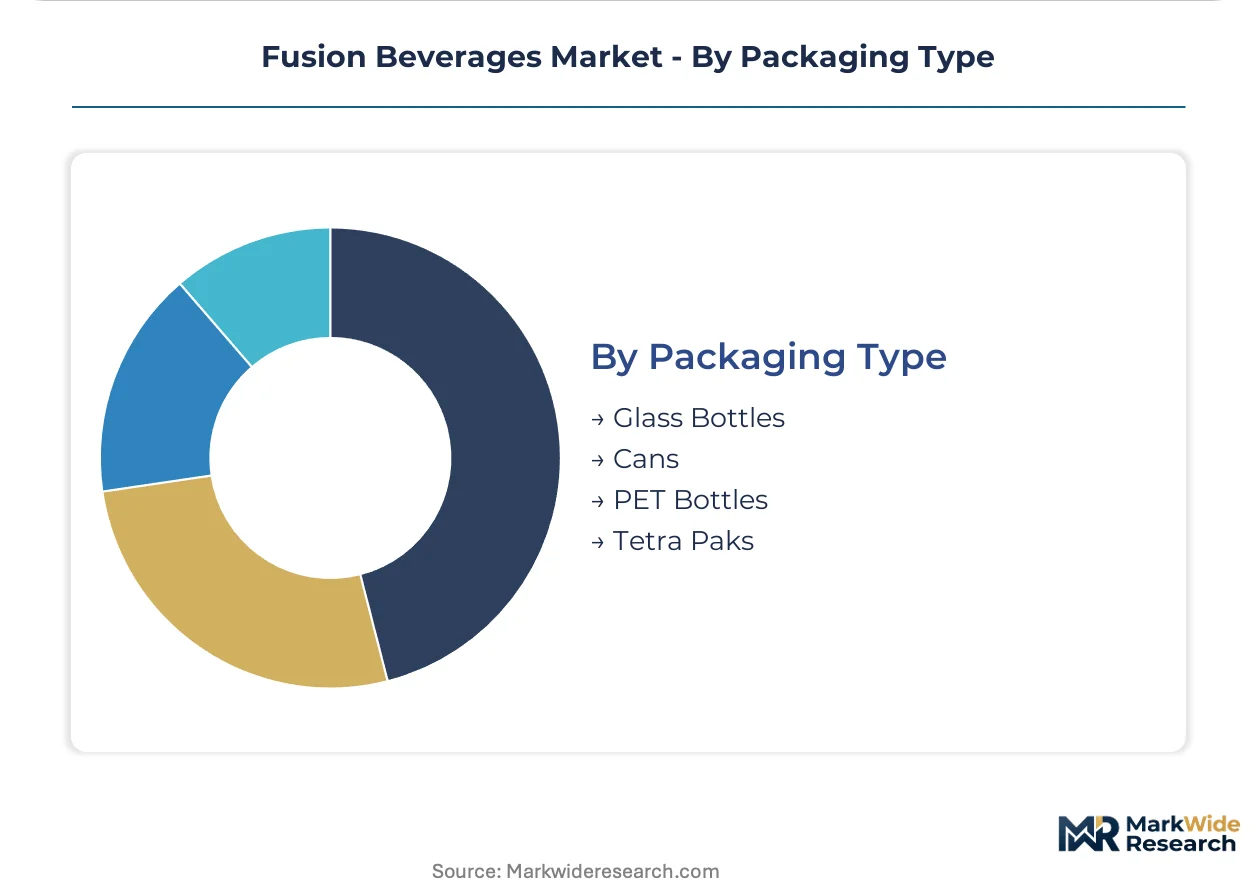
Packaging Type:
Barrier properties and sustainability credentials shape material selection against filling technology constraints.
- Glass Bottles:Premium positioning supporting kombucha and small-batch fermentation, with inert surfaces preserving flavor stability. Weight and fragility limit distribution radius.
- Cans:Dominant format for energy drinks and sparkling tea, with aluminum concentration among three North American suppliers creating seasonal bottlenecks. Infinitely recyclable messaging resonates with sustainability-focused buyers.
- PET Bottles:Lightweight solution for flavored water and mass-market hybrids, though oxygen permeability challenges probiotic viability without cold aseptic filling investment.
- Tetra Paks:Aseptic carton technology enabling ambient-stable probiotic distribution, particularly in European retail where shelf space efficiency matters.
Cans dominate current production; Tetra Paks show the strongest technology adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientists and fermentation specialists cluster in coastal innovation hubs where cold aseptic filling infrastructure meets wellness-focused consumer bases. Talent concentration in beverage formulation chemistry, probiotic stabilization, and regulatory compliance shapes geographic competitive advantage.
United States
Functional hydration startups and established beverage conglomerates compete for shelf space in Los Angeles and New York Metro health food channels. FDA GRAS substantiation timelines for novel botanical extracts extend 18-24 months, filtering smaller entrants from functional positioning claims. California's precision fermentation corridor near San Francisco integrates synthetic biology with traditional brewing infrastructure.
Germany
Pharmacy channel recognition of medical foods creates reimbursed distribution paths for clinical-grade hydration beverages targeting diabetic populations. EFSA's tightened 2025 probiotic health claim guidance mandates human intervention trials, concentrating market access among documented strain-specific formulations. Bavarian producers vertically integrate clinical research partnerships into product development pipelines.
United Kingdom
Tiered sugar taxation accelerates zero-sugar fermentation protocol adoption among London-based formulation houses. Health-conscious households in Greater Manchester and Birmingham compress beverage repertoires toward multi-benefit hybrids. Clean label mandates reshape supermarket assortment criteria, elevating transparent supply chain documentation requirements.
Australia
Urban coastal markets in Sydney and Melbourne exhibit refrigerator space constraints that favor sparkling tea-protein combinations over single-function purchases. TGA oversight of therapeutic claims intersects with state-level food safety frameworks for fermented products. Subscription direct-to-consumer models capture recurring revenue from wellness-focused households in dense metro areas.
Netherlands
Amsterdam-Rotterdam logistics corridors enable cold chain distribution of live SCOBY cultures across northwestern European markets. EFSA pre-market authorization requirements for functional claims filter unsubstantiated entrants from premium positioning. Dutch producers leverage health food store curation for EFSA-compliant probiotic complexity and clinical substantiation.
Fusion Beverages Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fusion beverage spectrum, with cold aseptic filling infrastructure and distribution scale separating tiers. Consolidated retail slotting fee structures favor players with promotional investment capacity, while subscription channels lower barriers for specialized nutrition entrants. Three strategic archetypes dominate: multinational conglomerates with beverage-scale distribution, specialized nutrition science pipelines, and precision fermentation biotechnology platforms. Dominant competitive moves include M&A for formulation IP and geographic expansion through pharmacy channel partnerships.
Within the multinational beverage conglomerate tier, PepsiCo, Nestlé, and Red Bull GmbH occupy positions defined by distribution infrastructure rather than formulation novelty. PepsiCo exemplifies scale-driven shelf space capture in convenience store channels. Nestlé represents specialized nutrition science integration with clinical validation pipelines. Red Bull GmbH anchors energy-positioned fusion lines through athlete and professional targeting. These players exemplify how capital deployment in cold chain logistics and retail consolidation creates defensive positioning against biotechnology-enabled entrants.
| Leading Market Players |
|---|
| PepsiCo |
| The Coca-Cola Company |
| Nestlé |
| Monster Beverage Corporation |
| Red Bull GmbH |
| Danone |
| Liquid Fusion |
| Keurig Dr Pepper |
| Campbell Soup |
| Others |
Supply Flow & Price Mechanics
Aluminum LME spot pricing volatility cascades through beverage packaging tiers, compressing margins for commodity-format producers while cold aseptic filling investments insulate premium kombucha and protein-tea hybrids from input cost transmission.
Pricing Analysis
Subscription bundling versus single-unit transactional purchasing splits the pricing architecture across this market. Three-tier pricing structure across premium, standard, and economy levels reflects fermentation complexity and clinical substantiation depth. Price differentiation hinges on EFSA-compliant strain documentation and cold chain certification. Cost compression in flavored water tiers is intensifying because aluminum can supply bottlenecks during seasonal spikes concentrate pricing power among three North American suppliers. Health-conscious households in subscription channels show least price sensitivity; convenience store energy drink purchasers exhibit highest elasticity.
Supply Chain Analysis
Refrigerated freight cost inflation from California to New York Metro corridors shapes distribution economics for live-culture products. Supply concentrates in United States precision fermentation clusters, German pharmaceutical-grade hydration facilities, and Scandinavian probiotic culture banks. Raw material dependencies include SCOBY cultivation substrates, adaptogen botanical extracts, and cold-pressed fruit bases. Single-source vulnerability around printed aluminum can capacity creates seasonal allocation risk. Distribution runs through consolidated retail slotting fee structures for mass-market SKUs, while direct-to-consumer subscription models bypass shelf-space barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where health-conscious households compress beverage repertoires toward clinically validated, multi-benefit formulations with transparent supply chain documentation.
For Market Incumbents: Deploy cold aseptic filling capacity expansion to defend shelf-stable probiotic positioning against precision fermentation biotechnology entrants. Backward integration into SCOBY culture banking and adaptogen extraction secures input quality tiers. Channel control through pharmacy partnerships in Germany and subscription platform ownership locks in recurring revenue against slotting fee inflation. For New Entrants and Emerging Players: EFSA's tightened 2025 probiotic health claim guidance in the European Union opens a window for clinical-grade hydration beverages with human intervention trial backing. White-space concentration sits in German pharmacy-channel medical foods for diabetic populations and Australian metro subscription models for refrigerator-constrained urban professionals. Direct-to-consumer launch with rapid formulation feedback loops enables iteration speed that retail slotting barriers prevent. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation biotechnology platforms converging synthetic biology with beverage-scale production economics. Long-term viability centers on rare bioactive molecule manufacturing capabilities and regulatory validation infrastructure. The signal to watch is German pharmacy reimbursement expansion for clinical-grade functional hydration targeting renal and metabolic patient populations.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Aseptic Filling Scale-Up | Unlocks shelf-stable probiotic distribution through ambient retail channels without live-culture degradation. |
| Precision Fermentation Integration | Enables synthetic biology-derived rare cannabinoids and tailored peptides at beverage production economics. |
| Pharmacy Channel Partnership | Creates reimbursed distribution path for medical-grade hydration in German diabetic care markets. |
| Subscription Platform Development | Bypasses consolidated retail slotting fees while capturing lifetime value from wellness-focused households. |
| Clinical Research Verticalization | Satisfies EFSA human intervention trial mandates for strain-specific probiotic health claim authorization. |
Methodological Framework
Bottom-up end-user consumption modeling reconciled against top-down cold aseptic filling capacity tracking forms the analytical core of this study. Primary interviews with beverage formulation chemists, health food store category buyers, pharmacy channel procurement managers, and subscription platform operators combined with secondary validation from FDA GRAS filings, EFSA health claim registers, Nielsen retail audit data, and aluminum industry capacity disclosures. Triangulation between demand-side household panel data and supply-side infrastructure investment pipelines ensures coverage integrity.
Historical trendline analysis across fermentation complexity tiers, functional additive density, and channel infrastructure development established baseline growth patterns. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and packaging format. CAGRs derive from elasticity-adjusted adoption curves and capacity-constrained supply expansion trajectories. Forecast inputs incorporate EFSA regulatory timeline probability, sugar taxation cascade effects, and precision fermentation cost reduction curves.
Revisions become necessary when FDA GRAS substantiation timelines extend beyond standard windows, aluminum supply concentration triggers allocation rationing, or EFSA probiotic guidance shifts strain documentation requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Electrolyte Mixes Market
Beverages
Bubble Food and Beverages Market
Beverages
Hydrogen Water Bottle Market
Beverages
Global Squash Drinks Market
Beverages
North America Kombucha Market
Beverages
Root Beer Market
Beverages
United Kingdom Energy Drink Market
Beverages
Low Calorie RTD Beverages Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Italy Bottled Water Market
Beverages
Global Electrolyte Drinks Market
Beverages
Fermented Foods and Beverages Market
Beverages
Sparkling Water Market
Beverages
Hydration Infusers Market
Beverages
Dairy Based Beverages Market