
 Fruit Juices and Nectars Market | 2026-2036
Fruit Juices and Nectars Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Juices and Nectars Market Foresight
Single-serve portion packs is pivoting how households and on-the-go buyers select fruit juices, shifting volume from bulk containers toward convenience-oriented formats. PepsiCo leverages its bottling network to sustain shelf presence across North American convenience channels. The Coca-Cola Company anchors its juice portfolio through Minute Maid and Simply Orange brand equity in refrigerated cases. Nestle competes in ambient nectar segments with geographic dominance across Latin American retail shelves.
Fruit juices and nectars comprise beverages extracted or pressed from fresh fruits, with nectars containing 25-50% fruit content plus permitted additives for stability and taste, processed through pasteurization or aseptic filling to achieve shelf stability. Their primary commercial purpose spans refreshment, nutritional supplementation, and ingredient supply to food manufacturers. The 100% Fruit Juice category leads value contribution due to premium positioning and health credentials, while Juice Blends capture faster volume growth as flavor innovation attracts younger demographics. PET Bottle packaging dominates cost-efficient distribution, though Tetra Pak formats hold margin pools in ambient-stable, export-oriented supply chains.
EU F-Gas Regulation and REACH constrain refrigerant choices and material compositions in European juice processing and distribution equipment. FDA enforces juice HACCP rules in the United States, mandating pathogen reduction steps that shape plant capital allocation and operational protocols. Stakeholders must monitor evolving extended producer responsibility frameworks for packaging waste, as these mechanisms will determine cost structures and format viability across major markets.
Market Dynamics
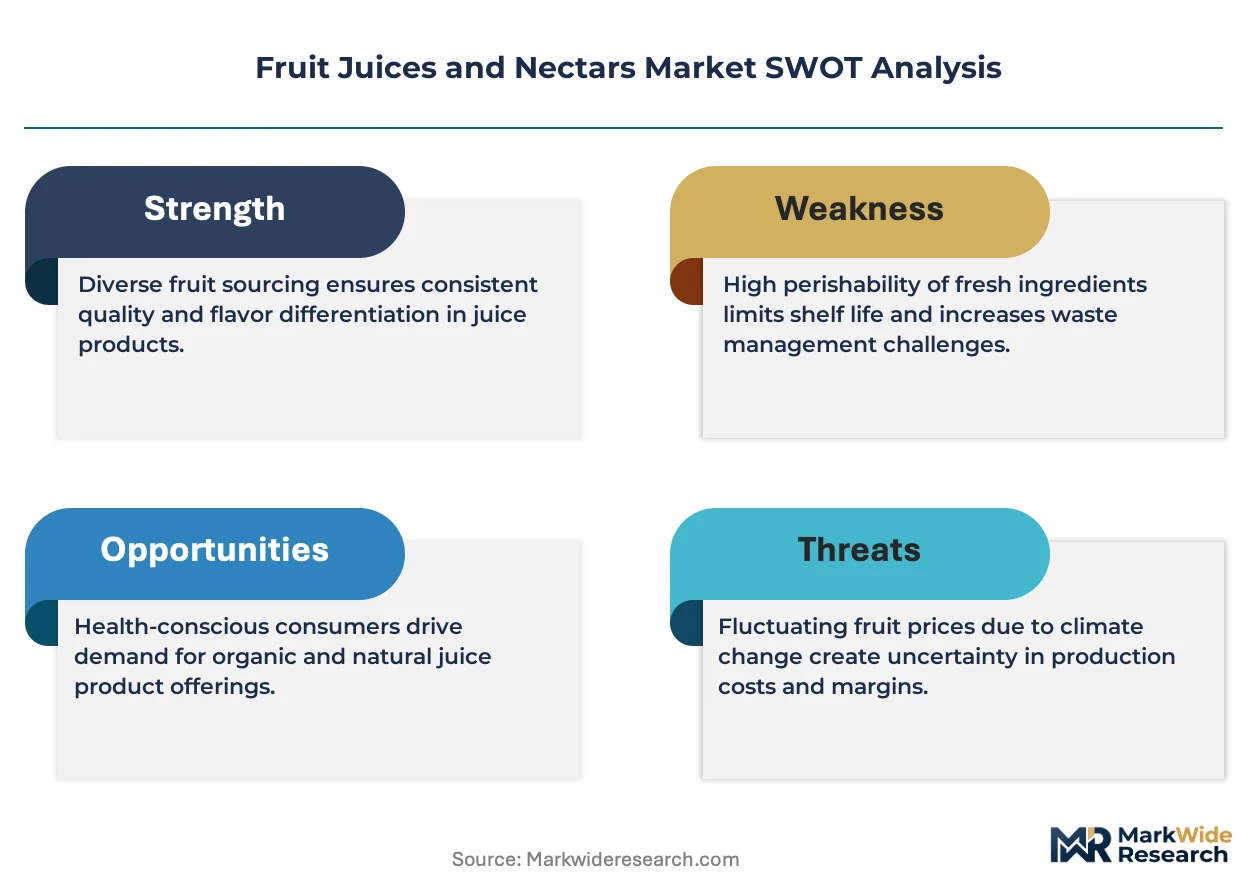
Clean-label beverage mandates are compressing formulation timelines as retailers demand shorter ingredient decks and transparent sourcing disclosures from their juice suppliers.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain infrastructure upgrades across European processing facilities are accelerating adoption of natural refrigerant systems that reduce operational carbon intensity.
- Food service channel expansion:Premium juice programs at quick-service restaurants and hospitality operators are pulling volume toward higher-margin not-from-concentrate formats.
- Tetra Pak aseptic filling:Extended shelf-life technology is electrifying export opportunities for tropical juice producers in Brazil and India.
Market Restraints
- Fruit input cost volatility:Weather-driven citrus and tropical fruit harvest variability compresses margin predictability for processors dependent on spot-market procurement.
- Supply concentration risk:PET resin and aseptic packaging substrate production clusters in East Asian manufacturing hubs expose bottlers to logistics disruption cascades.
- REACH compliance friction:Extended material safety testing timelines for novel packaging additives delay product launch windows in European markets.
Strategic Opportunities
- India modern retail buildout:Organized grocery expansion in Tier-2 and Tier-3 cities creates first-mover positioning for ambient-stable nectar portfolios.
- Extended producer responsibility frameworks:Packaging waste mandates in Germany and France reward early investment in closed-loop recycling infrastructure.
- High-pressure processing convergence:Cold pasteurization technology paired with clean-label positioning is electrifying the premium chilled juice segment.
Industry Challenges
- Food safety certification timelines:Juice HACCP validation protocols in FDA-regulated facilities extend facility commissioning periods and tie up capital.
- Legacy equipment integration:Retrofitting existing pasteurization lines for lower-energy operation creates engineering complexity and downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Juices and Nectars Market |
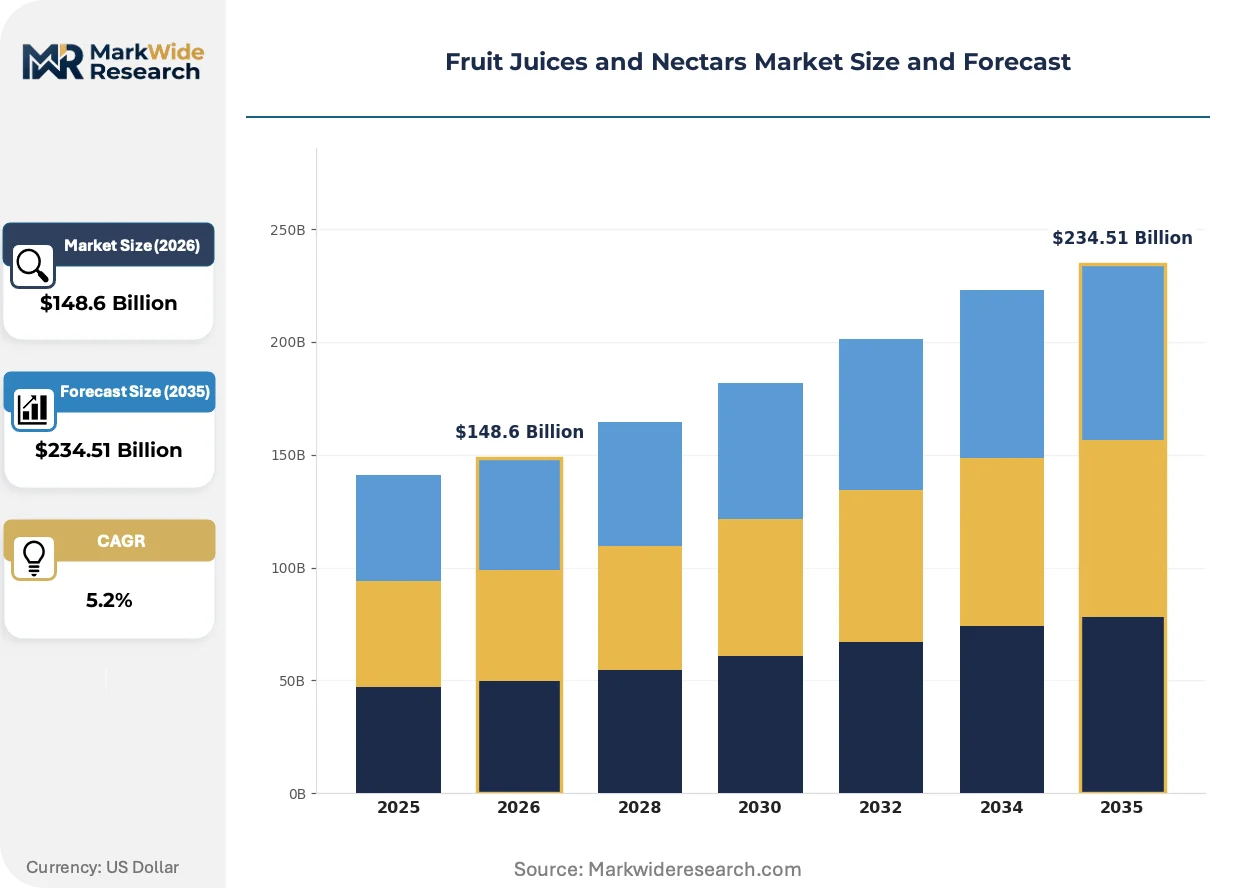
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $234.51 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 100% Fruit Juice, Nectar, Concentrate, Juice Blends, Vegetable Juice Packaging Type: Carton, Glass Bottle, PET Bottle, Tetra Pak, Aluminum Can End User: Supermarkets, Food Service, Convenience Stores, Online Retailers, Specialty Shops Distribution Channel: Modern Trade, Traditional Trade, E-commerce, Direct Selling, Wholesale |
| Companies Covered | The Coca-Cola Company, PepsiCo, Tropicana Products, Del Monte Foods, Ocean Spray Cranberries, Suntory Beverage & Food, AGRANA Group, Dohler Group, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Juices and Nectars Market Shifts & Advancements
Processing technology, regulatory compliance architecture, and channel configuration are simultaneously rewiring how juice products reach end consumers and what claims they can support.
Aseptic cartons with plant-based barrier layers are electrifying sustainable packaging roadmaps for ambient juice brands. European retailers are demanding these formats for their private-label programs. The shift is compressing demand for conventional fossil-based multilayer structures.
REACH and EU F-Gas Regulation are forcing reformulation of processing equipment refrigerants and packaging material compositions across European bottling operations. Compliance investments are diverting capital from line expansion. German and French facilities are absorbing the steepest cost adjustments.
Direct-to-food-service procurement is displacing traditional wholesale distribution for chilled juice volumes in North American urban markets. Restaurant groups are negotiating supply agreements directly with regional processors. This pattern is most visible in California and Florida citrus corridors.
Fruit Juices and Nectars Market Segmentation
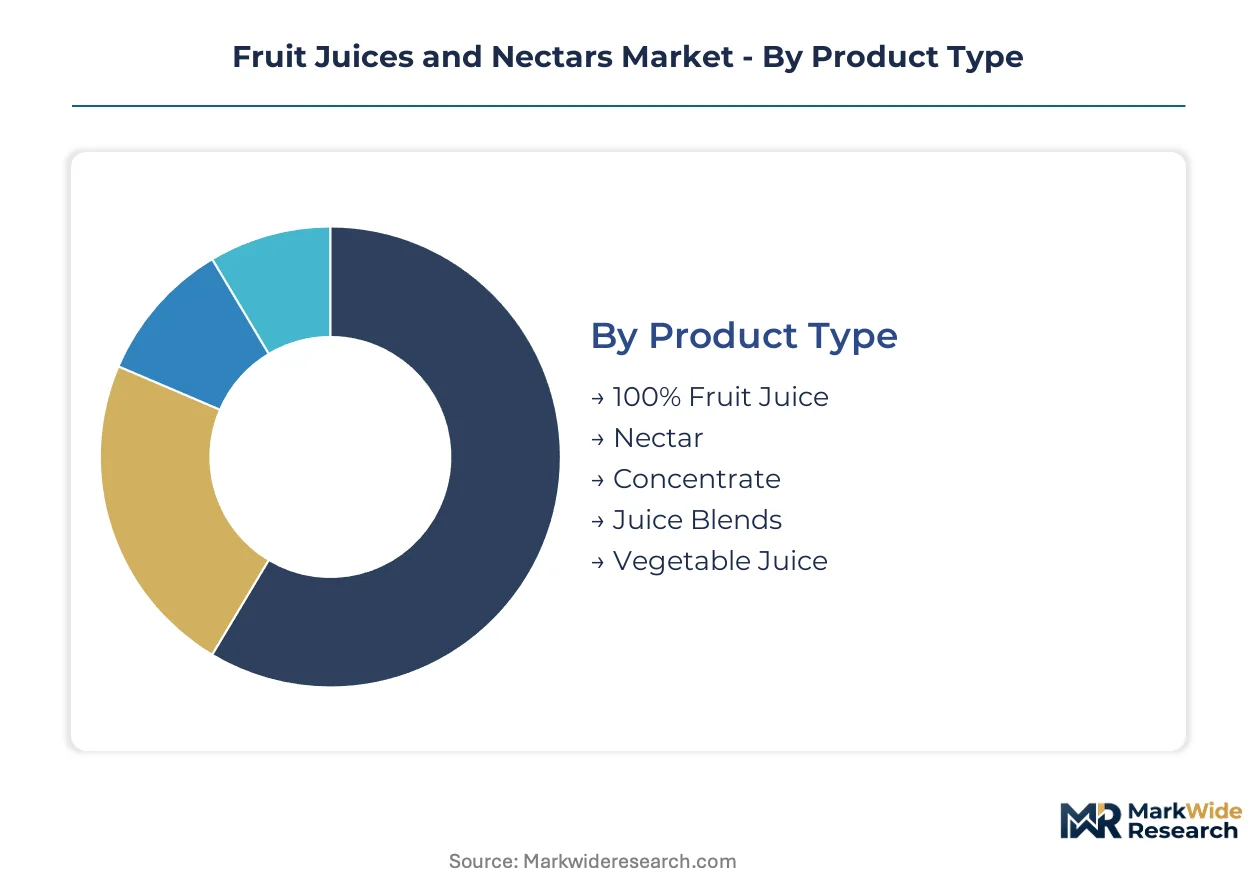
Segmentation in fruit juices and nectars separates volume-driven commodity plays from premium-margin specialty positions. Each axis—product formulation, packaging format, end-user channel, and distribution pathway—carries distinct capital requirements and regulatory exposure that reshape competitive economics.
Product Type:
Volume concentrates in entry-level refreshment while premium pools around functional nutrition claims and provenance storytelling.
- 100% Fruit Juice:Products containing no added sugars, preservatives, or dilutants beyond water naturally present in fruit. Demand concentrates in German refrigerated retail cases and North American club stores where clean-label credentials command shelf price premiums. FDA juice HACCP compliance adds processing cost but defends margin against commodity competition.
- Juice Blends:Formulations combining multiple fruit sources or fruit-vegetable hybrids to deliver novel flavor profiles and functional positioning. Brazilian and Indian urban markets are pulling volume fastest as younger consumers trial exotic combinations. Extended producer responsibility frameworks in France and Germany favor brands with transparent ingredient sourcing.
- Nectar:Beverages with 25-50% fruit content plus permitted water, sugars, and stabilizers for taste and shelf stability.
- Concentrate:Dehydrated or evaporated juice base requiring reconstitution, dominating industrial ingredient supply and export economics.
- Vegetable Juice:Single-vegetable or blended vegetable beverages positioned for functional nutrition and low-sugar alternatives.
Today's leader: 100% Fruit Juice. Tomorrow's challenger: Juice Blends.
Packaging Type:
Cost-per-unit and carbon footprint tradeoffs are forcing format selection toward either lowest landed cost or highest sustainability credential.
- Tetra Pak:Multilayer aseptic cartons enabling ambient distribution without refrigeration. Export-oriented Brazilian orange juice processors and Indian mango nectar bottlers rely on this format for extended shelf-life logistics into European and Middle Eastern markets. EU F-Gas Regulation compliance costs are accelerating plant-based barrier layer adoption.
- PET Bottle:Lightweight, shatter-resistant polymer containers dominating cost-efficient chilled distribution. German discount retailers and North American convenience channels specify this format for its logistics efficiency. REACH compliance timelines for recycled content certification are compressing launch windows.
- Carton:Gable-top or pure-paperboard containers for short-shelf-life chilled juices.
- Glass Bottle:Premium-positioned returnable or single-use format for provenance-focused brands.
- Aluminum Can:Emerging format for sparkling juice and on-the-go single-serve portions.
Format economics favor PET for volume, Tetra Pak for reach, with sustainability mandates rewriting the cost equation.
End User:
Channel power concentration determines who captures margin—retailers with shelf gatekeeping authority or food service operators with direct consumer relationships.
- Food Service:Restaurants, hotels, cafeterias, and institutional catering operations sourcing chilled and ambient juices for immediate consumption. California and Florida citrus processors are negotiating direct supply agreements with quick-service restaurant chains, bypassing traditional wholesale distributors. Premium not-from-concentrate programs are expanding fastest in this channel.
- Supermarkets:Organized grocery retailers with refrigerated and ambient shelf space for branded and private-label juices. German and French modern trade operators are demanding aseptic carton formats with plant-based barriers for their private-label programs.
- Convenience Stores:Small-format retail prioritizing grab-and-go single-serve packaging and impulse purchase positioning.
- Online Retailers:E-commerce platforms with ambient-stable, direct-to-home fulfillment economics.
- Specialty Shops:Health food, organic, and gourmet retailers curating premium and niche juice offerings.
Food Service is capturing margin fastest; Supermarkets retain volume dominance.
Distribution Channel:
Physical infrastructure maturity versus digital penetration rates are segmenting growth trajectories by geography.
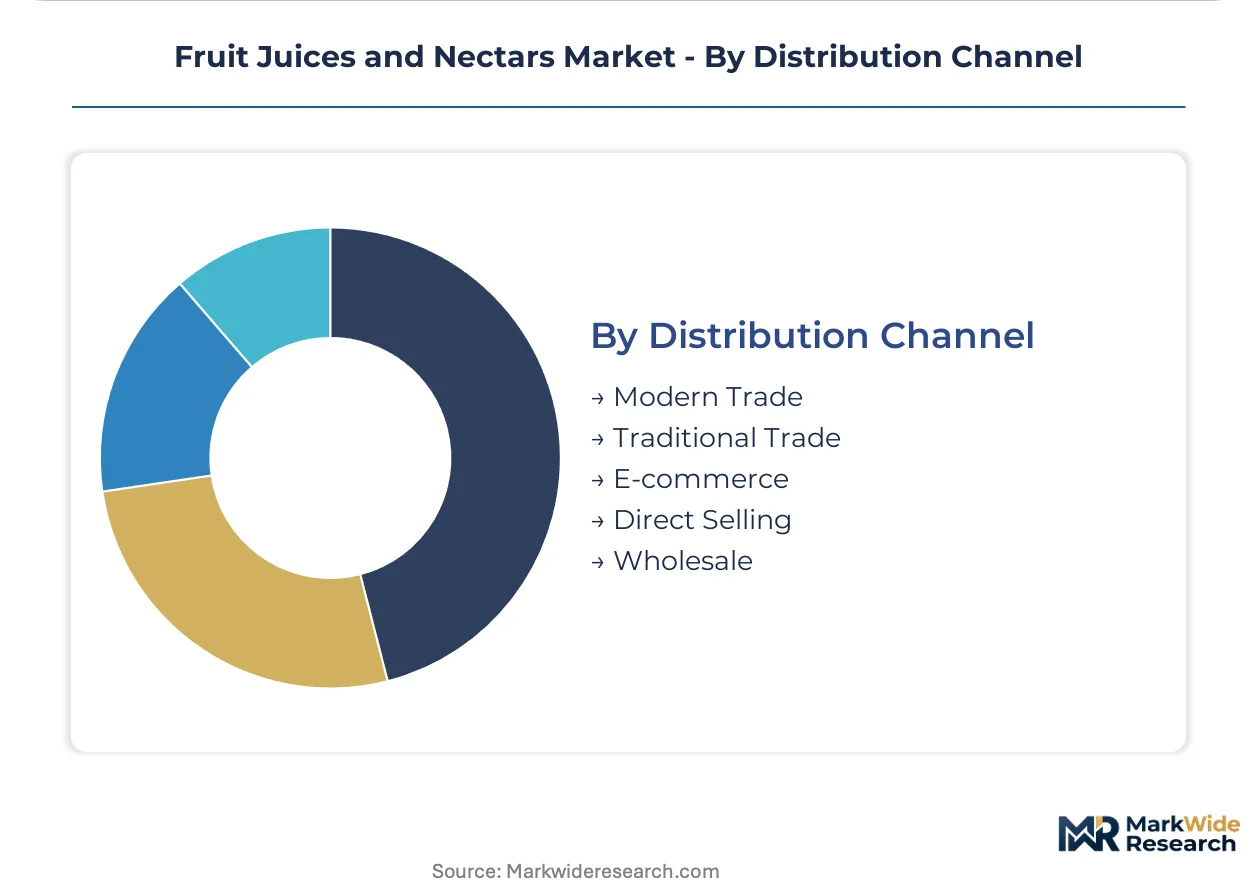
- E-commerce:Direct-to-consumer and platform-mediated online sales with ambient-stable fulfillment requirements. Indian Tier-2 and Tier-3 city expansion is driving nectar portfolio trials through organized grocery delivery platforms. FSSAI labeling compliance adds friction but defends quality positioning.
- Modern Trade:Organized retail chains with centralized procurement, cold-chain infrastructure, and private-label development capabilities. Brazilian and German markets show highest penetration of this channel for juice and nectar distribution.
- Traditional Trade:Fragmented independent retailers, open markets, and small-format stores dominating emerging market volume.
- Direct Selling:Processor-to-customer relationships bypassing intermediaries, common in food service and institutional contracts.
- Wholesale:Bulk distribution to secondary retailers and food service intermediaries with lower margin but higher volume throughput.
Modern Trade commands today's volume; E-commerce is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fruit juice industry traces its modern commercial roots to 19th-century Florida citrus groves and Mediterranean orange cultivation, with industrial-scale processing consolidating first in coastal plantation economies before diffusing to temperate zone markets.
United States
Florida and California citrus belts anchor domestic not-from-concentrate production, while cold-pressed premium segments expand in urban coastal markets. FDA juice HACCP enforcement shapes processing plant capital allocation across the Southeast. Direct procurement agreements between Florida processors and quick-service restaurant chains are displacing traditional wholesale distribution.
Germany
Discount retail dominance and private-label sophistication compress branded juice margins while elevating sustainability credentials as shelf gatekeeping criteria. EU F-Gas Regulation and REACH compliance requirements drive refrigeration system retrofits in Bavarian and North Rhine-Westphalian bottling facilities. The country's extended producer responsibility frameworks reward closed-loop carton recycling infrastructure investments.
Brazil
São Paulo state orange groves supply global concentrate and not-from-concentrate export volumes, with Tetra Pak aseptic filling enabling ambient-stable distribution to European and Middle Eastern markets. ANVISA sanitary regulations govern export certification timelines. Port infrastructure at Santos anchors tropical juice logistics networks serving import-dependent northern hemisphere markets.
India
Tier-2 and Tier-3 city modern retail buildout creates first-mover positioning for ambient nectar portfolios in Maharashtra and Gujarat organized grocery channels. FSSAI labeling compliance adds friction but defends quality positioning against informal sector competition. Mango and guava processing clusters in Uttar Pradesh and Andhra Pradesh supply raw material to branded bottlers.
China
Domestic citrus and apple processing scales in Shandong and Sichuan provinces serve both beverage and industrial ingredient demand. SAMR food safety supervision and GB standards compliance shape facility commissioning protocols. Yangtze River Delta cold-chain infrastructure supports chilled juice distribution to Shanghai and Jiangsu province urban consumers.
Fruit Juices and Nectars Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and channel access, with clean-label positioning and direct food service relationships defending price realization against private-label compression. The vendor base stratifies into three tiers: multinational beverage conglomerates with bottling network control, regional processors with raw material sourcing advantages, and private-label specialists serving retail consolidation. Consolidation pressure concentrates among mid-scale processors lacking either brand equity or captive agricultural supply. Competitive moves center on strategic partnerships for cold-chain infrastructure and portfolio diversification into functional beverage adjacencies.
Within the multinational tier, The Coca-Cola Company and PepsiCo exemplify beverage conglomerate positioning through bottling network leverage and convenience channel shelf presence. Nestle occupies a distinct archetype in ambient nectar segments with geographic concentration across Latin American retail. Among ingredient and private-label specialists, AGRANA Group and Dohler Group represent the processing-technology and formulation-supply vector serving branded bottlers and retail private-label programs.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Tropicana Products |
| Del Monte Foods |
| Ocean Spray Cranberries |
| Suntory Beverage & Food |
| AGRANA Group |
| Dohler Group |
| Nestle |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation mandates for natural refrigerant retrofits are forcing European bottlers to absorb capital costs that compress margin pools in chilled juice segments. German discount retailers and North American club stores exploit this pressure to extract price concessions from processors lacking captive cold-chain infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates fruit juice transactions, with not-from-concentrate positioning commanding shelf premiums in refrigerated cases while nectar concentrates anchor value-tier volumes. Price differentiation hinges on clean-label certification status and provenance sourcing transparency. Pricing pressure stems from private-label expansion in German and French modern trade channels. Food service operators demonstrate lowest price sensitivity due to direct procurement relationships, while discount retail buyers extract maximum concession.
Supply Chain Analysis
Freight cost volatility in refrigerated container logistics is reshaping sourcing geography decisions for tropical juice processors. Supply concentrates in Brazil, India, and Germany as these markets build processing scale and retail infrastructure. Raw material dependencies center on citrus concentrate, mango pulp, and aseptic packaging substrates. Single-source vulnerability in East Asian PET resin production exposes bottlers to disruption cascades. Distribution runs through modern trade chains in developed markets and fragmented traditional trade in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fruit juice sector has entered a late-cycle quality phase where margin defense requires premium specification investment rather than volume expansion. Consumer procurement is shifting decisively toward clean-label and provenance-verified offerings that reward early compliance investment.
For Market Incumbents: Anticipate margin compression from private-label substitution by deepening backward integration into tropical fruit sourcing clusters in Brazil and India. Prioritize certification investment for EU F-Gas Regulation compliance to defend shelf access in German and French retail channels. Channel control through direct food service relationships offers the most durable pricing power against commodity competition. For New Entrants and Emerging Players: Launch via e-commerce platforms targeting Indian Tier-2 and Tier-3 city households with ambient-stable nectar portfolios that bypass cold-chain infrastructure requirements. White-space concentration sits in functional juice blends with vegetable-fruit hybrid positioning for health-conscious urban consumers. Direct-to-food-service procurement agreements with quick-service restaurant chains offer the most penetrable entry vector in North American markets. For Investors and Strategic Acquirers: Asymmetric upside sits with regional processors possessing captive agricultural supply in tropical fruit belts and established Tetra Pak aseptic filling partnerships. Long-term viability favors assets with demonstrated REACH compliance and closed-loop recycling infrastructure in European markets. Monitor extended producer responsibility framework implementation in Germany and France as the critical inflection signal for packaging format winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Sourcing | Captive supply of Brazilian orange and Indian mango feedstock reduces spot-market exposure and margin volatility. |
| Natural Refrigerant Retrofit Program | EU F-Gas Regulation compliance in German facilities defends market access against non-compliant competitors. |
| Plant-Based Barrier Packaging Transition | Aseptic carton innovation aligns with French and German retailer sustainability mandates for private-label programs. |
| Direct Food Service Supply Agreements | Bypassing wholesale distributors in California and Florida corridors captures premium not-from-concentrate margins. |
| High-Pressure Processing Line Investment | Cold pasteurization technology enables clean-label positioning in premium chilled juice segments without thermal degradation. |
Research Methodology
Direct dialogue with juice processing plant managers, retail category buyers at German and Brazilian supermarket chains, food service procurement directors, and Tetra Pak equipment specialists grounded qualitative assessment. Secondary validation drew from FDA juice HACCP guidance documents, EU F-Gas Regulation implementation reports, ANVISA export certification databases, and FSSAI labeling compliance frameworks. Bottom-up volume modeling across product type, packaging format, and distribution channel segments was cross-checked against top-down macroeconomic indicators.
Segment-level value outputs across the projection horizon reflect demand elasticity parameters calibrated to clean-label premium coefficients and channel penetration rates. The analytical framework modeled 100% fruit juice, juice blends, nectars, and concentrates by PET bottle, Tetra Pak, and glass format configurations through food service, supermarket, convenience, and e-commerce pathways. CAGRs were derived from iterative reconciliation of historical consumption patterns with regulatory-driven format shift assumptions and modern retail buildout trajectories in target geographies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather events affecting citrus and tropical fruit harvests, sudden REACH compliance deadline accelerations, or logistics disruption in East Asian packaging substrate supply. Stakeholders should weight assumptions against their own operating context and sourcing exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Asia-Pacific Spring Water Market
Beverages
Bottled Air Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
North America Kombucha Market
Beverages
Global Soda Maker Market
Beverages
Apple Juice Concentrate Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Double Valve Moka Pots Market
Beverages
Drinking Water Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
North America Energy Drink Market
Beverages
Fermented Foods and Beverages Market
Beverages
GCC Bottled Water Market
Beverages
Middle East Energy Drinks Market
Beverages
Sports Drink Market