
 Caffeine-Based Drinks Market | 2026-2036
Caffeine-Based Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Caffeine-Based Drinks Market Analysis
Single-serve pod and can configurations is recalibrating how consumers trial and replenish caffeine-based drinks. The Coca-Cola Company leverages its fountain and cooler infrastructure to dominate immediate-consumption channels. PepsiCo anchors its portfolio through Mountain Dew and Starbucks licensed ready-to-drink lines. Nestle sustains leadership in at-home pod systems through machine-locked capsule ecosystems.
Caffeine-based drinks comprise beverages containing psychoactive methylxanthine compounds, typically dosed between 30 and 200 milligrams per serving, formulated through extraction, brewing, or synthetic addition for mental alertness and physical performance enhancement. Energy drinks occupy the highest-margin tier due to premium pricing and functional ingredient stacking, while ready-to-drink coffee captures volume leadership through convenience-store penetration. Iced coffee and bottled tea segments compete for afternoon consumption occasions, with flavor innovation in vanilla and berry variants driving trial among younger demographics.
The FDA enforces caffeine disclosure and GRAS status for novel stimulant additives, while the EU's Food Information to Consumers Regulation mandates precise labeling that shapes reformulation priorities across exported product lines. EFSA caffeine intake guidelines for adolescents directly constrain marketing and portion strategies in European markets. Stakeholders must monitor evolving stimulant thresholds and packaging waste directives to anticipate where compliance costs will reshape competitive economics.
Market Dynamics
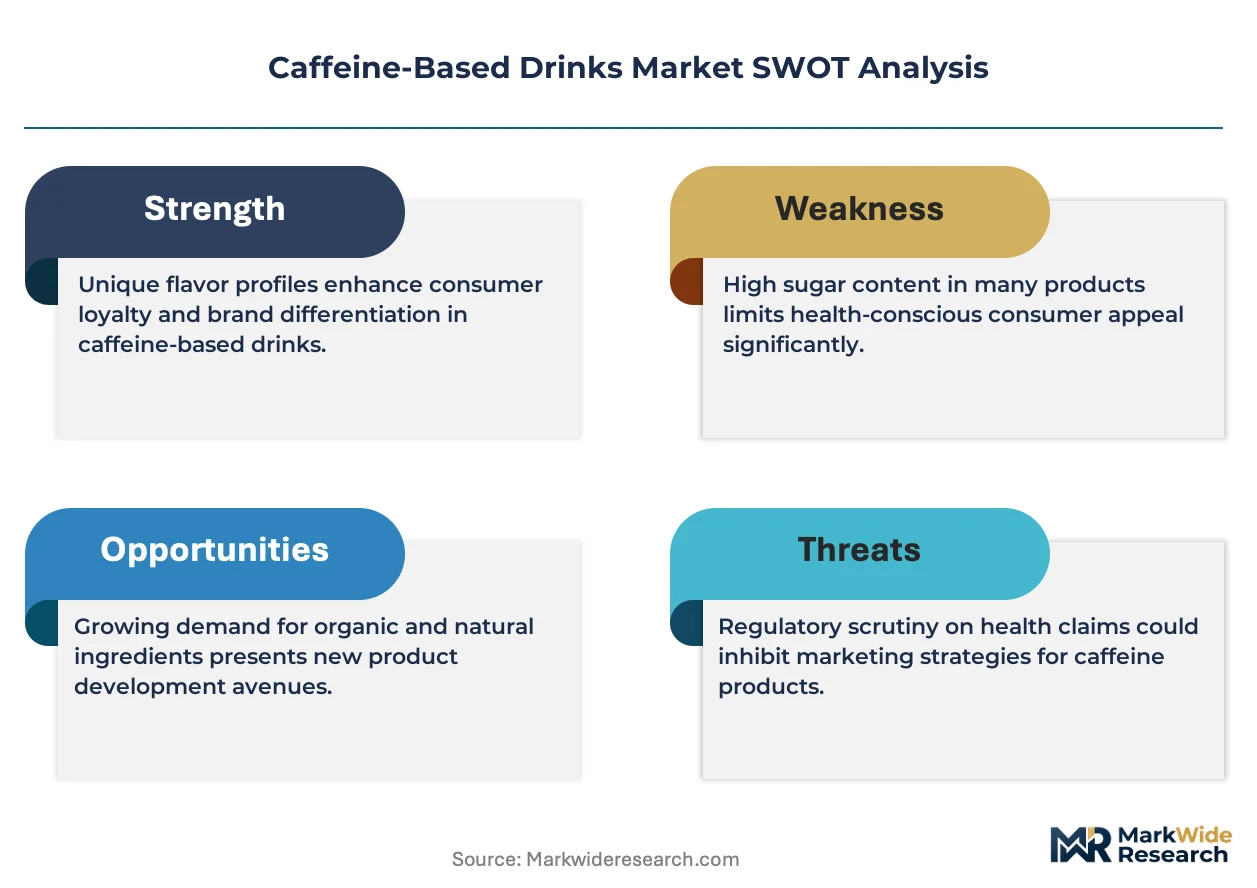
Reformulation pressure from sugar-content disclosure mandates is compressing legacy portfolios while functional ingredient stacking creates margin expansion vectors for energy drink specialists.
Growth Catalysts
- FDA Added Sugars Labeling:The FDA's mandatory added sugars line on Nutrition Facts panels is accelerating reformulation investment toward zero-calorie sweetener systems in exported US product lines.
- Pod System Penetration:At-home espresso pod infrastructure is expanding trial frequency among remote workers who previously relied on out-of-home coffeehouse channels.
- Ready-to-Drink Convenience:Fitness-oriented consumers are pulling single-serve canned coffee into post-workout consumption occasions previously occupied by sports nutrition beverages.
Market Restraints
- Arabica Price Volatility:Weather-driven supply shocks in Brazilian highland growing regions are transmitting cost pressure through roasted coffee input streams.
- EFSA Caffeine Thresholds:The European Food Safety Authority's 3 mg/kg bodyweight guidance for adolescents is constraining portion sizes and marketing reach in European markets.
- Synthetic Caffeine Sourcing:Pharmaceutical-grade synthetic caffeine production concentrates in Chinese and Indian chemical processors, creating single-source dependency risk.
Strategic Opportunities
- India Functional Beverage White Space:FSSAI's recent caffeine content notification framework is opening compliant pathways for energy drink market development in tier-2 cities.
- Microbiome-Positioned Formulations:Convergence between probiotic cultures and cold-brew coffee systems is enabling gut-health positioning in premium refrigerated channels.
- Direct-to-Subscription Models:Machine-locked pod ecosystems are capturing recurring revenue through auto-replenishment platforms that bypass traditional retail slotting fees.
Industry Challenges
- Flavor Chemist Talent Scarcity:Reformulation timelines are extending due to limited specialist capacity in natural flavor masking for high-intensity sweetener systems.
- Packaging Waste Compliance:Extended producer responsibility frameworks in Germany and France are forcing capital deployment into recyclable mono-material can and bottle redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caffeine-Based Drinks Market |
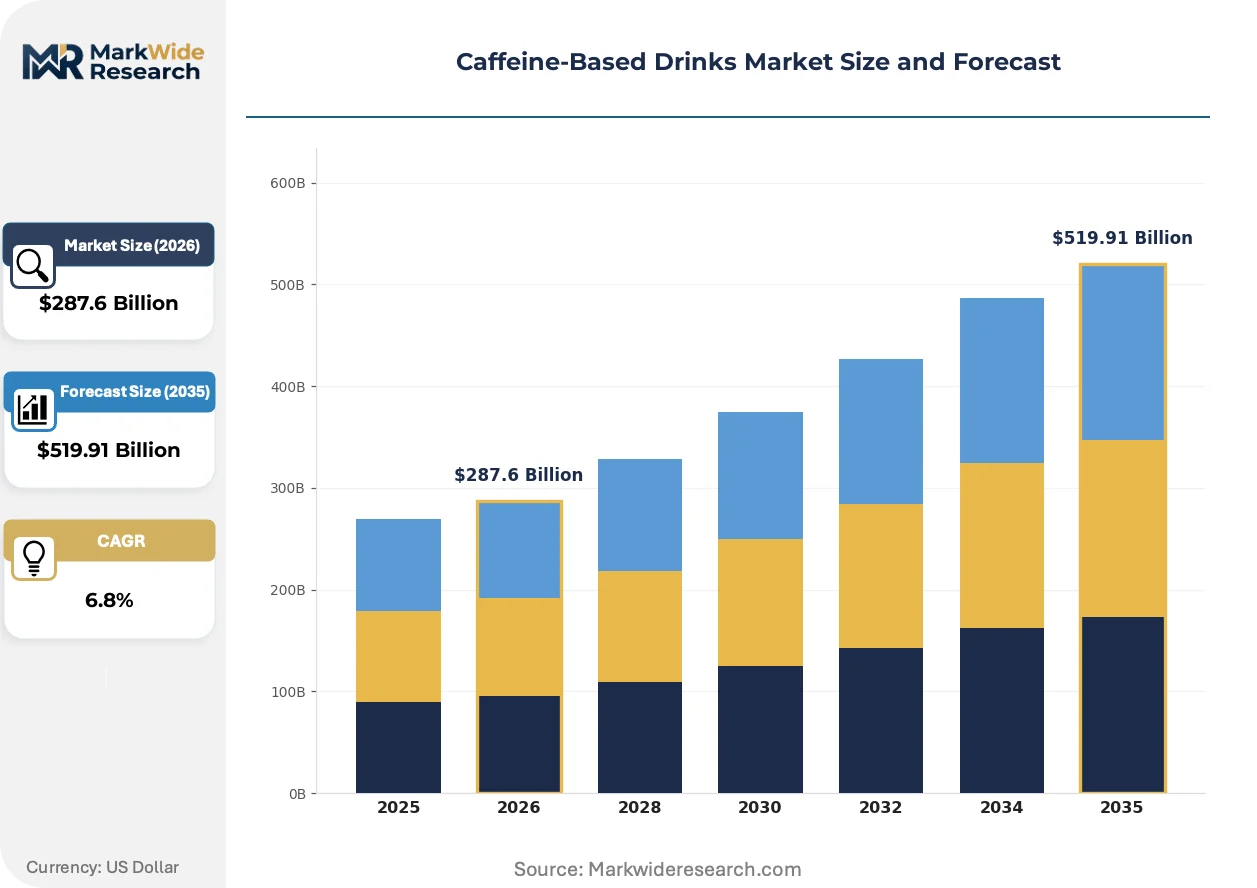
| Market Size in 2026 | $287.6 Billion |
| Market Size in 2035 | $519.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Iced Coffee, Bottled Tea, Ready-to-Drink Coffee Flavor: Citrus, Berry, Vanilla, Chocolate Packaging Type: Can, Glass Bottle, Plastic Bottle, Tetra Pak Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Cafés |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestle, Red Bull GmbH, Monster Energy Co., Keurig Dr Pepper, Starbucks Corp., AriZona Beverages USA LLC, Asahi Group Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caffeine-Based Drinks Market Emerging Trajectories
Functional ingredient layering and precision-dosing formats are displacing commodity caffeine positioning across all consumption occasions, from morning ritual to athletic performance.
Cold-brew nitrogen infusion technology is integrating into mainstream ready-to-drink portfolios. Convenience store buyers are adopting nitro-coffee SKUs at accelerating velocity. This format shift is integrating draft-system aesthetics into aluminum can packaging, compressing the experiential gap between café and retail channels.
EFSA's novel food approval pathways for botanical adaptogens are tightening ingredient substantiation requirements. Manufacturers must compile safety dossiers for ashwagandha and rhodiola additions. Energy drink formulations targeting European markets are responding by narrowing functional claims to caffeine-taurine synergies with established regulatory histories.
Subscription-based replenishment is capturing habitual caffeine consumers through machine-locked ecosystems. Pod and concentrate delivery models are displacing supermarket bulk purchasing among urban professionals. Japan and South Korea demonstrate the most advanced penetration of auto-replenishment platforms tied to smart appliance connectivity.
Caffeine-Based Drinks Market Segmentation
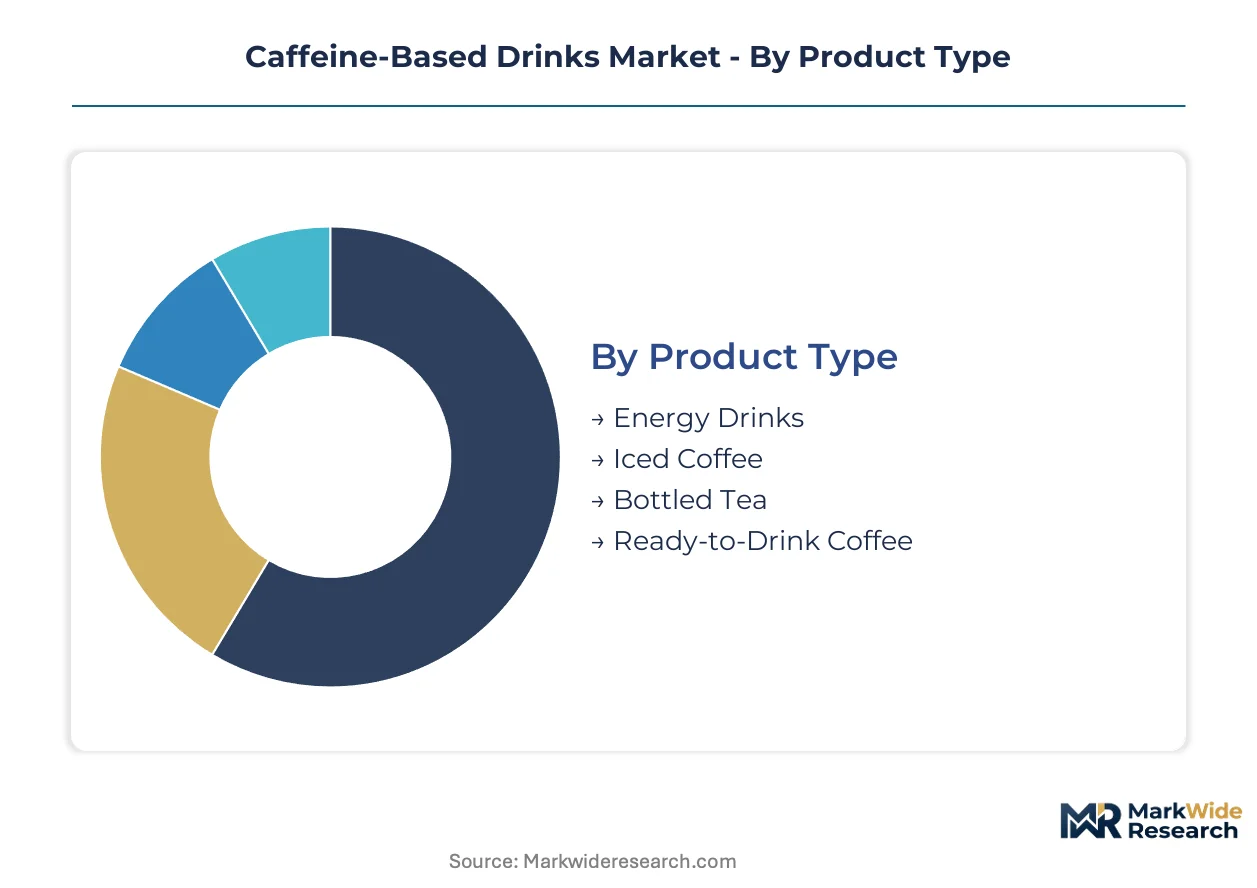
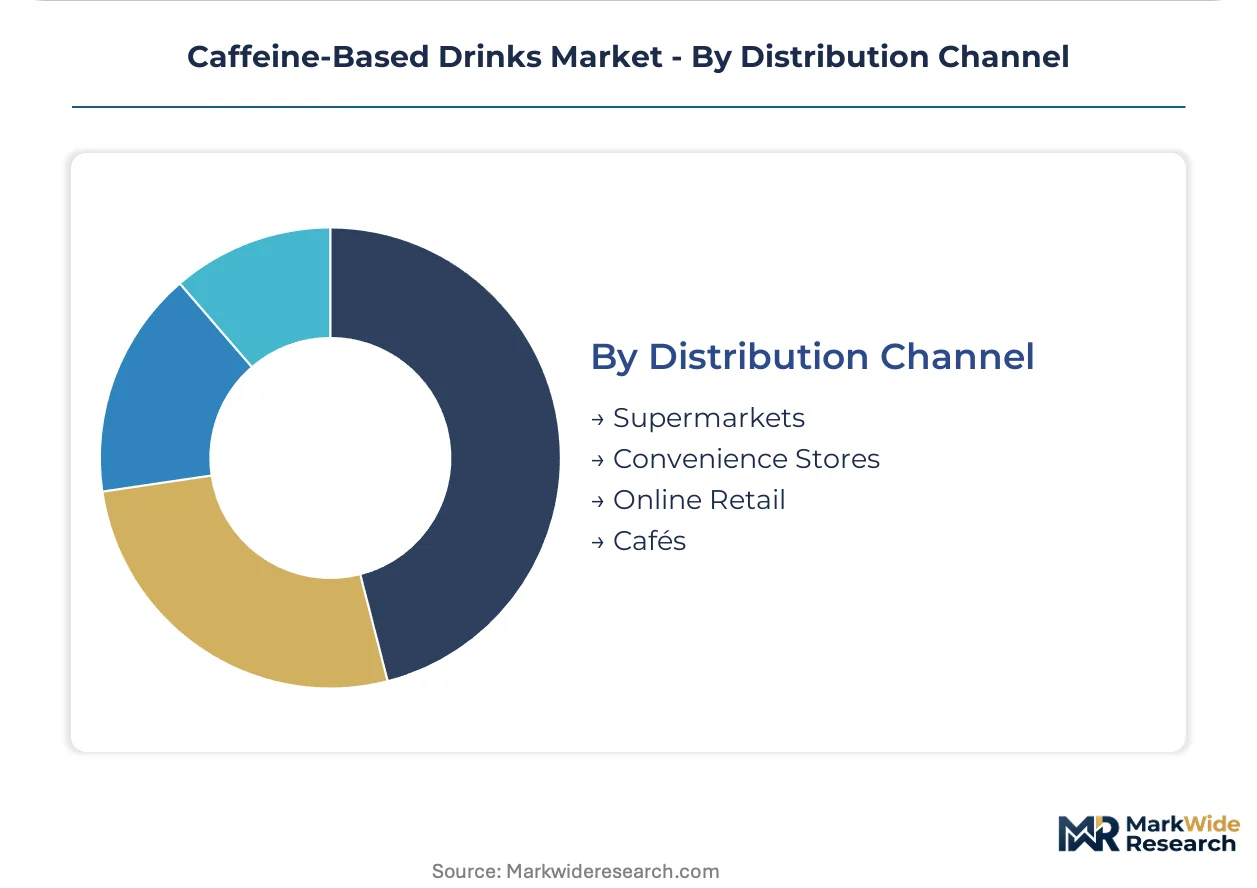
Caffeine-based drinks fragment across four distinct category systems. Product type determines margin structure and regulatory exposure. Flavor, packaging, and channel choices reshape trial frequency and loyalty economics in fundamentally different ways.
Product Type:
Volume leadership sits with convenience-oriented formats while premium margins concentrate in functional stacks.
- Energy Drinks:Highest-margin tier built on caffeine-taurine synergies and adaptogen layering. Demand concentrates among fitness-oriented consumers in the United States and Germany where gym-channel penetration drives repeat purchase. EFSA novel food pathways constrain botanical additions in exported European lines.
- Ready-to-Drink Coffee:Volume leader through single-serve can configurations and cold-brew nitrogen infusion. Post-workout consumption occasions among remote workers in Japan and Brazil are displacing traditional coffeehouse visits. Convenience-store cooler placement determines regional share distribution.
- Iced Coffee:Afternoon consumption bridge competing with bottled tea for office-channel placement.
- Bottled Tea:Lower caffeine positioning targeting evening and hydration occasions without sleep disruption.
Today's leader: Ready-to-Drink Coffee. Tomorrow's challenger: Energy Drinks.
Flavor:
Flavor selection signals demographic targeting and determines reformulation complexity under sugar disclosure rules.
- Citrus:Dominant energy drink profile masking bitterness of high-intensity sweetener systems. Youth demographics in Brazil and Mexico drive velocity in convenience channels. Natural flavor chemist scarcity extends development timelines for clean-label variants.
- Vanilla:Premium ready-to-drink coffee standard integrating with cold-brew nitrogen formats. Remote workers in Japan and South Korea favor this profile for at-home pod system trial. Auto-replenishment platforms capture habitual purchasers.
- Berry:Cross-category appeal bridging energy drinks and bottled tea for female-skewed trial.
- Chocolate:Indulgence positioning in mocha-style ready-to-drink coffee competing with afternoon snack occasions.
Citrus commands current volume. Vanilla posts the steepest expansion trajectory in subscription channels.
Packaging Type:
Material choice shapes recycling compliance costs and experiential differentiation in draft-system aesthetics.
- Can:Aluminum mono-material dominance in ready-to-drink coffee and energy drinks. Germany and France extended producer responsibility frameworks force capital deployment into recyclable redesigns. Nitrogen infusion technology integrates seamlessly with can geometry.
- Glass Bottle:Premium positioning in café-channel iced coffee with reusable deposit systems in European markets.
- Plastic Bottle:Cost-optimized bottled tea and value energy drink distribution in emerging markets.
- Tetra Pak:Aseptic cold-brew coffee for ambient distribution in retail channels with limited cooler infrastructure.
Can formats lead immediate consumption. Glass bottles gain share fastest in deposit-return markets.
Distribution Channel:
Channel mix determines margin capture versus trial accessibility in the convenience-versus-experience tradeoff.
- Convenience Stores:Velocity engine for single-serve energy drinks and ready-to-drink coffee. Cooler placement fees and slotting economics concentrate power with Coca-Cola and PepsiCo fountain infrastructure in the United States and Japan. Impulse purchase occasions drive flavor experimentation.
- Online Retail:Subscription auto-replenishment platforms for pod system lock-in. Urban professionals in South Korea and Japan demonstrate highest smart-appliance connectivity penetration. Direct models bypass retail slotting fees.
- Supermarkets:Multi-pack volume for pantry-loading and price-promotion sensitivity.
- Cafés:Draft-system experience bridging retail and out-of-home consumption for nitro-coffee formats.
Convenience stores dominate unit velocity. Online retail climbs fastest in recurring revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coffee cultivation took root in Ethiopian highlands before commercial roasting scaled in Brazil's São Paulo state during the nineteenth century. Energy drink formulation later emerged from Thailand and Austria in the 1970s, establishing the geographic split between agricultural commodity sourcing and functional beverage innovation that persists today.
United States
Fitness-oriented consumers in Texas and California are pulling canned cold-brew into post-workout routines previously served by sports nutrition products. FDA added sugars disclosure mandates are accelerating reformulation toward high-intensity sweetener systems in exported product lines. Atlanta and Purchase anchor rival fountain infrastructure networks that dominate immediate-consumption channel placement.
Brazil
Arabica price volatility in Minas Gerais highland growing regions is transmitting cost pressure through roasted coffee input streams for domestic processors. ANVISA's caffeine content notification framework shapes compliance pathways for energy drink market development in São Paulo and Rio de Janeiro. Campinas clusters concentrate flavor chemist talent for natural masking systems in clean-label reformulations.
Japan
Remote workers in Tokyo and Osaka are displacing traditional coffeehouse visits with at-home pod system trial frequency. METI's smart appliance connectivity standards enable auto-replenishment platform penetration among urban professionals. Kanto region demonstrates the most advanced subscription model adoption tied to machine-locked capsule ecosystems.
Germany
Extended producer responsibility frameworks in Bavaria and North Rhine-Westphalia are forcing capital deployment into recyclable mono-material can redesigns. EFSA's 3 mg/kg bodyweight caffeine guidance for adolescents constrains portion sizes and marketing reach across European exported lines. Hamburg and Munich anchor deposit-return system infrastructure that accelerates glass bottle share gain in premium iced coffee channels.
India
FSSAI's recent caffeine content notification framework is opening compliant pathways for energy drink development in Maharashtra and Karnataka tier-2 cities. Younger demographics in Mumbai and Bangalore drive citrus-flavored energy drink velocity in emerging convenience channels. Gujarat clusters concentrate aseptic Tetra Pak cold-brew production for ambient distribution in retail with limited cooler infrastructure.
Caffeine-Based Drinks Market Vendor Landscape
Premium-margin players sit above commodity-margin players across functional ingredient stacking and pod system lock-in economics. The vendor base concentrates around beverage conglomerates with fountain infrastructure, coffee specialists with machine-locked ecosystems, and energy drink pure-plays with adaptogen formulation capabilities. Three archetypes dominate: diversified conglomerates leveraging cooler placement networks, coffee specialists capturing recurring revenue through subscription pods, and functional specialists commanding premium pricing through ingredient layering. Competitive moves center on M&A for regional flavor portfolios and backward integration into roasted coffee supply.
Within the diversified conglomerate tier, The Coca-Cola Company and PepsiCo exemplify fountain and cooler infrastructure dominance that shapes immediate-consumption channel economics. Nestle occupies a position representing machine-locked pod ecosystem leadership through at-home espresso platforms. These three anchors demonstrate how scale-driven players capture recurring revenue while functional specialists like Red Bull GmbH command premium positioning through caffeine-taurine synergies.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestle |
| Red Bull GmbH |
| Monster Energy Co. |
| Keurig Dr Pepper |
| Starbucks Corp. |
| AriZona Beverages USA LLC |
| Asahi Group Holdings Ltd. |
| Others |
Supply Flow & Price Mechanics
Flavor chemist concentration in Campinas, Brazil and Hamburg, Germany creates labor-cost differentials that widen pricing spreads between clean-label premium tiers and commodity-standard formulations. These specialist clusters command premium compensation for natural masking expertise, pushing multinational brands toward automated sweetener-blending platforms in lower-cost jurisdictions while maintaining premium positioning through European certification tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates nitrogen-infused cold-brew cans from conventional ready-to-drink coffee and value-positioned bottled tea. Price differentiation rests on EFSA novel food certification status and machine-locked pod subscription lock-in. Cost compression in the standard tier is intensifying because Arabica price volatility from Minas Gerais transmits through roasted input streams. Fitness-oriented consumers in Texas and California show least price sensitivity for post-workout functional stacks, while pantry-loading suburban buyers in emerging markets drive economy-tier volume.
Supply Chain Analysis
Deposit-return flows through Hamburg and Munich infrastructure accelerate glass bottle refurbishment cycles for premium iced coffee channels. Raw material sourcing draws from Brazilian Arabica highlands, Chinese pharmaceutical-grade synthetic caffeine processors, and Indian chemical manufacturing clusters. Single-source dependency risk concentrates in Asian synthetic caffeine production. Distribution runs through Coca-Cola and PepsiCo fountain cooler networks in the United States and Japan, with auto-replenishment platforms bypassing traditional retail slotting in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EFSA's stringent novel food approval pathways in Europe and FSSAI's recently opened caffeine notification framework in India, where compliance costs diverge by an order of magnitude.
For Market Incumbents: Anchor machine-locked pod ecosystem loyalty through smart appliance connectivity standards in Japan and South Korea before challenger brands capture auto-replenishment platform share. Defend against energy drink pure-plays by accelerating backward integration into Brazilian Arabica supply to buffer weather-driven price shocks. Prioritize certification investment for EFSA-compliant adaptogen formulations to maintain European market access. For New Entrants and Emerging Players: Convenience store cooler placement partnerships in Maharashtra and Karnataka tier-2 cities offer the most penetrable white-space for citrus-flavored energy drink trial. Target microbiome-positioned cold-brew probiotic formulations in premium German refrigerated channels where gut-health positioning remains underdeveloped. Pursue direct-to-subscription models tied to machine-locked capsules to bypass incumbent slotting fee advantages. For Investors and Strategic Acquirers: Beverage conglomerates with fountain infrastructure are the most active acquirer in this space, seeking regional flavor portfolios and pod system technology. Long-term viability hinges on capturing recurring revenue through subscription lock-in rather than transactional retail volume. Watch for FSSAI enforcement tightening in India as the signal indicating when geographic-arbitrage windows may compress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Arabica Supply | Captive sourcing from Minas Gerais buffers weather-driven cost volatility for roasted inputs. |
| EFSA Novel Food Certification Investment | Adaptogen safety dossiers unlock premium positioning in European functional beverage channels. |
| Smart Appliance Connectivity Partnership | METI-standard auto-replenishment platforms capture habitual consumption in Japanese urban households. |
| Mono-Material Can Redesign | German and French extended producer responsibility compliance avoids capital deployment penalties. |
| Tier-2 City Convenience Channel Expansion | FSSAI-compliant energy drink distribution accesses underpenetrated Indian growth corridors. |
Methodological Framework
Direct dialogue with brand managers at multinational beverage conglomerates, category buyers at convenience store chains, flavor chemists in Brazilian and German specialist clusters, and regulatory affairs leads navigating EFSA and FSSAI frameworks grounded the qualitative foundation. Secondary validation drew from FDA added sugars labeling filings, EFSA novel food approval databases, FSSAI caffeine notification records, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Bottom-up segmentation analysis across product type, flavor profile, packaging material, and distribution channel dimensions combined with regional regulatory cluster differentiation throughout the forecast period. CAGRs were derived from trend-line extrapolation of historical consumption patterns adjusted for pod system penetration curves and reformulation investment cycles. Arabica futures price volatility and synthetic caffeine sourcing concentration served as key forecast sensitivity inputs.
Revisions become necessary when EFSA tightens adaptogen approval thresholds, FSSAI accelerates enforcement in Indian tier-2 markets, or Brazilian weather patterns disrupt highland growing regions more severely than historical baselines assume. Practitioners should monitor regulatory filing velocity in Europe, convenience channel cooler placement fees in emerging markets, and specialty coffee futures spreads for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Juices Market
Beverages
Vegetable Juice Market
Beverages
Juice Market
Beverages
Beverages Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Relaxation Beverages Market
Beverages
Herb Infused Water Market
Beverages
Double Valve Moka Pots Market
Beverages
Adaptogenic Beverages Market
Beverages
Maple Water Market
Beverages
South America Ready to Drink Beverages Market
Beverages
Packaged Cactus Water Market
Beverages
Bottled Water Processing Market
Beverages
Drinking Water Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Nitro-Infused Beverages Market