
 Celery Juice Market | 2026-2036
Celery Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Celery Juice Market Analysis
Glass packaging is shifting toward recycled polyethylene terephthalate in value-tier celery juice offerings, cutting unit costs without sacrificing shelf visibility. Bolthouse Farms leverages its captive agricultural supply chain to anchor pricing power across conventional retail channels. Pressed Juicery specializes in small-batch cold-pressed formats that dominate premium health food stores. Suja Life extends its organic certification pipeline into celery-specific SKUs, competing on clean-label positioning rather than volume scale.
Celery juice consists of hydraulically extracted liquid from Apium graveolens stalks, typically yielding 95-97% water with residual chlorophyll, electrolytes, and volatile phthalides; manufacturers cold-press at pressures exceeding 2,000 PSI to minimize oxidative degradation and preserve enzymatic activity for functional beverage applications. Fresh celery juice occupies the largest volume position due to immediate consumption patterns in juice bars and cafés, while organic celery juice commands disproportionate margin contribution through certification premiums and supply scarcity. Cold-pressed celery juice grows fastest among processing technologies as consumers associate minimal heat treatment with nutrient retention, and health food stores capture expanding shelf space for this format against supermarket consolidation of conventional pasteurized lines.
The FDA governs juice hazard analysis and critical control point compliance, mandating pathogen reduction treatments that cold-pressed producers navigate through validated alternative processes; organic certification under USDA National Organic Program rules shapes ingredient sourcing and label claims across domestic supply chains. California Department of Public Health enforces additional state-level juice manufacturing standards that elevate operational thresholds for West Coast producers. Stakeholders must monitor evolving enforcement discretion on raw juice safety protocols while building traceable farm-to-bottle documentation that satisfies both retail buyer requirements and liability exposure management.
Market Dynamics
Cold-pressed extraction technology is compressing conventional pasteurization timelines as manufacturers race to preserve enzymatic activity while meeting FDA pathogen reduction mandates. This technical tension between nutrient retention and safety compliance is restructuring capital allocation across processing facilities.
Growth Catalysts
- USDA National Organic Program certification:Clean-label premiums in health food stores pull supply toward traceable farm partnerships. Retail buyers now mandate organic pipeline documentation as a condition of shelf placement.
- Direct-to-consumer subscription infrastructure:Recurring revenue models in the United States reduce customer acquisition costs and stabilize demand forecasting for cold-pressed producers.
- Electrolyte positioning in functional beverages:Athletes and wellness consumers treat celery juice as a natural hydration alternative, expanding consumption occasions beyond morning rituals.
Market Restraints
- Perishable input volatility:Celery stalk prices fluctuate with California water allocation cycles, squeezing margin predictability for West Coast processors.
- Single-region supply concentration:Domestic production clusters in California's Central Valley, exposing national distribution to climate disruption and freight cost spikes.
- FDA HACCP compliance friction:Alternative pathogen validation processes for cold-pressed lines extend time-to-market and elevate insurance premiums versus pasteurized competitors.
Strategic Opportunities
- Canada functional beverage underpenetration:Health Canada regulatory alignment with FDA standards enables cross-border SKU replication with minimal reformulation costs.
- Recycled PET packaging conversion:rPET bottle adoption cuts unit economics for value-tier offerings while maintaining retail visibility against glass competitors.
- High-pressure processing hybridization:Combining cold-press extraction with HPP pathogen control bridges the nutrient-safety divide for conventional retail expansion.
Industry Challenges
- Juice safety protocol talent scarcity:Facilities struggle to hire HACCP-certified operators capable of managing non-thermal validation workflows at commercial scale.
- Farm-to-bottle traceability system integration:ERP upgrades required for organic certification documentation strain mid-tier processor IT budgets and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Celery Juice Market |
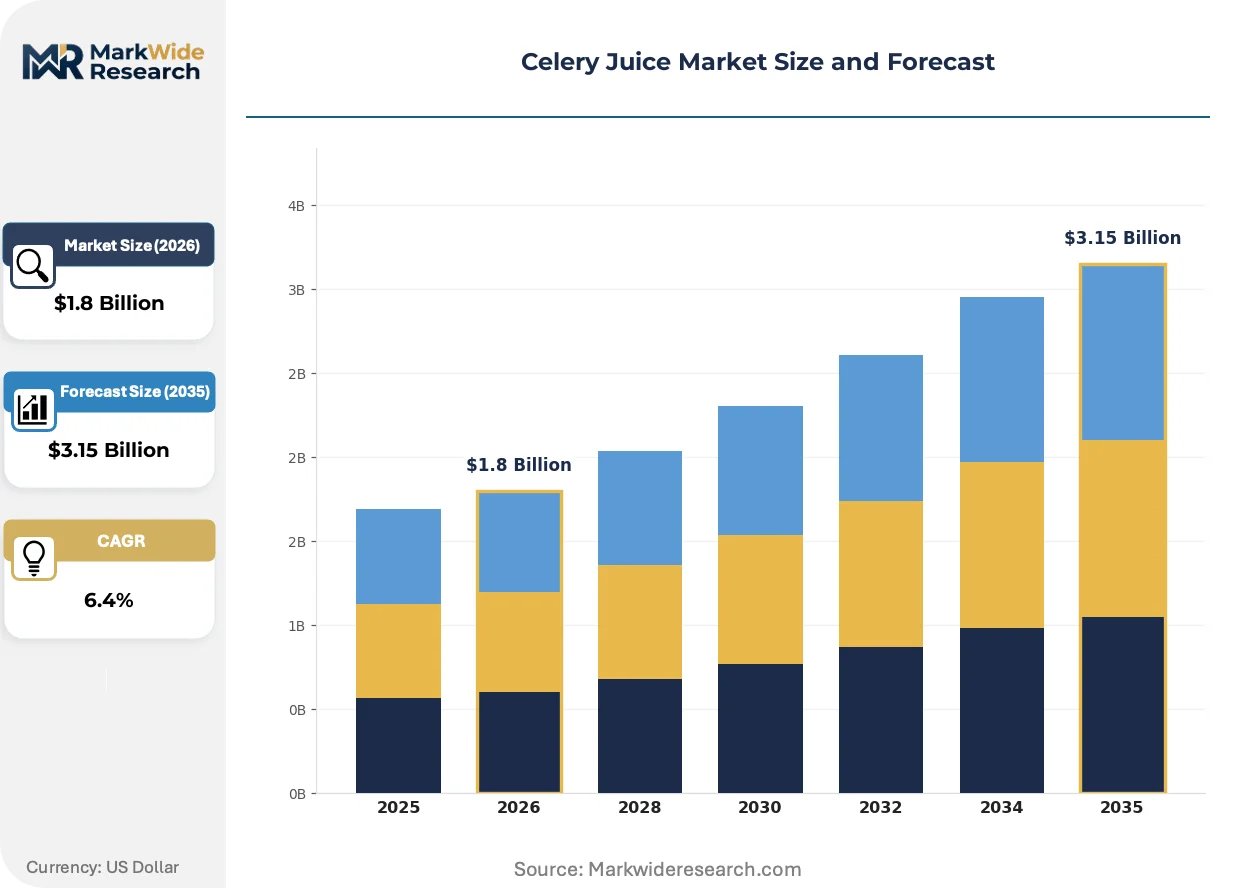
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Celery Juice, Organic Celery Juice, Cold-Pressed Celery Juice, Powdered Celery Juice Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores Packaging Type: Glass Bottles, Plastic Bottles, Tetra Packs, Cans Consumer Segment: Health Enthusiasts, Fitness Buffs, General Consumers, Wellness Seekers |
| Companies Covered | KeVita, Evolution Fresh, Bolthouse Farms, Lakewood Juices, KAUAI JUICE CO., Pressed Juicery, Naked Juice, Barakat Quality Plus, Suja Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Celery Juice Market Emerging Trajectories
Processing technology and packaging material science are converging to extend shelf stability without sacrificing the raw positioning that commands premium pricing. These shifts are compressing the traditional trade-off between accessibility and authenticity.
High-pressure processing equipment is integrating into cold-pressed celery juice lines to deliver log-reduction pathogen control without thermal degradation. Premium health food retailers are adopting HPP-treated SKUs to expand distribution radius beyond the 3-5 day window of purely raw products. This hybrid approach is integrating conventional supermarket channels previously closed to untreated juice, compressing the channel exclusivity that defined early market structure.
California Department of Public Health manufacturing standards are elevating operational thresholds for West Coast producers beyond federal FDA baselines. Out-of-state competitors face compliance cost disadvantages when entering California distribution. Cold-pressed specialists are responding by concentrating West Coast capacity and treating California as a separate regulatory jurisdiction within domestic strategy.
Subscription-based replenishment models are displacing single-unit café and juice bar purchases among core wellness consumers. Direct-to-consumer platforms capture recurring revenue while bypassing retail slotting fee structures. This channel rotation is most visible in United States metropolitan markets where delivery logistics density supports economically viable cold-chain fulfillment.
Celery Juice Market Segmentation
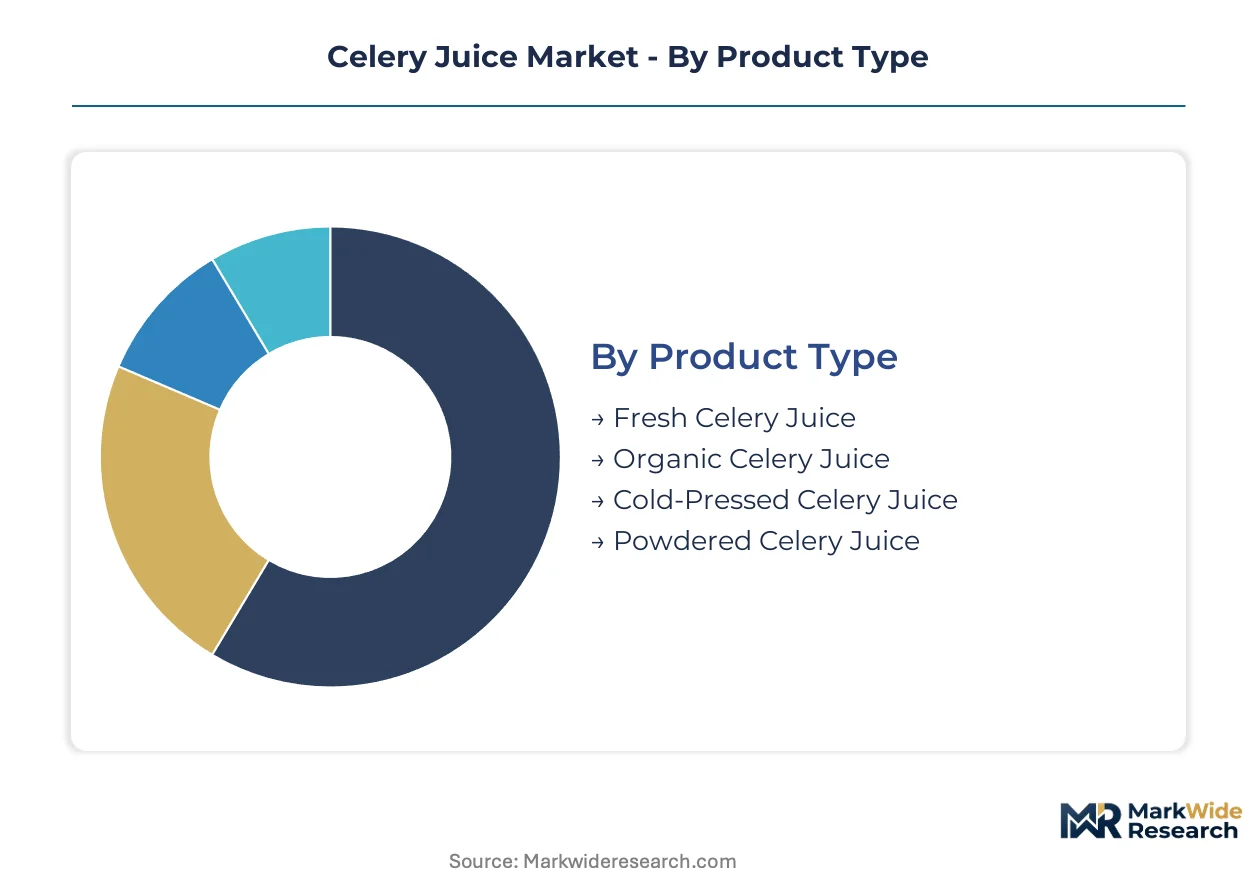
Celery juice segmentation reflects divergent processing philosophies and channel economics. Product format determines margin structure, while distribution choice dictates regulatory exposure and cold-chain investment.
Product Type:
Cold-pressed extraction at pressures exceeding 2,000 PSI defines the technical frontier, separating nutrient-retentive formats from conventional pasteurized lines.
- Fresh Celery Juice:Unprocessed liquid extracted within 24-48 hours of consumption, dominating juice bar and café immediate-serve channels. Demand clusters in United States metropolitan markets where cold-chain logistics density supports same-day fulfillment, though spoilage windows constrain inventory depth.
- Cold-Pressed Celery Juice:Hydraulically extracted under high pressure without heat application, preserving enzymatic activity and volatile phthalides for functional beverage positioning. United States health food stores allocate expanding shelf space to this format, driven by wellness consumer willingness to pay certification premiums for minimal processing.
- Organic Celery Juice:USDA National Organic Program certified supply chains command scarcity premiums through traceable farm partnerships.
- Powdered Celery Juice:Spray-dried or freeze-dried concentrates target portability and extended shelf stability for travel and emergency stockpiling.
Mature deployment sits with Fresh Celery Juice in foodservice channels. Newer deployment is concentrated in Cold-Pressed Celery Juice as retail buyers mandate non-thermal processing documentation.
Distribution Channel:
Channel selection determines pathogen compliance pathway and working capital intensity for celery juice producers.
- Health Food Stores:Specialty retailers like Whole Foods Market and Sprouts Farmers Market enforce supplier documentation standards exceeding conventional supermarket baselines. United States coastal metropolitan markets show highest SKU density, with buyers prioritizing organic certification and HACCP-validated alternative processing over volume scale.
- Online Retail:Direct-to-consumer subscription platforms bypass slotting fees and capture recurring revenue through replenishment algorithms. Cold-chain fulfillment density in United States urban corridors enables economically viable same-day or next-day delivery of raw and HPP-treated formats.
- Supermarkets:Consolidated retail chains favor pasteurized or HPP-treated lines with extended shelf stability for centralized distribution.
- Specialty Stores:Independent grocers and wellness boutiques curate small-batch regional producers for differentiation.
Established volume flows through Supermarket centralized procurement. Steepest expansion trajectory belongs to Online Retail subscription infrastructure.
Packaging Type:
Material science trade-offs between shelf visibility, unit economics, and sustainability credentials shape packaging selection.
- Glass Bottles:Premium positioning vehicle preserving taste neutrality and supporting premium price points in health food channels. United States West Coast producers favor glass for organic and cold-pressed lines despite freight cost penalties, responding to consumer perception of chemical migration risks from plastic alternatives.
- Recycled PET Bottles:rPET adoption cuts unit costs for value-tier offerings while maintaining retail shelf presence against glass competitors.
- Tetra Packs:Aseptic carton formats enable ambient distribution for pasteurized celery juice in conventional retail.
- Cans:Aluminum formats target convenience store and on-premise consumption occasions with single-serve portability.
Glass dominates premium organic and cold-pressed positioning. rPET conversion is accelerating fastest among cost-optimized conventional lines.
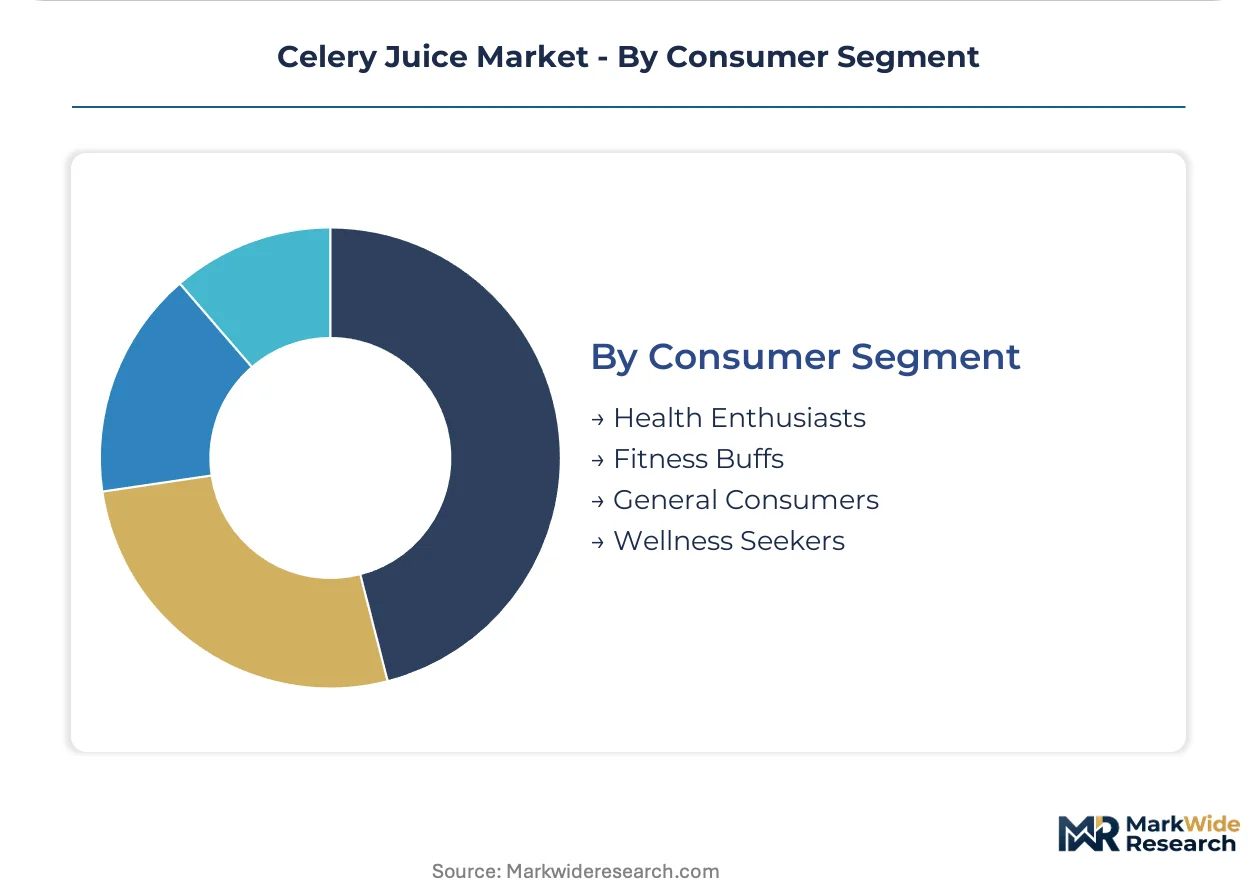
Consumer Segment:
Usage occasion and wellness sophistication divide celery juice purchasers into distinct demand profiles with divergent price elasticities.
- Health Enthusiasts:Daily ritual adopters consuming celery juice for digestive health and inflammation management, typically purchasing through subscription or high-frequency health food store visits. United States urban centers show highest per-capita consumption, with this segment driving demand for organic certification and processing transparency.
- Fitness Buffs:Athletes and gym-goers treating celery juice as natural electrolyte replacement for hydration and recovery. United States metropolitan fitness culture supports premium pricing for cold-pressed formats positioned against sports drinks.
- Wellness Seekers:Intermittent adopters responding to social media health trends with trial purchases.
- General Consumers:Price-sensitive occasional purchasers in conventional retail channels.
Health Enthusiasts anchor recurring revenue models. Fitness Buffs represent the fastest-climbing consumption occasion expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wellness consumers in the United States drive the majority of cold-pressed celery juice adoption, with metropolitan health food store density and subscription infrastructure creating demand concentration unmatched elsewhere.
United States
FDA HACCP mandates shape processing investments as California-based producers navigate stricter state-level juice manufacturing standards. Los Angeles and San Francisco health food corridors anchor cold-pressed capacity, with Bolthouse Farms leveraging Central Valley agricultural proximity for supply chain control.
Canada
Health Canada regulatory alignment with FDA standards enables cross-border SKU replication with minimal reformulation costs. Toronto and Vancouver metropolitan markets show expanding health food store penetration, though subscription cold-chain fulfillment density lags US urban corridors.
Germany
EFSA clean-label enforcement elevates organic certification requirements for imported functional beverages. Berlin and Hamburg wellness retail clusters drive demand for minimally processed juices, with domestic producers investing in high-pressure processing equipment to bridge nutrient-safety divides.
United Kingdom
Food Standards Agency novel food guidance shapes import compliance for cold-pressed formats. London's premium juice bar density supports immediate-serve fresh celery juice demand, while national supermarket chains favor HPP-treated lines for extended distribution radius.
Australia
FSANZ food safety standards mandate pathogen reduction treatments that cold-pressed producers address through validated alternative processes. Sydney and Melbourne health food retail expansion supports organic celery juice premium positioning, with traceable farm partnerships becoming shelf placement prerequisites.
Celery Juice Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive agricultural supply chains conferring pricing power in conventional retail while small-batch cold-press operations dominate premium health food channels. The vendor base organizes around three archetypes: vertically integrated agricultural processors, specialist cold-pressed juice boutiques, and diversified functional beverage conglomerates. Competitive moves concentrate on organic certification pipeline expansion and direct-to-consumer subscription infrastructure buildout.
Among diversified beverage conglomerates, KeVita and Naked Juice exemplify scale-driven market presence, while Bolthouse Farms anchors the agricultural-processor archetype with upstream supply control. Pressed Juicery occupies the specialist boutique tier, representing small-batch positioning against mass-market alternatives.
| Leading Market Players |
|---|
| KeVita |
| Evolution Fresh |
| Bolthouse Farms |
| Lakewood Juices |
| KAUAI JUICE CO. |
| Pressed Juicery |
| Naked Juice |
| Barakat Quality Plus |
| Suja Life |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up cold-pressed specialists have consolidated West Coast processing capacity, tightening supply discipline and anchoring premium pricing power against conventional pasteurized competitors. Their captive distribution networks and subscription revenue bases insulate margin structures from spot-market celery price volatility.
Pricing Analysis
Volume concentrates in conventional pasteurized lines while margins accrue disproportionately to cold-pressed and organic tiers. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic from conventional from private-label offerings. Price differentiation rests on certification grade and cold-chain delivery cost. Cost compression in value-tier rPET formats is intensifying because supermarket buyers are consolidating procurement. General Consumers in conventional retail channels exhibit highest price sensitivity, while Health Enthusiasts in subscription models show lowest elasticity.
Supply Chain Analysis
Regional distribution centers in California's Central Valley anchor hub-and-spoke patterns radiating to United States metropolitan markets. Celery cultivation concentrates in California, with secondary sourcing from Florida and Mexico for seasonal gap coverage. Raw material dependencies include agricultural water allocations, cold-press hydraulic equipment, and HPP validation services. Single-region supply concentration exposes national distribution to climate disruption and freight cost spikes. Distribution runs through direct-to-consumer subscription platforms for premium tiers and conventional retail consolidation for value offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Celery juice supply is structurally constrained by California water allocation cycles and HACCP-certified operator scarcity, bottlenecks that prop pricing power for incumbent processors with validated alternative treatment workflows.
For Market Incumbents: Extend organic certification pipeline depth through traceable farm partnerships to defend shelf placement at Whole Foods Market and Sprouts Farmers Market against emerging contract manufacturers. Add high-pressure processing capacity in California to bridge nutrient-safety divides for conventional retail expansion. Vertical integration into captive agricultural supply buffers margin pressure from input price volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription infrastructure in Canada, where Health Canada regulatory alignment enables cross-border SKU replication with minimal reformulation costs and fulfillment density gaps persist against United States urban corridors. Target Toronto and Vancouver metropolitan markets with HPP-treated hybrid formats that satisfy FSANZ-equivalent safety standards while preserving raw positioning claims. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier cold-pressed specialists with validated HACCP alternative processes and existing organic certification pipelines in California. Long-term viability hinges on subscription revenue share and West Coast cold-chain infrastructure ownership. Watch California Department of Public Health enforcement discretion on raw juice safety protocols as the inflection signal for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Pipeline Expansion | USDA National Organic Program documentation satisfies retail buyer mandates at specialty grocers. |
| High-Pressure Processing Hybridization | HPP integration bridges nutrient-safety divides for conventional supermarket channel entry. |
| Direct-to-Consumer Subscription Buildout | Recurring revenue models bypass slotting fees and stabilize demand forecasting. |
| Recycled PET Packaging Conversion | rPET adoption cuts unit economics for value-tier offerings while maintaining shelf visibility. |
| Cross-Border Canada Expansion | Health Canada regulatory alignment enables SKU replication with minimal reformulation costs. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving cold-pressed juice facility operators, health food store category buyers, organic certification auditors, HACCP validation specialists, and agricultural supply coordinators. FDA juice HACCP guidance documents, California Department of Public Health manufacturing standards, USDA National Organic Program certification records, and Nielsen retail audit data provided triangulation anchors. Bottom-up volume modeling and top-down value reconciliation converged on segment-level estimates.
Granularity-level modeling deployed product type, distribution channel, packaging format, and consumer segment dimensions at the country level across the analysis window. CAGRs derived from historical trajectory fitting and forward-looking demand elasticity assessment. Forecast inputs incorporated celery stalk price volatility patterns, cold-chain logistics density indices, and organic certification penetration curves.
California water allocation disruption, FDA enforcement discretion shifts on raw juice protocols, and HPP equipment capacity constraints are the dominant revision risks to projection outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market