

Enzyme-Enabled Cold-Brew Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Enzyme-Enabled Cold-Brew Concentrates Market Insights
Subscription-based replenishment models for liquid extracts is shifting how roasters lock in recurring revenue. Nestlé leverages its direct-to-consumer infrastructure to anchor cold-brew concentrate subscriptions across North American markets. JDE Peet's sustains European café partnerships through private-label enzymatic concentrate supply. Starbucks differentiates via in-house enzyme protocols that control extraction consistency at scale.
Enzyme-enabled cold-brew concentrates employ pectinase and cellulase enzymes to hydrolyze coffee cell walls during low-temperature extraction, yielding higher soluble solids at reduced steeping times while preserving volatile aromatic compounds. Liquid extracts command the widest distribution footprint among product type segments, though powder concentrates attract freight-cost-sensitive buyers in distant markets. Gourmet retail and food service applications generate the strongest margin pools, as enzymatic processing justifies price premiums over conventional cold-brew methods. Ultrafiltration and microfiltration technologies dominate current production lines, while nanoencapsulation remains an emerging frontier for shelf-stable flavor delivery.
FDA food additive regulations and USDA organic certification standards govern enzyme sourcing and labeling claims in the United States, directly influencing product development timelines and market access costs. EFSA enzyme safety evaluations under EU food law shape formulation choices for European exporters. Stakeholders must monitor evolving enzyme approval pathways and clean-label certification requirements as regulatory divergence between jurisdictions intensifies sourcing complexity.
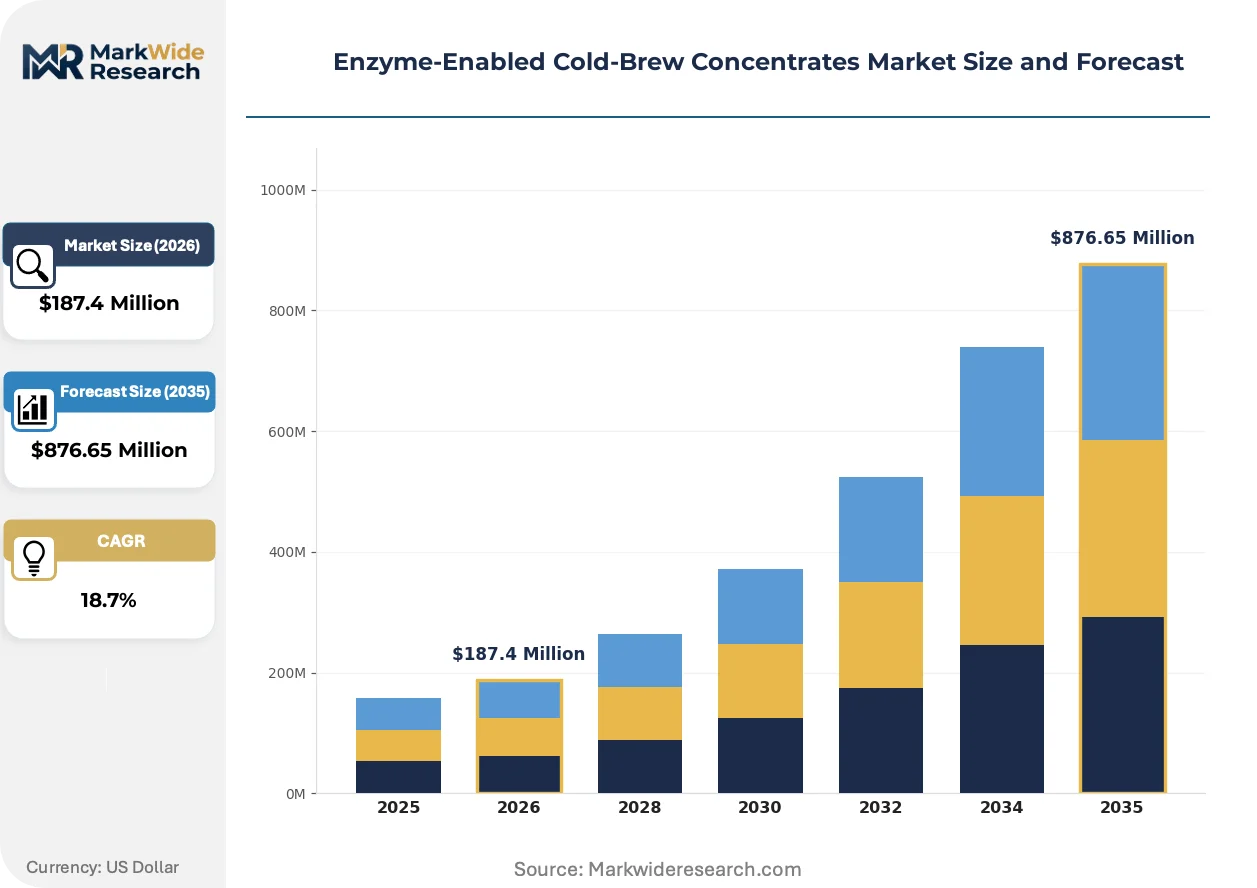
Market Dynamics
Enzymatic hydrolysis patents filed by European flavor houses are compressing extraction timelines while fragmenting competitive barriers across supply tiers. This technology diffusion is forcing incumbent roasters to defend proprietary protocols against commoditized enzyme platforms.
Growth Catalysts
- Specialty café channel expansion:Ready-to-drink formats in high-footfall urban locations drive concentrate throughput. Premium positioning in United States coastal corridors validates enzymatic price premiums.
- Clean-label certification alignment:USDA organic standards for enzyme sourcing accelerate product development pipelines. Certification-compliant suppliers gain preferred-access status with North American retail buyers.
- Pectinase-cellulase co-enzyme systems:Dual-enzyme protocols reduce steeping duration by half while preserving volatile aromatics. Roasters adopt these systems to compress production cycles without capital-intensive equipment swaps.
Market Restraints
- Enzyme input cost volatility:Fungal-derived pectinase prices fluctuate with agricultural substrate availability. Concentrate margins compress when enzyme procurement spikes coincide with coffee bean price rallies.
- European supply concentration:Three flavor houses control majority enzymatic hydrolysis patent estates. Licensing terms constrain formulation flexibility for mid-tier roasters outside preferred partner networks.
- Refrigerated distribution infrastructure gaps:Cold-chain requirements for liquid concentrates limit penetration into ambient-storage retail channels. Powder formats sacrifice sensory fidelity to bypass this constraint.
Strategic Opportunities
- Southeast Asian café culture expansion:Vietnam and Indonesia underpenetrated for enzymatic cold-brew relative to roast-and-ground consumption. Early entrants establish supply relationships with regional dairy-alternative chains.
- Nanoencapsulation convergence:Flavor stabilization technology intersects with enzymatic extraction to enable ambient-stable concentrates. Shelf-life extension opens convenience-store and vending-machine channels previously inaccessible.
- Subscription infrastructure redeployment:Direct-to-consumer replenishment models proven in North America transplant to European markets. Automated reorder algorithms reduce customer acquisition costs for liquid extract formats.
Industry Challenges
- Enzyme application engineering talent scarcity:Food biochemists with coffee-specific hydrolysis experience command premium compensation. Roasters compete with pharmaceutical and biofuel sectors for this skill pool.
- FDA-EFSA regulatory divergence:Divergent enzyme safety evaluation timelines force dual-track submission strategies. Product launch synchronization across Atlantic markets stretches to eighteen months.
- Ultrafiltration membrane fouling:Protein-polysaccharide complexes from enzymatic processing accelerate equipment degradation. Maintenance cycles compress operational uptime in high-throughput facilities.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzyme-Enabled Cold-Brew Concentrates Market Trends and Innovations
Modular enzyme dosing systems are disaggregating extraction control from fixed-capital infrastructure. This shift permits smaller roasters to access precision hydrolysis without proprietary bioreactor investments.
Immobilized enzyme cartridge technology is modularizing batch-scale enzymatic extraction. Regional roasting cooperatives adopt these plug-in systems to pilot concentrate production without dedicated clean-room facilities. The technology compresses minimum viable scale thresholds from industrial volumes to craft-roaster batches.
EFSA's updated guidance on food enzyme safety evaluations under EU food law tightens toxicological data requirements for cellulase variants. Reformulation timelines extend as suppliers commission new studies. European exporters to United States markets face asynchronous approval statuses that complicate unified product portfolios.
Café procurement committees now specify enzymatic processing credentials in cold-brew concentrate tenders. Food-service distributors respond by certifying supplier enzyme provenance through third-party audit chains. This specification intensity concentrates most visibly in United States Pacific Northwest and Northeast urban clusters where specialty coffee density supports premium sourcing.
Enzyme-Enabled Cold-Brew Concentrates Market Segmentation
Segmentation in the enzyme-enabled cold-brew concentrates market reveals how enzymatic processing creates distinct value tiers across physical formats and channel applications. Each category reflects divergent capital requirements, shelf-life engineering, and customer procurement behaviors that shape competitive positioning.
Product Type:
Customization spans from high-velocity liquid formats requiring cold-chain integrity to ambient-stable powders trading sensory fidelity for distribution reach.
- Liquid Extracts:Enzyme-hydrolyzed coffee solubles suspended in aqueous solution retain volatile aromatic compounds through ultrafiltration stabilization. Demand concentrates in United States coastal café corridors where refrigerated distribution infrastructure supports premium positioning. Cold-chain dependency limits penetration into convenience retail channels lacking temperature-controlled storage.
- Powder Concentrates:Spray-dried or freeze-dried enzymatic extracts reduce freight costs and extend shelf stability through moisture exclusion. Southeast Asian markets with fragmented cold-chain networks favor this format for dairy-alternative chain partnerships. Sensory degradation relative to liquid formats constrains gourmet retail placement.
- Ready-to-Drink:Pre-diluted enzymatic concentrates in single-serve packaging.
- Organic Blends:USDA-certified enzyme-sourced formulations commanding certification premiums.
- Single-Origin Mixes:Terroir-specific enzymatic extractions highlighting regional coffee provenance.
Leading the category by volume: Liquid Extracts. Growing fastest: Powder Concentrates.
Application:
Margin concentration follows channel sophistication, with food-service and gourmet retail capturing enzymatic price premiums while beverage manufacturing prioritizes throughput scale.
- Cafés:High-footfall urban locations deploy ready-to-drink enzymatic formats for rapid throughput without on-site extraction equipment. United States specialty coffee density in Pacific Northwest and Northeast urban clusters validates premium procurement specifications.
- Food Service:Institutional and contract catering operations leverage enzymatic concentrates for consistency at volume. Private-label supply agreements with European flavor houses dominate this channel through enzymatic hydrolysis patent licensing.
- Beverage Manufacturing:Ingredient-scale procurement for ready-to-drink product lines.
- Gourmet Retail:Premium shelf placement targeting home-barista consumers.
- Home Brewing:Direct-to-consumer subscription replenishment models.
Highest margin capture: Food Service. Steepest expansion trajectory: Home Brewing.
Technology:
Patent concentration among European flavor houses fragments access to enzymatic hydrolysis while filtration technologies commoditize across equipment suppliers.
- Enzymatic Hydrolysis:Pectinase-cellulase co-enzyme systems hydrolyze coffee cell walls to accelerate soluble solids extraction at reduced temperatures. Three European flavor houses control majority patent estates, constraining formulation flexibility for unlicensed roasters.
- Ultrafiltration:Membrane separation removes suspended solids and microorganisms post-extraction. Protein-polysaccharide complexes from enzymatic processing accelerate membrane fouling, compressing maintenance cycles in high-throughput facilities.
- Cold Extraction:Traditional low-temperature steeping without enzymatic acceleration.
- Microfiltration:Pore-size-based clarification for extended shelf stability.
- Nanoencapsulation:Emerging flavor stabilization enabling ambient-stable concentrate delivery.
Most widely deployed: Ultrafiltration. Technology with highest R&D investment: Nanoencapsulation.
End User:
Procurement sophistication varies from vertically integrated roasters with in-house enzyme protocols to distributor-dependent boutique brands.
- Specialty Coffee Roasters:Vertically integrated operations develop proprietary enzymatic extraction protocols to differentiate consistency at scale. Starbucks exemplifies this tier through captive enzyme application engineering.
- Boutique Beverage Brands:Smaller-scale operators license enzymatic technology through equipment partnerships or toll manufacturing arrangements. Modular immobilized enzyme cartridges reduce minimum viable scale thresholds for this segment.
- Artisan Distributors:Curated portfolio operators sourcing enzymatic concentrates for regional café networks.
- Premium Retail Chains:Grocery and specialty store buyers specifying clean-label enzyme provenance.
Deepest vertical integration: Specialty Coffee Roasters. Fastest-growing procurement volume: Boutique Beverage Brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in European flavor houses while consumption concentrates in United States specialty coffee corridors. This geographic split shapes cross-border licensing flows and cold-chain investment priorities. Regulatory divergence between FDA and EFSA enzyme approval pathways complicates unified product portfolios.
United States
Specialty café density in Pacific Northwest and Northeast urban corridors validates premium enzymatic pricing. FDA food additive regulations govern pectinase and cellulase sourcing for concentrate formulations. Seattle and Portland roasting clusters drive specification intensity for clean-label enzyme provenance in food-service tenders.
Germany
Private-label enzymatic concentrate supply dominates European food-service channel procurement. EFSA enzyme safety evaluations under EU food law shape reformulation timelines for cellulase variants. Bavaria-based flavor houses control majority patent estates for hydrolysis protocols, constraining unlicensed roaster access.
Vietnam
Dairy-alternative chain partnerships create entry points for powder concentrate formats in underpenetrated café markets. The country's national food safety authority regulates enzyme imports for beverage processing applications. Ho Chi Minh City roasting cooperatives pilot modular immobilized enzyme cartridges for regional concentrate production.
United Kingdom
Direct-to-consumer subscription infrastructure supports liquid extract replenishment models in London and Southeast England. EFSA guidance on food enzyme toxicological data requirements extends product development cycles for exporters. Manchester and Birmingham distribution hubs manage cold-chain logistics for refrigerated concentrate formats.
Indonesia
Fragmented cold-chain networks favor powder concentrate adoption in Jakarta and Surabaya café markets. The national food and drug regulator oversees enzyme safety standards for imported coffee processing inputs. Bali specialty tourism corridors generate niche demand for single-origin enzymatic extractions.
Enzyme-Enabled Cold-Brew Concentrates Market Competitive Landscape
Top-tier vendors anchor enzymatic hydrolysis patent licensing, while mid-tier roasters rely on equipment partnerships and toll manufacturing arrangements. The competitive structure stratifies across captive enzyme protocol developers, licensed technology adopters, and private-label supply specialists. Two strategic archetypes dominate: vertically integrated specialty roasters with in-house application engineering, and boutique brands leveraging modular cartridge systems. Technology licensing and geographic expansion represent the dominant competitive moves as European patent holders extend reach into Southeast Asian markets.
Among Swiss-anchored conglomerates, Nestlé exemplifies the direct-to-consumer infrastructure archetype through subscription-based replenishment models. Dutch-registered JDE Peet's occupies a position within the private-label supply tier for European café partnerships. Seattle-based Starbucks anchors the vertically integrated specialty roaster segment through captive enzyme protocols. These three entities represent distinct strategic postures without implying specific market share or operational metrics.
| Leading Market Players |
|---|
| Nestlé |
| The J.M. Smucker Company |
| Keurig Dr Pepper |
| Starbucks |
| JDE Peet's |
| JAB Holding Company |
| Califia Farms |
| La Colombe Coffee Roasters |
| Wandering Bear Coffee |
| Others |
Pricing and Supply Chain Analysis
Food biochemists with coffee-specific hydrolysis experience concentrate in Germany and the United States Pacific Northwest, commanding premium compensation that widens pricing-tier spreads between enzymatic and conventional cold-brew concentrates. Labor-cost differentials between these talent clusters and emerging production regions in Southeast Asia feed directly into tiered pricing structures.
Pricing Analysis
Margin tightening in liquid extract tiers reflects cold-chain logistics costs and enzyme input volatility. Three-tier pricing structure across premium organic-certified, standard enzymatic, and economy conventional levels separates buyer segments by certification grade and volume commitment. Pricing pressure intensifies in powder concentrate tiers as freight-cost-sensitive buyers in distant markets trade sensory fidelity for distribution reach. Food-service distributors exhibit highest price sensitivity due to contract-based procurement, while specialty cafés in United States coastal corridors demonstrate lowest sensitivity to enzymatic premiums.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Vietnam anchor hub-and-spoke cold-chain networks for liquid extracts. Enzyme sourcing draws from fungal fermentation facilities in Bavaria and agricultural substrate suppliers in the American Midwest. Single-source vulnerability concentrates in European flavor house patent estates controlling pectinase-cellulase licensing. Distribution runs through temperature-controlled logistics partnerships for refrigerated formats, while ambient-stable powder concentrates bypass cold-chain infrastructure through spray-dried production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme application engineering talent scarcity props pricing power for licensed suppliers, constraining capacity expansion timelines across all tiers.
For Market Incumbents: Extend patent licensing reach into Southeast Asian markets before regional roasters develop indigenous enzyme protocols. Defend proprietary extraction consistency through captive pectinase-cellulase co-enzyme system investments. Capacity addition in Vietnam and Indonesia counters emerging entrant toll-manufacturing arrangements. For New Entrants and Emerging Players: Dairy-alternative chain partnerships in Vietnam and Indonesia offer the most penetrable white-space targets for powder concentrate formats. Modular immobilized enzyme cartridges reduce capital barriers to pilot-scale production. Direct-to-consumer subscription algorithms proven in North American markets transplant to European replenishment infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with boutique beverage brands leveraging modular cartridge systems given nanoencapsulation convergence enabling ambient-stable delivery. Long-term viability frames around flavor stabilization technology intersecting with enzymatic extraction. Acquisition target archetype: regional roasting cooperatives with established café network relationships. Signal to watch: EFSA-FDA enzyme approval synchronization timelines compressing or extending product launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Licensing Expansion | European flavor houses extend enzymatic hydrolysis access to Southeast Asian roasters through regional partnerships. |
| Modular Cartridge Deployment | Immobilized enzyme systems reduce minimum viable scale thresholds for craft-roaster concentrate production. |
| Nanoencapsulation R&D Investment | Flavor stabilization technology opens convenience-store and vending-machine channels previously inaccessible to liquid formats. |
| Direct-to-Consumer Infrastructure | Subscription replenishment models transplant from North American to European liquid extract markets. |
| Clean-Label Certification Program | USDA organic enzyme sourcing standards accelerate preferred-access status with North American retail buyers. |
Research Methodology
Document review covered enzyme safety evaluation filings with FDA and EFSA, patent estates held by European flavor houses, and café procurement tender specifications, complemented by interviews with specialty coffee roasters, food-service distribution procurement leads, and enzyme application engineering specialists. Secondary validation drew from customs records of enzyme imports, cold-chain logistics operator disclosures, and specialty coffee retail audit data. Bottom-up volume modeling triangulated against top-down market sizing across product type and application segments.
Segment-level outputs across liquid extracts, powder concentrates, ready-to-drink formats, and organic blends were generated through the projection horizon using enzymatic processing adoption curves and café channel expansion rates. CAGRs derived from regression analysis of historical concentrate throughput against specialty coffee density metrics and enzyme cost trajectories. Modeled inputs included pectinase price volatility indices, refrigerated distribution infrastructure penetration rates, and clean-label certification compliance timelines.
Caveats apply where EFSA-FDA regulatory divergence, fungal substrate agricultural supply shocks, or nanoencapsulation technology maturation delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.