
 Cold Pressed Juice Market | 2026-2036
Cold Pressed Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Pressed Juice Market Analysis
The FDA's Juice HACCP regulation is recalibrating pasteurization exemptions and microbial testing thresholds for raw juice producers. Suja Life LLC leverages cold-chain logistics to sustain shelf-stable distribution across conventional retail. Pressed Juicery Inc. anchors its growth through company-owned storefronts in dense metropolitan zones. Bolthouse Farms competes via captive agricultural supply and economies of scale in bottle production.
Cold pressed juice refers to beverages extracted through hydraulic pressing at ambient temperatures below conventional centrifugal methods, preserving heat-sensitive enzymes and vitamin C content while yielding lower oxidation rates. The process employs pressures exceeding thousands of pounds per square inch without thermal pasteurization, serving wellness-oriented consumers seeking minimally processed nutrition. Fruits dominate volume throughput due to established orchard supply chains and consumer palatability, though superfood blends command premium positioning through functional ingredient density. Bottles retain structural preference in supermarkets and health stores for brand visibility and resealability, while pouches gain traction in online channels for shipping efficiency and reduced breakage.
The USDA Organic seal and FDA Juice HACCP framework govern labeling claims and pathogen control, with the former restricting synthetic inputs across orchards and the latter mandating hazard analysis for unpasteurized products. These standards elevate compliance costs for entrants while rewarding certified incumbents with retail placement advantages. Stakeholders must monitor evolving state-level raw milk and juice statutes that could expand or constrain direct-to-consumer distribution pathways.
Market Dynamics
The FDA's updated Juice HACCP regulations are forcing producers to recalibrate pasteurization exemptions and microbial testing thresholds, compressing margins for small-batch operators while advantaging certified incumbents with retail placement leverage.
Growth Catalysts
- Urban wellness corridors:Health-conscious consumers in dense metropolitan zones anchor volume throughput, with California and New York metropolitan corridors driving premium positioning for functional blends.
- USDA Organic certification:The seal restricts synthetic inputs across orchards, rewarding certified producers with shelf-space advantages in conventional retail channels.
- Cold-chain logistics advancement:Temperature-controlled distribution networks now sustain shelf-stable delivery without thermal degradation, extending reach beyond local production radii.
Market Restraints
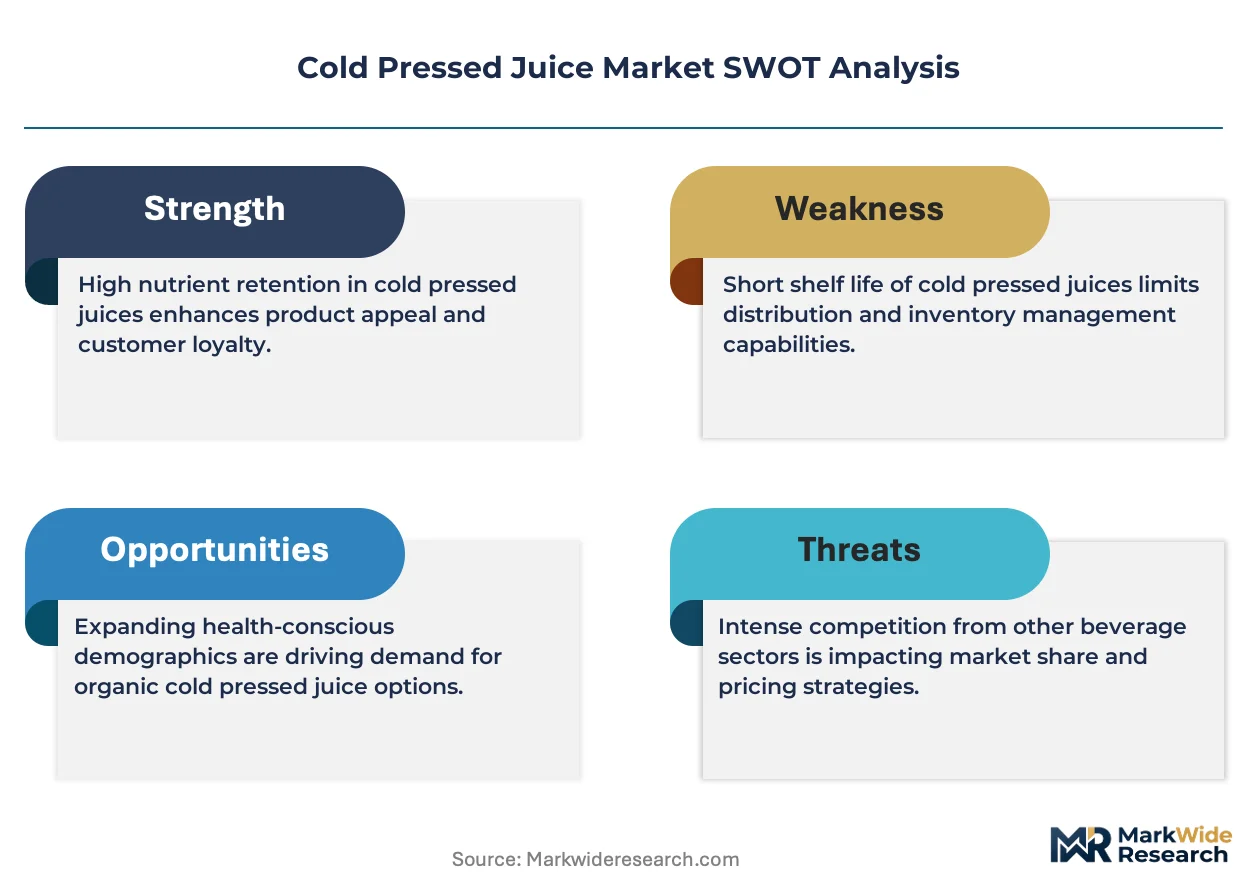
- Perishability constraints:Unpasteurized cold-pressed juice carries pathogen risks that compress distribution windows and elevate spoilage rates versus thermally treated alternatives.
- Input cost volatility:Organic fruit procurement fluctuates with orchard yield cycles and climate stress, squeezing margin stability for non-vertically integrated producers.
- Regulatory compliance burden:FDA Juice HACCP hazard analysis mandates elevate fixed costs for microbial testing and documentation, creating barriers to entry for small-scale entrants.
Strategic Opportunities
- Pouch format expansion:Flexible packaging gains traction in direct-to-consumer channels for shipping efficiency and breakage reduction versus glass bottles.
- Superfood ingredient density:Functional blends incorporating adaptogens and botanicals command premium pricing from wellness-oriented buyers seeking targeted nutrition outcomes.
- State-level raw juice statutes:Evolving legislation in select jurisdictions could expand direct-to-consumer distribution pathways outside conventional retail gatekeepers.
Industry Challenges
- Food safety certification timelines:FDA Juice HACCP compliance requires extended validation periods for new production facilities, delaying market entry.
- Cold-chain infrastructure capex:Refrigerated storage and transport equipment demands substantial capital deployment, constraining expansion velocity for undercapitalized operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Pressed Juice Market |
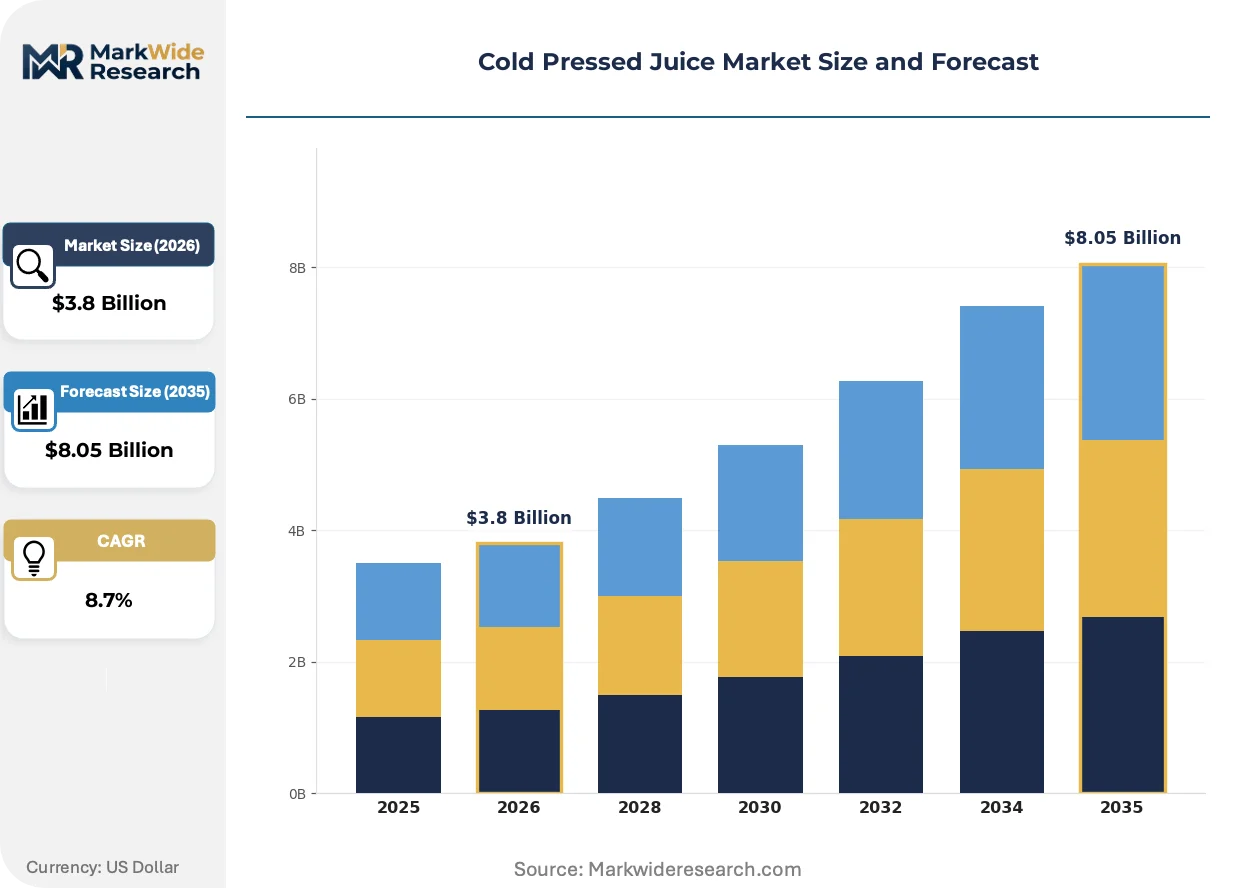
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Mixes, Superfood Packaging Type: Bottles, Tetra Packs, Pouches, Jars Distribution Channel: Online, Supermarkets, Health Stores, Cafes End User: Fitness Enthusiasts, Health Conscious Consumers, Restaurants, Caterers |
| Companies Covered | Evolution Fresh, Juice Generation, Pressed Juicery Inc., Bolthouse Farms, Juice Press LLC, Suja Life LLC, The Hain Celestial Group Inc., Village Juicery Inc., PepsiCo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Pressed Juice Market Emerging Trajectories
Hydraulic pressing technology and packaging format evolution are compressing traditional centrifugal methods while regulatory scrutiny intensifies pathogen control protocols across production networks.
High-pressure processing equipment is consolidating shelf-life extension capabilities without thermal degradation, preserving heat-sensitive enzymes and vitamin C content. Wellness-oriented retailers and conventional supermarkets alike are adopting HPP-treated lines to bridge the gap between raw positioning and safety compliance. This technology is consolidating the competitive set by enabling regional producers to compete with national brands on distribution reach.
The FDA's Juice HACCP regulation is recalibrating microbial testing thresholds and documentation requirements for unpasteurized products. Producers must now maintain hazard analysis critical control point plans with validated pathogen reduction steps. Small-batch operators in California and New York face the steepest compliance curve, with many pursuing voluntary HPP treatment to preempt regulatory exposure.
Subscription-based replenishment models are displacing single-unit impulse purchases in urban wellness corridors. Direct-to-consumer channels leverage pouch formats and insulated shipping to bypass conventional retail gatekeepers, capturing recurring revenue from high-frequency consumers. This pattern concentrates in dense metropolitan zones where delivery density optimizes logistics economics.
Cold Pressed Juice Market Segmentation
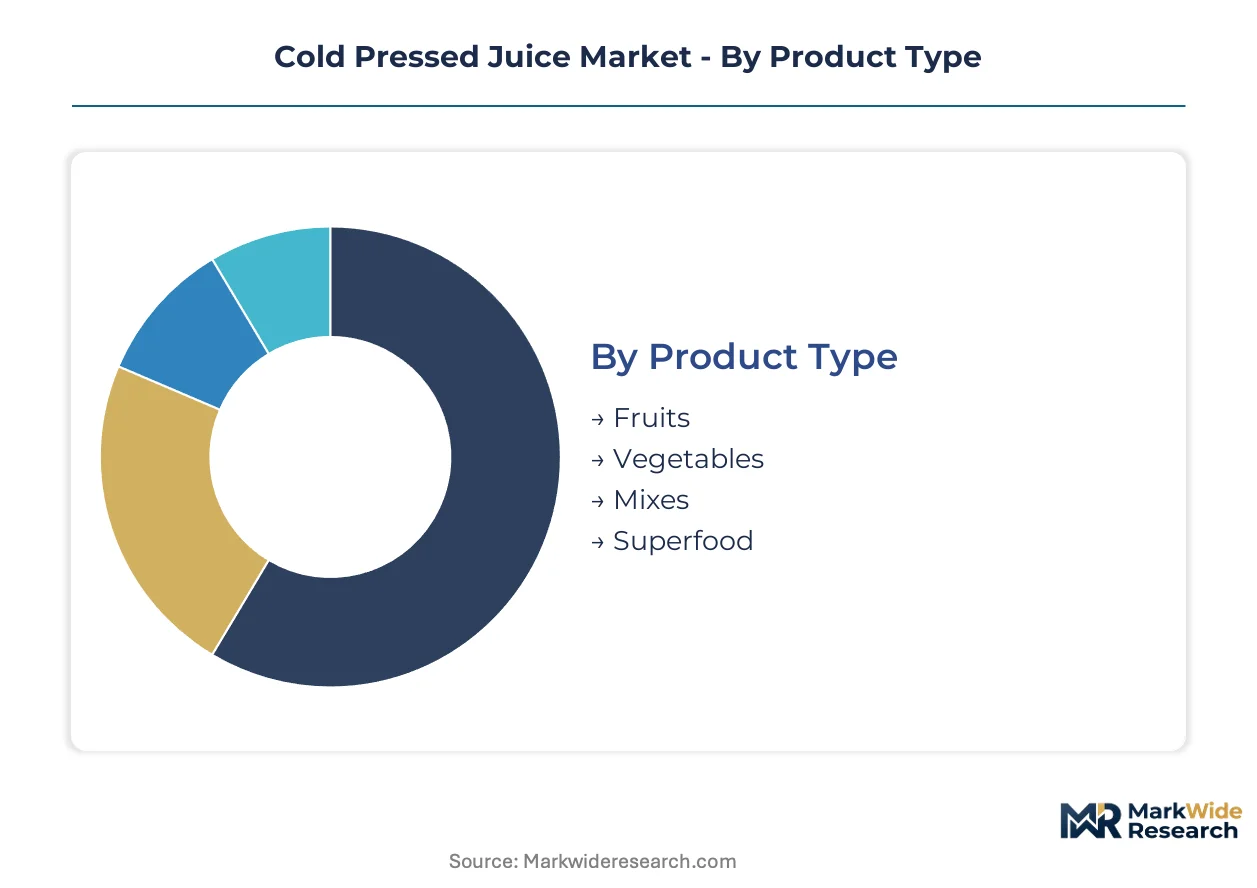
Cold pressed juice segmentation reveals divergent margin profiles across packaging formats and channel strategies. Product type and end-user alignment determine procurement scale, while distribution channel selection dictates cold-chain infrastructure requirements and spoilage risk exposure.
Product Type:
Standalone single-ingredient juices serve baseline nutrition needs, while embedded functional blends integrate adaptogens and botanicals for targeted wellness outcomes.
- Fruits:Apple, orange, and citrus varietals dominate volume throughput due to established orchard supply chains and broad consumer palatability. California and Florida metropolitan corridors anchor procurement scale for conventional retail placement.
- Vegetables:Leafy green and root vegetable formulations carry higher per-unit input costs and narrower taste acceptance, concentrating demand in wellness-oriented urban enclaves where health-conscious consumers prioritize functional density over flavor accessibility.
- Mixes:Multi-ingredient blends balance palatability with perceived nutritional comprehensiveness, serving fitness enthusiasts seeking convenient post-workout recovery solutions.
- Superfood:Açaí, turmeric, and spirulina-infused lines command premium positioning through ingredient scarcity and functional ingredient density.
Volume placements concentrate in Fruits; the faster expansion belongs to Superfood.
Packaging Type:
Cost tier stratification separates premium glass presentations from economy-focused flexible formats, with mid-tier Tetra Packs bridging retail visibility and logistics efficiency.
- Bottles:Glass and premium PET containers dominate supermarket and health store shelves, offering brand visibility and resealability that supports premium pricing in conventional retail channels.
- Pouches:Flexible film packaging reduces shipping weight and breakage rates, gaining traction in direct-to-consumer subscription models where insulated delivery logistics optimize recurring revenue economics.
- Tetra Packs:Aseptic carton technology extends ambient shelf stability without refrigeration, enabling broader distribution reach for value-positioned lines.
- Jars:Wide-mouth glass containers serve foodservice and bulk retail formats where portion flexibility and visual ingredient appeal drive purchase decisions.
Supermarket visibility favors Bottles; the steepest expansion trajectory belongs to Pouches.
Distribution Channel:
Geographic concentration patterns separate dense urban corridor strategies from dispersed suburban coverage models.
- Supermarkets:Conventional grocery chains provide mass-market access with refrigerated case placement requirements, demanding consistent supply reliability and promotional slotting fees.
- Online:Direct-to-consumer platforms bypass retail gatekeepers through subscription replenishment models, concentrating in New York and California metropolitan zones where delivery density minimizes per-unit logistics costs.
- Health Stores:Specialty retailers like Whole Foods and regional cooperatives prioritize USDA Organic certification and local sourcing narratives, rewarding compliant producers with preferred placement.
- Cafes:Foodservice integration captures impulse consumption occasions, with grab-and-go refrigerated displays in urban wellness corridors driving single-unit velocity.
Volume concentrates in Supermarkets; the fastest share gains belong to Online.
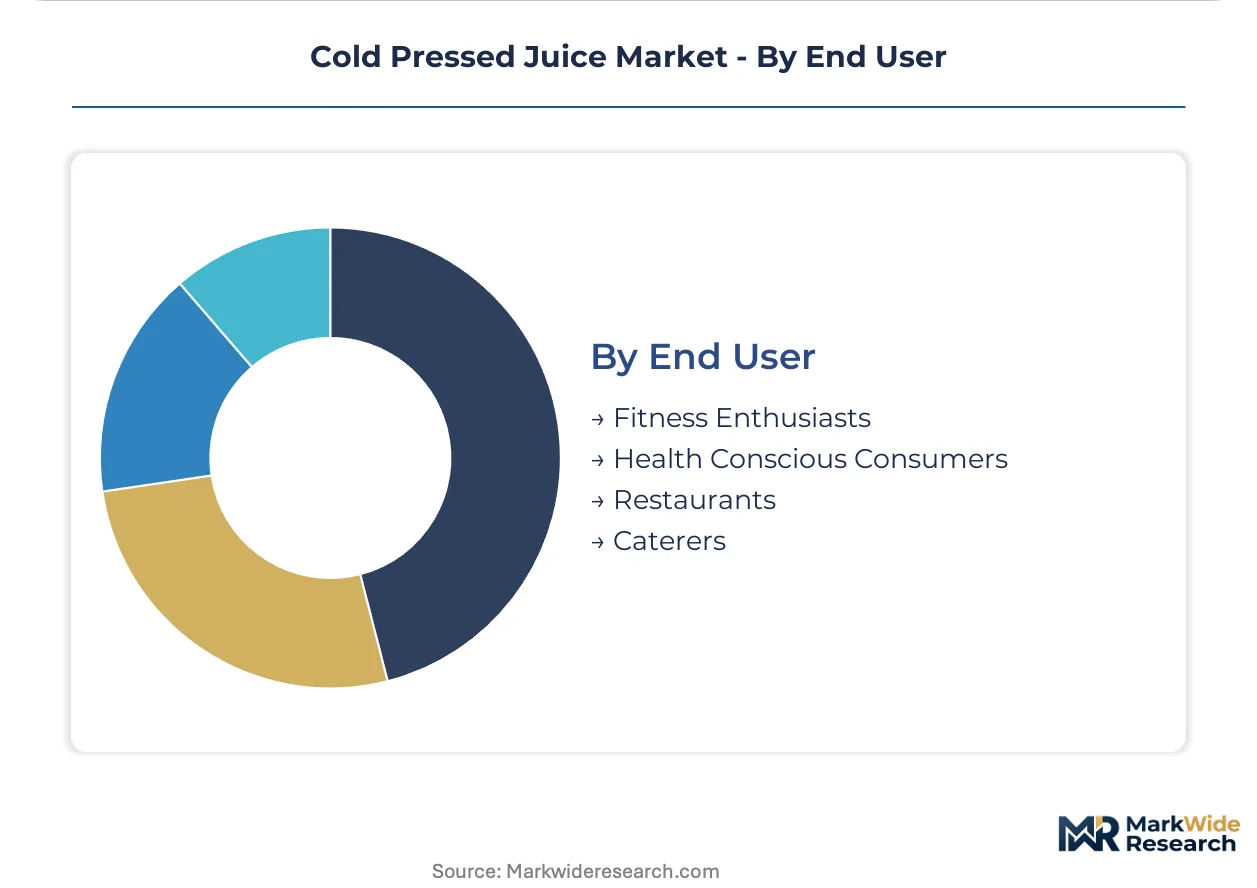
End User:
Customer type segmentation separates individual consumption patterns from institutional procurement scale, with divergent quality thresholds and price sensitivity profiles.
- Health Conscious Consumers:Urban professionals and wellness-focused households drive premium positioning for organic-certified and functional ingredient lines, prioritizing clean label claims over unit economics.
- Fitness Enthusiasts:Gym-goers and athletic populations seek post-workout recovery formulations with electrolyte density and protein integration, anchoring demand for performance-positioned blends.
- Restaurants:Fine dining and fast-casual operators incorporate cold pressed juice into beverage programs and culinary applications, requiring consistent quality specifications and foodservice-grade packaging.
- Caterers:Event and corporate dining services demand bulk formats with extended holding stability, prioritizing cost efficiency and logistical reliability over brand differentiation.
Revenue concentration sits with Health Conscious Consumers; the expansion is climbing the fastest for Fitness Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Enterprise Zone program and New York's START-UP NY initiative concentrate cold-pressed juice production through tax abatements and logistics infrastructure support. Metropolitan wellness corridors in these states anchor North American demand density.
United States
Urban health-conscious consumers in Los Angeles and New York City drive premium positioning for organic-certified blends. The FDA's Juice HACCP regulation mandates hazard analysis and microbial testing for unpasteurized products, elevating compliance costs for small-batch operators. California's Central Valley agricultural belt supplies orchard-scale fruit inputs to processing facilities in the San Francisco Bay Area.
Canada
Toronto and Vancouver metropolitan zones sustain demand for functional superfood formulations through fitness-oriented retail channels. Health Canada's food safety framework requires pathogen control plans for raw juice distribution, paralleling US regulatory stringency. The Okanagan Valley in British Columbia anchors domestic fruit procurement for regional bottling operations.
Germany
Berlin and Munich wellness consumers prioritize clean-label organic positioning over conventional juice alternatives. The EU's organic certification framework and Germany's national food safety authority enforce strict residue limits across orchard supply chains. The Bavarian agricultural region supplies apple and pear inputs to processing clusters in southern Germany.
United Kingdom
London's dense metropolitan corridor concentrates subscription-based direct-to-consumer demand for premium cold-pressed lines. The Food Standards Agency mandates microbiological standards for unpasteurized beverages sold through retail channels. The Kent orchard belt in southeastern England supplies seasonal citrus and apple inputs to bottling facilities serving the capital.
Australia
Sydney and Melbourne health-conscious professionals sustain premium pricing for functional ingredient blends through specialty retail and cafe channels. Food Standards Australia New Zealand enforces microbiological criteria for raw juice products, requiring validated pathogen reduction steps. The Riverina region in New South Wales anchors domestic fruit procurement scale for eastern seaboard processing.
Cold Pressed Juice Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: beverage multinationals leveraging captive distribution, regional specialists controlling local supply chains, and direct-to-consumer platforms scaling subscription economics. Consolidation pressures favor operators with cold-chain infrastructure and certified organic sourcing. Competitive moves concentrate on format diversification and geographic expansion through strategic partnerships.
Within the pure-play specialist tier, Suja Life LLC and Pressed Juicery Inc. exemplify contrasting channel strategies, while Bolthouse Farms represents diversified beverage conglomerate positioning. These companies anchor archetypal approaches to market participation without dictating uniform strategic outcomes across the competitive set.
| Leading Market Players |
|---|
| Evolution Fresh |
| Juice Generation |
| Pressed Juicery Inc. |
| Bolthouse Farms |
| Juice Press LLC |
| Suja Life LLC |
| The Hain Celestial Group Inc. |
| Village Juicery Inc. |
| PepsiCo Inc. |
| Others |
Supply Flow & Price Mechanics
USDA Organic certification ladders bifurcate the market into premium-positioned certified tiers and conventional alternatives, with this divergence manifesting in both procurement premiums paid to orchard operators and refrigerated logistics investments required to maintain cold-chain integrity from California's Central Valley to East Coast retail cases.
Pricing Analysis
Short lead-time premiums reward rapid fulfillment capabilities in subscription channels, while spot inventory discounts clear aging stock approaching expiration windows. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels stratifies the market. Price differentiation rests on certification grade and cold-chain infrastructure depth. Pricing pressure stems from input cost volatility in organic fruit procurement. Fitness enthusiasts exhibit lowest price sensitivity; institutional foodservice buyers show highest elasticity.
Supply Chain Analysis
Refrigerated freight costs consume disproportionate margin share for cross-country distribution, compressing economics for non-vertically integrated operators. Supply concentration anchors in California, Florida, and Mexico for citrus and orchard fruits. Raw material dependencies center on organic apple concentrate, cold-pressed orange juice, and açaí pulp imports. Single-source vulnerability from California drought cycles threatens procurement stability. Distribution runs through temperature-controlled third-party logistics networks terminating at retail distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Juice HACCP regulation constructs a formidable cost-of-compliance barrier, elevating fixed investment thresholds for microbial testing and documentation that insulate certified incumbents from undercapitalized challengers.
For Market Incumbents: Anchor shelf-stable positioning through high-pressure processing equipment deployment, preempting regulatory exposure while extending distribution radius. Bolster backward integration into orchard operations to buffer organic input cost volatility. Defensive priority centers on cold-chain infrastructure densification in Texas and Florida growth corridors. For New Entrants and Emerging Players: Pouch-format subscription platforms offer technology-first wedge into direct-to-consumer channels with minimal retail slotting fee exposure. Target fitness-oriented metropolitan zones in Austin and Denver with performance-positioned superfood blends. Go-to-market angle leverages insulated shipping partnerships to bypass conventional grocery gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing captive organic supply and HPP certification given FDA enforcement intensification. Long-term viability favors operators with decade-scale orchard contracts and multi-state cold-chain footprints. Acquisition target archetype: certified regional bottlers with underutilized capacity. Signal to watch: state-level raw juice statute liberalization enabling direct farm-to-consumer pathways.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Deployment | Extends shelf life without thermal degradation, satisfying FDA pathogen controls while preserving enzyme activity. |
| Backward Integration into Orchards | Captures margin from organic fruit procurement and insulates against California drought-driven supply shocks. |
| Pouch Format Expansion | Reduces shipping weight and breakage rates in direct-to-consumer channels, optimizing subscription economics. |
| Subscription Platform Launch | Captures recurring revenue from high-frequency urban consumers, bypassing supermarket promotional slotting fees. |
| State Regulatory Engagement | Positions operators to exploit evolving raw juice statutes that expand direct-to-consumer distribution pathways. |
Methodological Framework
Multi-period observation of FDA enforcement patterns, organic certification trajectories, and cold-chain infrastructure buildouts anchored the trend analysis, supplemented by interviews with juice production facility managers, organic orchard operators, refrigerated logistics coordinators, and supermarket category buyers. Secondary validation drew from FDA warning letter databases, USDA organic handler certificates, customs import records for açaí and tropical fruit concentrates, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spending estimates.
Input-output matrices mapped fruit procurement flows through processing stages to packaging and channel distribution across product type, packaging format, and end-user segmentation dimensions. CAGRs were derived from regression-based trending of historical volume trajectories adjusted for regulatory inflection points. Forecast inputs incorporated orchard yield cycle projections and HPP equipment penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended FDA enforcement moratoriums or catastrophic California drought scenarios. Projections assume continued organic certification premiums and stable cold-chain infrastructure investment levels. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Apple Juice Concentrate Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
BBQ Charcoal Market
Beverages
Middle East Energy Drinks Market
Beverages
South America Energy Drink Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Caffeinated Beverage Market
Beverages
Low Fat Drinks Market
Beverages
Semillon Market
Beverages
Hot Cocoa Mix Market
Beverages
Fusion Beverages Market
Beverages
Sparkling Water Market
Beverages
Botanical Infused Beverages Market
Beverages
North America Juices Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Packaged Coconut Water Market