
 Nutrient Dense Food Products Market | 2026-2036
Nutrient Dense Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Nutrient Dense Food Products Market Analytics
Plant-based proteins is broadening the raw-material base for nutrient dense formulations, reducing reliance on dairy isolates and soy concentrates. Arla Foods leverages its cooperative dairy infrastructure to sustain organic whey protein output across Northern Europe. Nestle S.A. competes through vertically controlled supply chains spanning Latin American superfood sourcing. Danone S.A. specializes in fermented plant proteins, occupying a distinct position in gut-health-aligned nutrition.
Nutrient dense food products deliver concentrated bioactive compounds, vitamins, minerals, and macronutrients within reduced caloric volumes, typically achieved through minimal processing of whole-food matrices such as sprouted grains, cold-pressed oils, and freeze-dried botanicals. Their primary commercial purpose centers on addressing micronutrient deficiencies in populations consuming calorie-sufficient yet nutritionally depleted diets. Superfoods and plant-based proteins command the largest current revenue pools, while sports nutrition applications within the application dimension represent the fastest-expanding channel as endurance athletes and CrossFit participants shift from synthetic supplements to whole-food recovery formats. Meal replacement formulations targeting weight watchers exhibit mature growth trajectories with compressed margins, whereas nutritional supplements for dietary management retain premium pricing through clinical-grade certification requirements.
FDA nutrition labeling rules and EFSA health claims frameworks mandate substantiated bioactive content declarations, forcing reformulation investments and third-party testing protocols. The EU Green Deal's Farm to Fork strategy and USDA organic certification standards further constrain permissible inputs while rewarding regenerative sourcing practices. Stakeholders must monitor evolving protein quality scoring methodologies and carbon-footprint disclosure mandates to preserve market access and consumer trust.
Market Dynamics
Clean-label mandates from FDA and EFSA are forcing reformulation investments across the nutrient dense food products sector, compressing margins for synthetic-additive-dependent producers while rewarding whole-food ingredient sourcing.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Regenerative sourcing requirements under this framework create preferential market access for certified organic producers across Northern European retail channels.
- Sports Nutrition End-Use Expansion:Endurance athletes and CrossFit participants are shifting recovery consumption from synthetic isolates toward whole-food matrices, expanding addressable volume in performance nutrition.
- Sprouted Grain Processing Technology:Enzymatic activation of grains is improving bioavailability metrics without synthetic fortification, satisfying clean-label procurement criteria in German and Japanese markets.
Market Restraints
- Organic Protein Input Cost Volatility:Weather-dependent yields of pea and hemp concentrates create margin pressure for formulators dependent on non-dairy protein bases.
- Supply Concentration in Latin American Superfoods:Quinoa, chia, and açaí sourcing clusters in Peru and Brazil expose processors to geopolitical and climate disruption risks.
- EFSA Health Claims Substantiation Requirements:Clinical trial documentation for bioactive compound declarations imposes six-figure validation costs that exclude mid-tier entrants.
Strategic Opportunities
- Fermented Plant Protein White Space:Gut-health-aligned positioning remains underexploited in North American retail relative to European penetration rates.
- Direct-to-Consumer Freeze-Dried Botanical Channels:Subscription models for personalized micronutrient stacks bypass conventional retail slotting fee barriers.
- USDA Organic Certification Tailwinds:Federal procurement preferences and school nutrition program eligibility expand institutional volume for certified producers.
Industry Challenges
- Third-Party Testing Talent Scarcity:ISO 17025-accredited laboratories capable of bioactive compound quantification face capacity constraints extending certification timelines.
- Cold-Press Equipment Capex Intensity:Low-temperature oil extraction infrastructure requires seven-figure capital deployment with extended depreciation schedules.
- Carbon-Footprint Disclosure Standardization Delays:Competing methodologies for Scope 3 agricultural emissions create audit complexity for multi-ingredient formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutrient Dense Food Products Market |
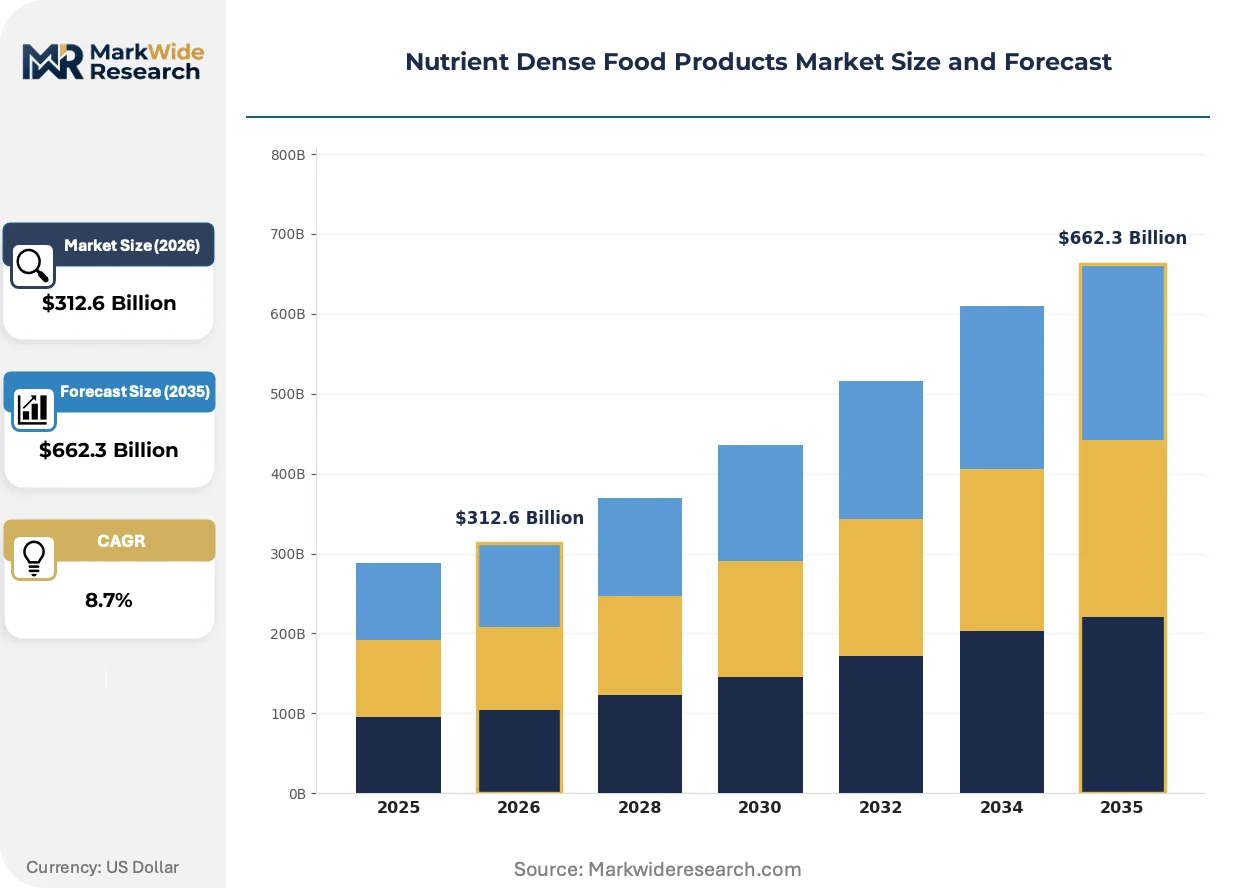
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superfoods, Energy Bars, Nutritional Supplements, Plant-Based Proteins Application: Health Supplements, Meal Replacement, Sports Nutrition, Dietary Management Consumer Type: Health-Conscious Individuals, Athletes, Vegetarian Consumers, Weight Watchers Ingredients: Organic Fruits, Whole Grains, Nuts, Legumes |
| Companies Covered | Arla Foods, Dairy Farmers of America, Nestle S.A., Lactalis International, Unilever Plc, Danone S.A., Fonterra Cooperative Group, Gujarat Cooperative Milk Marketing Federation, FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutrient Dense Food Products Market Evolving Landscape
Cellular agriculture and precision fermentation are disrupting conventional protein isolation, while regulatory carbon-accounting mandates and shifting procurement authority are restructuring competitive access across retail and institutional channels.
Precision fermentation of dairy-identical proteins is decentralizing whey production away from concentrated cooperative processing infrastructure. Boutique fitness brands and regional sports nutrition labels are adopting these inputs at triple-digit annual expansion rates. This technology is decentralizing supply chain control from legacy dairy conglomerates toward biotech-enabled formulators with laboratory-scale production capacity.
EFSA's evolving Novel Food catalog requirements are compressing approval timelines for bioactive botanical extracts. Manufacturers must now submit comprehensive toxicological dossiers prior to market entry, elevating compliance expenditure. Fermented plant protein categories face the steepest regulatory burden, with German and French regulators demanding batch-level stability documentation.
Certification-driven procurement authority is rotating toward institutional foodservice directors with mandated clean-label purchasing quotas. Conventional broadline distributors are losing share to specialized organic procurement cooperatives with direct farm relationships. This shift is most visible in United States K-12 nutrition programs and German hospital system catering contracts, where USDA Organic and EU Organic logos determine vendor eligibility.
Nutrient Dense Food Products Market Segmentation
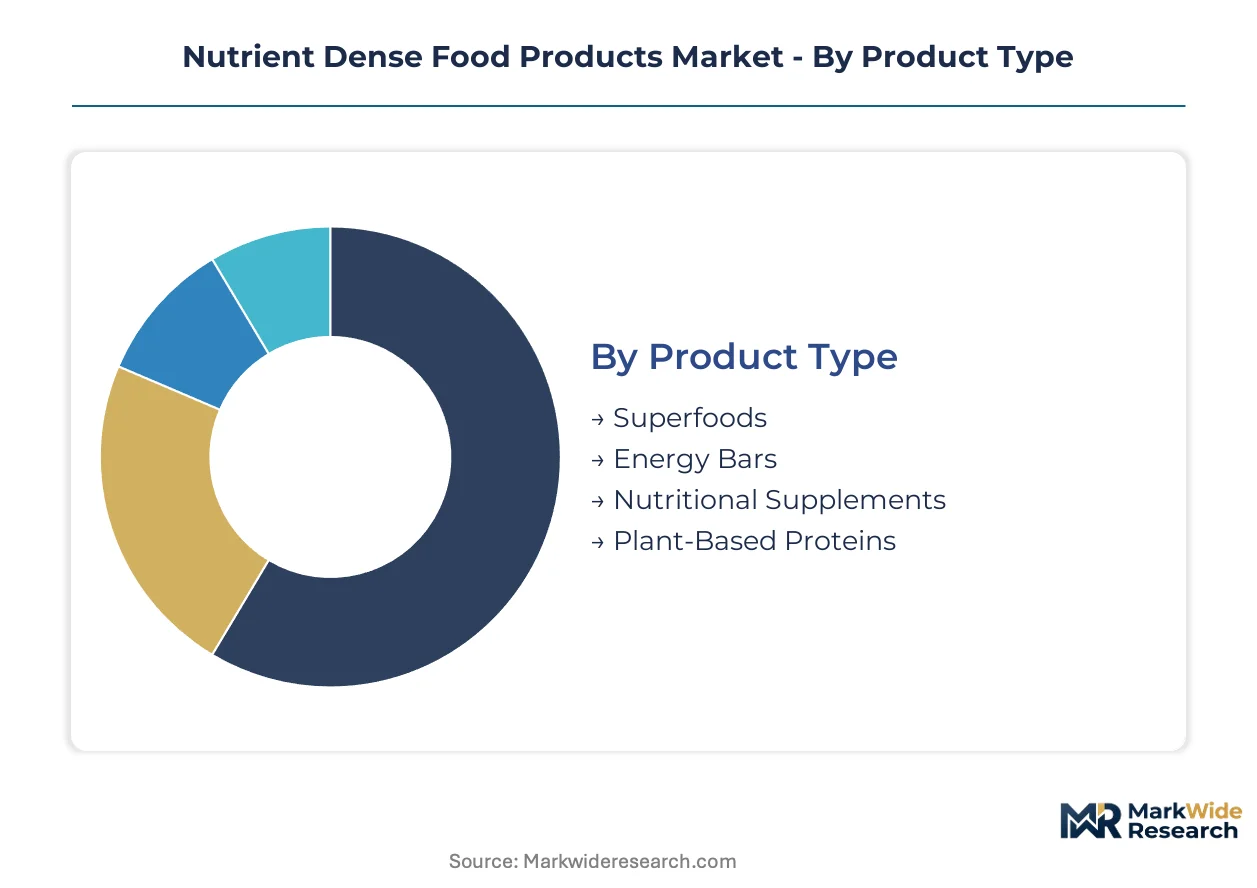
Segmentation in nutrient dense food products reveals distinct value capture mechanisms across formulation complexity and consumer sophistication tiers. Product architecture and application context determine margin structures, procurement channels, and regulatory exposure for each segment cluster.
Product Type:
Standardization dominates commodity formats while customization concentrates in functional ingredient blends and bioactive-optimized matrices.
- Superfoods:Freeze-dried botanicals and cold-pressed powders deliver concentrated phytonutrient loads with minimal processing. Demand clusters in German and Japanese markets where EFSA health claims frameworks and JAS organic standards enforce substantiated bioactive declarations. Clean-label procurement quotas in United States institutional foodservice accelerate adoption.
- Plant-Based Proteins:Fermented and enzymatically treated concentrates achieve amino acid completeness rivaling dairy isolates. Sports nutrition formulators in North America and Northern Europe source these inputs at expanding volume as endurance athletes reject synthetic recovery products. Carbon-footprint disclosure mandates favor pea and hemp bases over imported soy concentrates.
- Energy Bars:Composite formulations binding sprouted grains with nut butters and adaptogenic extracts.
- Nutritional Supplements:Clinical-grade capsules and tinctures targeting micronutrient deficiency correction.
Most installed capacity flows through Superfoods. Expansion is steepest in Plant-Based Proteins.
Application:
Volume scale inverses with margin intensity as meal replacement commoditizes while clinical-grade dietary management retains premium pricing.
- Sports Nutrition:Whole-food recovery formats displace synthetic isolates among CrossFit participants and endurance athletes. German and Japanese regulatory frameworks permit fewer health claims than FDA rules, compressing formulation flexibility in those markets. Boutique fitness brands drive triple-digit input growth for precision-fermented proteins.
- Dietary Management:Medical-grade formulations for diabetes, renal, and metabolic syndrome patients require clinical trial documentation and third-party bioactive quantification. EFSA substantiation costs exclude mid-tier entrants. Hospital system catering contracts in Germany and United States K-12 programs create institutional volume anchors.
- Health Supplements:Over-the-counter micronutrient stacks for general wellness maintenance.
- Meal Replacement:Calorie-controlled complete nutrition for weight management protocols.
Procurement authority concentrates in Sports Nutrition through direct-to-consumer channels. Regulatory burden peaks in Dietary Management.
Consumer Type:
Price sensitivity stratifies across motivation intensity, from discretionary wellness seekers to performance-committed athletes with non-negotiable nutritional protocols.
- Athletes:Professional and competitive amateur segments demand batch-tested, banned-substance-certified inputs with transparent supply chain documentation. German anti-doping regulations and NSF Certified for Sport protocols in United States create dual compliance thresholds. Subscription retention rates exceed general wellness categories by substantial margins.
- Health-Conscious Individuals:Urban professionals prioritizing functional nutrition over conventional staples. Japanese metropolitan markets show highest per-capita expenditure on sprouted grain and fermented plant protein categories. USDA Organic and JAS certification logos determine retail purchase decisions.
- Vegetarian Consumers:Ethical and environmental motivation clusters driving plant-exclusive formulation demand.
- Weight Watchers:Calorie-restricted meal replacement users with compressed margin tolerance.
Athletes command premium pricing tiers. Health-Conscious Individuals represent the broadest addressable base.
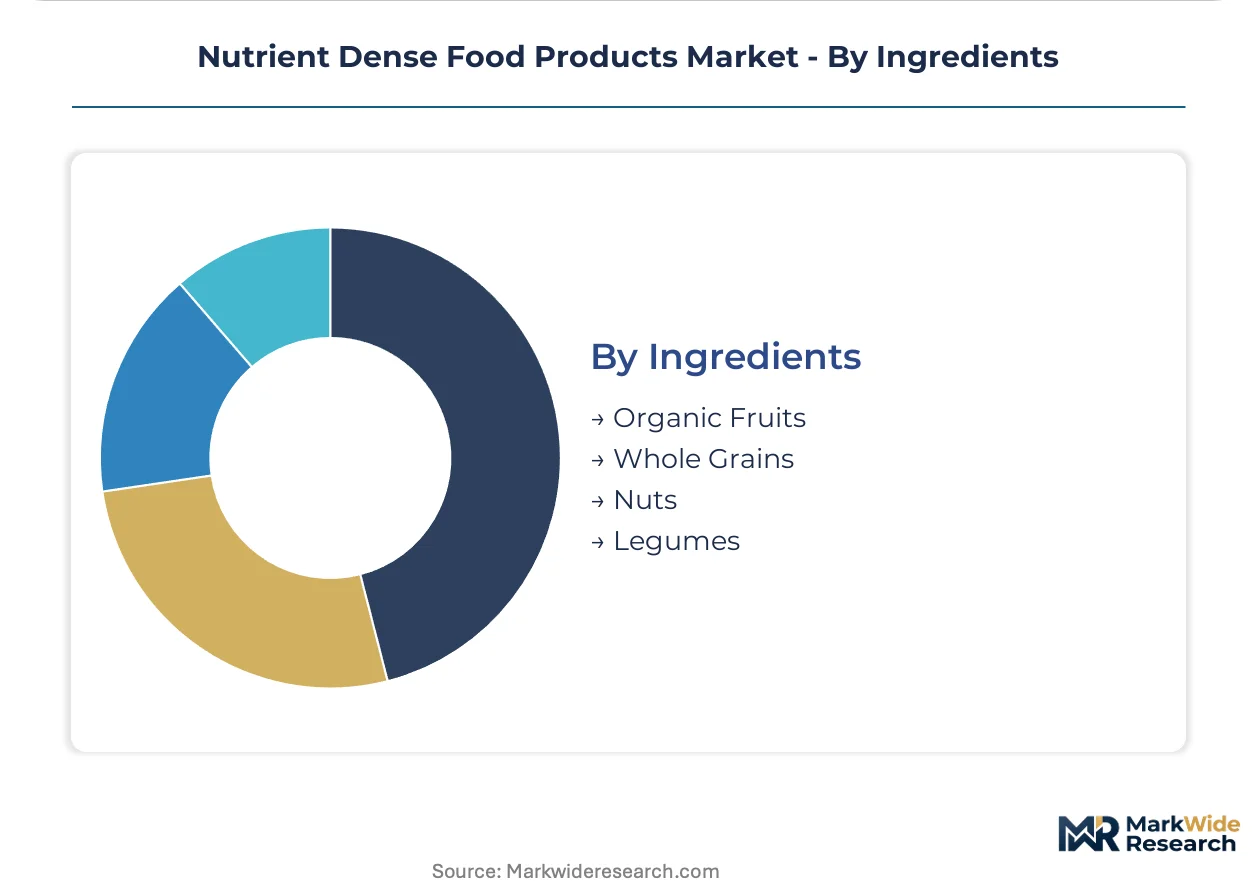
Ingredients:
Supply concentration risk varies by agricultural geography and climate dependency of cultivation zones.
- Organic Fruits:Freeze-dried berries and tropical concentrates from Latin American sourcing clusters. Peruvian and Brazilian açaí and camu camu exports face geopolitical and weather disruption exposure. EFSA Novel Food catalog requirements impose toxicological dossier burdens on new botanical introductions.
- Whole Grains:Sprouted wheat, quinoa, and amaranth processed through enzymatic activation technology. German milling infrastructure leads European capacity for bioavailability-optimized grain inputs. EU Green Deal Farm to Fork regenerative sourcing requirements favor domestic European suppliers.
- Nuts:Almond, cashew, and macadamia bases for protein fortification and textural binding.
- Legumes:Pea, lentil, and chickpea concentrates for amino acid complementation in plant-based formulations.
Ingredient sourcing concentrates in Organic Fruits. Processing value-add accumulates in Whole Grains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German milling infrastructure anchors European nutrient dense food processing capacity, with enzymatic grain activation technology clustering around Cologne-Düsseldorf industrial corridors. Demand concentrates in metropolitan zones where health-conscious professionals and institutional procurement programs overlap.
United States
USDA organic certification drives K-12 school nutrition program eligibility and federal procurement preferences for nutrient dense suppliers. FDA nutrition labeling rules mandate substantiated bioactive declarations, forcing third-party testing investments. California's Central Valley and Pacific Northwest host sprouted grain processing clusters serving boutique fitness brands.
Germany
EFSA health claims frameworks enforce strict bioactive compound documentation, compressing formulation flexibility for sports nutrition entrants. EU Green Deal Farm to Fork regenerative sourcing requirements create preferential retail access for certified organic producers. Cologne-Düsseldorf industrial corridors concentrate enzymatic grain activation capacity for export markets.
Japan
JAS organic standards and metropolitan health-conscious consumers sustain premium expenditure on fermented plant proteins and sprouted grain categories. METI guidance on functional food labeling shapes product development timelines for domestic formulators. Tokyo-Osaka urban corridors anchor direct-to-consumer subscription channels for personalized micronutrient stacks.
Brazil
Latin American superfood sourcing clusters expose processors to climate and geopolitical disruption risks for quinoa, chia, and açaí inputs. ANVISA novel food regulations impose toxicological dossier requirements on new botanical introductions. São Paulo state hosts freeze-dried botanical processing infrastructure serving North American and European export demand.
India
FSSAI functional food regulations and rising urban professional disposable income expand addressable base for plant-based protein categories. Gujarat Cooperative Milk Marketing Federation infrastructure demonstrates cooperative dairy adaptation toward nutrient dense output. Maharashtra and Karnataka metropolitan zones concentrate direct-to-consumer brand headquarters targeting domestic health-conscious segments.
Nutrient Dense Food Products Market Competitive Landscape
Global majors compete with regional champions across supply chain control and certification depth, producing a tiered structure where scale advantages clash with local sourcing relationships. Cooperative dairy infrastructure dominates Northern European organic whey output, while Latin American superfood sourcing networks remain fragmented among regional aggregators. Three archetypes prevail: vertically integrated multinationals with captive farm relationships, cooperative processors with member-farmer governance, and biotech-enabled precision fermentation specialists. Competitive intensity centers on backward integration into regenerative agriculture and exclusive procurement contracts with institutional foodservice directors.
Within the cooperative processor tier, Arla Foods and Fonterra Cooperative Group exemplify member-governed structures with distributed farm infrastructure. Nestle S.A. occupies a position among vertically integrated multinationals with controlled Latin American superfood sourcing networks. Danone S.A. anchors the fermented plant protein specialization vector, occupying distinct gut-health-aligned positioning relative to dairy-centric competitors.
| Leading Market Players |
|---|
| Arla Foods |
| Dairy Farmers of America |
| Nestle S.A. |
| Lactalis International |
| Unilever Plc |
| Danone S.A. |
| Fonterra Cooperative Group |
| Gujarat Cooperative Milk Marketing Federation |
| FrieslandCampina |
| Others |
Value Network & Pricing Analysis
ISO 17025-accredited laboratory technicians in Germany and the United States command wage premiums that compress margins for mid-tier formulators while enabling premium pricing for certified producers. Labor-cost differentials between these technical certification hubs and Latin American sourcing regions widen pricing-tier spreads across organic protein concentrates and bioactive botanical extracts.
Pricing Analysis
Input-cost pass-through from organic pea and hemp protein concentrates drives pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on USDA Organic or EU Organic certification grade and volume scale of procurement contracts. Pricing pressure stems from weather-dependent yield volatility in Canadian and Ukrainian pea-growing regions. Weight Watchers in the meal replacement segment exhibit highest price sensitivity, while professional athletes in sports nutrition tolerate substantial premiums for banned-substance-certified inputs.
Supply Chain Analysis
Certification and qualification gating through USDA Organic, EU Organic, and JAS standards concentrates supply authority among accredited processors in Germany, the United States, and Japan. Raw material flows draw from Peruvian quinoa and açaí clusters, Canadian prairie pea protein infrastructure, and Northern European enzymatic grain activation facilities. Single-source vulnerability in Latin American superfood sourcing exposes formulators to climate disruption and geopolitical friction. Distribution runs through specialized organic procurement cooperatives with direct farm relationships, bypassing conventional broadline distributors in institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EFSA's stringent health claims substantiation costs in Europe and FDA's comparatively flexible labeling rules in the United States creates cost-advantaged formulation opportunities for transatlantic operators.
For Market Incumbents: Anchor market position through captive supply contracts with regenerative agriculture cooperatives in Northern Europe and precision fermentation capacity additions in North American biotechnology corridors. Consolidation investments should target ISO 17025-accredited testing laboratories facing capacity constraints. Certification depth remains the priority defensive lever against precision-fermentation-enabled entrants. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models for personalized micronutrient stacks, bypassing retail slotting fee barriers that exclude capital-constrained formulators. Fermented plant protein positioning in North American retail represents the most penetrable white space relative to European saturation. Gut-health-aligned branding offers differentiated go-to-market positioning against dairy-centric incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier organic processors lacking direct-to-consumer channel infrastructure. Long-term viability over the coming decade hinges on backward integration into regenerative sourcing and carbon-footprint disclosure capabilities. Watch for EFSA Novel Food catalog expansion as the critical regulatory inflection signal for bioactive botanical extract valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Decentralizes whey protein production from cooperative dairy infrastructure toward laboratory-scale biotech operators. |
| Regenerative Agriculture Certification Program | Secures preferential retail access under EU Green Deal Farm to Fork procurement quotas in German hospital systems. |
| Direct-to-Consumer Channel Launch | Bypasses conventional distributor markups and slotting fees for personalized micronutrient subscription retention. |
| Third-Party Testing Laboratory Acquisition | Resolves ISO 17025 capacity constraints that currently extend certification timelines for bioactive compound declarations. |
| Sprouted Grain Processing Technology Licensing | Transfers enzymatic activation capabilities to emerging markets seeking clean-label bioavailability without synthetic fortification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sports nutrition formulators, institutional foodservice procurement directors, organic certification auditors, and precision fermentation technologists with secondary validation against FDA nutrition labeling filings, EFSA health claims registers, USDA organic certification databases, and EU Green Deal Farm to Fork implementation reports. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Segment-weighting across product type, application context, consumer motivation tier, and ingredient sourcing geography structured the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to normalized baseline consumption patterns, incorporating sports nutrition end-use expansion rates, clean-label regulatory compliance cost trajectories, and regenerative sourcing adoption curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA Novel Food catalog expansion delays or Latin American superfood sourcing disruptions. Forecasts reflect documented assumptions regarding protein quality scoring methodology evolution and carbon-footprint disclosure standardization timelines. Deviation in EU Green Deal procurement quota enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Spirulina Powder Market