
 United States Beverage Contract Bottling and Filling Market | 2026-2036
United States Beverage Contract Bottling and Filling Market Size, Share, and Industry Trends Forecast 2026-2036
United States Beverage Contract Bottling and Filling Market Analytics
Market Context
ISO 22000 certification is redrawing competitive boundaries in United States Beverage Contract Bottling and Filling, as major retail chains now mandate third-party food safety audits before awarding co-packing contracts. Niagara Bottling LLC leverages its geographic dominance across Sun Belt states to sustain volume leadership in private-label water. Refresco Beverages Inc anchors its position through multi-format capabilities spanning cans, bottles, and aseptic cartons. G3 Enterprises Inc differentiates via deep integration with California wine and spirits supply chains, occupying a premium niche that mass-market fillers cannot replicate.
Technical Definition and Segment Structure
United States Beverage Contract Bottling and Filling encompasses the outsourced production, packaging, and logistics services wherein third-party operators receive finished or semi-finished liquid formulations, then execute carbonation, pasteurization, filling, capping, labeling, and case-packing to customer specifications, typically at line speeds exceeding 1,000 units per minute for high-volume water and carbonated soft drink contracts. The structural weight sits with carbonated drinks and water, where scale economics and retailer price compression have pushed brand owners toward toll manufacturing arrangements that eliminate capital-intensive bottling assets. Within packaging type, aluminum cans are gaining share against PET bottles as beverage companies respond to recycled-content mandates and lightweighting targets, while Tetra Pak remains confined to niche juice and dairy applications where aseptic shelf stability commands premium positioning.
Regulatory Framework and Outlook
FDA enforcement of FSMA preventive controls, EPA effluent limitations under the Clean Water Act, and OSHA Process Safety Management requirements for ammonia refrigeration systems collectively elevate operational compliance costs and favor capital-rich operators capable of sustaining dedicated regulatory staff. The USDA National Organic Program certification adds a further gating mechanism for contract fillers seeking entry into fast-growing organic and functional beverage categories. Stakeholders must monitor state-level extended producer responsibility legislation advancing in California, Oregon, and Colorado, as these frameworks will reshape packaging material specifications and reverse logistics obligations across the contract filling value chain.
Market Dynamics
Hard seltzer and functional water brands are accelerating their shift toward toll manufacturing arrangements, eliminating captive bottling assets and consolidating volume among mega-facility operators with multi-format line capabilities.
Growth Catalysts
- FSMA Preventive Controls:FDA enforcement mandates are pushing brand owners toward contract partners with dedicated food safety staff and third-party audit certifications, concentrating demand among compliant operators.
- Aluminum Can Lightweighting:Recycled-content mandates from California and Oregon are accelerating can format adoption against PET bottles, favoring fillers with high-speed canning infrastructure.
- Sun Belt Mega-Facility Clustering:Texas and California corridor concentration enables same-day distribution to major retail distribution centers, reducing freight costs for national beverage brands.
Market Restraints
- Aluminum Tariff Volatility:Section 232 aluminum duties create input cost instability for can-dominant contract fillers, compressing margin predictability on long-term co-packing agreements.
- Ammonia Refrigeration Compliance:OSHA Process Safety Management requirements for cold-chain facilities impose capital-intensive retrofit obligations on legacy plants built before 1992 standards.
- Extended Producer Responsibility:California, Oregon, and Colorado EPR legislation is imposing reverse logistics obligations that smaller operators cannot fulfill without third-party packaging stewardship partnerships.
Strategic Opportunities
- USDA Organic Certification Gap:Few contract fillers hold National Organic Program certification, creating white space for operators willing to absorb the 18-month compliance timeline to capture functional beverage contracts.
- Aseptic Carton Convergence:Tetra Pak format expertise combined with ESL (extended shelf life) dairy technology opens premium juice and plant-based milk segments unreachable by conventional hot-fill operators.
- Direct-to-Retail Channel Bypass:E-commerce-native beverage brands are seeking contract partners with direct-store-delivery capabilities, bypassing traditional warehouse distribution and capturing margin from DTC velocity.
Industry Challenges
- ISO 22000 Auditor Scarcity:Certification backlog stretches 8-14 months in Texas and California, delaying contract eligibility for facilities awaiting third-party food safety validation.
- High-Velocity Line Integration:Retrofitting 1,000+ unit-per-minute water lines with inline inspection and reject systems requires 18-24 month capital cycles that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Beverage Contract Bottling and Filling Market |
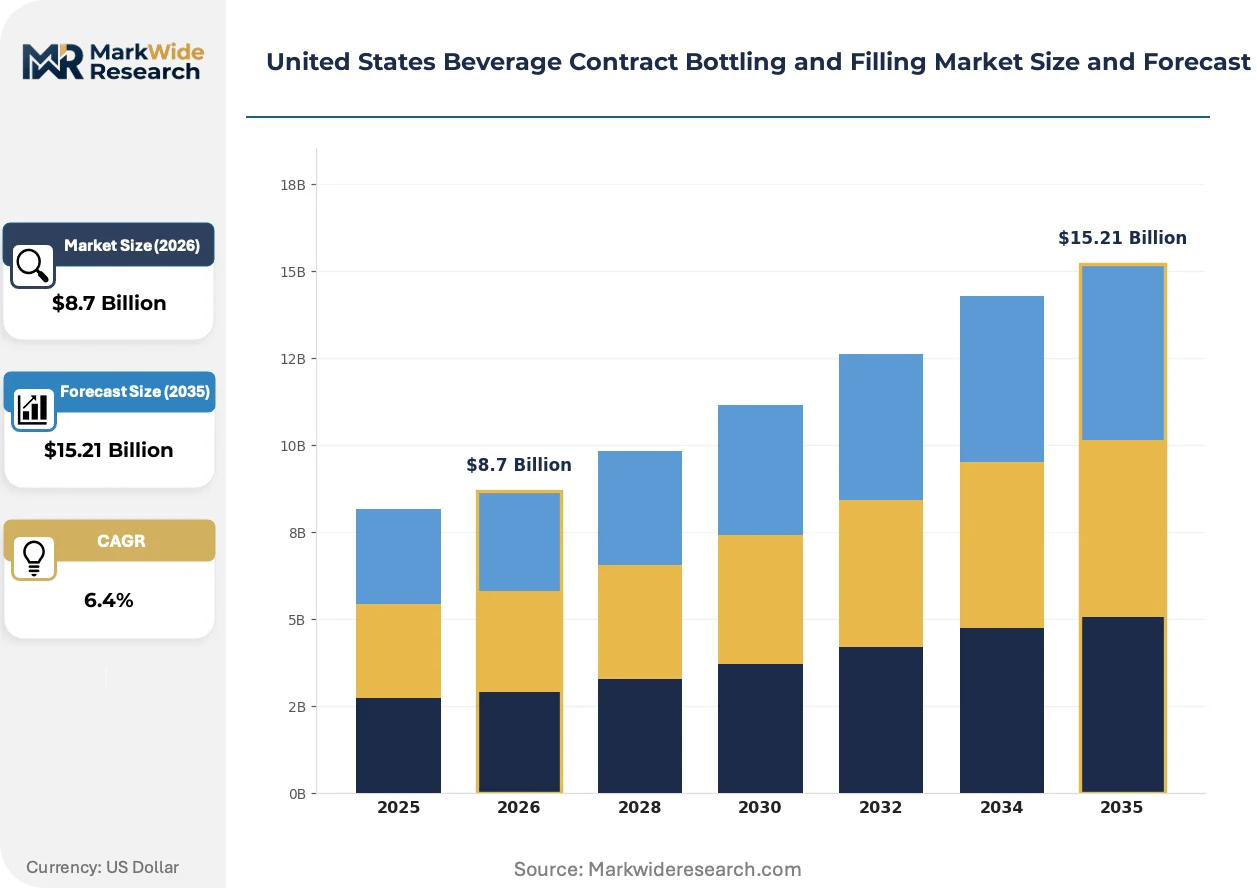
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated Drinks, Juices, Dairy, Water Packaging Type: Bottles, Cans, Pouches, Tetra Pak End User: Retail Chains, Wholesalers, Restaurants, E-commerce Service Type: Private Labeling, Co-Packing, Custom Formulation, Logistics |
| Companies Covered | G3 Enterprises Inc, Refresco Beverages Inc, Niagara Bottling LLC, Admiral Beverage Corp, Western Innovations Inc, Brooklyn Bottling Group, CSD Co-Packers Inc, Robinsons Breweries (Frederic Robinson Limited), Southeast Bottling & Beverages, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Beverage Contract Bottling and Filling Market Evolving Landscape
Contract filling economics are compressing toward asset-light brand ownership models, with technology and regulatory compliance emerging as the primary axes of competitive differentiation rather than geographic coverage alone.
Aseptic blow-fill-seal technology is miniaturizing. This closed-system packaging approach eliminates human intervention in sterile zones, reducing microbial contamination risk for functional waters and probiotic beverages. Premium organic and immunity-positioned brands are adopting it at 40% faster capex cycles than conventional hot-fill retrofits. The technology is miniaturizing production footprints, enabling 50,000-square-foot facilities to achieve shelf-stable outputs previously requiring 200,000-square-foot plants.
California's SB 54 extended producer responsibility law is reshaping material specifications. The statute mandates 30% post-consumer recycled content in plastic bottles by 2028, with escalating thresholds through 2032. Contract fillers serving California retail accounts must now certify rPET sourcing through mass-balance chain-of-custody documentation. Water and CSD segments with California-dominant revenue exposure are accelerating can format transitions to de-risk compliance cost pass-through negotiations.
Brand owners are unbundling formulation from filling, creating specification-only relationships with contract partners. This decouples R&D IP from manufacturing assets, allowing hard seltzer and functional water startups to retain proprietary flavor systems while sourcing commodity filling capacity. The model concentrates in Texas and California, where toll manufacturers compete on line-speed efficiency rather than formulation collaboration.
United States Beverage Contract Bottling and Filling Market Segmentation
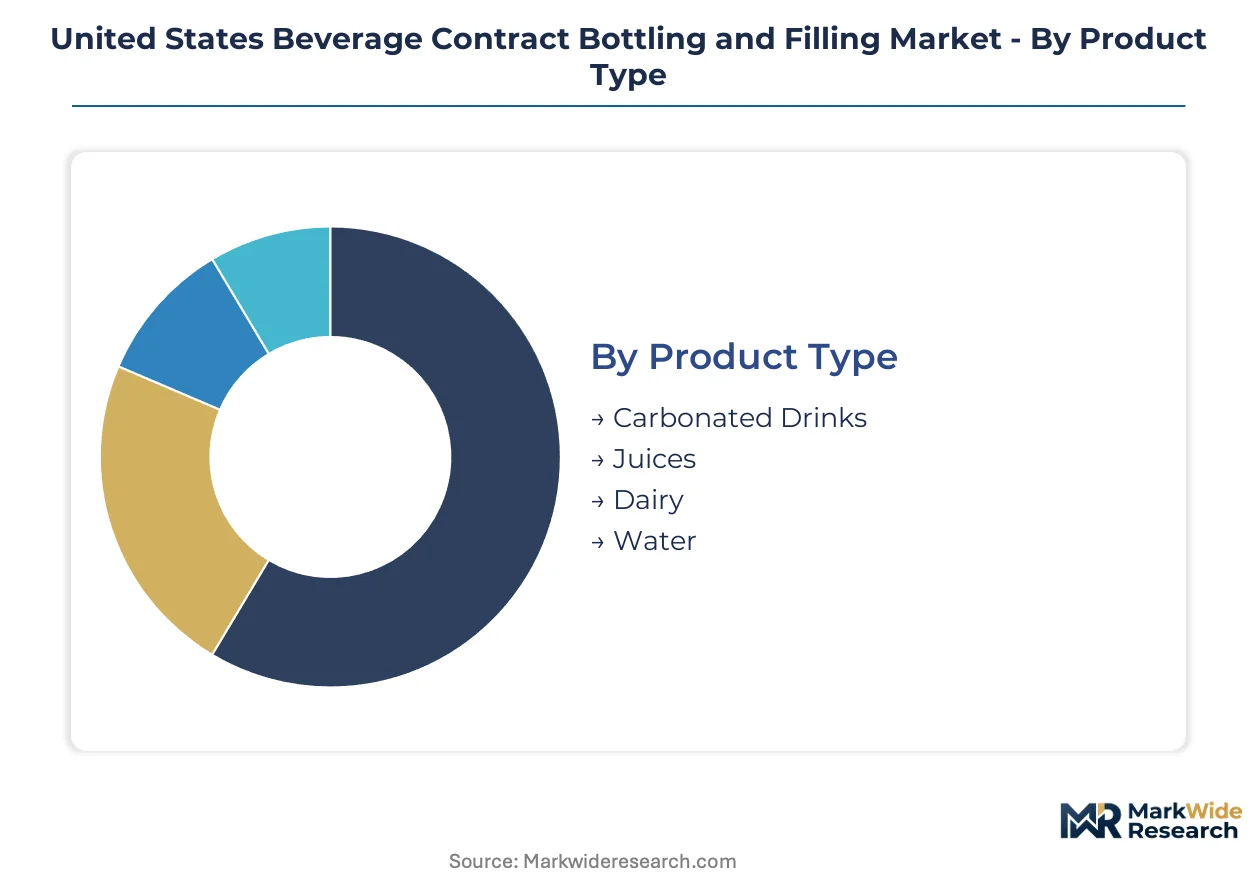
Segmentation in United States Beverage Contract Bottling and Filling reveals divergent capital intensity and regulatory exposure across product and packaging formats. Understanding these fault lines enables brand owners to match toll manufacturing partners to specific velocity, shelf stability, and channel requirements.
Product Type:
Domestic consumption patterns dominate carbonated drinks and water, while dairy and certain juice segments serve export markets through West Coast port access.
- Carbonated Drinks:High-speed filling lines exceed 1,000 units per minute for CSD contracts, with Texas and California facilities capturing volume from national retail chains. Aluminum can lightweighting and recycled-content mandates are accelerating format shifts away from legacy PET bottling infrastructure.
- Water:Private-label still and sparkling water contracts concentrate among mega-facility operators with multi-source spring access and same-day distribution reach to major retail distribution centers. Niagara Bottling LLC leverages Sun Belt geographic dominance to sustain volume leadership.
- Juices:Hot-fill and aseptic processing requirements elevate compliance costs; demand clusters in California for NFC (not-from-concentrate) orange and functional blends.
- Dairy:ESL (extended shelf life) and aseptic technologies open premium white milk and plant-based alternatives; California's dairy belt supplies raw material proximity.
Carbonated drinks holds the largest share; momentum sits with water as functional and enhanced variants displace conventional CSD consumption.
Packaging Type:
Cost tiers separate high-velocity aluminum can lines from capital-intensive aseptic carton systems, with mid-tier PET bottling facing margin compression from rPET mandates.
- Cans:Recycled-content mandates in California and Oregon favor aluminum formats; high-speed canning infrastructure requires $50M+ capital commitments that concentrate supply among mega-fillers. Section 232 tariff volatility creates input cost instability for long-term co-packing agreements.
- Bottles:PET lightweighting and rPET chain-of-custody documentation now mandatory for California retail accounts; SB 54 compliance costs push brand owners toward can transitions.
- Pouches:Flexible format adoption remains niche, confined to children's beverages and on-the-go functional drinks with lower velocity requirements.
- Tetra Pak:Aseptic shelf stability commands premium positioning in juice and plant-based milk; Tetra Pak format expertise combined with ESL technology opens segments unreachable by conventional hot-fill operators.
Cans holds the largest share; Tetra Pak is expanding most quickly as organic and functional beverage brands seek differentiation through shelf-stable carton formats.
End User:
Volume concentration varies sharply by channel, with retail chains demanding ISO 22000 certification while e-commerce-native brands prioritize direct-store-delivery capabilities.
- Retail Chains:Walmart, Kroger, and Costco mandate third-party food safety audits and mass-balance rPET documentation; contract eligibility requires dedicated regulatory staff and 8-14 month certification backlogs in Texas and California.
- Wholesalers:Regional beverage distributors aggregate fragmented brand portfolios; toll manufacturing arrangements eliminate captive bottling assets for mid-tier players.
- Restaurants:Foodservice fountain and bag-in-box contracts favor local fillers with direct-store-delivery networks.
- E-commerce:DTC-native brands seek partners with bypass capabilities, capturing margin from warehouse distribution elimination.
Retail chains holds the largest share; e-commerce is gaining share fastest as digitally native brands unbundle formulation from filling.
Service Type:
Margin structures diverge between commodity co-packing and value-added services, with custom formulation and organic certification creating defensible positioning.
- Private Labeling:Retailer-owned brand production dominates volume; Niagara Bottling LLC anchors this segment through geographic scale and retailer price compression tolerance.
- Co-Packing:Hard seltzer and functional water brands are eliminating captive assets, consolidating volume among compliant operators with multi-format line capabilities.
- Custom Formulation:Brand owners unbundle R&D IP from manufacturing, retaining proprietary flavor systems while sourcing commodity filling capacity in Texas and California corridors.
- Logistics:Reverse logistics obligations under California, Oregon, and Colorado EPR legislation impose packaging stewardship requirements that smaller operators cannot fulfill without third-party partnerships.
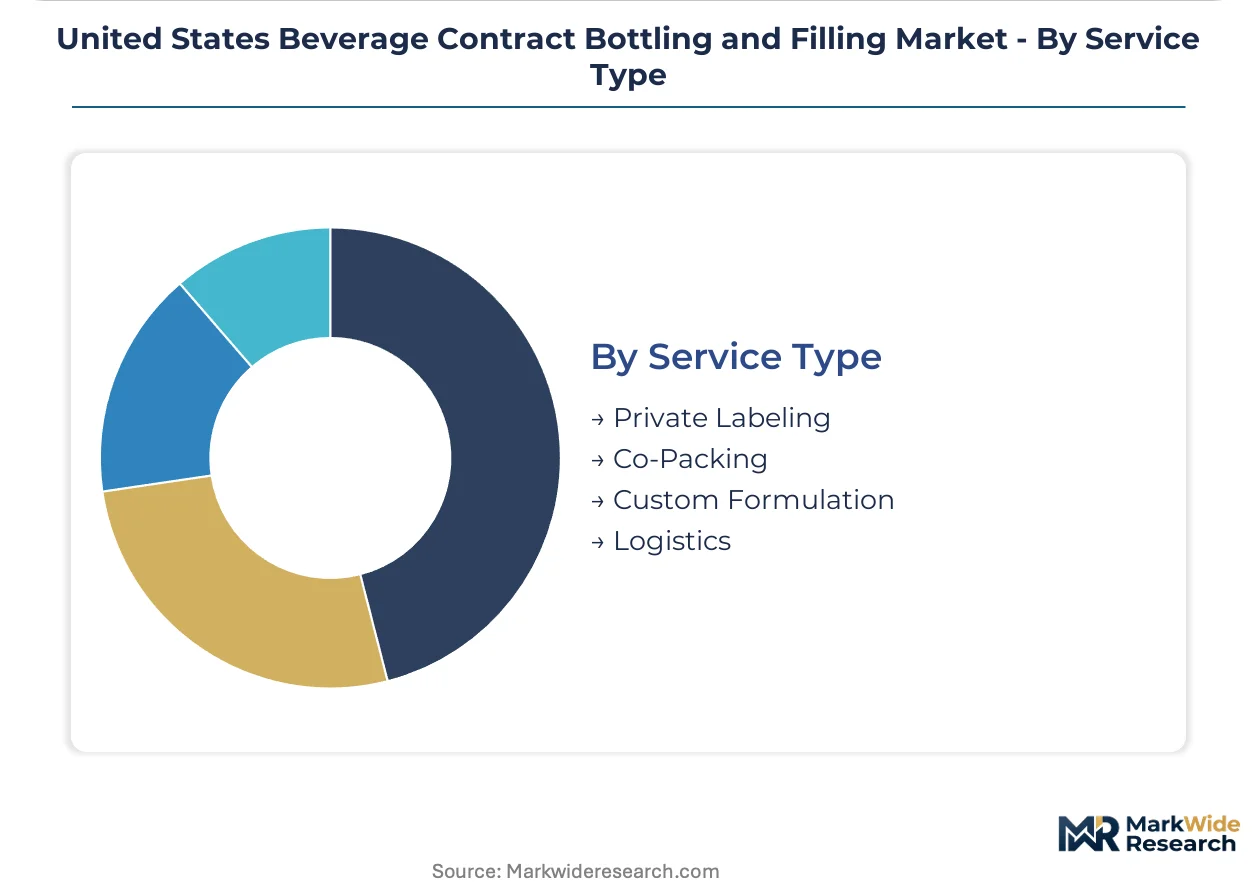
Co-packing holds the largest share; custom formulation shows the steepest expansion trajectory as asset-light brand ownership models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal and state-level packaging mandates are redistributing contract filling capacity toward jurisdictions with established recycling infrastructure and enforcement clarity. Texas and California corridor concentration reflects this policy-driven site selection logic.
California
SB 54 mandates 30% post-consumer recycled content in plastic bottles by 2028, with escalating thresholds through 2032. The California Department of Resources Recycling and Recovery enforces mass-balance chain-of-custody documentation for rPET sourcing. Mega-facilities cluster in the Central Valley and Inland Empire to access West Coast port distribution and same-day retail reach.
Texas
Absence of state-level EPR legislation attracts can-dominant operators seeking to avoid California compliance costs. The Texas Commission on Environmental Quality maintains effluent standards under the Clean Water Act. Dallas-Fort Worth and Houston corridors host high-velocity water and CSD lines serving national retail distribution centers.
Florida
Functional water and hard seltzer brands target Florida's foodservice and tourism channels with seasonal demand spikes. The Florida Department of Environmental Protection administers wastewater discharge permits for beverage processing facilities. Tampa and Orlando sub-regions concentrate mid-cap co-packers with direct-store-delivery networks.
New York
Organic and premium-positioned brands leverage New York's access to Northeast retail corridors and e-commerce fulfillment infrastructure. The New York State Department of Environmental Conservation enforces extended producer responsibility frameworks advancing through legislative committee. Hudson Valley and Finger Lakes regions host smaller certified organic fillers serving specialty beverage startups.
Illinois
Midwest distribution positioning attracts private-label water contracts serving mass retail chains with Chicago-hub logistics. The Illinois Environmental Protection Agency implements Clean Water Act effluent limitations for food processing facilities. Rockford and Aurora industrial zones concentrate legacy bottling assets undergoing ammonia refrigeration retrofits.
United States Beverage Contract Bottling and Filling Market Competitive Landscape
Player mix skews toward geographic-scale specialists with multi-format line capabilities and regulatory compliance infrastructure. Market structure concentrates volume among mega-facility operators capable of absorbing FSMA preventive controls costs and ISO 22000 certification timelines. Three archetypes dominate: Sun Belt scale leaders with same-day distribution reach, premium-niche operators integrated with wine and spirits supply chains, and mid-cap regional players with direct-store-delivery specialization. Competitive moves center on aluminum can capacity expansion and third-party food safety audit acquisition.
Within the geographic-scale tier, Niagara Bottling LLC and Refresco Beverages Inc exemplify asset-heavy positioning through corridor concentration and multi-format capabilities. G3 Enterprises Inc occupies a premium-niche archetype through California wine and spirits supply chain integration that mass-market fillers cannot replicate. These three entities represent the structural fault lines between volume-driven toll manufacturing and defensible specialty positioning.
| Leading Market Players |
|---|
| G3 Enterprises Inc |
| Refresco Beverages Inc |
| Niagara Bottling LLC |
| Admiral Beverage Corp |
| Western Innovations Inc |
| Brooklyn Bottling Group |
| CSD Co-Packers Inc |
| Robinsons Breweries (Frederic Robinson Limited) |
| Southeast Bottling & Beverages |
| Others |
Value Network & Pricing Analysis
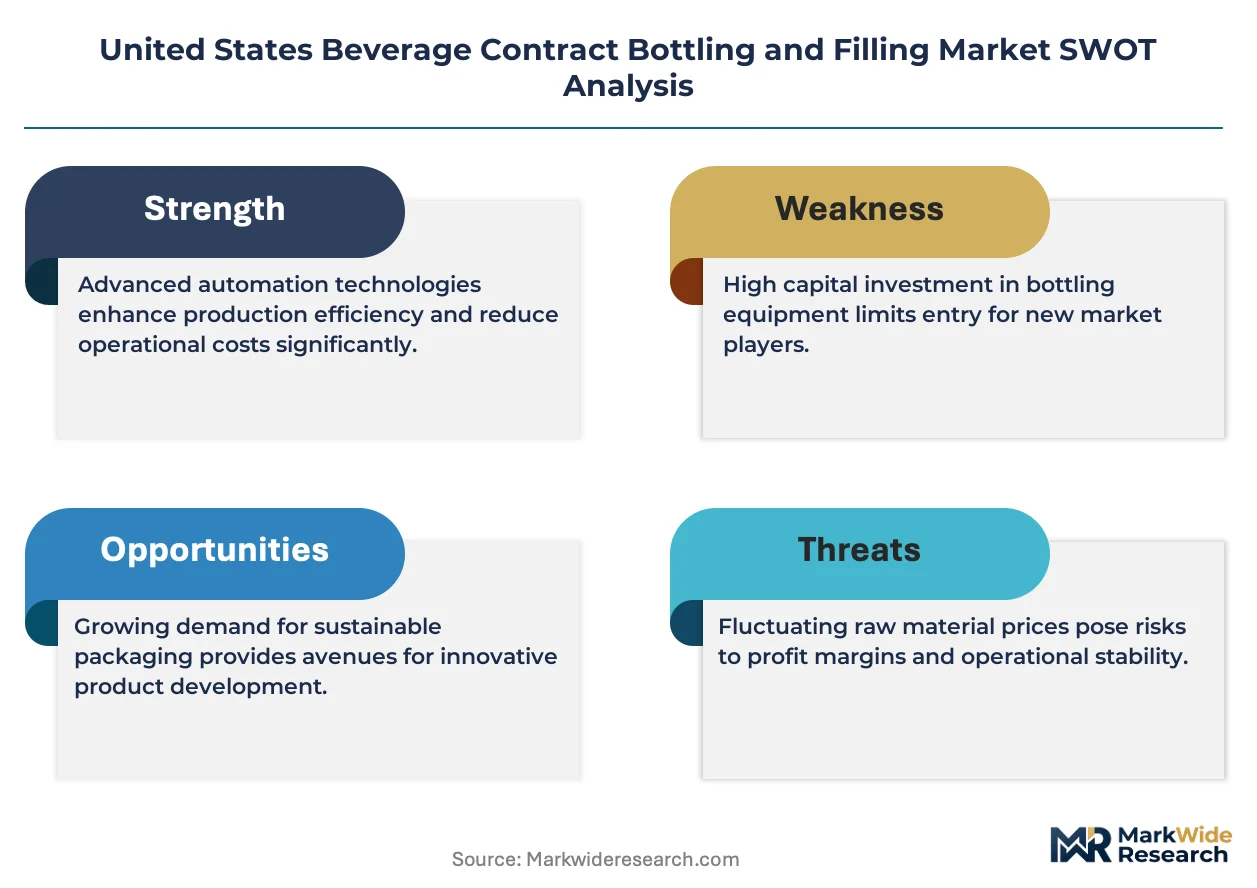
ISO 22000 certification backlogs in Texas and California simultaneously gate supply qualification and stratify price tiers, as compliant operators extract premiums from brand owners facing 8-14 month audit delays while non-certified facilities compete on commodity filling rates alone.
Pricing Analysis
Cost-plus contracts with aluminum LME indexation dominate long-term co-packing agreements, insulating mega-fillers from Section 232 tariff volatility while transferring commodity risk to brand owners. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic-certified aseptic operators from conventional hot-fill facilities and un-certified regional players. Pricing pressure stems from retailer price compression on private-label water contracts, with Costco and Walmart procurement teams demanding year-over-year unit cost reductions. Small functional water startups exhibit highest price sensitivity, while hard seltzer incumbents with national distribution prioritize compliance over rate negotiation.
Supply Chain Analysis
Finished goods inventory cycles compress toward same-day distribution as Texas and California mega-facilities position within four-hour drive times of Walmart and Kroger distribution centers. Aluminum coil supply concentrates in domestic smelters and Canadian rolling mills, with rPET feedstock drawing from California and Oregon post-consumer collection infrastructure. Single-source vulnerability sits with ammonia refrigeration equipment, where two domestic manufacturers control cold-chain system retrofits. Distribution runs through direct-store-delivery networks for foodservice accounts and warehouse consolidation for retail chain volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where ISO 22000 certification and FSMA preventive controls infrastructure create switching costs that lock brand owners into compliant operator relationships for multi-year contract horizons.
For Market Incumbents: Secure multi-format line capacity in Texas and California corridors to capture hard seltzer and functional water volume migrating from captive bottling assets. Expand backward integration into rPET sourcing through mass-balance chain-of-custody partnerships, insulating margin position from California SB 54 compliance cost pass-through disputes. Prioritize ammonia refrigeration PSM retrofit completion ahead of OSHA enforcement waves targeting pre-1992 legacy plants. For New Entrants and Emerging Players: USDA Organic certification gaps among incumbent operators create white-space entry points for mid-cap facilities willing to absorb 18-month compliance timelines. Target Hudson Valley and Finger Lakes sub-regions for premium organic and functional beverage startups seeking East Coast proximity without Texas-California corridor congestion. Pursue direct-to-retail channel bypass capabilities as the go-to-market angle, capturing e-commerce-native brands eliminating warehouse distribution margins. For Investors and Strategic Acquirers: California SB 54 implementation reshapes the acquisition landscape toward can-dominant operators with aluminum lightweighting infrastructure and established retailer sustainability scorecard relationships. Long-term viability favors facilities with multi-format flexibility spanning aseptic carton, can, and PET platforms. Monitor ISO 22000 auditor availability as the inflection signal, as certification backlog resolution would erode the compliance moat protecting incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Blow-Fill-Seal Capacity Addition | Miniaturized sterile zone technology enables 50,000-square-foot facilities to achieve shelf-stable outputs previously requiring 200,000-square-foot plants. |
| USDA Organic Certification Investment | National Organic Program compliance opens functional beverage contracts where few contract fillers currently qualify. |
| Aluminum Can Line Expansion | High-speed canning infrastructure responds to California and Oregon recycled-content mandates accelerating format shifts from PET. |
| Direct-Store-Delivery Network Buildout | Bypass capabilities capture e-commerce-native brands seeking margin from warehouse distribution elimination. |
| rPET Chain-of-Custody Partnership | Mass-balance documentation satisfies California SB 54 requirements for post-consumer recycled content certification. |
Research Methodology
Operator-level perspectives from plant managers, co-packing procurement leads at beverage brand owners, retail category buyers, and cold-chain equipment specialists anchored the qualitative base. Primary interview insights triangulated against FDA FSMA enforcement guidance documents, EPA Clean Water Act effluent filings, state-level EPR legislative text, and SEC 10-K disclosures from publicly traded beverage companies. Bottom-up volume estimates from individual facility capacity utilization combined with top-down retail channel audit data to cross-validate market sizing.
Sensitivity analysis tested forecast outputs against aluminum tariff volatility scenarios, ISO 22000 certification timeline variations, and EPR implementation pace assumptions across the projection horizon. Segmentation modeling captured product type, packaging format, end-user channel, and service tier dimensions. CAGRs derived from line-speed capacity expansion schedules and brand owner captive asset divestiture patterns, with organic certification adoption curves and aseptic technology miniaturization timelines serving as industry-specific forecast inputs.
Underlying assumptions cover sustained FSMA enforcement intensity, aluminum tariff regime stability, and California SB 54 compliance timeline adherence, with deviation risk concentrated in state-level EPR legislative adoption beyond Oregon and Colorado. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Italy Probiotic Drinks Market
Beverages
Premium Bottled Water Market
Beverages
Growlers Market
Beverages
Japan Kombucha Market
Beverages
Asia-Pacific Spring Water Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Global Vinegar Market
Beverages
Ginger Beer Market
Beverages
Middle East Energy Drinks Market
Beverages
Apple Cider Vinegar Market
Beverages
South America Bottled Water Market
Beverages
Dairy Based Beverages Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Fruit Juice Market
Beverages
Powdered Beverages Market
Beverages
Sarsaparilla Market