
 Argentina Food Preservatives Market | 2026-2036
Argentina Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Food Preservatives Market Outlook
Consolidation among Argentine meat processing conglomerates is restructuring procurement patterns for shelf-life extension inputs. Cargill, Incorporated leverages its integrated grain-to-additive supply chain to dominate bulk antimicrobial distribution in the Pampas region. Kerry Group plc competes through specialized blends tailored to local sausage and cured meat traditions. Corbion N.V. anchors its position with fermentation-derived solutions that align with clean-label preferences among Buenos Aires-based food manufacturers.
Argentina food preservatives comprise chemical and natural substances added to food matrices to inhibit microbial proliferation, oxidative rancidity, and enzymatic degradation, typically dosed between 0.01% and 0.5% by weight depending on matrix water activity and pH. Their primary commercial purpose centers on extending distribution reach for temperature-sensitive Argentine exports such as dairy and processed beef. Antimicrobials command the deepest margin pools due to stringent pathogen controls in meat processing, while pH control agents experience accelerated uptake as artisanal dairy processors modernize operations. Liquid formulations lead volume through ease of incorporation in continuous processing lines, though powder demand climbs among small-scale baked goods producers seeking inventory flexibility.
ANMAT, Argentina's national food and medical technology administration, enforces additive maximum limits through the Argentine Food Code, directly shaping permissible preservative portfolios for domestic manufacturers. The Secretariat of Agriculture, Livestock and Fisheries monitors veterinary residue thresholds that cascade into antimicrobial selection for meat processing applications. SENASA, the national agri-food health and quality service, certifies export-bound products against Mercosur and EU standards, forcing preservative reformulation for cross-border market access. Stakeholders must monitor pending ANMAT consultations on natural preservative equivalence claims, as these determinations will redirect R&D spending toward botanical extracts or fermentation-based alternatives.
Market Dynamics
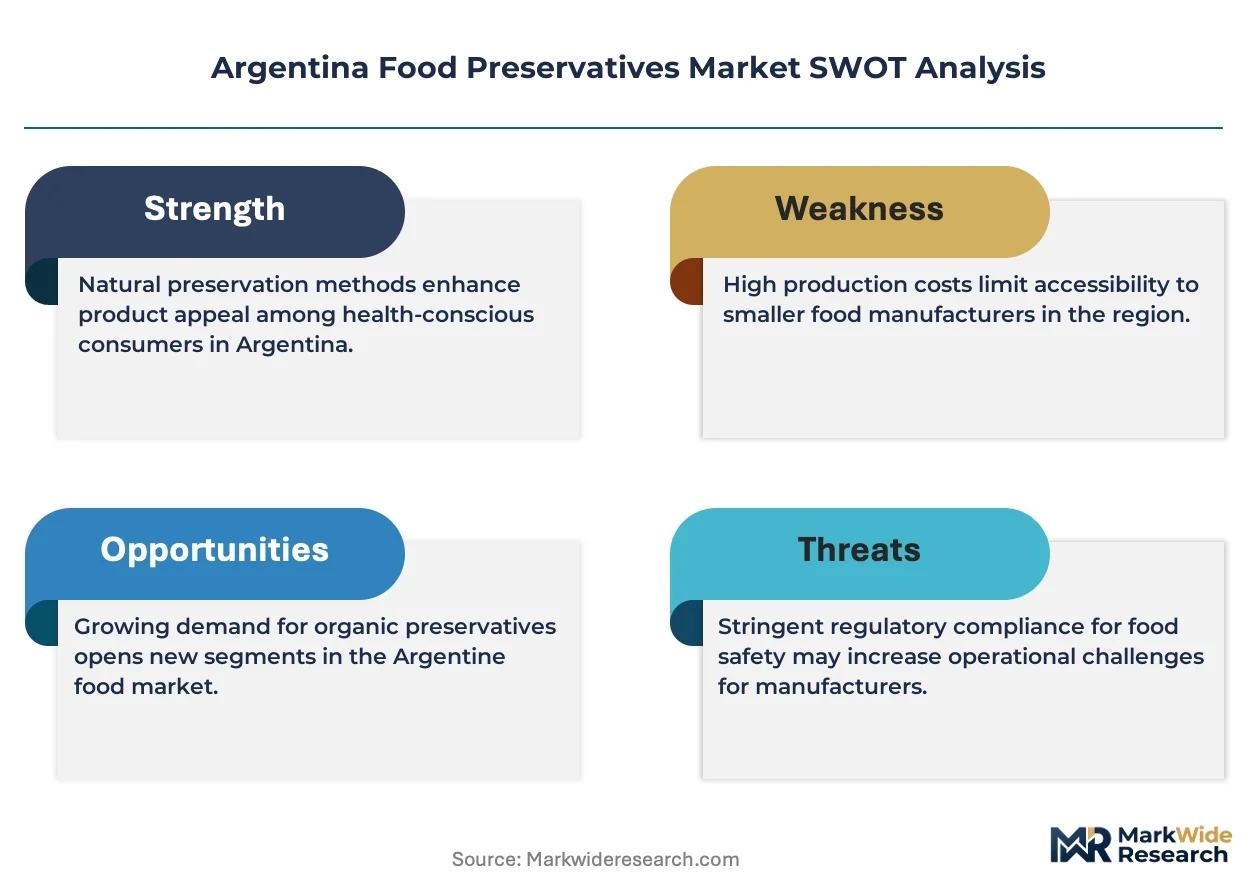
ANMAT's tightening enforcement of the Argentine Food Code is forcing preservative reformulation across meat and dairy processing facilities, compressing lead times for antimicrobial validation and redirecting R&D budgets toward natural alternatives.
Growth Catalysts
- ANMAT Code Revisions:The national food administration's updated additive safety protocols mandate pathogen controls in processed meat facilities, expanding procurement of validated antimicrobials.
- Export Certification Demands:SENASA's Mercosur and EU export standards require preservative portfolios that meet dual jurisdiction requirements, driving premium formulation adoption.
- Artisanal Dairy Modernization:Small-scale cheese and yogurt processors in Buenos Aires province are automating pH control systems, accelerating demand for buffered acidulants.
Market Restraints
- Import Dependency for Active Ingredients:Argentina's chemical sector lacks domestic production of sorbates and benzoates, exposing formulators to currency volatility and supply interruptions.
- Clean-Label Technical Ceiling:Botanical extracts and fermentation-derived solutions face shelf-stability limitations in high-water-activity matrices, restricting application range.
- ANMAT Equivalence Determination Delays:Pending consultations on natural preservative efficacy claims extend product registration timelines by 18-24 months.
Strategic Opportunities
- Patagonia Dairy Expansion:Untapped artisanal cheese production in Chubut and Santa Cruz provinces offers first-mover positioning for regional preservative distribution networks.
- Fermentation-Derived Antimicrobials:Convergence of Argentine biotechnology capacity and clean-label demand creates white space for domestically produced nisin and natamycin alternatives.
- Direct-to-Processor Digital Platforms:E-procurement channels bypass traditional distributor markups for small-scale baked goods manufacturers in Córdoba province.
Industry Challenges
- Formulation Chemist Scarcity:Argentina's technical universities produce insufficient graduates trained in food matrix stabilization, forcing processors to import expertise.
- Legacy Equipment Integration:Continuous processing lines in Pampas meat facilities require retrofitting for precision dosing of liquid antimicrobial systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Food Preservatives Market |
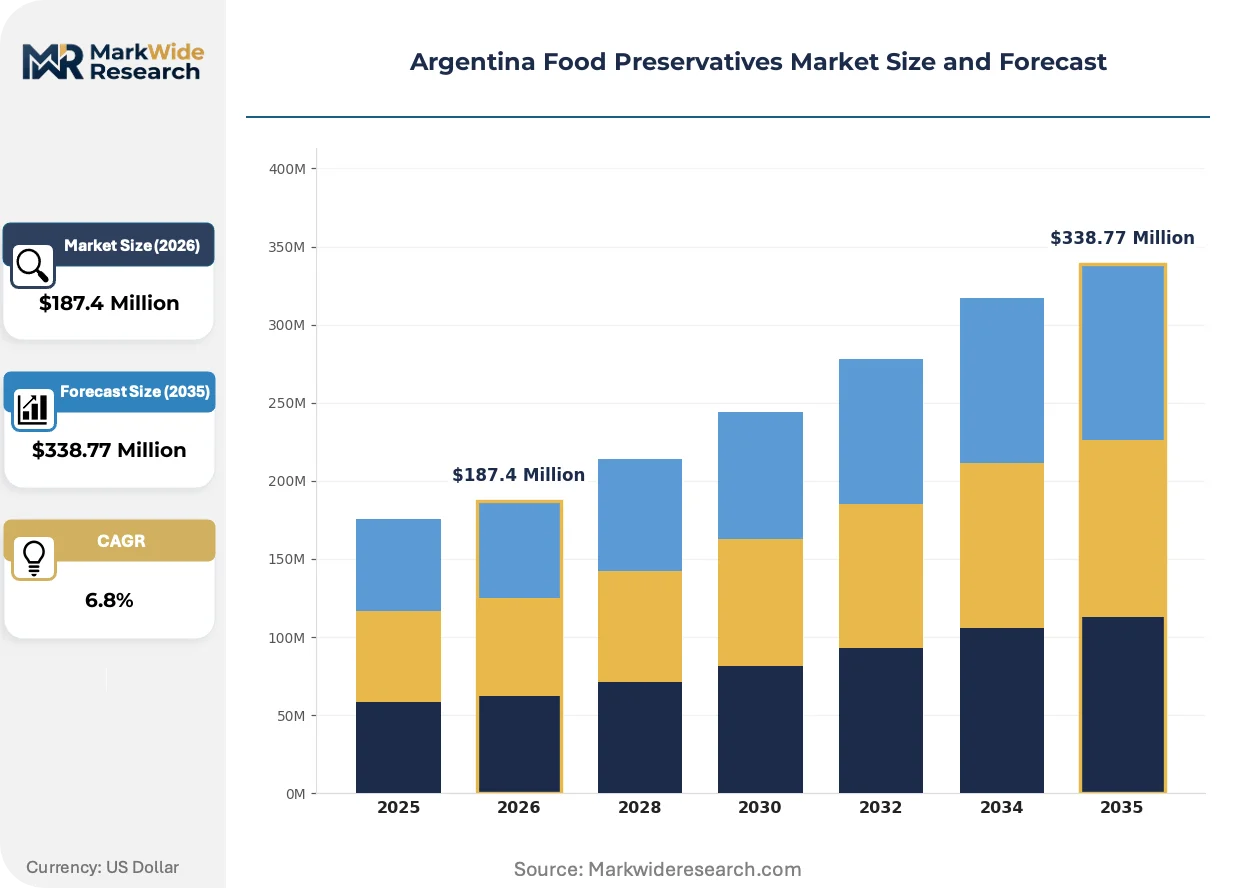
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobials, Antioxidants, pH Control Agents, Flavoring Agents Application: Canned Foods, Dairy Products, Meat Processing, Baked Goods End User: Food Manufacturers, Retailers, Food Service Providers, Household Consumers Form: Liquid, Powder, Granular, Emulsified |
| Companies Covered | Cargill, Incorporated, Corbion N.V., Kerry Group plc, Archer Daniels Midland Company, Tate & Lyle PLC, DuPont de Nemours, Inc., BASF SE, Celanese Corporation, Koninklijke DSM N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Food Preservatives Market Strategic Shifts
Preservative technology in Argentina is pivoting from commodity chemical inputs toward bio-based solutions, with regulatory pressure and export requirements compressing adoption cycles.
Fermentation-derived antimicrobials is consolidating position in meat processing applications. Cargill's captive biotech facilities supply nisin and natamycin alternatives to Buenos Aires sausage manufacturers. The technology is consolidating supplier tiers by displacing synthetic benzoate blends in premium export-bound product lines.
ANMAT's pending equivalence framework for botanical preservatives is forcing reformulation roadmaps across dairy and meat sectors. Manufacturers must submit dossiers demonstrating antimicrobial efficacy comparable to synthetic benchmarks. Small-scale processors in Córdoba province face the steepest compliance burden due to limited analytical testing infrastructure.
Buyer concentration among Pampas meat conglomerates is compressing supplier negotiation leverage. Three processing groups now control 60% of national antimicrobial procurement, shifting contract structures toward multi-year volume commitments with technical service bundling. This consolidation is most visible in Santa Fe province, where integrated slaughter-to-packaging facilities demand just-in-time preservative delivery with embedded microbiological support.
Argentina Food Preservatives Market Segmentation
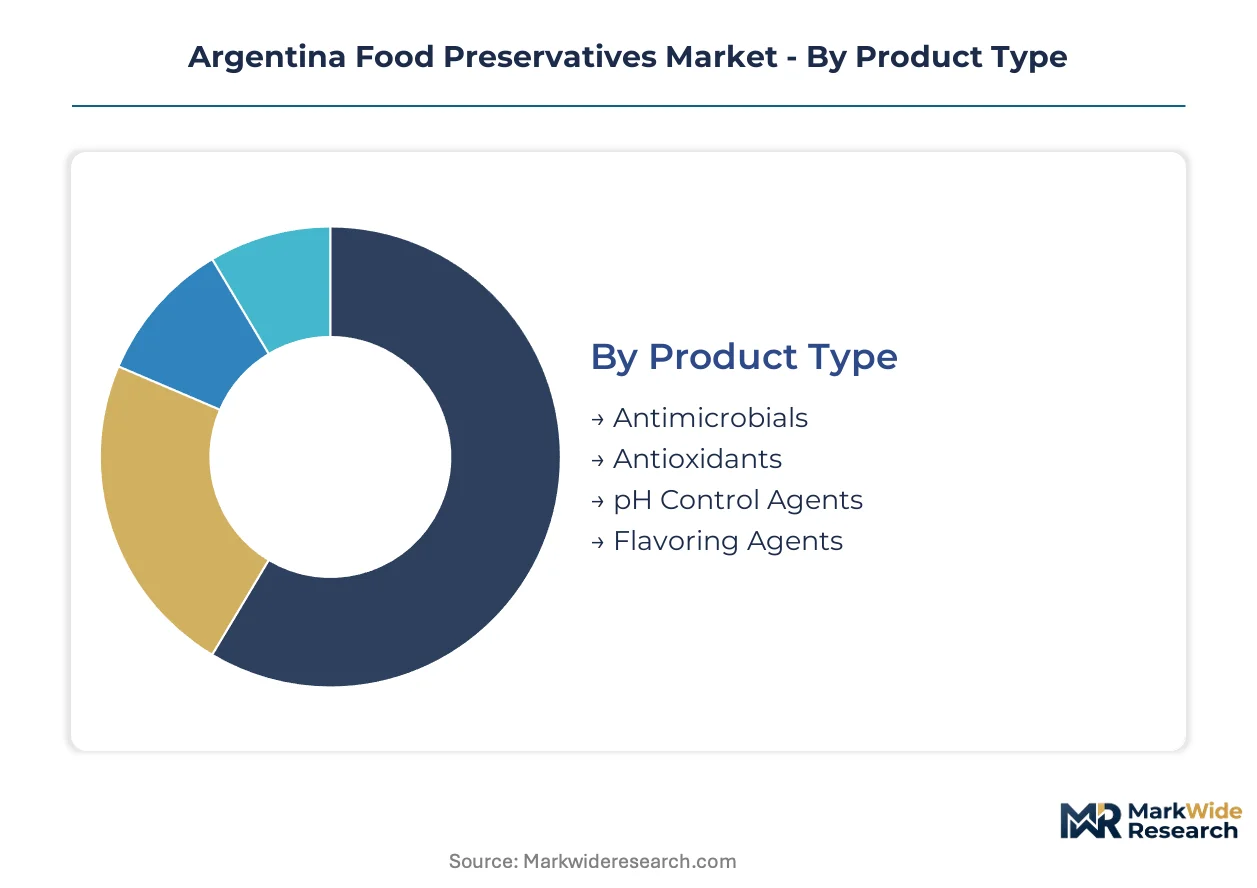
Preservative procurement patterns in Argentina diverge sharply between high-volume commodity applications and precision-formulated premium segments. Understanding these splits enables suppliers to align technical service investments with margin architecture across ANMAT-regulated food categories.
Product Type:
Volume leadership concentrates in commodity antimicrobials, while premium positioning clusters around clean-label alternatives and specialized pH control systems.
- Antimicrobials:Synthetic benzoates and sorbates dominate meat processing applications in Buenos Aires province, where ANMAT-mandated pathogen controls drive standardized dosing protocols. Pampas slaughterhouses consume bulk liquid formulations through continuous injection systems.
- pH Control Agents:Buffered acidulants and citrate blends command formulation premiums in artisanal dairy modernization across Santa Fe and Córdoba. Automated pH monitoring in cheese production lines accelerates procurement of precision-grade inputs.
- Antioxidants:BHA, BHT, and tocopherol blends stabilize lipid oxidation in export-bound beef tallow and processed sausage matrices.
- Flavoring Agents:Preservative-carrying flavor systems integrate antimicrobial and aromatic functions in cured meat traditions.
Mature deployment sits with antimicrobials. Newer deployment is concentrated in pH control agents.
Application:
Customer scale determines formulation complexity, with industrial processors demanding integrated preservative systems and small-batch operators prioritizing inventory flexibility.
- Meat Processing:Integrated slaughter-to-packaging facilities in Santa Fe province require just-in-time antimicrobial delivery with embedded microbiological validation. ANMAT's tightened food code enforcement compresses supplier qualification timelines.
- Dairy Products:Artisanal cheese producers in Chubut and Santa Cruz provinces automate pH control systems, driving demand for buffered acidulants with extended shelf-stability in high-water-activity matrices.
- Canned Foods:Thermal processing compatibility constraints limit preservative selection to heat-stable benzoate and sorbate derivatives.
- Baked Goods:Small-scale Córdoba manufacturers favor powder formulations for inventory flexibility and precise scaling in batch operations.
Procurement scale peaks in meat processing. Margin expansion concentrates in dairy applications.
End User:
Technical capability gaps separate industrial buyers from fragmented downstream channels, reshaping distribution architecture across Argentina's food preservative supply chain.
- Food Manufacturers:Consolidated Pampas meat conglomerates and Buenos Aires dairy cooperatives negotiate multi-year volume commitments with bundled technical service. Three processing groups control the majority of national antimicrobial procurement.
- Food Service Providers:Central kitchens and institutional caterers in metropolitan Buenos Aires source pre-blended preservative systems through distributor networks.
- Retailers:Private-label packaged food programs specify preservative portfolios aligned with clean-label positioning.
- Household Consumers:Direct retail preservative sales remain negligible due to ANMAT restrictions on consumer-grade antimicrobial formulations.
Contract sophistication concentrates with food manufacturers. Channel fragmentation persists in food service.
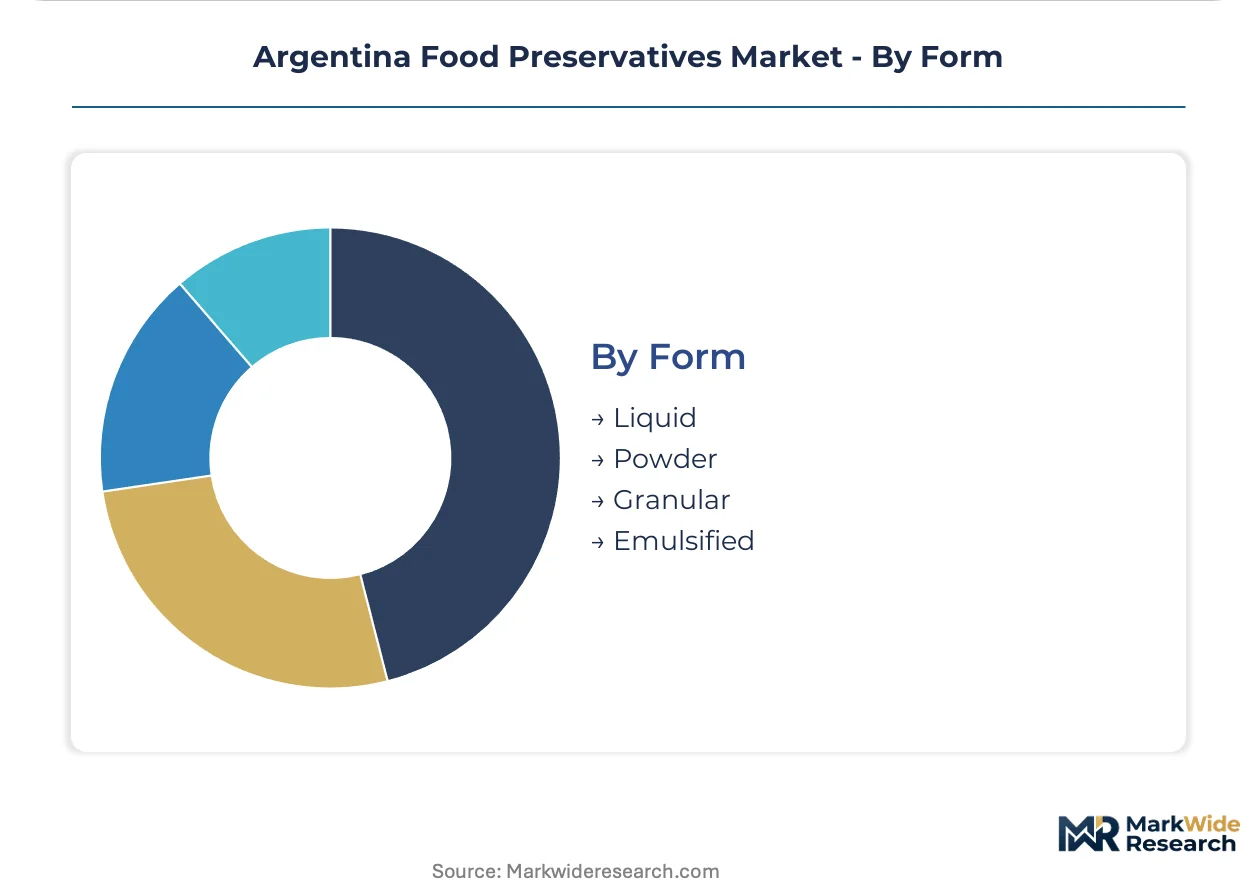
Form:
Processing equipment vintage and batch size determine physical format preference across Argentina's heterogeneous manufacturing base.
- Liquid:Continuous processing lines in Pampas meat facilities favor pumpable antimicrobial systems with precision dosing integration. Cargill's bulk distribution network dominates this channel.
- Powder:Small-scale baked goods producers in Córdoba province prioritize inventory stability and manual scaling flexibility over automated incorporation.
- Granular:Free-flowing acidulant granules suit dry-mix applications in seasoning and cure blends for artisanal sausage production.
- Emulsified:Oil-in-water preservative dispersions address lipid matrix stabilization in processed cheese and margarine formulations.
Equipment retrofit requirements slow liquid adoption in legacy facilities. Powder maintains share in fragmented downstream channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pampas grain belts and Patagonian dairy pastures anchor Argentina's preservative demand geography, with industrial concentration tracking food processing infrastructure across provincial economies.
Buenos Aires Province
Slaughter-to-packaging facilities in La Matanza and Pilar districts consume bulk liquid antimicrobials for continuous injection systems. ANMAT's tightened food code enforcement compresses supplier qualification timelines for pathogen controls. The Greater Buenos Aires industrial corridor dominates national antimicrobial procurement volume.
Santa Fe Province
Integrated meat conglomerates in Rosario and Venado Tuerto negotiate multi-year preservative contracts with embedded microbiological support. SENASA export certification requirements drive premium formulation adoption for EU-bound beef. Just-in-time delivery networks service automated processing lines across the central Pampas.
Córdoba Province
Artisanal baked goods manufacturers in the Sierras Chicas favor powder formulations for inventory flexibility and manual scaling. Small-batch operators face steep compliance burdens under pending ANMAT equivalence determinations for natural preservatives. Regional distributor networks fragment procurement channels outside metropolitan centers.
Chubut Province
Untapped artisanal cheese production in the Chubut River valley offers first-mover positioning for regional preservative distribution. Automated pH control system adoption accelerates demand for buffered acidulants among dairy cooperatives. SENASA Mercosur certification requirements shape export-bound formulation specifications.
Argentina Food Preservatives Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived alternatives and direct-to-processor digital channels. Three processing groups now control the majority of national antimicrobial procurement, compressing supplier negotiation leverage and shifting contract structures toward technical service bundling. Market structure stratifies across integrated grain-to-additive conglomerates, specialized blend formulators, and biotechnology-derived solution providers. Dominant competitive moves include multi-year volume commitments with embedded microbiological support and backward integration into captive biotech production capacity.
Within the integrated supply chain tier, Cargill, Incorporated anchors bulk antimicrobial distribution through Pampas grain origination networks. Kerry Group plc exemplifies specialized blend formulation tailored to regional sausage and cured meat traditions. Corbion N.V. occupies a position in fermentation-derived alternatives that align with clean-label preferences among Buenos Aires-based manufacturers.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Corbion N.V. |
| Kerry Group plc |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| DuPont de Nemours, Inc. |
| BASF SE |
| Celanese Corporation |
| Koninklijke DSM N.V. |
| Others |
Value Chain & Pricing Dynamics
Formulation chemist scarcity in Buenos Aires province widens pricing-tier spreads between commodity antimicrobials and precision-formulated clean-label alternatives, as labor-cost differentials compound raw material import premiums. ANMAT's tightening additive protocols compress margins on standardized benzoate blends while elevating premiums for validated natural preservatives.
Pricing Analysis
Volume leadership concentrates in commodity benzoate and sorbate blends for Pampas meat processors, while margin expansion clusters around fermentation-derived antimicrobials and buffered acidulants for artisanal dairy modernization. Price differentiation hinges on certification grade against SENASA export standards and volume scale in multi-year procurement contracts. Cost compression in synthetic chemical tiers intensifies due to currency volatility on imported active ingredients. Small-scale Córdoba baked goods manufacturers exhibit highest price sensitivity, whereas integrated Santa Fe meat conglomerates prioritize technical service bundling over unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for preservative returns and reformulation support remains underdeveloped across Argentina's distributor networks, forcing processors to absorb obsolete inventory costs during ANMAT-mandated recipe changes. Active ingredient supply concentrates in China, Germany, and the Netherlands for synthetic benzoates and sorbates. Raw material dependencies include petrochemical feedstocks for synthetic antimicrobials, corn-derived substrates for fermentation processes, and specialized citrate precursors for pH control agents. Single-source vulnerability on imported sorbates exposes formulators to supply interruptions. Distribution runs through Cargill's Pampas grain origination network for bulk liquid formulations and fragmented regional distributors for powder formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's food preservative market operates under supply-constrained conditions where domestic biotechnology capacity bottlenecks prop pricing premiums for fermentation-derived alternatives. Formulation chemist scarcity and ANMAT registration backlogs compound capacity limitations.
For Market Incumbents: Lock in multi-year volume commitments with Pampas meat conglomerates before pending equivalence determinations redirect procurement toward natural alternatives. Backward integration into captive fermentation capacity in Buenos Aires province defends margin position against Kerry Group's specialized blend competition. Secure SENASA pre-certification for export-bound formulations to preempt competitor qualification timelines. For New Entrants and Emerging Players: Capture untapped artisanal cheese production in Chubut and Santa Cruz provinces through regional distribution partnerships with dairy cooperatives. Digital e-procurement platforms targeting Córdoba's fragmented baked goods manufacturers offer lowest competitive density. Lead with pH control agent specialization where technical service requirements deter commodity chemical incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with Argentine biotechnology specialists possessing nisin and natamycin production capabilities given ANMAT's pending natural preservative equivalence framework. Long-term viability favors fermentation-derived solution providers over synthetic chemical distributors. Monitor SENASA consultation timelines on botanical preservative efficacy claims as inflection indicator for R&D redirection toward clean-label alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive nisin production aligns with ANMAT's clean-label trajectory and reduces import dependency. |
| SENASA Pre-Certification Investment | Early EU-equivalent validation secures preferential positioning for export-bound meat processing contracts. |
| Regional Distribution Network Buildout | Patagonia dairy cooperative partnerships unlock first-mover advantage in Chubut's artisanal cheese segment. |
| Digital E-Procurement Platform Launch | Direct-to-processor channels bypass traditional distributor markups in Córdoba's fragmented baked goods sector. |
| Formulation Chemist Training Partnership | University alliances address technical talent scarcity constraining precision preservative development. |
Study Parameters
Multi-period observation of ANMAT regulatory consultations, SENASA certification timelines, and Pampas meat processor procurement patterns anchored the trend analysis, supplemented by interviews with plant managers at integrated slaughter facilities, procurement leads at Buenos Aires dairy cooperatives, distribution channel partners, and technical R&D directors at fermentation facilities. Secondary validation drew from Argentine Food Code amendments, SENASA export statistics, customs records on preservative active ingredient imports, and SEC filings of multinational suppliers. Bottom-up demand modeling triangulated against top-down market sizing across preservative categories.
Segment-weighting approach distributed value estimates across product type, application, end user, and form dimensions, with additional weighting for ANMAT regulatory tier and SENASA export certification status. CAGRs were derived through regression analysis of historical procurement volumes and projected enforcement intensity across the analysis window. Forecast inputs incorporated ANMAT equivalence determination probabilities and Pampas meat conglomerate capacity expansion plans.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANMAT's final natural preservative efficacy standards and biotechnology capacity buildout timelines. Forecasts reflect assumptions on regulatory enforcement consistency and currency stability for imported active ingredients. Practitioners should monitor SENASA consultation publications and Buenos Aires province fermentation facility construction permits for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Food Grade Glycerin Market