
 Saudi Arabia Food & Beverage Market | 2026-2036
Saudi Arabia Food & Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Food & Beverage Market Insights
Smart cold-chain logistics and AI-driven demand forecasting is reconfiguring how perishable inventory moves from farm to shelf across Saudi Arabia. Almarai leverages its integrated dairy farming and processing network to sustain freshness guarantees in ambient desert conditions. The Coca-Cola Bottling Company of Saudi Arabia anchors its distribution through direct-store-delivery systems that control shelf presence in modern trade outlets. PepsiCo Saudi Arabia differentiates via localized flavor portfolios aligned with regional palate preferences.
The Saudi Arabia Food & Beverage sector encompasses the production, processing, packaging, and distribution of edible goods and potable liquids, spanning ambient-stable and temperature-controlled categories with halal certification as a mandatory compositional parameter. Its commercial purpose centers on nourishing a young, urbanizing population while supporting food security objectives under Vision 2030. Dairy products command the largest value pool among product types due to daily consumption frequency and premiumization in labneh and strained yogurt formats. Online retail represents the fastest-growing distribution channel as grocery delivery apps reshape household replenishment patterns. Households remain the dominant customer type, though restaurant and hotel procurement is intensifying as tourism and entertainment sectors expand.
SFDA mandates govern product registration, ingredient disclosure, and facility inspections for all domestic and imported food items. Halal certification requirements administered by SASO and religious oversight bodies shape both local production standards and import eligibility criteria. MOF's excise tax framework on sweetened beverages has redirected formulation strategies toward reduced-sugar variants. Stakeholders must monitor how evolving local content regulations and subsidy restructuring affect cost structures for imported raw materials versus domestically cultivated alternatives.
Market Dynamics
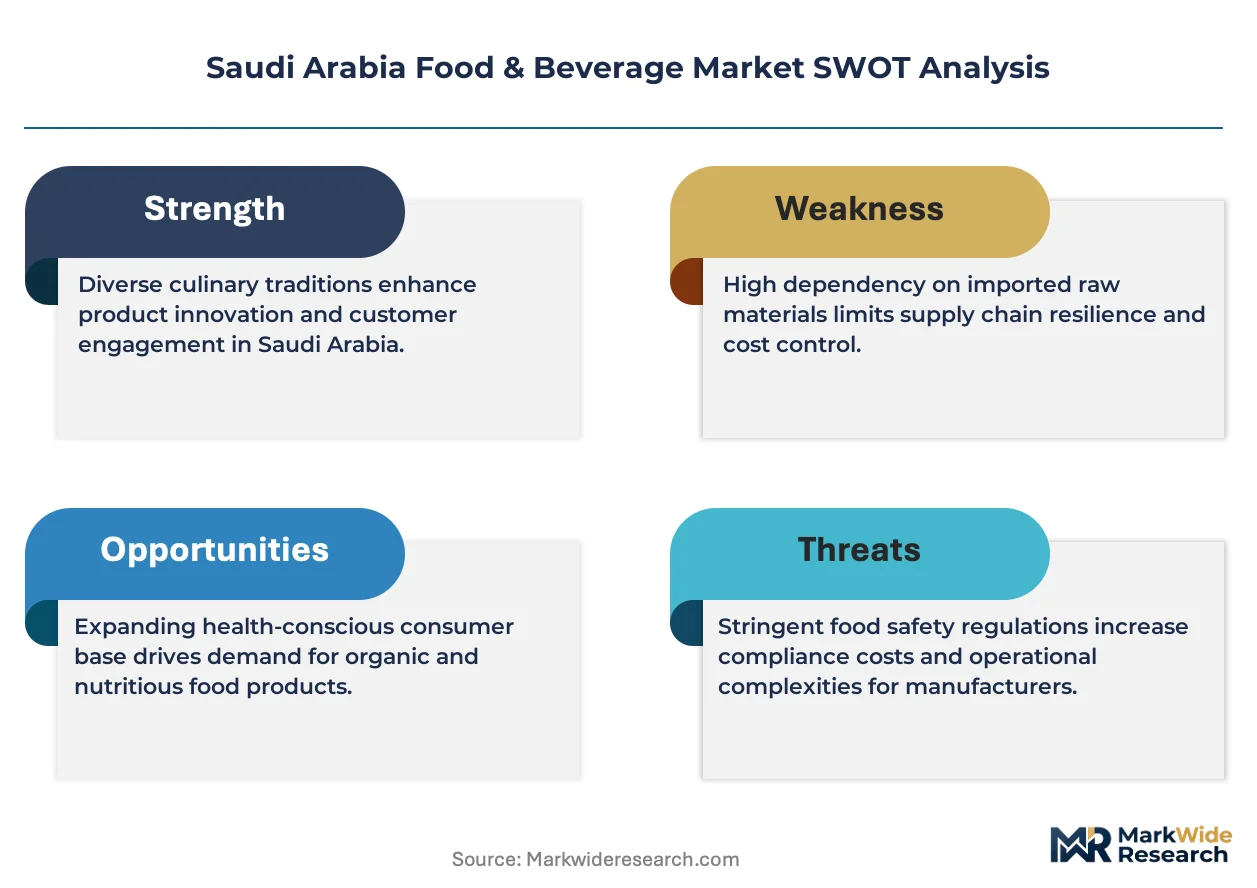
SFDA enforcement of updated labeling protocols and halal certification standards is compressing compliance timelines for domestic manufacturers while accelerating import substitution programs under Vision 2030 food security mandates.
Growth Catalysts
- Vision 2030 Localization Incentives:Government procurement preferences and subsidy restructuring for domestic agriculture are pulling multinational processors toward in-country ingredient sourcing.
- Smart Cold-Chain Expansion:IoT-enabled temperature monitoring and predictive logistics platforms are extending shelf-stable distribution reach into second-tier urban corridors.
- SFDA Streamlined Registration:Digital product registration portals and harmonized halal certification pathways are reducing time-to-market for compliant domestic formulations.
Market Restraints
- Feed Input Cost Volatility:Global grain and alfalfa price swings transmit directly into dairy and poultry production economics, compressing processor margins during import dependency.
- Water Scarcity Constraints:Desalination-dependent irrigation for domestic agriculture limits scale economics for fresh produce cultivation versus ambient-stable imports.
- Regulatory Friction on Imports:SASO technical barriers and extended halal certification timelines for foreign-origin goods create inventory risk for distributors reliant on global supply.
Strategic Opportunities
- Qassim and Asir Agricultural Zones:Underdeveloped highland farming regions offer land-lease incentives and water allocation for specialty crop cultivation targeting premium retail channels.
- Quick-Service Restaurant Supply Contracts:Chain expansion in entertainment and tourism zones is creating captive procurement demand for locally processed proteins and bakery inputs.
- Reduced-Sugar Formulation Tailwinds:MOF excise tax structures on sweetened beverages are redirecting R&D investment toward natural sweetener blends and functional beverage platforms.
Industry Challenges
- Specialized Food Safety Auditor Shortage:Limited pool of SFDA-accredited inspectors is extending facility certification timelines and delaying production ramp-ups.
- Legacy ERP Integration with Traceability Platforms:Mid-scale processors face capex burdens and system downtime risks when grafting blockchain or IoT modules onto existing inventory management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Food & Beverage Market |
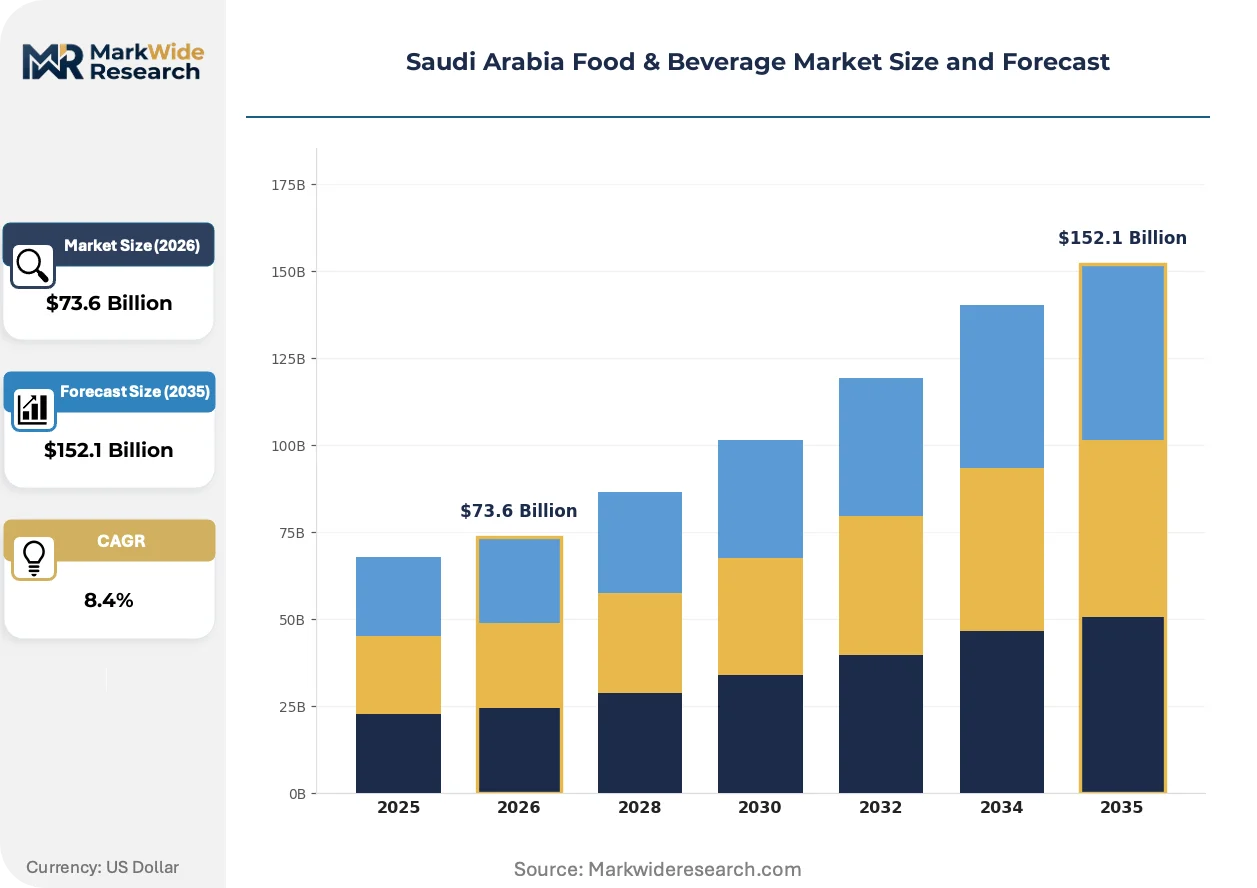
| Market Size in 2026 | $73.6 Billion |
| Market Size in 2035 | $152.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy Products, Baked Goods, Snacks, Beverages Distribution Channel: Supermarkets, Hypermarkets, Convenience Stores, Online Retail Customer Type: Households, Restaurants, Cafes, Hotels Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | National Agricultural Development Company (NADEC), The Coca-Cola Bottling Company of Saudi Arabia, Almarai, Arasco, Al Rabie Saudi Foods Co. Ltd., Savola Group, PepsiCo Saudi Arabia, Almunajem Foods, SADAFCO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Food & Beverage Market Trends and Innovations
Digital traceability systems and AI-driven demand sensing are compressing replenishment cycles while repositioning freshness guarantees as a competitive differentiator in ambient desert distribution environments.
Blockchain-enabled farm-to-fork traceability platforms are rendering obsolete paper-based batch documentation and manual recall procedures. Large-format retail chains and hospitality procurement desks are mandating real-time provenance verification for high-value protein and dairy categories. This transparency infrastructure is compressing supplier qualification timelines while raising compliance barriers for non-integrated competitors.
SFDA's phased implementation of front-of-pack nutritional labeling and allergen disclosure mandates is forcing reformulation across processed snack and beverage portfolios. Manufacturers are consolidating SKUs to reduce label complexity while accelerating clean-label ingredient substitution programs. The dairy and bakery segments face the steepest adaptation curves given multi-component recipes and extended shelf-life requirements.
Household replenishment patterns are fragmenting across channel types as grocery delivery apps capture urban pantry-stocking occasions. Hypermarket operators are responding with dark-store micro-fulfillment models targeting sub-one-hour delivery windows. Riyadh and Jeddah corridors exhibit the densest adoption of subscription-based dairy and fresh produce auto-replenishment programs.
Saudi Arabia Food & Beverage Market Segmentation
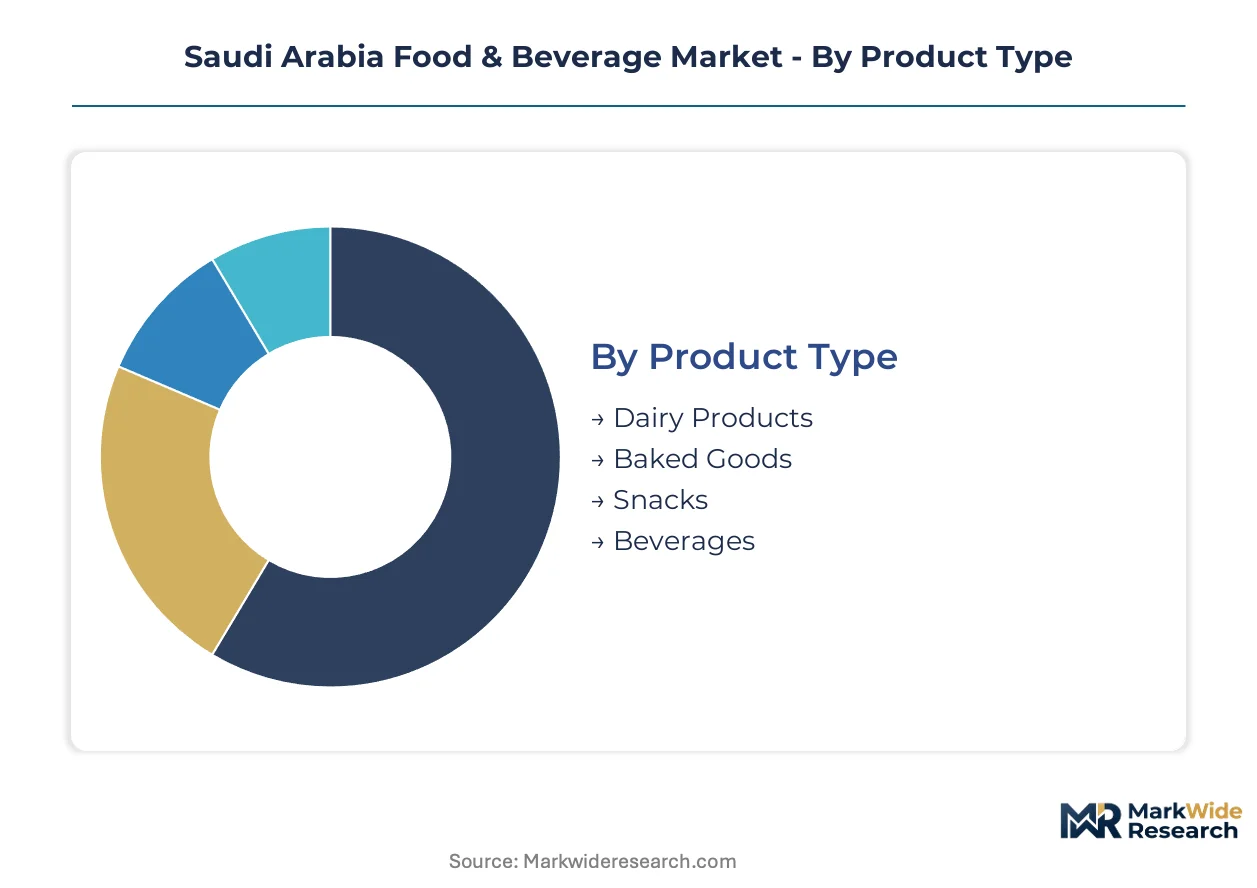
Saudi Arabia's food and beverage segmentation reflects divergent velocity profiles across consumption occasions. Dairy and bakery categories turn inventory daily while ambient snacks and beverages stretch replenishment cycles. Channel and customer stratification further fragments demand signals across Riyadh-Jeddah corridors versus emerging secondary cities.
Product Type:
Cycle times separate perishables from shelf-stable formats, with refrigeration-dependent categories commanding operational intensity.
- Dairy Products:Labneh, fresh milk, and strained yogurt require cold-chain integrity from Almarai's integrated farms through retail display. Daily consumption frequency in Saudi households sustains the category's revenue concentration, though water-scarce feed economics compress processor margins.
- Baked Goods:Flatbreads, pastries, and artisan loaves carry 3-7 day freshness windows that strain distribution coordination. QSR procurement in entertainment zones and tourism districts is pulling industrial bakery capacity toward contract manufacturing arrangements.
- Snacks:Ambient-stable chips, nuts, and confectionery tolerate extended shelf presence. SFDA's front-of-pack labeling mandates are forcing sodium and sugar reformulation across processed portfolios.
- Beverages:Carbonated, juice, and functional drink segments face MOF excise tax pressure on sweetened variants. Reduced-sugar R&D pipelines and natural sweetener substitution now dominate manufacturer investment.
Dairy Products dominates installed base. Beverages is where expansion concentrates.
Distribution Channel:
Capital intensity and fulfillment speed create a hierarchy from sprawling hypermarket footprints to algorithmic last-mile logistics.
- Supermarkets:Neighborhood-format operators like Al Othaim and Tamimi balance SKU breadth with convenience positioning. Riyadh's dense residential clusters sustain their replenishment frequency advantage over hypermarket destinations.
- Hypermarkets:Carrefour and Lulu anchor suburban retail with one-stop household stock-up missions. Dark-store micro-fulfillment retrofits are compressing delivery windows to under one hour in Jeddah corridors.
- Convenience Stores:Small-footprint urban outlets capture impulse and immediate-consumption occasions. Petromin and other fuel-retail hybrids are expanding fresh food and beverage adjacencies.
- Online Retail:Grocery delivery apps and subscription auto-replenishment are climbing the fastest. Jahez, HungerStation, and dedicated supermarket platforms fragment pantry-stocking behavior away from physical formats.
Hypermarkets command the largest physical footprint. Online Retail is gaining share fastest.
Customer Type:
Procurement scale and specification rigor separate institutional buyers from fragmented household demand.
- Households:Weekly stock-up missions and emergent app-based replenishment define consumption. Halal certification and date-label vigilance shape purchase criteria across income tiers.
- Restaurants:Quick-service chains and full-service operators demand consistent ingredient specification with volume discounts. Vision 2030 entertainment and tourism zone expansion is accelerating captive procurement demand.
- Cafes:Specialty coffee and tea venues prioritize premium dairy and alternative milk formats. Jeddah's coastal cosmopolitan corridors concentrate this segment's growth.
- Hotels:International hospitality brands impose global food safety and traceability standards on local suppliers. Haramain high-speed railway corridor developments are expanding room inventory and F&B service requirements.
Households anchor volume throughput. Restaurants concentrate procurement innovation.
Price Tier:
Margin architecture stratifies across certification grade, ingredient provenance, and packaging sophistication rather than pure performance differentiation.
- Premium:Organic, imported, and specialty-positioned offerings command shelf space in Riyadh's upscale retail corridors. SASO quality mark and international certification stacking justify price elevation.
- Mid-Range:Domestic branded alternatives balance quality signaling with household budget constraints. Almarai and Saudi dairy cooperatives anchor this tier's supply security.
- Economy:Private-label and basic commodity formats serve price-sensitive segments. Government subsidy pass-through on domestically cultivated inputs supports margin sustainability.
- Value:Promotional and bulk-packaged offerings capture stock-up occasions. Hypermarket operators use this tier to drive traffic and basket size expansion.
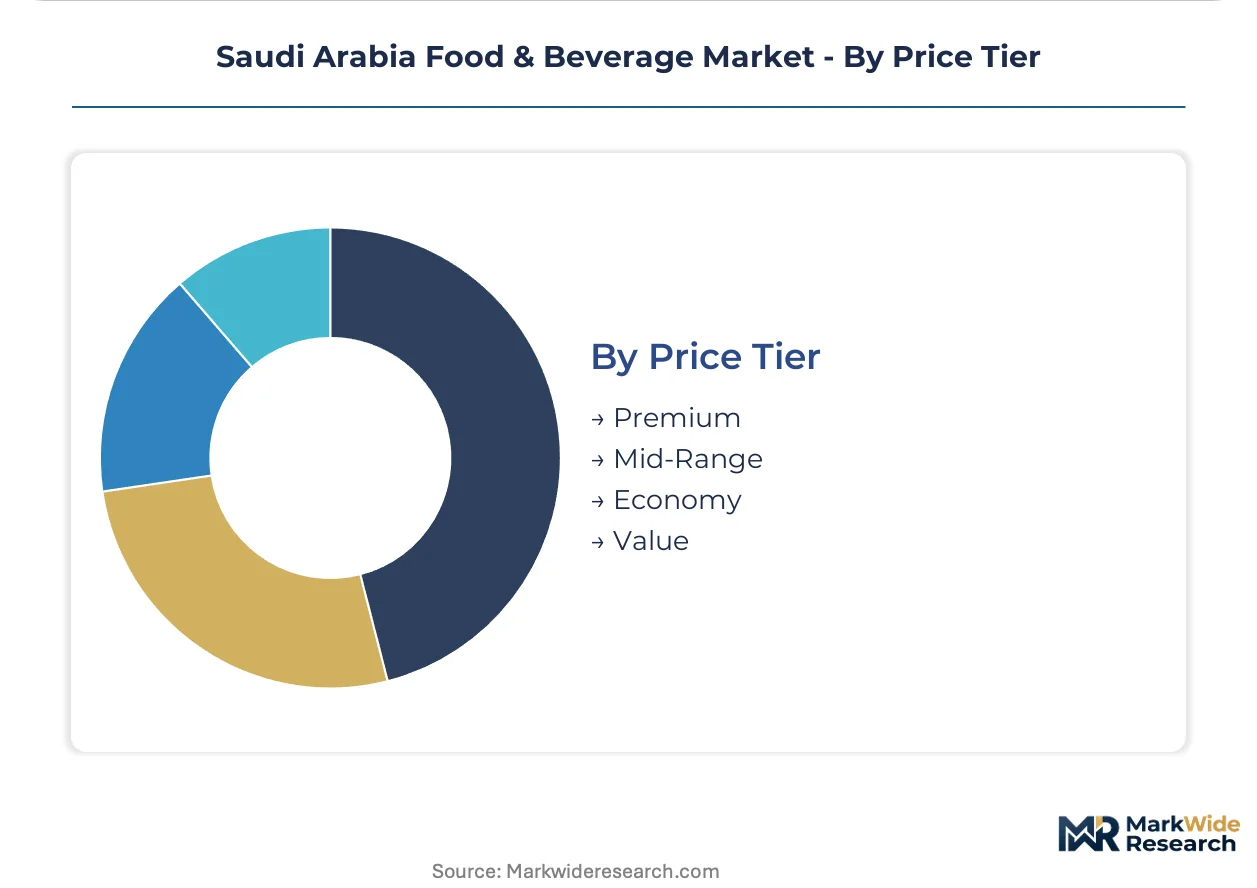
Mid-Range holds the broadest household penetration. Premium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports processed dairy and ambient beverages across Gulf Cooperation Council corridors, with UAE and Kuwait absorbing premium packaged goods volumes. Domestic production clusters concentrate around Riyadh and Jeddah distribution hubs serving both local consumption and re-export demand.
Riyadh
Central region households drive dairy and fresh bakery consumption at daily replenishment frequencies. SFDA's centralized product registration portal accelerates domestic formulation approvals for processors headquartered in the capital. King Abdullah Food Security City anchors integrated dairy farming and processing capacity with direct rail links to Dammam port.
Eastern Province
Petrochemical adjacent industries supply packaging materials and food-grade plastics to downstream processors. SASO's proximity to Jubail industrial city streamlines halal certification audits for export-oriented manufacturers. Dammam's King Abdulaziz Port handles bulk grain imports feeding Arasco's feed milling and protein processing operations.
Western Region
Jeddah's coastal cosmopolitan corridors concentrate specialty coffee, premium dairy, and hospitality procurement demand. MOF's customs modernization at Jeddah Islamic Port reduces dwell times for temperature-sensitive imports from European suppliers. Makkah and Madinah pilgrimage traffic sustains institutional food service volumes with strict halal traceability requirements.
NEOM Northwest
Green hydrogen-powered desalination and controlled-environment agriculture projects target food security localization mandates. NEOM's regulatory sandbox allows SFDA pilot programs for blockchain-enabled supply chain verification. The Line's planned vertical farming districts aim to reduce vegetable import dependency through solar-powered hydroponic cultivation.
Qassim
Highland agricultural zones receive subsidized water allocations for date cultivation and specialty crop experimentation. Ministry of Environment, Water and Agriculture land-lease incentives attract dairy processors seeking feed crop security. Buraydah's central location between Riyadh and Eastern Province distribution networks supports regional cold-chain consolidation.
Saudi Arabia Food & Beverage Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Saudi Arabia's food and beverage sector. National dairy and beverage processors dominate modern trade shelf presence through direct-store-delivery infrastructure. Three strategic archetypes prevail: integrated farm-to-shelf operators, multinational bottling licensees, and regional trading houses controlling import distribution. Competitive moves concentrate on backward integration into feed cultivation and forward integration into quick-service restaurant supply contracts.
Among integrated dairy specialists, Almarai exemplifies captive supply chain control from alfalfa cultivation through retail distribution. The Coca-Cola Bottling Company of Saudi Arabia occupies a position as the licensed anchor for carbonated beverage category management in modern trade channels. Savola Group represents diversified food holding structures spanning edible oils, retail operations, and processed dairy interests.
| Leading Market Players |
|---|
| National Agricultural Development Company (NADEC) |
| The Coca-Cola Bottling Company of Saudi Arabia |
| Almarai |
| Arasco |
| Al Rabie Saudi Foods Co. Ltd. |
| Savola Group |
| PepsiCo Saudi Arabia |
| Almunajem Foods |
| SADAFCO |
| Others |
Pricing and Supply Chain Analysis
Feed input cost volatility from global grain and alfalfa markets compresses processor margins while simultaneously widening spreads between premium domestic dairy and economy imported alternatives, forcing supply chain reconfiguration toward in-country cultivation.
Pricing Analysis
Current-generation cold-chain logistics pricing sits at a premium to conventional ambient distribution, while next-generation blockchain-enabled traceability commands further elevation. Three-tier pricing structure across premium, standard, and economy levels stratifies by halal certification grade and volume scale. Cost compression in the economy tier is intensifying because government subsidy restructuring on imported feed inputs is transmitting directly to shelf prices. Quick-service restaurant chains exhibit the lowest price sensitivity due to captive procurement contracts, while household replenishment through grocery delivery apps shows highest elasticity.
Supply Chain Analysis
SASO technical barriers and extended halal certification timelines for foreign-origin goods function as de facto export controls limiting import flows. Geographic supply concentration centers on domestic Saudi production clusters, with secondary sourcing from UAE re-export hubs and European specialty ingredient suppliers. Raw material dependencies rest on imported grain and alfalfa for dairy feed, desalinated water for irrigation, and food-grade packaging from Jubail petrochemical corridors. Single-source vulnerability runs through the limited pool of SFDA-accredited auditors extending facility certification timelines. Distribution runs through direct-store-delivery systems anchored by integrated processors and hypermarket dark-store micro-fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of SFDA-accredited food safety auditors and blockchain-traceability engineers constrains production ramp-ups and compliance timelines, making specialized certification capabilities the decisive competitive asset.
For Market Incumbents: Build captive halal certification infrastructure by training in-house auditors to SFDA accreditation standards and acquiring blockchain traceability platforms for farm-to-fork verification. Almarai's integrated model demonstrates how backward integration into alfalfa cultivation insulates margin compression from global feed price swings. Securing exclusive supply contracts with expanding quick-service restaurant chains in entertainment zones locks in volume throughput against emerging dairy cooperatives. For New Entrants and Emerging Players: Qassim highland agricultural zones with subsidized water allocations represent the most penetrable entry point for specialty crop cultivation targeting premium retail channels. Reduced-sugar beverage formulation white-space, accelerated by MOF excise tax structures, offers R&D-focused entrants a regulatory-tailwind category. A go-to-market angle emphasizing localized flavor portfolios aligned with regional palate preferences bypasses incumbent brand equity in carbonated drinks. For Investors and Strategic Acquirers: SFDA's phased implementation of front-of-pack nutritional labeling reshapes the acquisition landscape toward processors with clean-label reformulation capabilities already deployed. Long-term viability over the coming decade hinges on water-scarce feed economics and desalination-powered agricultural technology. Acquisition target archetype: mid-scale processors with legacy ERP systems ripe for IoT-module integration and traceability platform grafting. The signal to watch is Ministry of Environment, Water and Agriculture land-lease incentive announcements in underdeveloped farming regions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Cultivation | Alfalfa farming in Qassim secures input cost stability against global grain volatility. |
| Blockchain Traceability Platform Deployment | SFDA pilot programs at NEOM validate farm-to-fork verification for premium retail channels. |
| Reduced-Sugar Formulation R&D | MOF excise tax structures redirect investment toward natural sweetener blends and functional beverages. |
| Quick-Service Restaurant Supply Contracts | Vision 2030 entertainment zone expansion creates captive procurement demand for locally processed proteins. |
| Dark-Store Micro-Fulfillment Retrofit | Hypermarket operators in Jeddah corridors compress delivery windows to under one hour. |
Research Methodology
Operator-level perspectives from dairy processing plant managers, SFDA regulatory affairs leads, hypermarket category buyers, quick-service restaurant procurement directors, and cold-chain logistics coordinators anchored the qualitative base. Primary interview findings were cross-referenced with secondary validation from SFDA product registration databases, SASO halal certification records, Ministry of Environment water allocation disclosures, and customs import manifests for grain and feed inputs. Bottom-up segment sizing and top-down macroeconomic triangulation converged on volume and value estimates.
Scenario-bracketing around feed input cost volatility, water scarcity constraints, and regulatory enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type cycle times, distribution channel capital intensity, customer procurement scale, and price tier certification requirements. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for Vision 2030 localization mandates and tourism sector expansion. Industry-specific forecast inputs incorporated desalination capacity buildout timelines and Qassim agricultural zone development trajectories.
Stress conditions across global grain price bands, SFDA auditor availability, and pilgrimage traffic volumes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy restructuring continuity and halal certification pathway harmonization. Material shifts in Saudi water policy or SASO import technical barriers would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Juice Concentrates Market
Beverages
NFC JUICE Market
Beverages
Cactus Water Market
Beverages
Bottled Air Market
Beverages
Italy Bottled Water Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Plant Based Protein Beverages Market
Beverages
Baby Drinks Market
Beverages
Craft Soda Market
Beverages
Morocco Bottled Water Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
Fruit Beverages Market
Beverages
Italy Probiotic Drinks Market
Beverages
Growlers Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Fiber Fortified Beverages Market