
 Vegan Collagen Protein Market | 2026-2036
Vegan Collagen Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Collagen Protein Market Insights
Precision fermentation of plant-derived collagen peptides is tilting production economics toward microbial chassis engineered for hydroxyproline-rich outputs. Geltor leverages this biomanufacturing platform to supply bio-identical collagen alternatives without animal inputs. Vital Proteins anchors the North American retail channel through mass-market powder distribution. Sunwarrior differentiates via whole-food protein blends that combine multiple plant bases for amino acid completeness.
Vegan collagen protein comprises recombinant or plant-sourced peptides formulated to replicate the glycine-proline-hydroxyproline triplet structure of Type I and III animal collagen, typically achieving 85-95% amino acid homology through yeast or bacterial expression systems. The ingredient serves primarily to support dermal extracellular matrix signaling and connective tissue synthesis in nutricosmetic and sports recovery applications. Powder formulations dominate current manufacturing throughput due to stability advantages in bulk handling and extended shelf life, while gummies capture disproportionate margin pools through unit-dose convenience positioning in beauty & personal care. Pea protein supplies the largest raw material base by volume, though brown algae protein exhibits the fastest trajectory as marine biotechnology firms scale polysaccharide-coupled extraction methods.
FDA GRAS self-determination governs ingredient safety notification for U.S. supplement manufacturers, while EFSA novel food assessments constrain European market entry timelines for fermentation-derived proteins. CSRD reporting requirements and EU Green Deal carbon accounting rules are pressuring cosmetic brands to document supply chain emissions from protein sourcing through finished goods. Stakeholders must weigh regulatory compliance investments against the pace at which national pharmacopeias adopt analytical standards for bio-equivalence to animal collagen.
Market Dynamics
Precision fermentation economics are restructuring competitive advantage in vegan collagen production, as microbial chassis engineering compresses unit costs and enables bio-identical peptide outputs that bypass agricultural supply chains entirely.
Growth Catalysts
- EU Green Deal carbon accounting:Cosmetic brands face mandatory Scope 3 disclosure requirements, accelerating defection from animal-derived inputs toward fermentation-based alternatives with auditable supply chains.
- Clean-label beauty positioning:German and United Kingdom retailers command premium shelf space for products bearing vegan certification, pulling formulation decisions upstream.
- Pea protein infrastructure:Existing extraction capacity from plant-protein processors provides immediate raw material availability without greenfield capital deployment.
Market Restraints
- EFSA novel food timelines:Fermentation-derived protein approvals average 18-24 months, gating European market entry and freezing launch pipelines.
- Hydroxyproline synthesis costs:Microbial production of this critical amino acid residue remains 3-4x above animal-extraction benchmarks, constraining margin expansion.
- Single-source bioreactor dependency:Contract fermentation capacity concentrates among three North American CDMOs, creating supply vulnerability.
Strategic Opportunities
- Brown algae protein scale-up:Marine biotechnology firms in Norway and Iceland are commercializing polysaccharide-coupled extraction methods with superior amino acid profiles.
- Sports recovery applications:Functional beverage brands seek connective-tissue signaling claims for post-workout positioning, expanding beyond nutricosmetic core.
- CSRD-aligned procurement:Corporate sustainability reporting mandates create preferential purchasing terms for suppliers with verified carbon-negative production.
Industry Challenges
- Fermentation scale-up talent scarcity:Bioprocess engineers with industrial-scale microbial production experience command 40% salary premiums, constraining capacity expansion timelines.
- Analytical standardization gaps:National pharmacopeias lack harmonized bio-equivalence protocols for animal collagen comparison, freezing insurance reimbursement pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Collagen Protein Market |
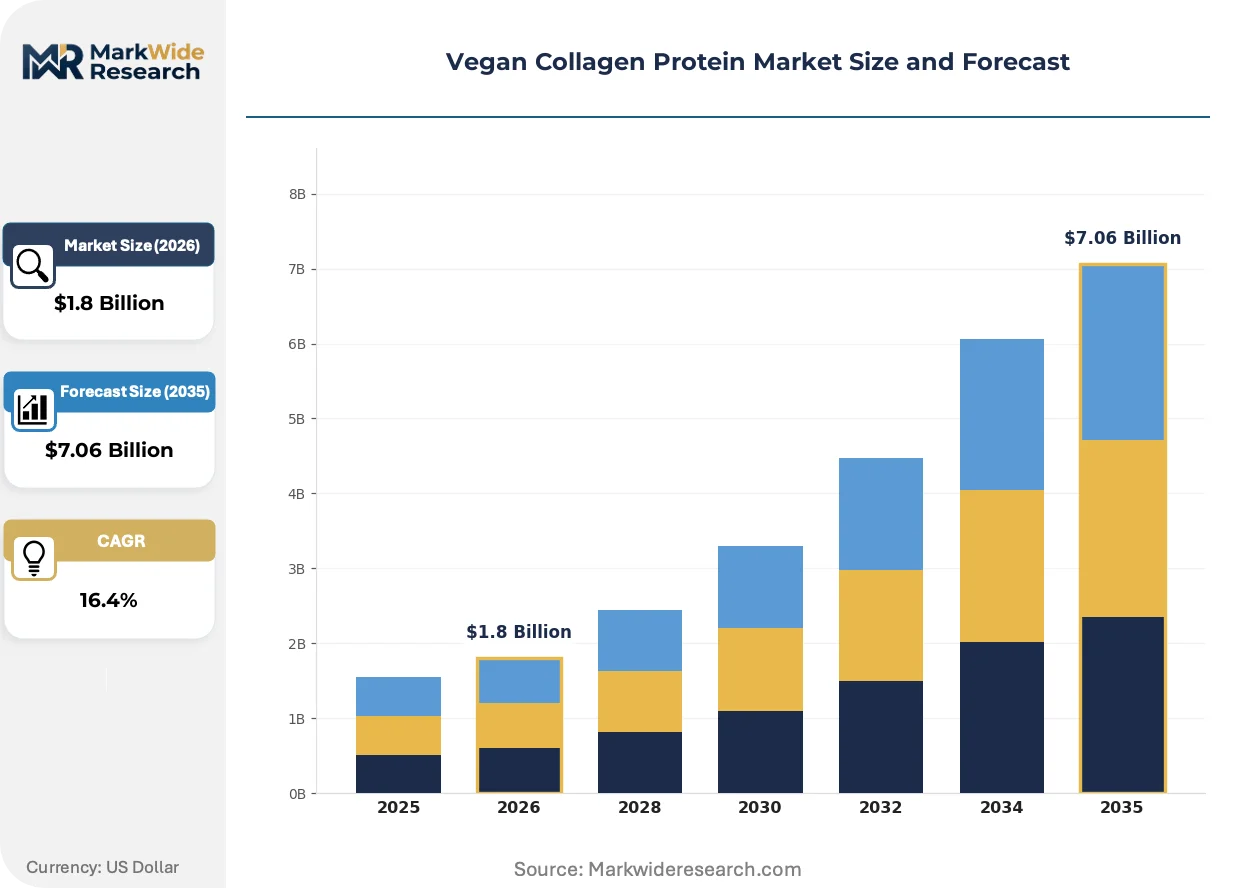
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Pumpkin Seed Protein, Rice Protein, Brown Algae Protein, Wheat Protein Application: Nutritional Supplements, Functional Foods, Sports Nutrition, Beauty & Personal Care, Infant Nutrition End User: Supplement Manufacturers, Food & Beverage Producers, Cosmetic Brands, Pharmaceutical Companies Form: Powder, Capsules, Liquid, Gummies, Tablets |
| Companies Covered | Revive Collagen, Geltor, Vital Proteins, Sunwarrior, Ancient + Brave, Raw Beauty Lab, Alpha Foods, VeCollal, OZiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Collagen Protein Market Trends and Innovations
Biomanufacturing platform convergence with marine biotechnology is erasing traditional boundaries between plant-derived and microbial protein sourcing, creating hybrid production architectures that optimize for amino acid completeness and carbon intensity simultaneously.
Precision fermentation of hydroxyproline-rich peptides is collapsing the cost differential between bio-identical vegan collagen and animal-extracted alternatives. Cosmetic formulators in Germany and the United Kingdom are adopting these inputs at contract volumes that now match pilot-scale animal collagen offtake. The technology is collapsing incumbent supplier margins and forcing backward integration decisions across the ingredient tier.
CSRD reporting requirements and EU Green Deal carbon accounting rules are mandating supply chain transparency from protein sourcing through finished goods. Cosmetic brands must now document emissions across Tier 2 and Tier 3 suppliers or face exclusion from retail partnerships. This regulatory pressure is most acute in France and the Netherlands, where supermarket chains have imposed 2027 deadlines for Scope 3 disclosure.
Clean-label certification has become a primary filter in professional and retail channel assortment decisions. German drugstore chains now require vegan collagen documentation for entry into dermocosmetic sets, displacing traditional animal-derived SKUs without equivalent positioning. This preference shift is most visible in mass-market beauty, where private-label penetration of vegan collagen powders exceeds branded alternatives in unit velocity.
Vegan Collagen Protein Market Segmentation
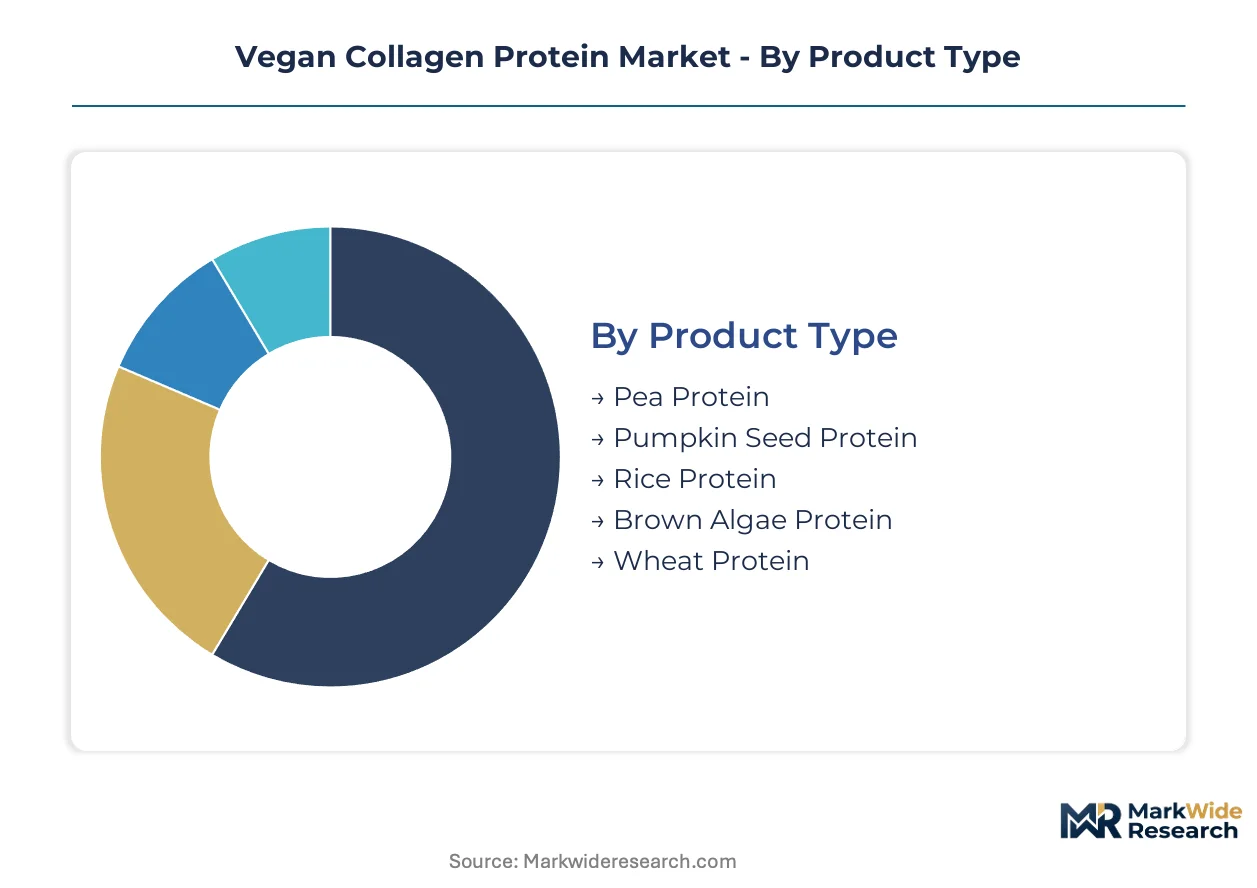
Vegan collagen protein serves divergent functional requirements across nutraceutical, food, and cosmetic value chains. Segmentation reveals how formulation chemistry and delivery format determine addressable margin pools and regulatory pathway complexity.
Product Type:
Plant protein feedstocks span legume, cereal, and marine biomass categories with distinct amino acid completeness profiles and extraction economics.
- Pea Protein:Yellow split pea isolate supplies the dominant raw material base by volume, leveraging established fractionation infrastructure in Canada and France. Nutritional supplement manufacturers in Germany anchor procurement contracts due to neutral flavor compatibility with unflavored powder positioning.
- Brown Algae Protein:Polysaccharide-coupled extraction from Ascophyllum and Laminaria species delivers superior hydroxyproline analog concentrations. Norwegian biotechnology firms are scaling commercial volumes as EFSA novel food pathways advance for marine-derived peptides.
- Pumpkin Seed Protein:Cucurbita pepo press cake yields complete amino acid profiles with allergen-free certification appeal. Functional food brands in the United Kingdom formulate clean-label bars around this input.
- Rice Protein:Oryza sativa brown rice isolate provides hypoallergenic positioning for infant nutrition applications. Asian contract manufacturers dominate extraction capacity.
- Wheat Protein:Triticum aestivum gluten-rich fractions offer cost-advantaged hydrolysates for cosmetic topical applications. Celiac sensitivity labeling constrains food-grade adoption.
Established volume favors pea protein; emerging adoption favors brown algae protein.
Application:
End-use segmentation tracks regulatory jurisdiction complexity and finished goods margin structure across five verticals.
- Nutritional Supplements:Powder and capsule formats dominate this core revenue pool, with FDA GRAS self-determination governing U.S. market entry. Direct-to-consumer subscription models in North America concentrate demand for unflavored bulk powders.
- Beauty & Personal Care:Nutricosmetic positioning commands premium unit economics through gummy and liquid delivery systems. EU Green Deal carbon accounting requirements are accelerating formulation switches from animal collagen in France and the Netherlands.
- Functional Foods:Beverage fortification and bakery applications require heat-stable protein isolates. Japanese functional food regulations under FOSHU framework create specialized pathway requirements.
- Sports Nutrition:Post-workout recovery claims drive demand for rapid-digesting hydrolysates. German fitness nutrition brands lead adoption of fermentation-derived bio-identical peptides.
- Infant Nutrition:Hypoallergenic protein requirements and stringent safety dossiers limit supplier qualification. Rice protein concentrates serve this segment due to documented tolerance profiles.
Beauty & personal care captures the steepest expansion trajectory; nutritional supplements retain the deepest volume base.
End User:
Customer type segmentation reflects divergent procurement sophistication and specification stringency across value chain tiers.
- Cosmetic Brands:L'Oréal and Unilever-scale beauty houses demand carbon-negative supply chain documentation under CSRD reporting mandates. Clean-label certification has become a mandatory gate for dermocosmetic line inclusion in German drugstore channels.
- Supplement Manufacturers:Capsule and tablet contract packagers prioritize powder flowability and compressibility specifications. U.S. West Coast CDMOs concentrate formulation expertise.
- Food & Beverage Producers:CPG giants require thermal stability and neutral flavor masking for beverage applications. Pea protein isolates with 80%+ protein content dominate procurement tenders.
- Pharmaceutical Companies:Excipient-grade specifications and pharmacopeial compliance create entry barriers. Hydroxyproline content standardization remains unresolved across national compendia.
Cosmetic brands drive specification escalation; supplement manufacturers absorb the highest volume throughput.
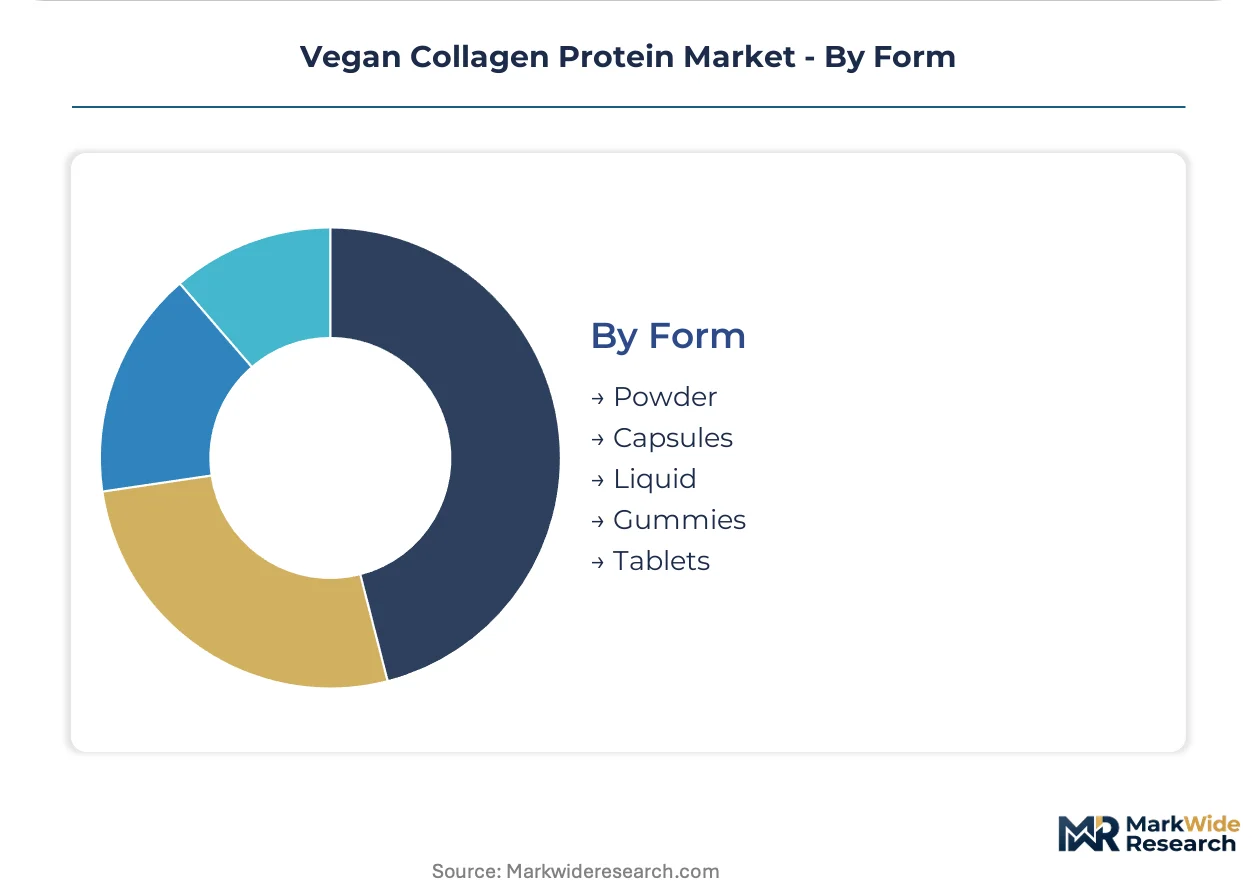
Form:
Delivery format determines stability requirements, dosing precision, and margin capture across the value chain.
- Powder:Bulk handling efficiency and 24-month shelf stability make this the manufacturing throughput leader. German and U.S. contract manufacturers maintain the largest spray-drying and agglomeration capacity.
- Gummies:Unit-dose convenience and beauty-positioning compatibility generate disproportionate margin pools. Pectin-based vegan gelatin alternatives enable clean-label claims in United Kingdom retail.
- Capsules:Two-piece hard shell and soft gel formats serve pharmaceutical-grade dosing requirements. HPMC vegetarian capsules have displaced gelatin in premium positioning.
- Liquid:Ready-to-drink functional beverages require aseptic processing and cold chain logistics. Japanese and South Korean markets show concentrated adoption.
- Tablets:Direct compression and wet granulation methods suit high-volume, low-margin production. Sports nutrition brands favor this format for cost-sensitive distribution.
Powder commands manufacturing scale; gummies are climbing the fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in vegan collagen protein tilt heavily toward import-dependent European markets, while North American and Asian producers supply fermentation-derived and plant-extracted volumes. Germany and the United Kingdom absorb the largest inbound shipments, driven by cosmetic brand procurement and clean-label retail mandates.
Germany
Drugstore chains and dermocosmetic brands command formulation switches toward vegan-certified inputs. ECHA registration requirements under REACH govern novel protein ingredient safety dossiers. The Rhine-Ruhr industrial corridor hosts contract manufacturers scaling spray-drying capacity for powder exports across the EU.
United Kingdom
Beauty retailers impose vegan certification as a mandatory gate for shelf placement in nutricosmetic sets. The Food Standards Agency enforces novel food assessments for fermentation-derived peptides entering the market. London-based formulation houses partner with marine biotechnology firms to secure brown algae protein supply.
United States
Direct-to-consumer subscription models concentrate demand for unflavored bulk powders among precision fermentation suppliers. FDA GRAS self-determination enables rapid market entry without pre-market approval timelines. West Coast CDMOs in California and Oregon dominate contract manufacturing capacity for capsule and tablet formats.
France
Supermarket chains have imposed 2027 deadlines for Scope 3 carbon disclosure across cosmetic ingredient supply chains. ANSM oversees safety assessments for topical and ingestible collagen alternatives. The Île-de-France region anchors headquarters for multinational beauty houses driving procurement specification escalation.
Norway
Marine biotechnology firms commercialize polysaccharide-coupled extraction methods for brown algae protein with superior hydroxyproline analog concentrations. The country's national food safety authority advances EFSA-aligned novel food pathways for marine-derived peptides. Coastal processing clusters in Trøndelag scale commercial fermentation capacity for export to German and UK cosmetic brands.
Vegan Collagen Protein Market Competitive Landscape
On the supply side, the industry is bifurcating between precision fermentation specialists and plant-protein processors with established extraction infrastructure. Tier-one players leverage microbial chassis engineering to bypass agricultural supply chains entirely, while mid-tier competitors rely on pea and rice protein fractionation from existing capacity. Three archetypes dominate: biomanufacturing platform operators, whole-food protein blenders, and marine biotechnology specialists. Capacity expansion and backward integration into raw material sourcing represent the dominant competitive moves.
Within the biomanufacturing tier, Geltor exemplifies platform-based production of bio-identical peptides without animal inputs. Vital Proteins and Sunwarrior occupy distinct positions in the branded consumer products segment, with the former anchoring mass-market retail distribution and the latter representing whole-food formulation approaches. These three companies illustrate the strategic divergence between microbial production and plant-based sourcing architectures.
| Leading Market Players |
|---|
| Revive Collagen |
| Geltor |
| Vital Proteins |
| Sunwarrior |
| Ancient + Brave |
| Raw Beauty Lab |
| Alpha Foods |
| VeCollal |
| OZiva |
| Others |
Pricing and Supply Chain Analysis
Three North American CDMOs hold captive contract fermentation capacity, funneling margin capture toward cosmetic brands with carbon-negative supply chain documentation under CSRD mandates. Pea protein fractionation in Canada and France anchors economy-tier powder pricing, while precision fermentation hydroxyproline outputs command premium positioning in German dermocosmetic channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in this market. Certification grade under EU Green Deal carbon accounting protocols and volume scale in powder offtake contracts serve as the primary price differentiation drivers. Cost compression in standard-tier pea protein isolates is intensifying because brown algae protein scale-up in Norway erodes amino acid completeness premiums. Mass-market supplement manufacturers exhibit the highest price sensitivity, whereas L'Oréal-scale cosmetic houses absorb premium fermentation-derived peptide costs without volume negotiation.
Supply Chain Analysis
West Coast CDMOs in California and Oregon concentrate contract manufacturing capacity for capsule and tablet formats, while spray-drying clusters in Germany's Rhine-Ruhr corridor handle powder exports. Raw material flows draw from yellow split pea isolate in Canada, Ascophyllum and Laminaria biomass in Norway, and rice protein concentrates across Asian extraction facilities. Single-source bioreactor dependency among the three dominant North American fermentation operators creates acute supply vulnerability. Distribution runs through direct-to-consumer subscription models in the United States and beauty retailer procurement gates in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan collagen protein sits in early-cycle expansion, with EU Green Deal Scope 3 disclosure mandates accelerating cosmetic brand procurement switches from animal-derived inputs.
For Market Incumbents: Insulate fermentation-derived peptide margins through backward integration into microbial chassis engineering capabilities, neutralizing the 3-4x hydroxyproline synthesis cost penalty against animal extraction benchmarks. Capture capacity addition in Norway's coastal processing clusters to secure brown algae protein feedstock ahead of EFSA novel food pathway completions. Lock in long-term offtake contracts with German drugstore chains before clean-label certification becomes a mandatory gate for dermocosmetic line inclusion. For New Entrants and Emerging Players: Sports recovery applications in functional beverage positioning represent the most penetrable entry point, as German fitness nutrition brands actively seek connective-tissue signaling claims beyond traditional nutricosmetic cores. Marine biotechnology partnerships in Iceland and Norway unlock polysaccharide-coupled extraction methods with superior amino acid profiles unavailable to legacy pea protein processors. A direct-to-clinical channel strategy targeting dermatology practices in France bypasses saturated mass-market retail gates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation sub-segments as microbial chassis engineering compresses unit costs and enables bio-identical peptide outputs. The 5-10 year viability window favors platform-based biomanufacturing operators with demonstrated EFSA novel food pathway navigation over commodity plant-protein fractionators. Acquisition target archetypes include marine biotechnology specialists with scaled brown algae extraction and CDMOs with validated hydroxyproline-rich peptide production. The signal to watch is EFSA approval velocity for fermentation-derived proteins, as timeline compression from 18-24 months would unlock frozen European launch pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Geltor's microbial chassis engineering collapses cost differentials against animal-extracted collagen benchmarks. |
| Marine Biotechnology Partnership | Norwegian brown algae protein commercialization secures hydroxyproline analog concentrations superior to legume isolates. |
| CSRD-Aligned Procurement Certification | Carbon-negative supply chain documentation satisfies French supermarket 2027 Scope 3 disclosure deadlines. |
| Direct-to-Consumer Subscription Launch | Unflavored bulk powder positioning in North America bypasses retailer margin extraction and captures recurring revenue. |
| EFSA Novel Food Pathway Navigation | Accelerated regulatory approval for fermentation-derived peptides unlocks frozen German and UK launch pipelines. |
Research Methodology
A standing panel of precision fermentation bioprocess engineers, cosmetic brand procurement directors, EFSA regulatory affairs consultants, and German drugstore category buyers provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA GRAS notification filings, EFSA novel food application databases, EU Green Deal implementation directives, and CSRD reporting framework guidance documents. Bottom-up volume estimates from ingredient supplier interviews triangulated against top-down cosmetic brand procurement surveys.
Scenario-bracketing framed analytical approach across the projection horizon, with base, optimistic, and conservative cases reflecting EFSA approval timeline variance and brown algae protein scale-up velocity. Segmentation dimensions modeled included product type, application vertical, end user archetype, and delivery format. CAGRs derived from S-curve penetration modeling against animal collagen displacement rates. Industry-specific forecast inputs incorporated hydroxyproline synthesis cost trajectories and clean-label certification adoption curves in German retail channels.
Macroeconomic conditions sit as an overlay; deviation in EU carbon pricing mechanisms or marine biomass harvest yields would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA regulatory velocity and precision fermentation scale-up economics. Quarterly review of novel food approval timelines and CDMO capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Melatonin Supplements Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Whey Protein Market