
 United States Offshore Support Vessels Market | 2026-2036
United States Offshore Support Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
United States Offshore Support Vessels Market Intelligence
Subchapter M compliance under U.S. Coast Guard regulations is rotating the competitive field toward operators with certified safety management systems and inspected towing vessels. Edison Chouest Offshore leverages its extensive Gulf Coast shipyard network to control newbuild capacity and crew training pipelines. Tidewater anchors its position through a diversified fleet spanning platform supply and anchor handling segments across multiple U.S. basins. SEACOR Marine Holdings specializes in premium-specification vessels for deepwater clients demanding enhanced station-keeping capabilities.
Offshore support vessels are purpose-built marine craft typically ranging from 150 to over 300 feet in length, designed to transport personnel, provisions, and equipment to fixed and floating offshore energy installations while maintaining dynamic positioning class notation for operations in sea states up to Beaufort scale 6. Platform supply vessels constitute the mature volume backbone of the U.S. fleet, with stable charter demand tied to Gulf of Mexico production maintenance cycles. Crew boats represent a faster-growing segment as offshore wind construction off Massachusetts and New York intensifies demand for rapid personnel transfer with reduced transit times. Multi-purpose vessels command premium day rates where installation and surveying capabilities merge into single-hull configurations.
The U.S. Coast Guard enforces Subchapter M towing vessel inspection regimes while the Maritime Administration administers Jones Act construction and manning requirements that shape fleet eligibility for domestic offshore work. Environmental compliance under EPA vessel general permit discharge standards adds operational cost layers that favor newer, treatment-system-equipped tonnage. Stakeholders must weigh charter-rate durability against capital commitments for dual-fuel or hybrid propulsion configurations as offshore energy customers harden decarbonization clauses in long-term agreements.
Market Dynamics
The U.S. offshore support vessel fleet faces simultaneous pressure from Jones Act construction mandates and offshore wind charter specifications that exceed legacy Gulf of Mexico vessel capabilities. This structural tension between protected domestic supply and evolving demand specifications is compressing effective fleet availability while elevating newbuild capital requirements.
Growth Catalysts
- Offshore Wind Installation Surge:Vineyard Wind and South Fork Wind projects off Massachusetts and New York are generating charter demand for turbine installation vessels and crew transfer boats that legacy oil-and-gas fleets cannot fulfill.
- Subchapter M Compliance Rotation:U.S. Coast Guard towing vessel inspection regimes are retiring non-compliant tonnage, creating replacement demand for certified operators with inspected vessel management systems.
- Gulf Coast Shipyard Concentration:Louisiana and Texas yards are consolidating newbuild capacity for platform supply and anchor handling vessels, shortening delivery timelines for domestic operators.
Market Restraints
- Steel and Engine Cost Volatility:Marine-grade steel and dual-fuel propulsion systems face input price swings that compress newbuild margins before charter rates stabilize.
- Specialized Vessel Supply Concentration:Wind turbine installation jack-ups and heavy-lift vessels remain concentrated among a handful of European and Asian builders, limiting Jones Act-compliant availability.
- EPA Vessel General Permit Friction:Discharge treatment system mandates add operational cost layers that disadvantage older tonnage without ballast water and graywater management retrofits.
Strategic Opportunities
- Mid-Atlantic Wind Lease Areas:Bureau of Ocean Energy Management lease blocks off New Jersey and Maryland remain underdeveloped, creating first-mover positioning for vessel operators with Jones Act-compliant installation assets.
- Hydrogen and Ammonia Fuel Convergence:Dual-fuel engine technology paired with alternative fuel bunkering infrastructure offers path to zero-emission vessel specifications demanded by European-owned wind developers.
- Integrated Service Contracting:Developers are consolidating turbine transport, foundation installation, and cable laying under single-vessel charters, rewarding multi-purpose vessel investments.
Industry Challenges
- Mariner Credentialing Bottlenecks:U.S. Coast Guard license processing delays and limited dynamic positioning operator training capacity are constraining crew availability for newbuild deliveries.
- Hybrid Propulsion Integration Complexity:Battery-hybrid and dual-fuel systems require shipyard retrofit expertise and vendor coordination that extends commissioning timelines beyond conventional diesel installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Offshore Support Vessels Market |
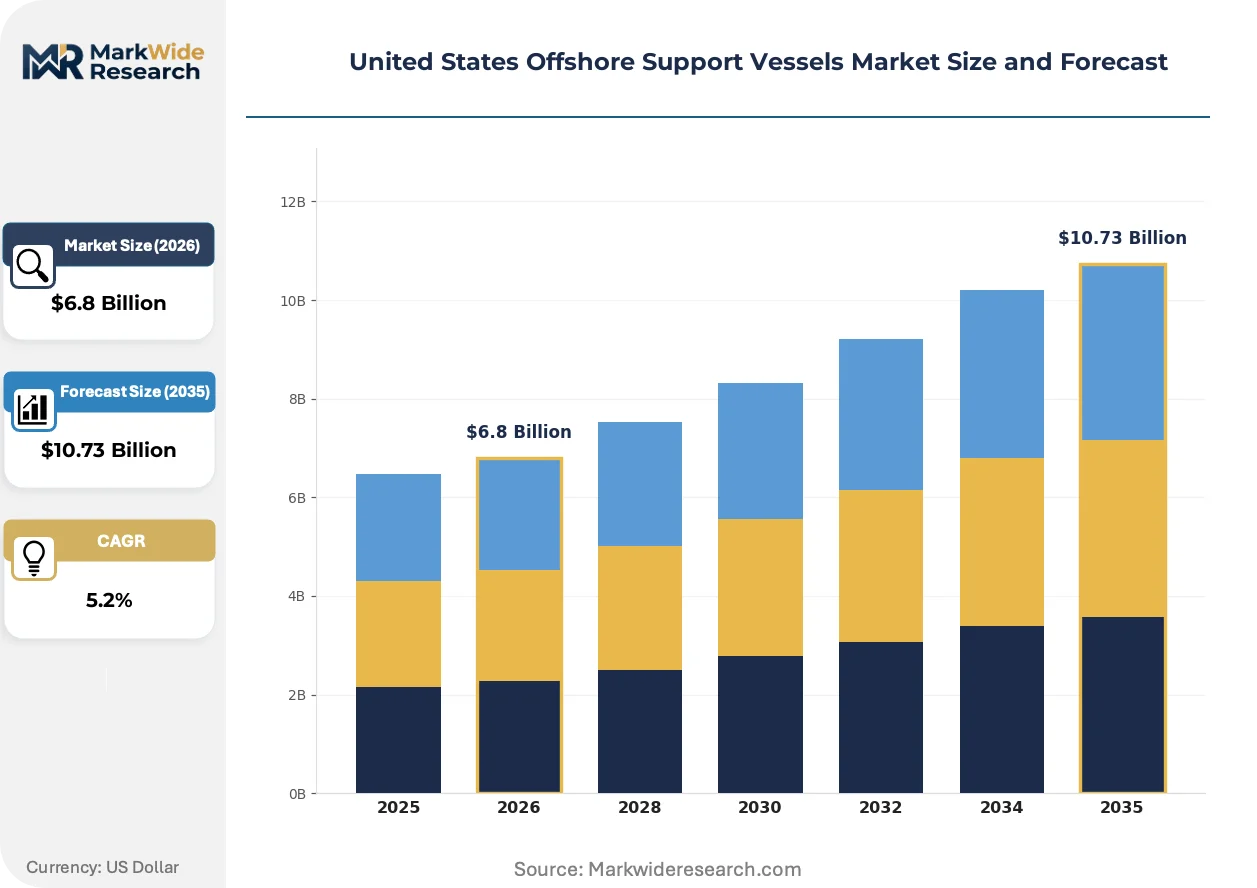
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Anchor Handling Tug Supply, Platform Supply, Crew Boat, Multi-Purpose Vessel End User: Oil & Gas, Renewables, Research, Government Service Type: Logistics Support, Maintenance, Surveying, Installation Size: Small, Medium, Large, Extra Large |
| Companies Covered | Edison Chouest Offshore, Crowley, Tidewater, Siem Offshore, Bourbon Maritime, SEACOR Marine Holdings, Harvey Gulf International Marine, Solstad Offshore, Hornbeck Offshore Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Offshore Support Vessels Market Strategic Shifts & Innovations
Propulsion technology and charter contracting models are actively restructuring competitive positioning in the U.S. offshore support vessel sector. Fleet operators are balancing decarbonization investments against charter rate durability in an environment where offshore wind specifications diverge from legacy oil-and-gas requirements.
Hybrid-electric propulsion architecture is decomposing conventional diesel-mechanical powertrain dominance in crew transfer and platform supply segments. Offshore wind developers with European parent companies are specifying battery-hybrid vessels for North Atlantic operations, compressing the viable lifespan of non-hybrid tonnage in premium charter markets. Shipyards in Louisiana are responding with parallel hybrid installations that maintain diesel redundancy while satisfying emission clauses.
The U.S. Coast Guard's Subchapter L implementation for offshore supply vessels is tightening intact stability and fire safety standards beyond existing international conventions. This regulatory divergence is forcing domestic operators into earlier vessel replacement cycles than global competitors face, elevating capital intensity for Jones Act-compliant fleets. Platform supply vessels operating in the Gulf of Mexico bear the heaviest retrofit burden as the inspection regime phases in through 2026.
Charter contracting is compressing toward performance-guaranteed availability terms rather than bareboat or time-charter structures with operational risk retained by the vessel owner. Offshore wind developers are transferring weather downtime and fuel cost exposure to operators, displacing traditional day-rate mechanisms. This shift is most visible in Massachusetts and New York lease areas where European project sponsors have imported contracting norms from North Sea developments.
United States Offshore Support Vessels Market Segmentation
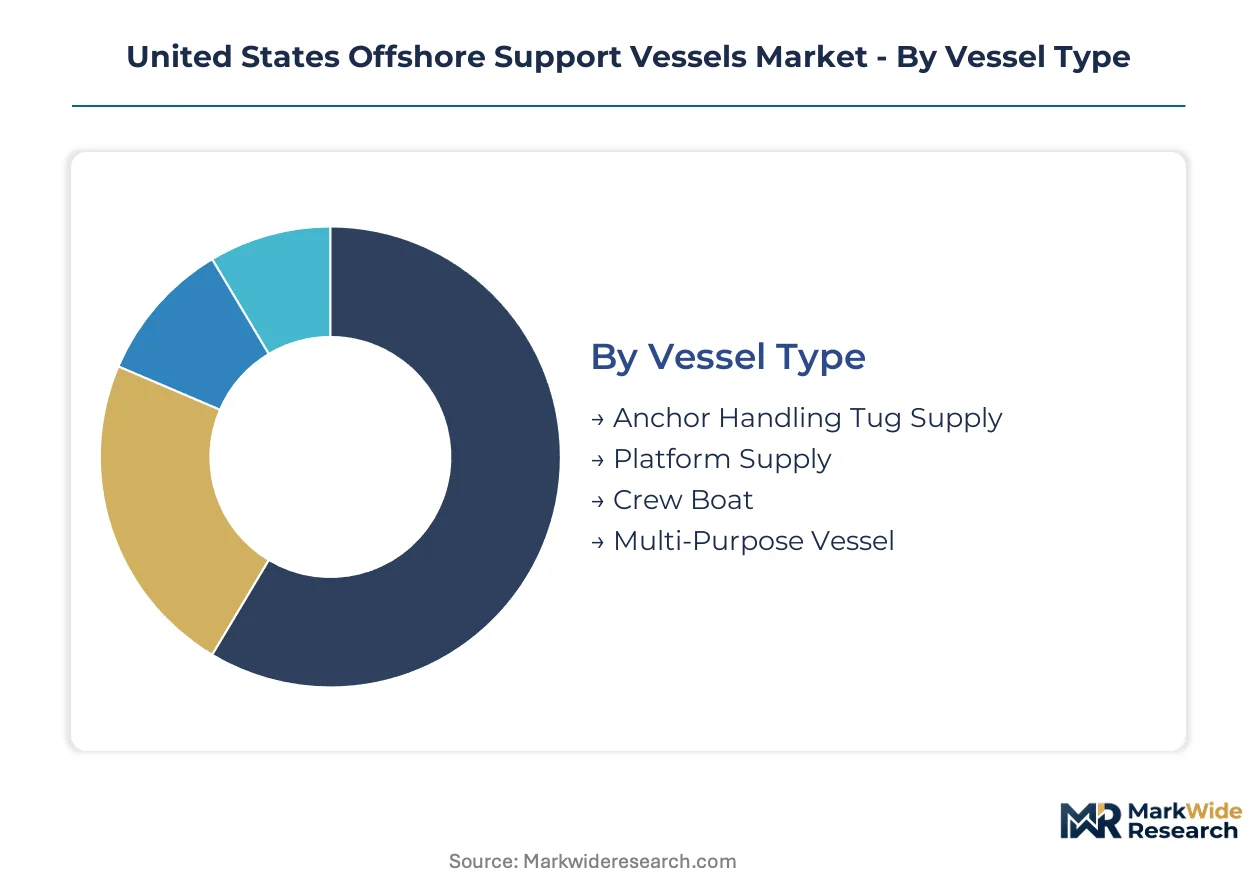
Vessel specifications and service requirements diverge sharply between offshore wind construction and legacy oil-and-gas maintenance, fragmenting charter demand across incompatible fleet categories. Regulatory mandates from the U.S. Coast Guard and EPA further stratify the competitive field by propulsion type and discharge compliance.
Vessel Type:
U.S. Coast Guard Subchapter M and Subchapter L regimes impose distinct inspection standards on towing versus supply vessels, creating regulatory moats around certified operators.
- Anchor Handling Tug Supply:Twin-screw vessels with 100-tonne bollard pull ratings anchor floating production platforms in Gulf of Mexico deepwater. Demand concentrates in Louisiana offshore corridors where tension-leg platform maintenance requires constant station-keeping support.
- Platform Supply:Open-deck cargo carriers with 1,000+ square metres of clear deck space transport drilling consumables to fixed-leg structures. Gulf Coast production maintenance cycles generate stable charter volumes, though day rates face pressure from aging diesel-mechanical tonnage.
- Crew Boat:Aluminum-hull fast supply vessels with 25-knot cruise speeds shuttle personnel to wind turbine installation sites off Massachusetts and New York. Reduced transit times command premium pricing against conventional platform supply alternatives.
- Multi-Purpose Vessel:Hybrid-propulsion hulls merge cable-laying carousels with subsea crane capacity for integrated offshore wind contracts.
Platform supply vessels handle the majority of throughput; crew boats are gaining share fastest as wind lease areas mature.
End User:
Customer procurement patterns split between capital-intensive installation projects and recurring operational expenditure budgets.
- Oil & Gas:Supermajor production subsidiaries charter on annual frameworks with fuel-cost pass-through clauses. Gulf of Mexico brownfield maintenance sustains demand for inspected towing vessels and platform supply tonnage.
- Renewables:European-owned wind developers specify battery-hybrid propulsion and dynamic positioning class notation in Requests for Proposal. Vineyard Wind and South Fork Wind sponsors impose North Sea contracting norms on U.S. operators.
- Research:Academic consortiums and oceanographic institutes charter multi-beam survey vessels for seabed mapping.
- Government:Maritime Administration and Navy Military Sealift Command procure Jones Act-compliant assets for strategic reserve.
Oil and gas retains the largest installed base of chartered vessels; renewables shows the steepest expansion trajectory on new contract awards.
Service Type:
Performance-guaranteed availability terms are displacing traditional time-charter structures as offshore wind sponsors transfer operational risk.
- Logistics Support:Provisions, spare parts, and personnel transport to fixed and floating installations. Gulf Coast operators dominate with established shore-base networks in Port Fourchon and Houma.
- Maintenance:Subsea inspection, repair, and maintenance using remotely operated vehicle launch capabilities. Demand clusters around aging Gulf of Mexico infrastructure requiring integrity management.
- Surveying:Geophysical and geotechnical site investigation for wind lease area characterization.
- Installation:Turbine component transport, foundation pile driving, and inter-array cable laying.
Logistics support commands the largest vessel-days; installation is climbing the fastest as wind construction accelerates.
Size:
Harbor infrastructure and Jones Act shipyard capacity constrain viable hull dimensions for domestic construction.
- Small:Crew boats under 150 feet length overall serving near-shore wind sites.
- Medium:Platform supply vessels between 150 and 220 feet with 2,500 deadweight tonnes capacity.
- Large:Anchor handling tug supply vessels exceeding 220 feet with 150-tonne bollard pull.
- Extra Large:Heavy-lift installation jack-ups and turbine installation vessels requiring specialized European or Asian construction.
Medium-size hulls carry the bulk of operational tonnage; extra-large vessels face the tightest supply constraints under Jones Act build requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind developers and Gulf of Mexico production operators concentrate procurement decisions in distinct coastal corridors, each imposing specialized vessel specifications that reshape regional fleet deployment patterns.
Gulf Coast
Louisiana and Texas anchor brownfield oil-and-gas maintenance demand, with tension-leg platform operations requiring constant anchor handling support. The U.S. Coast Guard enforces Subchapter M towing vessel inspection regimes that retire non-compliant tonnage. Port Fourchon and Houma host dense shore-base networks where shipyards consolidate newbuild capacity for platform supply vessels.
Northeast Atlantic
Vineyard Wind and South Fork Wind projects off Massachusetts generate charter demand for turbine installation vessels and crew transfer boats. EPA vessel general permit discharge standards add operational cost layers that favor newer, treatment-system-equipped tonnage. New Bedford and New London harbor infrastructure supports rapid personnel transfer operations with reduced transit times.
Mid-Atlantic
Bureau of Ocean Energy Management lease blocks off New Jersey and Maryland remain underdeveloped, creating first-mover positioning for Jones Act-compliant installation assets. State renewable portfolio standards accelerate procurement timelines. Baltimore and Philadelphia shipyards face pressure to adapt legacy repair capacity for hybrid-propulsion newbuilds.
Pacific Coast
Floating offshore wind proposals off California confront deeper water depths that exceed conventional jack-up capabilities. The California Air Resources Board imposes emission standards that compress viable lifespan of diesel-mechanical tonnage. Humboldt Bay and Port of Long Beach infrastructure investments aim to capture West Coast wind installation demand.
United States Offshore Support Vessels Market Key Industry Players
Player mix skews toward vertically integrated Gulf Coast operators with captive shipyard capacity. Three tiers structure competitive positioning: diversified fleet holding companies, specialized wind installation contractors, and regional platform supply operators. Consolidation pressure intensifies as charter contracting shifts toward performance-guaranteed availability terms. Scale advantages concentrate among operators controlling newbuild pipelines and Coast Guard-certified safety management systems.
Within the integrated-tier, Edison Chouest Offshore exemplifies shipyard-network control over crew training and vessel delivery timelines. Tidewater and SEACOR Marine Holdings occupy positions spanning multiple U.S. basins with diversified platform supply and anchor handling portfolios. These operators represent archetypes for navigating Subchapter M compliance rotation and offshore wind specification divergence.
| Leading Market Players |
|---|
| Edison Chouest Offshore |
| Crowley |
| Tidewater |
| Siem Offshore |
| Bourbon Maritime |
| SEACOR Marine Holdings |
| Harvey Gulf International Marine |
| Solstad Offshore |
| Hornbeck Offshore Services |
| Others |
Cost & Logistics Intelligence
Dual-fuel engine retrofits replacing conventional diesel-mechanical powertrains are redrawing Gulf Coast shipyard sourcing patterns while compressing newbuild margins before charter rates stabilize. This substitution dynamic concentrates vessel construction demand in Louisiana and Texas yards capable of hybrid propulsion integration, elevating pricing power for certified operators with inspected towing vessel management systems.
Pricing Analysis
Cost-plus contracts with marine-grade steel indexation dominate platform supply vessel charters in the Gulf of Mexico. Three-tier pricing structure across premium hybrid-propulsion, standard diesel-mechanical, and economy non-compliant tiers reflects Subchapter M certification status and dynamic positioning class notation. Pricing pressure stems from EPA vessel general permit retrofit mandates that disadvantage aging tonnage. Renewables developers with European parent companies show least price sensitivity, prioritizing emission clauses over day-rate minimization.
Supply Chain Analysis
South Korea and China anchor global production of dual-fuel engines and battery-hybrid propulsion systems that Jones Act shipyards install in U.S.-built hulls. Domestic vessel construction draws from marine-grade steel mills in Alabama and Indiana, plus Norwegian-designed dynamic positioning equipment. Single-source vulnerability concentrates in European and Asian heavy-lift jack-up fabrication where Jones Act compliance cannot be satisfied. Distribution runs through Port Fourchon and Houma shore-base networks serving Gulf Coast production corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore wind installation specifications are disrupting legacy oil-and-gas vessel demand patterns, creating asymmetric growth pockets for operators with Jones Act-compliant hybrid tonnage. Subchapter L implementation for offshore supply vessels tightens intact stability standards beyond international conventions, compressing replacement cycles.
For Market Incumbents: Shield charter rate durability by locking in long-term availability contracts with Vineyard Wind and South Fork Wind sponsors before European vessel operators establish U.S. subsidiaries. Deepen backward integration into Gulf Coast shipyard capacity to control newbuild delivery timelines against Subchapter M compliance rotation. Prioritize Coast Guard-certified safety management system investments that create regulatory moats around inspected towing vessel segments.
For New Entrants and Emerging Players: Anchor in Mid-Atlantic wind lease areas off New Jersey and Maryland where Bureau of Ocean Energy Management blocks remain underdeveloped and first-mover positioning is achievable. Target crew boat segments serving Massachusetts and New York turbine installation sites, where aluminum-hull fast supply vessels command premium pricing against conventional platform supply alternatives. Pursue integrated service contracting models that merge turbine transport and cable laying under single-vessel charters.
For Investors and Strategic Acquirers: The market sits at an infrastructure-build phase that favors operators with captive shipyard networks and Coast Guard-certified training pipelines. Long-term viability hinges on exposure to offshore wind construction rather than Gulf of Mexico brownfield maintenance. Acquisition targets should display hybrid-propulsion newbuild pipelines and Subchapter M compliance completion. Watch for Bureau of Ocean Energy Management lease auction timing as inflection indicator for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Program | EPA vessel general permit compliance protects charter eligibility in Northeast Atlantic wind corridors. |
| Shipyard Network Expansion | Louisiana and Texas capacity concentration shortens delivery timelines for Jones Act-compliant newbuilds. |
| Integrated Installation Contracting | Single-vessel charters covering turbine transport and cable laying capture offshore wind procurement consolidation. |
| Dynamic Positioning Training Pipeline | U.S. Coast Guard license processing bottlenecks constrain crew availability for premium-specification vessels. |
| Mid-Atlantic Lease Area Positioning | Bureau of Ocean Energy Management blocks off New Jersey and Maryland offer first-mover charter advantages. |
Research Approach
Initial hypotheses were tested against primary input from offshore vessel operators, Gulf Coast shipyard executives, wind project developers, and U.S. Coast Guard inspection officials and refined through secondary validation. Stakeholder interviews combined with Bureau of Ocean Energy Management lease databases, EPA vessel general permit filings, Customs and Border Protection Jones Act enforcement records, and SEC 10-K disclosures from publicly traded marine operators. Bottom-up vessel-by-vessel fleet analysis triangulated against top-down charter market sizing across the projection horizon.
Variance decomposition separated volume drivers from price elasticity effects throughout the forecast period. Segmentation dimensions modeled include vessel type, propulsion architecture, end-use sector, and regional lease area maturity. CAGRs derived from historical charter rate trajectories and newbuild delivery schedules, with offshore wind installation timelines and Subchapter M compliance deadlines as industry-specific forecast anchors.
Decision-makers should treat outputs as directional under sustained Jones Act enforcement and offshore wind procurement acceleration; material deviation in steel input costs or Coast Guard regulatory timing would warrant model refresh. Recalibration cycles align with material shifts in Bureau of Ocean Energy Management auction schedules and hybrid propulsion technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Offshore Support Vessel Service Market