
 UAE Container Terminal Operations Market | 2026-2036
UAE Container Terminal Operations Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Container Terminal Operations Market Analytics
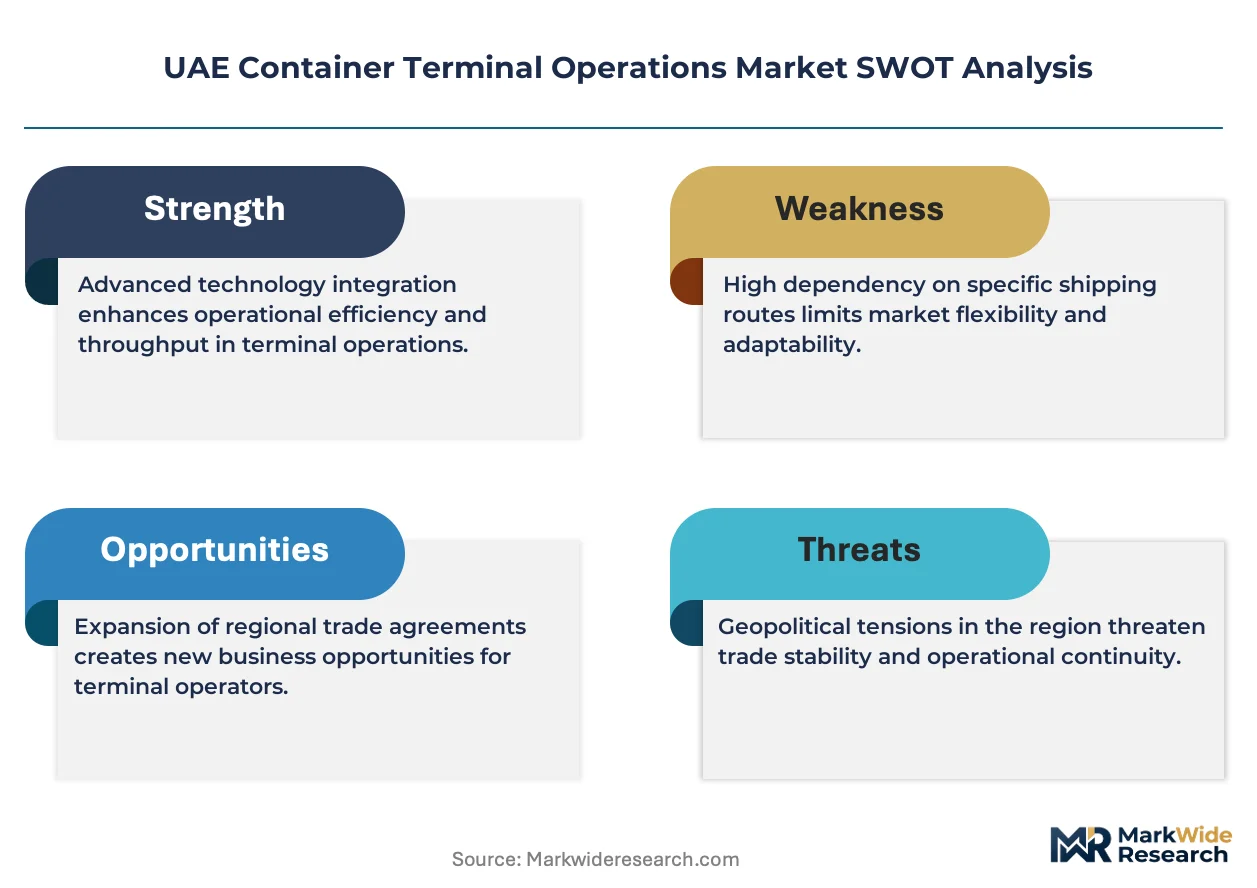
Software-defined berth scheduling is decoupling vessel turnaround commitments from physical infrastructure ownership, letting operators sell throughput guarantees as subscription services. DP World leverages its Jebel Ali scale to anchor premium long-term contracts with shipping lines. AD Ports Group competes through backward integration into maritime logistics, controlling feeder networks that feed Khalifa Port. CSP Abu Dhabi Terminal specializes in semi-automated crane systems that differentiate its cost structure against manual competitors.
Container terminal operations encompass the coordinated movement, storage, and interchange of standardized shipping containers between vessels and land-based transport, requiring gantry cranes with 65-ton lift capacity, yard tractors, and real-time terminal operating systems that synchronize berth windows with customs clearance. The primary purpose is minimizing vessel dwell time while maximizing container throughput per hectare of quay. Deep-water terminals command the largest revenue pools given post-Panamax vessel compatibility, while automated technology segments capture expanding margin pools as labor costs rise and Emiratization targets tighten workforce availability. Specialized terminals serving temperature-controlled or hazardous cargo occupy defensible niches with premium pricing power.
MOHAP oversees occupational safety frameworks that mandate crane operator certification cycles, while the UAE's federal maritime regulator enforces port security protocols aligned with International Ship and Port Facility Security standards. Abu Dhabi Ports PJSC navigates these requirements by embedding compliance into its operating procedures, reducing inspection delays that otherwise cascade into berth congestion. Stakeholders must monitor how Khalifa Industrial Zone expansion reshapes hinterland connectivity and whether AD Ports' freight forwarding integration triggers service bundling that redefines standalone terminal pricing.
Market Dynamics
Automation investments at Jebel Ali and Khalifa Port are compressing vessel turnaround windows while tightening berth scheduling constraints, forcing operators to restructure labor deployment and crane utilization protocols.
Growth Catalysts
- Emiratization Mandates:Federal workforce localization targets are accelerating capital deployment into semi-automated crane systems that reduce dependency on manual labor pools.
- Petrochemical Export Expansion:Rising cargo volumes from Ruwais and Al Taweelah industrial zones are generating sustained terminal booking demand for specialized container handling.
- Khalifa Industrial Zone Connectivity:Hinterland rail and road infrastructure expansion is extending terminal catchment areas into Abu Dhabi's manufacturing corridors.
Market Restraints
- Crane Procurement Lead Times:Post-Panamax gantry crane manufacturing backlogs from European and Asian suppliers are stretching equipment delivery cycles to 18-24 months.
- Skilled Technician Scarcity:Terminal operating system engineers and automation specialists command premium wages that inflate fixed cost structures.
- MOHAP Certification Cycles:Crane operator recertification requirements under federal occupational safety frameworks create periodic workforce availability gaps.
Strategic Opportunities
- Subscription-Based Throughput Guarantees:Software-defined berth scheduling enables operators to monetize capacity commitments without physical asset ownership transfer.
- Feeder Network Integration:Control over maritime logistics chains connecting Khalifa Port to secondary Gulf ports creates captive cargo flow advantages.
- Temperature-Controlled Specialization:Pharmaceutical and perishable cargo handling infrastructure at Abu Dhabi terminals commands premium pricing with limited direct competition.
Industry Challenges
- Legacy System Integration:Real-time terminal operating system deployment requires synchronization with customs clearance platforms that operate on disparate data architectures.
- Automation Workforce Transition:Crane operator roles shifting from manual control to supervisory monitoring demand reskilling programs that extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Container Terminal Operations Market |
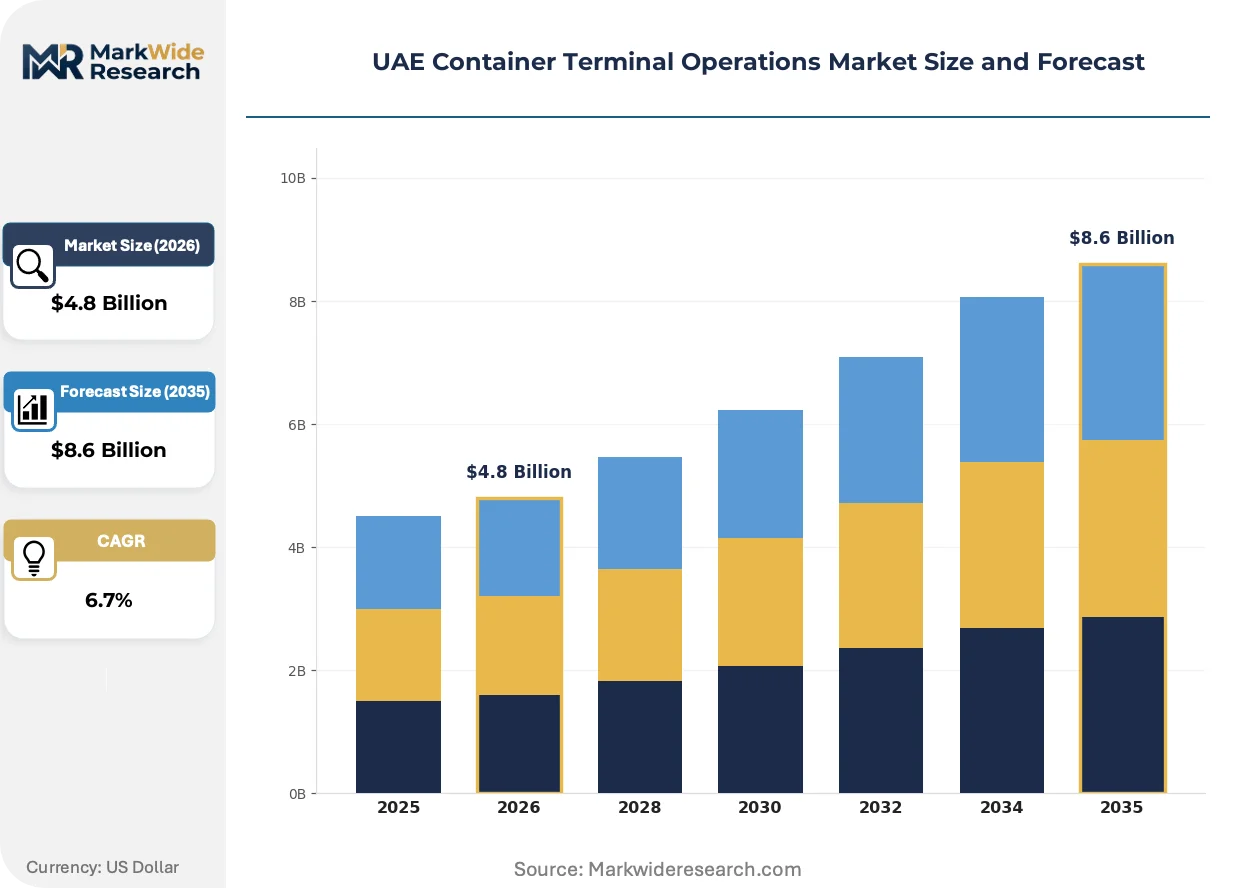
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Terminal Type: Deep-Water, Inland, Specialized, Multipurpose Service Type: Loading, Unloading, Storage, Maintenance Technology: Automated, Semi-Automated, Manual, Hybrid End User: Shipping Lines, Freight Forwarders, Importers, Exporters |
| Companies Covered | DP World, AD Ports Group, CSP Abu Dhabi Terminal, Abu Dhabi Terminal (ADT), Abu Dhabi Ports PJSC, Khorfakkan Container Terminal, Saqr Port Authority, IRSHAD - Abu Dhabi Petroleum Ports Operating Company, Al Yasat Petroleum Operation Company Limited LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Container Terminal Operations Market Evolving Landscape
Digital twin technologies and predictive maintenance algorithms are reconfiguring how terminal operators manage asset lifecycles and berth allocation. These shifts compress decision cycles and alter competitive positioning around data capabilities.
Automated guided vehicle systems for yard container movement are modularizing terminal layout design. DP World and AD Ports Group are deploying these systems at greenfield expansions and brownfield retrofits alike. The technology is modularizing how operators scale throughput capacity without proportional quay extension investments.
MOHAP's enhanced occupational safety enforcement under federal maritime security alignment is mandating biometric access controls and real-time personnel tracking across terminal zones. Terminal operators are embedding compliance infrastructure into capital planning rather than treating it as operational overhead. Abu Dhabi terminals are responding fastest given AD Ports Group's integrated regulatory affairs structure.
Shipping lines are consolidating procurement of terminal services into multi-year framework agreements that bundle berth access, stevedoring, and intermodal connectivity. Traditional spot-market cargo handling is losing share to these consolidated contracts. The shift is most visible in Jebel Ali's premium long-term contract structure with major container lines.
UAE Container Terminal Operations Market Segmentation
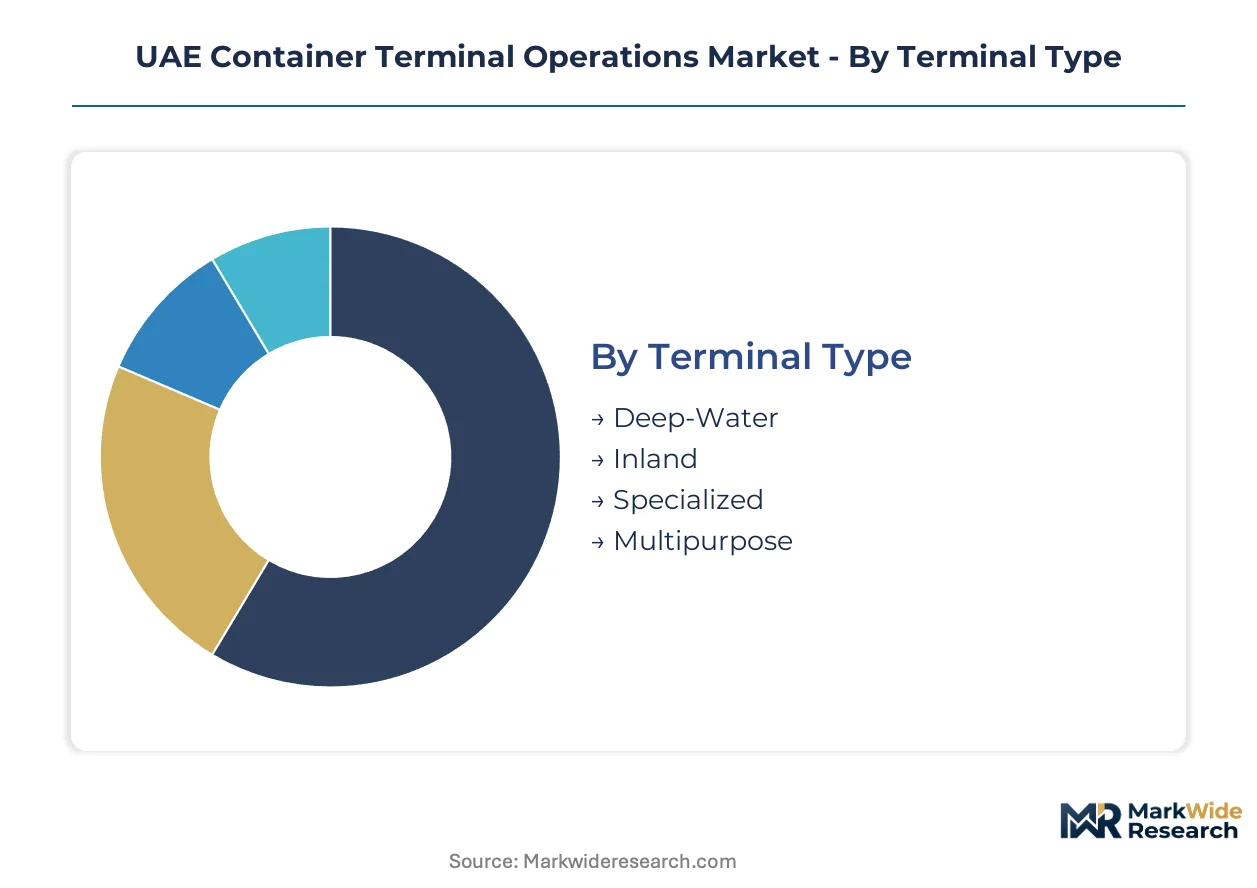
Terminal operators in the UAE segment their offerings across vessel compatibility, cargo handling intensity, and technology integration levels. These divisions determine pricing architecture, capital deployment cycles, and contract structuring with shipping lines and logistics intermediaries.
Terminal Type:
Customization versus standardization splits sharply across this category, with specialized infrastructure commanding premium positioning against commodity multipurpose alternatives.
- Deep-Water:Post-Panamax vessel compatibility with alongside depths exceeding 16 meters enables direct calls from 20,000+ TEU container ships without transshipment. Jebel Ali and Khalifa Port concentrate demand here as petrochemical exporters from Ruwais and Al Taweelah industrial zones expand terminal bookings for specialized container handling.
- Specialized:Temperature-controlled and hazardous cargo infrastructure occupies defensible niches with limited direct competition, featuring pharmaceutical-grade cold chain and chemical containment systems that differentiate cost structures against manual competitors. Abu Dhabi terminals are responding fastest given AD Ports Group's integrated regulatory affairs structure and MOHAP compliance embedding.
- Inland:Dry ports and logistics zones extend terminal catchment through bonded warehousing and customs pre-clearance facilities.
- Multipurpose:General cargo flexibility accommodates breakbulk, Ro-Ro, and containerized volumes with lower capital intensity but compressed margins.
Leading the category by volume: Deep-Water. Expanding most quickly: Specialized.
Service Type:
Cost tier stratification separates high-velocity vessel turnaround services from extended storage revenue pools.
- Loading:Gantry crane operations with 65-ton lift capacity synchronize with vessel stowage plans to minimize port stay duration. DP World leverages its Jebel Ali scale to anchor premium long-term contracts with shipping lines through guaranteed berth windows.
- Unloading:Discharge productivity metrics determine shipping line procurement decisions, with automated crane systems reducing vessel dwell time while maximizing container throughput per hectare of quay.
- Storage:Yard utilization economics depend on dwell time distribution and reefer power consumption, with pharmaceutical and perishable cargo handling at Abu Dhabi terminals commanding premium pricing.
- Maintenance:Container repair, cleaning, and pre-trip inspection services generate ancillary revenue with lower capital barriers.
Highest revenue concentration: Loading. Steepest expansion trajectory: Storage.
Technology:
Margin differentiation tracks automation intensity, with labor substitution creating widening cost advantages against manual competitors.
- Automated:Automated guided vehicle systems for yard container movement are modularizing terminal layout design at greenfield expansions and brownfield retrofits alike. DP World's automation investments at Jebel Ali reflect technology shifts reshaping throughput capacity without proportional quay extension investments.
- Semi-Automated:Remote-operated gantry cranes with supervisory monitoring reduce crane operator headcount while maintaining human intervention for exception handling. CSP Abu Dhabi Terminal specializes in these systems that differentiate its cost structure against manual competitors.
- Manual:Conventional crane and tractor operations persist at smaller facilities with lower volume thresholds.
- Hybrid:Phased automation transitions blend legacy equipment with selective technology upgrades to manage capital deployment pacing.
Widest margin capture: Automated. Gaining share fastest: Semi-Automated.
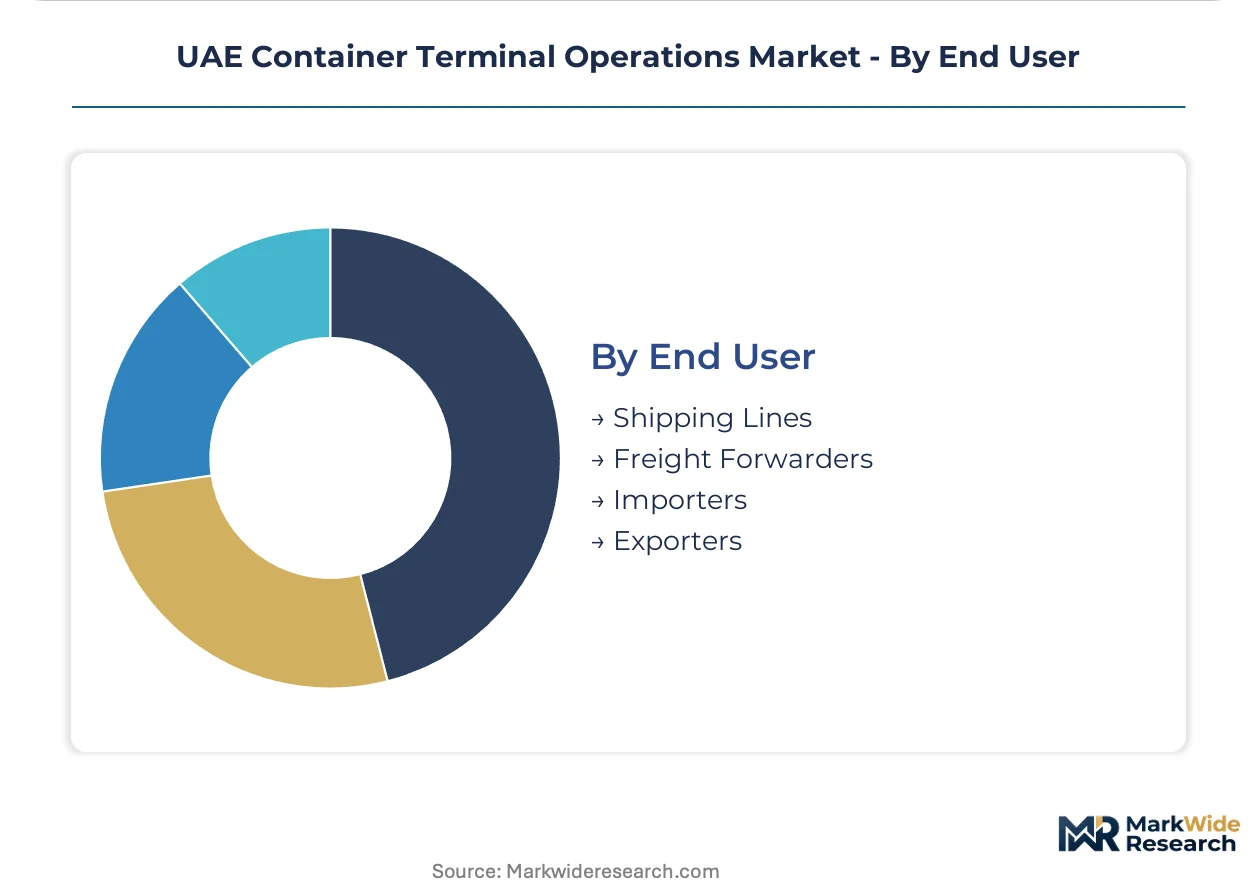
End User:
Customer type determines contract duration, pricing structure, and service bundling intensity.
- Shipping Lines:Vessel operators consolidate procurement of terminal services into multi-year framework agreements that bundle berth access, stevedoring, and intermodal connectivity. Traditional spot-market cargo handling is losing share to these consolidated contracts at Jebel Ali.
- Freight Forwarders:Logistics intermediaries demand flexible booking windows and documentation integration, with AD Ports Group competing through backward integration into maritime logistics controlling feeder networks that feed Khalifa Port.
- Importers:Beneficial cargo owners prioritize customs clearance velocity and last-mile connectivity.
- Exporters:Industrial shippers from Khalifa Industrial Zone require synchronized terminal access with manufacturing schedules.
Dominant contract value: Shipping Lines. Growing fastest: Freight Forwarders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of container terminal services concentrates in Dubai and Abu Dhabi, while cargo demand originates from industrial zones across the Northern Emirates and broader Gulf trade corridors. Consumption patterns diverge between transshipment throughput and direct hinterland cargo, creating distinct operational economics across emirate-level port authorities.
Dubai
Jebel Ali Port processes the majority of UAE container volumes, driven by petrochemical exports from Al Taweelah and Ruwais industrial corridors. DP World operates under Dubai Maritime City Authority oversight, which enforces port security protocols aligned with International Ship and Port Facility Security standards. Jebel Ali Free Zone manufacturing clusters generate captive terminal demand through synchronized logistics contracts.
Abu Dhabi
Khalifa Port expansion targets specialized container handling for pharmaceutical and temperature-controlled cargo segments. AD Ports Group navigates MOHAP occupational safety mandates through embedded compliance infrastructure that reduces inspection delays. Khalifa Industrial Zone connectivity projects extend terminal catchment into Abu Dhabi's manufacturing corridors via dedicated rail and road links.
Sharjah
Khorfakkan Container Terminal serves East-West shipping lanes with deep-water access independent of Strait of Hormuz transit constraints. Sharjah Ports Authority applies federal maritime security frameworks with streamlined customs pre-clearance facilities. Hamriyah Free Zone petrochemical processors generate specialized container bookings for hazardous cargo handling.
Ras Al Khaimah
Saqr Port Authority manages bulk and breakbulk cargo flows from RAK Ceramics and cement manufacturing clusters. The emirate's industrial regulator enforces crane operator certification cycles under MOHAP-aligned occupational safety standards. Al Ghail Industrial Zone exporters require synchronized terminal access for construction materials shipments.
Fujairah
IRSHAD operates petroleum port infrastructure serving offshore bunkering and energy logistics adjacent to container terminal networks. Fujairah Port Authority coordinates with federal maritime regulators on security protocol implementation. The emirate's East Coast location provides alternative routing for cargo bypassing Dubai-Abu Dhabi concentration.
UAE Container Terminal Operations Market Competitive Landscape
Top-tier vendors anchor premium long-term contract structures, while mid-scale operators compete through specialized cargo handling capabilities and feeder network integration. The vendor base clusters around three strategic archetypes: integrated port authorities controlling hinterland logistics chains, semi-automated terminal specialists differentiating on crane technology, and regional niche players serving hazardous or temperature-controlled segments. Dominant competitive moves include backward integration into maritime logistics and phased automation transitions blending legacy equipment with selective technology upgrades.
Among UAE-based integrated operators, DP World and AD Ports Group exemplify scale-driven port authority archetypes with control over feeder networks and industrial zone connectivity. CSP Abu Dhabi Terminal occupies a position within the semi-automated specialist tier, differentiating cost structures through remote-operated gantry crane systems. These three entities collectively represent the competitive spectrum from hinterland-integrated logistics to technology-differentiated terminal operations.
| Leading Market Players |
|---|
| DP World |
| AD Ports Group |
| CSP Abu Dhabi Terminal |
| Abu Dhabi Terminal (ADT) |
| Abu Dhabi Ports PJSC |
| Khorfakkan Container Terminal |
| Saqr Port Authority |
| IRSHAD - Abu Dhabi Petroleum Ports Operating Company |
| Al Yasat Petroleum Operation Company Limited LLC |
| Others |
Value Network & Pricing Analysis
Steel price indices and gantry crane manufacturing costs cascade through terminal equipment procurement into berth access pricing tiers, compressing margins for operators locked into long-dated equipment contracts while rewarding those with backward integration into maintenance services.
Pricing Analysis
Margin tightening in automated terminal segments reflects crane procurement backlogs from European and Asian suppliers stretching to 18-24 months. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed berth windows from spot-market cargo handling and storage-only arrangements. Pricing pressure stems from shipping lines consolidating procurement into multi-year framework agreements that bundle stevedoring with intermodal connectivity. Freight forwarders exhibit highest price sensitivity due to thin margins on documentation and booking services, while petrochemical exporters from Ruwais absorb premium rates for specialized hazardous cargo handling.
Supply Chain Analysis
Post-Panamax gantry crane supply rests on German, Chinese, and South Korean heavy equipment manufacturers with concentrated order books. Terminal operating systems draw from European and North American software vendors, while automated guided vehicle fleets source from Japanese and German robotics specialists. Single-source vulnerability concentrates in crane control system components subject to export licensing restrictions. Distribution runs through direct manufacturer-to-operator contracts with embedded maintenance clauses, bypassing traditional equipment distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over feeder networks and hinterland rail connectivity determines contract renewals. Players are pursuing backward integration into maritime logistics chains as the decisive upstream lever.
For Market Incumbents: Anchor premium positioning through multi-year framework agreements with shipping lines that bundle berth guarantees with Khalifa Industrial Zone rail connectivity. Defend against semi-automated terminal specialists by accelerating crane operator reskilling programs under MOHAP certification cycles. Invest in embedded compliance infrastructure to reduce inspection delays that cascade into berth congestion. For New Entrants and Emerging Players: Feeder network operators represent the most accessible channel partner type for securing captive cargo flows into Khalifa Port. Target temperature-controlled pharmaceutical handling at Abu Dhabi terminals where AD Ports Group's integrated structure creates service bundling gaps. Penetrate through niche hazardous cargo certification that commands premium pricing with limited direct competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor semi-automated terminal specialists with remote-operated crane technology in Abu Dhabi. Long-term viability hinges on operators' ability to monetize software-defined berth scheduling as subscription services rather than transactional cargo handling. Watch Khalifa Industrial Zone expansion announcements as the signal for hinterland connectivity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Feeder Network Integration | Control over maritime logistics chains feeding Khalifa Port creates captive cargo flow advantages against spot-market competitors. |
| Semi-Automated Crane Deployment | Remote-operated gantry systems at CSP Abu Dhabi Terminal differentiate cost structures as Emiratization mandates tighten labor pools. |
| Temperature-Controlled Infrastructure | Pharmaceutical-grade cold chain investment commands premium pricing with limited competition in Abu Dhabi's specialized terminal segment. |
| Software-Defined Berth Scheduling | DP World's automation investments enable throughput guarantees as subscription services decoupled from physical asset ownership. |
| Hinterland Rail Connectivity | Khalifa Industrial Zone expansion extends terminal catchment into Abu Dhabi's manufacturing corridors via dedicated freight links. |
Research Methodology
Multi-period observation of vessel turnaround metrics, berth utilization rates, and automation deployment timelines anchored the trend analysis, supplemented by interviews with terminal operations directors, maritime logistics procurement managers, crane maintenance engineers, and customs clearance platform specialists. Secondary validation drew from UAE federal maritime regulator filings, MOHAP occupational safety enforcement records, DP World and AD Ports Group infrastructure disclosure documents, and International Ship and Port Facility Security compliance audits. Bottom-up volume modeling triangulated against top-down terminal capacity assessments across the analysis window.
Segment-weighting applied vessel compatibility tiers, cargo handling intensity levels, technology integration stages, and end-user contract structures across the projection horizon. CAGRs derived from equipment procurement cycle analysis, labor cost trajectory modeling, and petrochemical export volume correlations. Forecast inputs incorporated crane manufacturing backlog durations, Emiratization mandate implementation schedules, and Khalifa Industrial Zone connectivity project milestones.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Strait of Hormuz transit routes, abrupt shifts in federal workforce localization targets, and unanticipated MOHAP regulatory amendments. Forecasts reflect documented assumptions about equipment delivery timelines and shipping line consolidation patterns. A small set of named triggers warrants ongoing watch: crane procurement lead time extensions, AD Ports Group freight forwarding integration announcements, and DP World automation rollout pace at Jebel Ali expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
United States Maritime Information Market