
 Global Waterway Transportation Software and Services Market | 2026-2036
Global Waterway Transportation Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waterway Transportation Software and Services Market Analysis
Logistics providers are reorganizing procurement priorities around real-time cargo visibility, while shipping companies retain dominant budget share for core fleet operations. Veson Nautical dominates voyage management systems for bulk commodity traders. SAP leverages its ERP backbone to anchor integrated logistics platforms across European barge operators. Descartes Systems specializes in customs compliance layers that interconnect with port authority data exchanges.
Waterway transportation software and services encompass digital platforms that coordinate vessel routing, cargo tracking, berth scheduling, and regulatory filing through API-connected maritime databases, typically processing AIS telemetry at sub-minute intervals to optimize inland and coastal freight movements. Routing software leads solution spending as fuel optimization algorithms deliver measurable operating cost reductions, while cloud-based deployment models represent the fastest-growing architecture category as terminal operators abandon legacy on-premises infrastructure. Port management modules concentrate margin pools where vendor lock-in from specialized berth-allocation logic creates high switching costs.
The International Maritime Organization mandates electronic data interchange for vessel clearance, while the EU Green Deal's F-Gas Regulation pushes operators toward emissions-monitoring software stacks. The US Coast Guard's subchapter M towing vessel rules require inspection documentation systems that drive demand for compliance solutions. Stakeholders must weigh interoperability investments against fragmented national single-window port systems that resist standardization.
Market Dynamics
The International Maritime Organization's emissions mandates are compressing vessel operators' technology refresh cycles, forcing simultaneous investment in compliance software and fuel optimization platforms across inland and coastal fleets.
Growth Catalysts
- EU Green Deal F-Gas Regulation:The regulation mandates real-time emissions monitoring for refrigerated cargo vessels, compelling operators to deploy sensor-integrated fleet management stacks across Rhine and Danube corridors.
- Cloud migration:Terminal operators are abandoning on-premises berth scheduling systems for API-connected SaaS platforms that synchronize with port authority data exchanges in real time.
- Bulk commodity traders:These buyers are consolidating procurement around voyage management systems that integrate commodity pricing feeds with vessel position telemetry for arbitrage optimization.
Market Restraints
- Legacy system entrenchment:Specialized berth-allocation algorithms in major European ports create vendor lock-in that resists cloud migration despite operational inefficiencies.
- Input cost volatility:Satellite bandwidth and AIS data feed subscriptions fluctuate with telecom provider pricing, squeezing margins for software vendors serving mid-size barge operators.
- Substitution threat:Rail freight visibility platforms are capturing modal shift demand on routes where waterway infrastructure congestion erodes transit time advantages.
Strategic Opportunities
- India's inland waterways:The National Waterways Act expansion creates greenfield demand for vessel tracking and cargo matching platforms on the Ganga-Bhagirathi-Hooghly system.
- Digital twin convergence:Integration of hydrodynamic simulation with live AIS streams enables predictive draft optimization for container-on-barge services.
- US Coast Guard subchapter M:Towing vessel inspection documentation mandates drive first-time compliance software adoption among previously unregulated inland operators.
Industry Challenges
- Maritime cybersecurity expertise scarcity:Port authorities struggle to staff SOC teams capable of securing OT-IT converged environments where berth control systems interface with cloud logistics platforms.
- Interoperability fragmentation:National single-window port systems in Germany, Netherlands, and Belgium resist API standardization, forcing vendors to maintain redundant integration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waterway Transportation Software and Services Market |
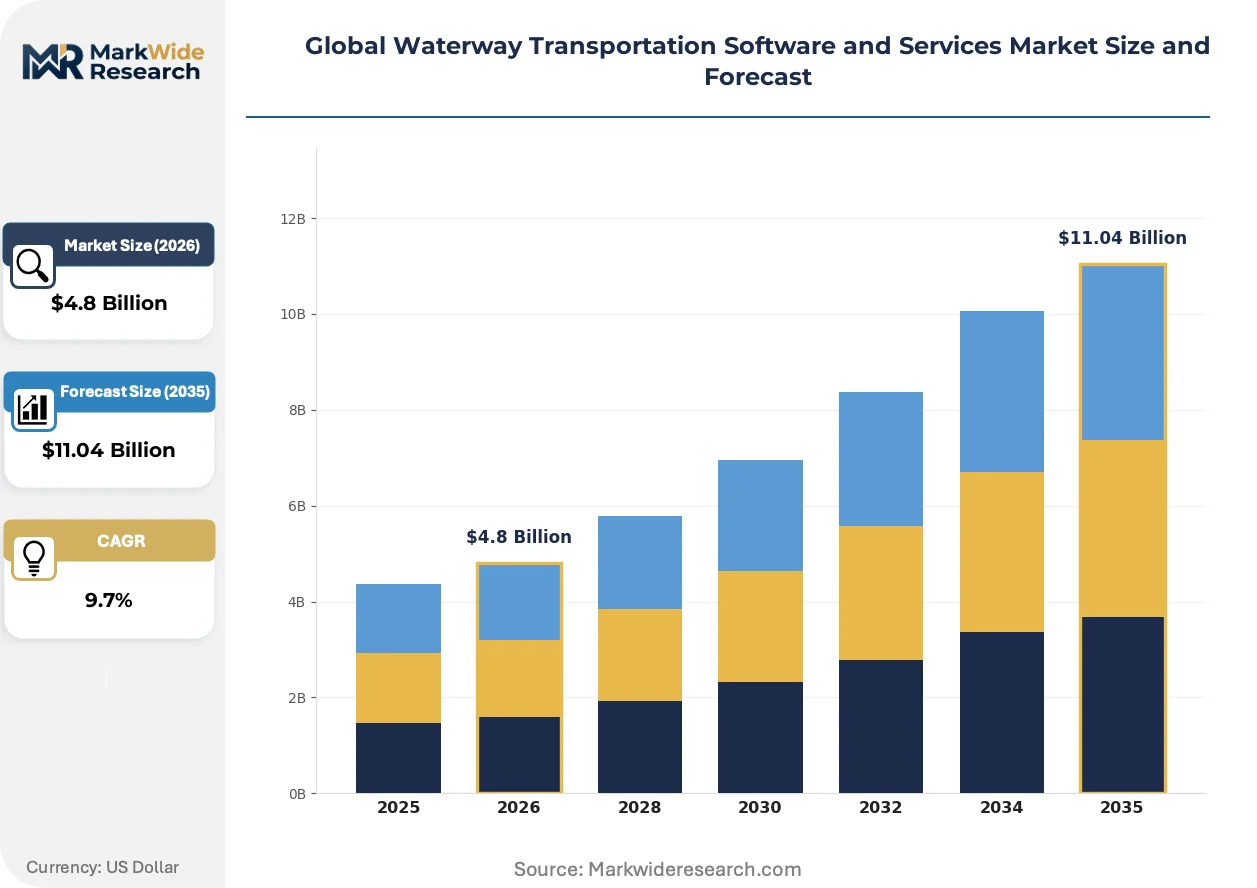
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Routing Software, Fleet Management, Port Management, Compliance Solutions End User: Shipping Companies, Logistics Providers, Government Agencies, Marine Surveyors Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile Solutions Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Veson Nautical, SAP, Accenture, Aljex Software, Descartes Systems, DNV GL, BASS Software, Cognizant, High Jump Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waterway Transportation Software and Services Market Emerging Trajectories
Machine learning inference at the edge is compressing decision latency for vessel routing, while regulatory data mandates are hardening requirements for audit-ready software architectures across maritime compliance stacks.
Edge-deployed fuel optimization algorithms are displacing shore-based batch processing for route planning. Bulk carriers plying the Rhine-Main-Danube corridor are adopting these systems fastest, with retrofit installations accelerating through 2024. The technology is displacing manual noon-report workflows and compressing charter party dispute resolution timelines from weeks to hours.
The EU Green Deal's F-Gas Regulation is mandating refrigerant leak detection with automated reporting for reefer barges. This industrial consequence forces software vendors to embed emissions telemetry directly into cargo management modules rather than bolt-on compliance tools. Reefer operators in Netherlands and Belgium are responding fastest, driven by Antwerp port authority incentive programs tied to berth priority scheduling.
Charterers are unbundling voyage management from bundled service contracts, instead procuring software directly and demanding API access to carrier operational data. This procurement evolution disrupts traditional shipbroker information asymmetry and replaces it with transparent cargo-position matching platforms. The shift is most visible in German chemicals logistics, where BASF and Bayer have mandated direct software procurement for contracted barge operators.
Global Waterway Transportation Software and Services Market Segmentation
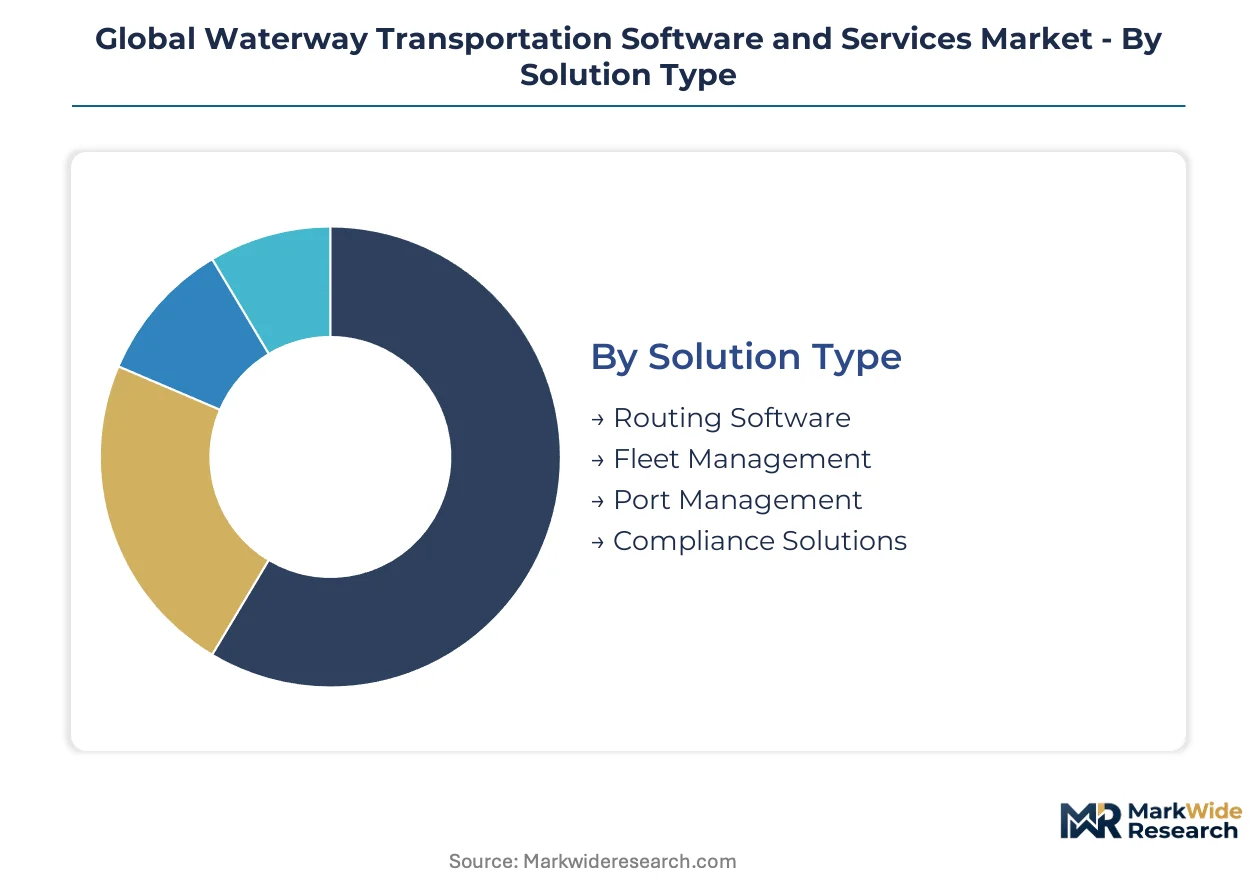
Waterway transportation software segments diverge sharply by infrastructure maturity across trade corridors. Procurement patterns in the Rhine basin differ fundamentally from greenfield deployments on India's National Waterways, forcing vendors to maintain parallel solution architectures.
Solution Type:
German and Dutch operators concentrate procurement in domestically developed routing platforms, while export-led demand from Southeast Asian port authorities favors integrated compliance suites.
- Routing Software:Fuel optimization algorithms process AIS telemetry at sub-minute intervals to calculate draft-adjusted paths through constrained channels. Rhine-Main-Danube operators deploy these systems fastest, driven by charter party clauses that penalize arrival window deviations.
- Fleet Management:Cloud-native platforms unify vessel position tracking with maintenance scheduling across distributed barge fleets. Belgian chemical shippers mandate these systems for contracted carriers serving Antwerp-Rotterdam corridors.
- Port Management:Berth-allocation modules with vendor-specific optimization logic create high switching costs at major European terminals.
- Compliance Solutions:Automated regulatory filing systems interface with EU single-window portals and US Coast Guard documentation requirements.
Routing software commands the established base. The steepest expansion runs through fleet management platforms.
End User:
Cost tier separation distinguishes enterprise-grade deployments from mid-market adoption, with shipping companies absorbing premium pricing for integrated stacks while surveyors fragment across point solutions.
- Shipping Companies:Bulk commodity traders dominate budget allocation, procuring voyage management systems that integrate commodity pricing feeds with vessel telemetry. These buyers unbundle software from brokered service contracts, demanding direct API access to carrier operational data.
- Logistics Providers:Third-party operators prioritize real-time cargo visibility layers that interconnect with shipper ERP systems. Procurement concentrates in Germany, where Rhine corridor modernization drives replacement of legacy terminal operating systems.
- Government Agencies:Port authorities and inland waterway administrations procure vessel traffic management infrastructure with cybersecurity-hardened architectures.
- Marine Surveyors:Inspection documentation specialists adopt mobile-first platforms for subchapter M compliance and cargo condition reporting.
Shipping companies anchor revenue concentration. Logistics providers are climbing the fastest as procurement autonomy expands.
Deployment Model:
Application criticality determines architecture choice, with berth control systems resisting cloud migration while cargo tracking layers migrate rapidly.
- Cloud-Based:SaaS platforms synchronize with port authority data exchanges through API-connected maritime databases. Terminal operators abandon on-premises infrastructure for these deployments, though specialized berth-allocation logic in Rotterdam and Hamburg creates residual on-premises retention.
- On-Premises:Legacy installations persist where OT-IT convergence risks deter cloud exposure, particularly in vessel traffic management centers.
- Hybrid:Split architectures isolate critical control systems on-premises while pushing analytics and reporting to cloud tiers.
- Mobile Solutions:Tablet-based applications support towboat inspection workflows and reefer cargo monitoring with offline synchronization capabilities.
On-premises retains mission-critical workloads. Cloud-based deployments are expanding most quickly as cybersecurity frameworks mature.
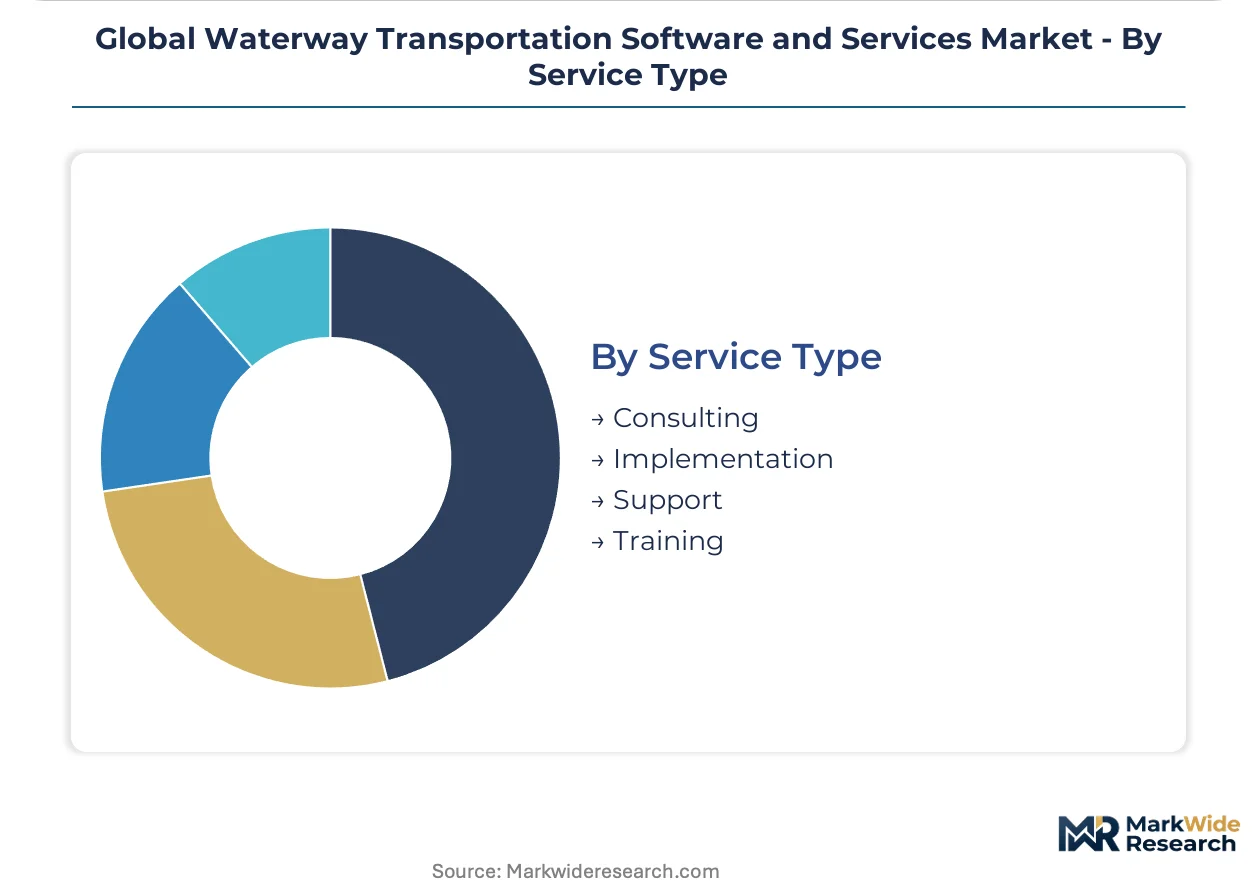
Service Type:
Customer maturity separates implementation-heavy engagements from recurring support relationships, with greenfield markets consuming training services at higher ratios.
- Consulting:Advisory services address interoperability fragmentation across national single-window systems, with vendors maintaining redundant integration layers for Germany, Netherlands, and Belgium.
- Implementation:System integration projects concentrate where EU Green Deal F-Gas Regulation mandates retrofit emissions-monitoring stacks onto existing fleet management platforms.
- Support:Technical maintenance contracts secure recurring revenue through API dependency and specialized berth-allocation algorithm updates.
- Training:Change management services address maritime cybersecurity expertise scarcity as port authorities staff SOC teams for OT-IT converged environments.
Implementation services command the established base. Support contracts are gaining share fastest as installed bases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for waterway logistics concentrates in Germany, where Rhine corridor operators drive fleet management platform demand. Vendors cluster around port cities with dense barge traffic and stringent emissions enforcement.
Germany
Rhine-Main-Danube operators procure voyage management systems with integrated fuel optimization algorithms. The EU Green Deal F-Gas Regulation mandates real-time emissions monitoring for refrigerated cargo vessels. Duisburg and Hamburg anchor development clusters where terminal operators modernize berth-allocation infrastructure.
United States
Towing vessel operators adopt compliance documentation platforms following expanded Coast Guard enforcement. Subchapter M rules require inspection record systems for previously unregulated inland fleets. The Mississippi River corridor from St. Louis to New Orleans drives procurement concentration among barge fleet managers.
Netherlands
Antwerp-Rotterdam chemical shippers mandate cloud-based cargo visibility for contracted carriers. Port authority incentive programs tie berth priority scheduling to emissions performance metrics. Rotterdam's terminal operators lead hybrid cloud adoption for critical control system isolation.
India
The National Waterways Act expansion generates greenfield demand for vessel tracking on the Ganga-Bhagirathi-Hooghly system. DGFT and inland waterway administration procurement prioritizes API-connected cargo matching platforms. Kolkata and Patna anchor implementation clusters for first-generation fleet digitization.
Belgium
Reefer barge operators deploy sensor-integrated emissions telemetry fastest among Rhine corridor nations. Automated refrigerant leak detection reporting integrates directly with cargo management modules. Antwerp's chemical logistics cluster drives premium software procurement for multimodal synchronization.
Global Waterway Transportation Software and Services Market Vendor Landscape
Concentration sits with ERP-anchored platforms and specialized maritime software vendors. The vendor base splits between horizontal logistics suites and purpose-built voyage management systems. Three archetypes dominate: enterprise resource planning extenders, niche maritime specialists, and systems integrators wrapping compliance layers around operational cores. Competitive moves center on API standardization partnerships and vertical acquisition of sensor telemetry providers.
Within the maritime specialist tier, Veson Nautical and BASS Software occupy positions shaped by charterer procurement unbundling. SAP anchors the ERP-extender archetype for European barge operators. Descartes Systems represents the compliance-layer specialist model, interfacing with port authority data exchanges. Accenture and Cognizant sit within the systems integrator cluster, packaging implementation services around vendor platforms.
| Leading Market Players |
|---|
| Veson Nautical |
| SAP |
| Accenture |
| Aljex Software |
| Descartes Systems |
| DNV GL |
| BASS Software |
| Cognizant |
| High Jump Software |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal F-Gas Regulation gates both vendor qualification and price differentiation simultaneously, mandating sensor-integrated emissions monitoring stacks that separate certified compliance platforms from basic routing tools. Charterers unbundling voyage management from brokered contracts compress price premiums for integrated suites while elevating API-access tiers.
Pricing Analysis
The EU Green Deal F-Gas Regulation dictates the pricing tier structure by mandating real-time emissions telemetry as a baseline capability, forcing three-tier pricing structure across premium sensor-integrated, standard API-connected, and economy legacy-anchored levels. Price differentiation centers on ISO 27001 cybersecurity certification and berth-priority integration depth. Cost compression in the mid-market tier is intensifying because satellite bandwidth subscriptions fluctuate with telecom provider pricing. Bulk commodity traders exhibit least price sensitivity due to charter party penalty clauses, while mid-size barge operators absorb maximum pricing pressure.
Supply Chain Analysis
Inventory lead times for AIS telemetry hardware stretch longest where semiconductor component sourcing concentrates in Taiwan, South Korea, and Germany. Software development draws from cloud infrastructure providers, maritime data aggregators, and sensor OEMs. Single-source vulnerability sits with EU single-window API standardization delays forcing redundant integration layers. Distribution runs through direct vendor-to-operator sales with Accenture and Cognizant packaging implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national single-window systems creates niche opportunities for compliance-layer specialists as charterers demand direct software procurement over bundled broker services.
For Market Incumbents: Fortify berth-allocation algorithm lock-in at Rotterdam and Hamburg terminals against cloud-native challengers by embedding emissions telemetry directly into cargo management modules rather than bolt-on compliance tools. Prioritize backward integration into sensor hardware supply to offset satellite bandwidth cost volatility squeezing margins for mid-market barge operator segments. For New Entrants and Emerging Players: Anchor in India's National Waterways Act expansion where greenfield vessel tracking demand on the Ganga-Bhagirathi-Hooghly system lacks entrenched legacy competition. Target API-connected cargo matching platforms for Kolkata and Patna implementation clusters with DGFT-aligned regulatory filing as the go-to-market wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from ERP-anchored logistics platforms seeking to divest non-core maritime modules as SAP and Oracle refocus on cloud-native verticals. Five-to-ten-year viability hinges on OT-IT convergence expertise scarcity resolving through cybersecurity talent pipeline development. Watch for Antwerp port authority incentive program expansion as inflection signal for reefer barge emissions-monitoring stack adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API Standardization Partnership | Descartes Systems interfaces with German, Dutch, and Belgian port authority data exchanges to reduce redundant integration layers. |
| Sensor Telemetry Acquisition | Veson Nautical embeds emissions monitoring directly into voyage management systems for F-Gas Regulation compliance. |
| Cloud-Native Platform Launch | Terminal operators abandon on-premises berth scheduling for SaaS platforms synchronizing with Rotterdam's hybrid infrastructure. |
| Geographic Expansion | BASS Software targets India's National Waterways with first-generation fleet digitization on the Hooghly corridor. |
| Compliance Layer Integration | SAP anchors integrated logistics platforms across European barge operators with EU single-window regulatory filing modules. |
Methodological Framework
A spread of perspectives from fleet operations directors, port authority IT procurement leads, maritime software integration specialists, and inland waterway administration officials converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EU single-window documentation, US Coast Guard subchapter M enforcement records, AIS telemetry provider disclosures, and customs trade flow databases. Bottom-up vessel operator demand sizing triangulated against top-down software vendor revenue attribution.
Segmentation dimensions modeled span solution type, end-user archetype, deployment architecture, and regional regulatory framework clusters across the analysis window. CAGRs derived from logistic diffusion curves fitted to cloud migration adoption patterns and emissions compliance mandate phase-in schedules. Forecast inputs incorporated charter party unbundling velocity and satellite bandwidth pricing volatility assumptions.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement and US Coast Guard subchapter M expansion; material deviation in regulatory timeline or cloud cybersecurity framework maturation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
North America Container Terminal Operations Market