
 Cambodia Freight and Logistics Market | 2026-2036
Cambodia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia Freight and Logistics Market Outlook
Asset-light leasing models for container fleets and cold-chain equipment are reshaping competitive entry in Cambodian logistics. Twin Logistics (Cambodia) leverages its Phnom Penh depot network to dominate garment-industry forwarding. SEKO Logistics Cambodia sustains cross-border e-commerce clearance capacity through bonded warehouse partnerships. Bolloré Logistics (Cambodia) anchors regional sea-air connectivity via Sihanoukville port operations.
Cambodia freight and logistics encompasses the planning, execution, and control of goods movement across road, rail, air, and sea modes, with cold-chain specifications for agricultural exports and garment-industry lead times measured in hours, not days. Its primary commercial purpose is reducing landed costs for manufacturers in special economic zones while connecting landlocked production clusters to ASEAN trade corridors. Transport services and freight forwarding together capture the dominant margin pool, as these segments bundle customs brokerage and multimodal coordination into single-contract offerings. Warehousing is the fastest-growing segment category, driven by bonded-facility expansion near Phnom Penh and Sihanoukville to serve e-commerce and manufacturing verticals.
Cambodia's Ministry of Public Works and Transport enforces axle-load regulations and cross-border weight standards that directly shape fleet investment and road-freight pricing. The General Department of Customs and Excise implements ASEAN Single Window protocols, digitizing declaration flows and compressing border-clearance windows for manufacturing exporters. Stakeholders must monitor whether Cambodia's pending accession to the WTO Trade Facilitation Agreement full tier will accelerate customs automation or expose domestic forwarders to ASEAN-wide competition.
Market Dynamics
ASEAN Single Window digitization is compressing customs clearance windows from days to hours, forcing Cambodian forwarders to restructure bonded warehousing networks around Phnom Penh and Sihanoukville industrial corridors.
Growth Catalysts
- Garment Export Lead-Time Compression:Fast-fashion buyers now demand 72-hour factory-to-port cycles, pulling investment into express bonded corridors connecting Phnom Penh special economic zones to Vietnam and Thailand border crossings.
- ASEAN Single Window Protocol:The General Department of Customs and Excise digitized declaration flows, eliminating redundant paper documentation and reducing cross-border manufacturing clearance friction.
- Cold-Chain Infrastructure Buildout:Rice and cassava exporters are installing temperature-controlled container fleets to access premium ASEAN fresh-produce retail channels.
Market Restraints
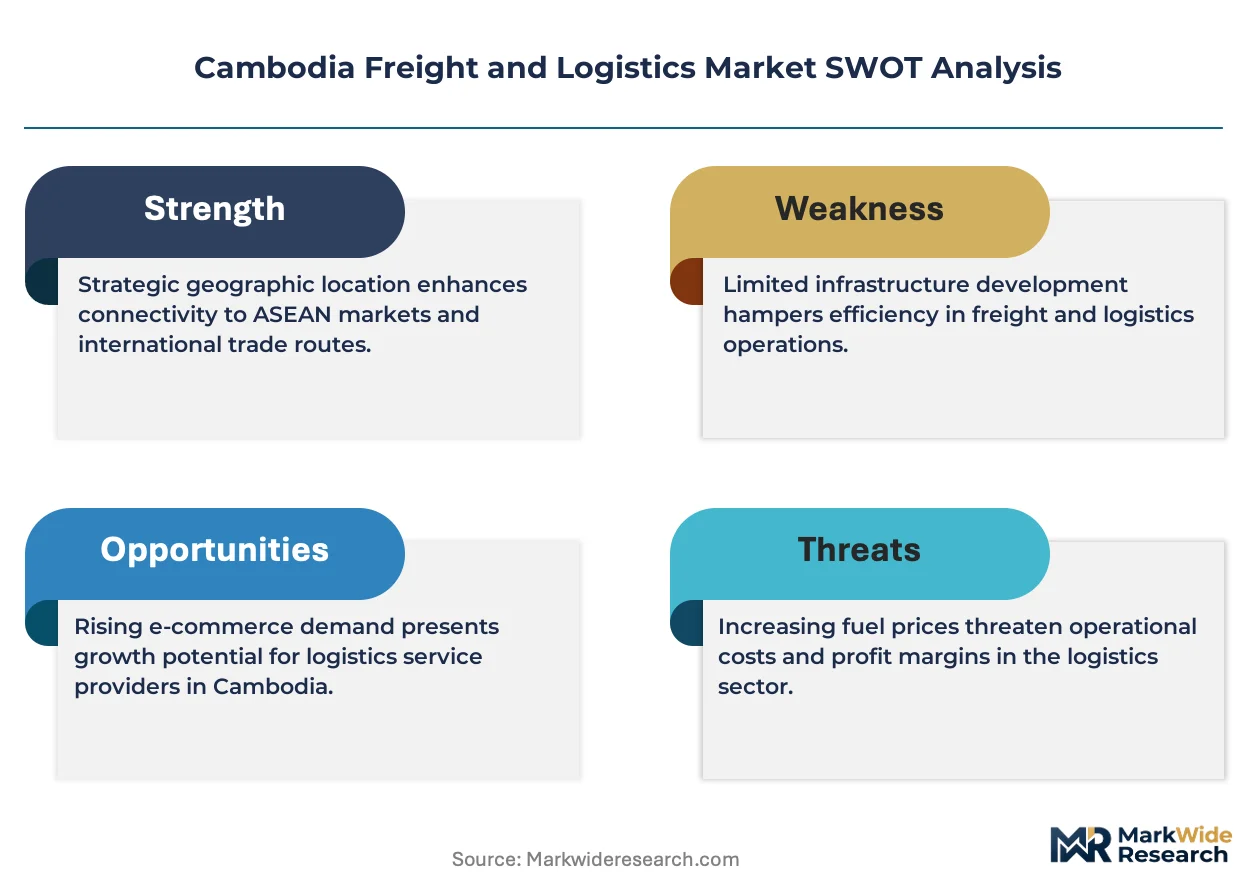
- Fuel Cost Volatility:Diesel prices drive 60-70% of Cambodian road-freight operating costs, exposing fleet operators to margin compression when global crude benchmarks spike.
- Driver Certification Bottlenecks:Cambodia's Ministry of Public Works and Transport enforces axle-load and cross-border weight standards that limit fleet utilization rates below regional peers.
- Port Capacity Concentration:Sihanoukville Autonomous Port handles 70% of containerized trade, creating single-point-of-failure risk for garment manufacturers with just-in-time supply chains.
Strategic Opportunities
- Kampot and Koh Kong Corridor Development:Underpenetrated southern provinces offer greenfield logistics park sites with direct Thai Gulf access, bypassing Sihanoukville congestion.
- E-Commerce Fulfillment Integration:Cross-border parcel volumes from Chinese platforms are pulling demand for last-mile sorting hubs in Phnom Penh peripheral districts.
- WTO Trade Facilitation Accession:Pending full-tier membership would accelerate customs automation and expose domestic forwarders to ASEAN-wide competitive benchmarking.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems lack API compatibility with ASEAN Single Window data standards, forcing manual reconciliation during peak export windows.
- Refrigeration Technician Scarcity:Cold-chain equipment maintenance requires specialized HVAC-electrician hybrid skills that Cambodia's technical training institutes have not scaled to meet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia Freight and Logistics Market |
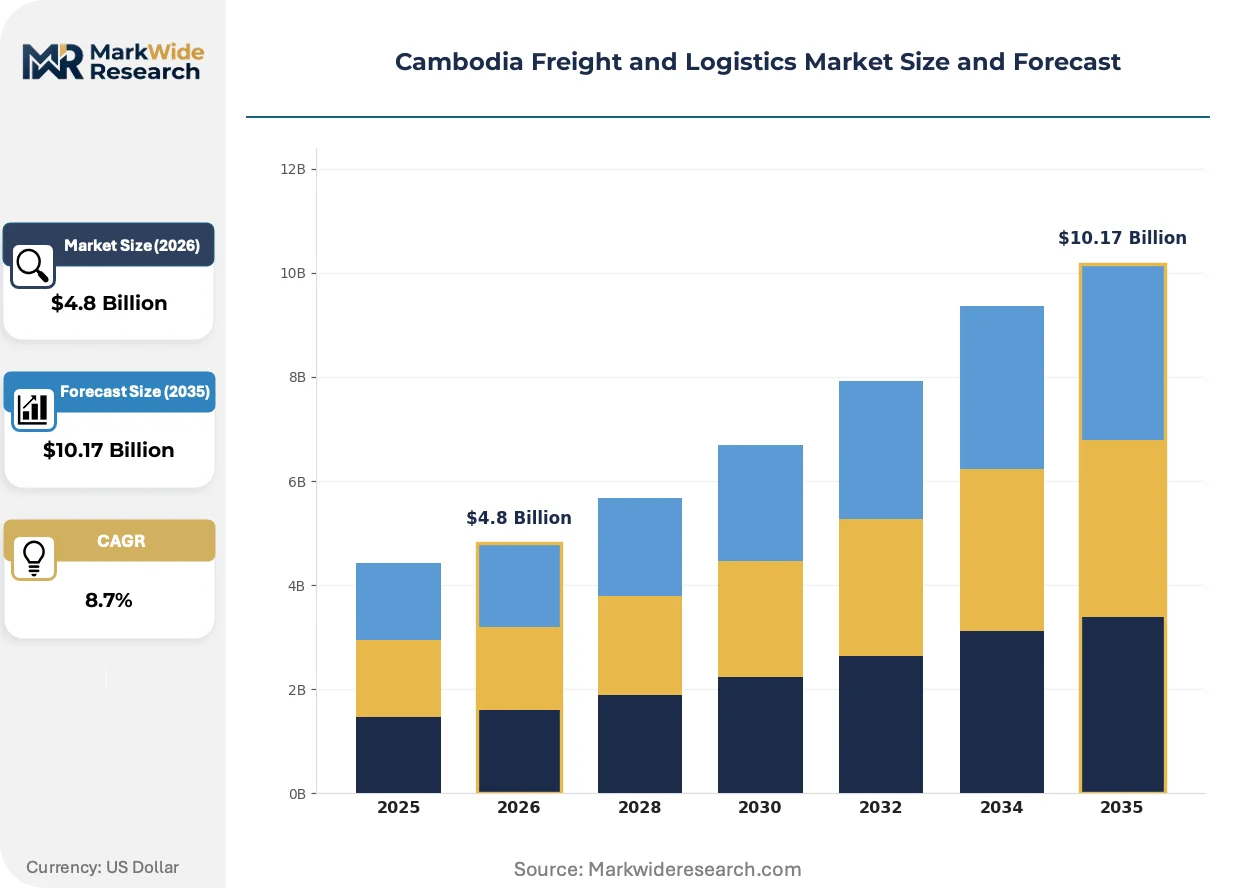
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transport Services, Warehousing, Customs Brokerage, Freight Forwarding Industry Vertical: Retail, Manufacturing, Agriculture, E-Commerce Distribution Channel: Direct Sales, Online Platforms, Third-Party Logistics, Wholesale Transportation Mode: Road, Rail, Air, Sea |
| Companies Covered | Twin Logistics (Cambodia), SEKO Logistics Cambodia, Heng Heng Import Export, CHLL Global Logistics, Master Delivery Import Export, BEST Express Cambodia, Bolloré Logistics (Cambodia), Macle Logistics (Cambodia), J&T Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia Freight and Logistics Market Strategic Shifts
Digitization of customs brokerage and warehouse management systems is collapsing information asymmetries between shippers and carriers, compressing the traditional forwarder margin pool.
Blockchain-enabled bill-of-lading verification is rendering obsolete paper-based document transfer between Cambodian exporters and Vietnamese trans-shipment agents. Garment manufacturers in Phnom Penh special economic zones are piloting distributed-ledger contracts to accelerate payment settlement. This compression of documentation cycles is forcing traditional freight forwarders to reprice bundled services or unbundle customs brokerage entirely.
Cambodia's General Department of Customs and Excise is extending ASEAN Single Window protocols to cover agricultural sanitary certificates, aligning with regional food-safety traceability mandates. Rice exporters now submit phytosanitary documentation through unified digital portals rather than parallel paper channels. The agricultural vertical faces the steepest compliance adaptation curve, with smaller cooperatives lagging behind integrated trading houses in system integration.
Consolidation of garment purchasing into fewer multinational buying offices is compressing forwarder negotiation cycles from annual to quarterly rate reviews. Large manufacturers in Phnom Penh industrial zones now run reverse auctions for container-slot commitments, displacing relationship-based contract renewal. This procurement rationalization is most visible among EU and US fast-fashion brands with concentrated Cambodia sourcing footprints.
Cambodia Freight and Logistics Market Segmentation
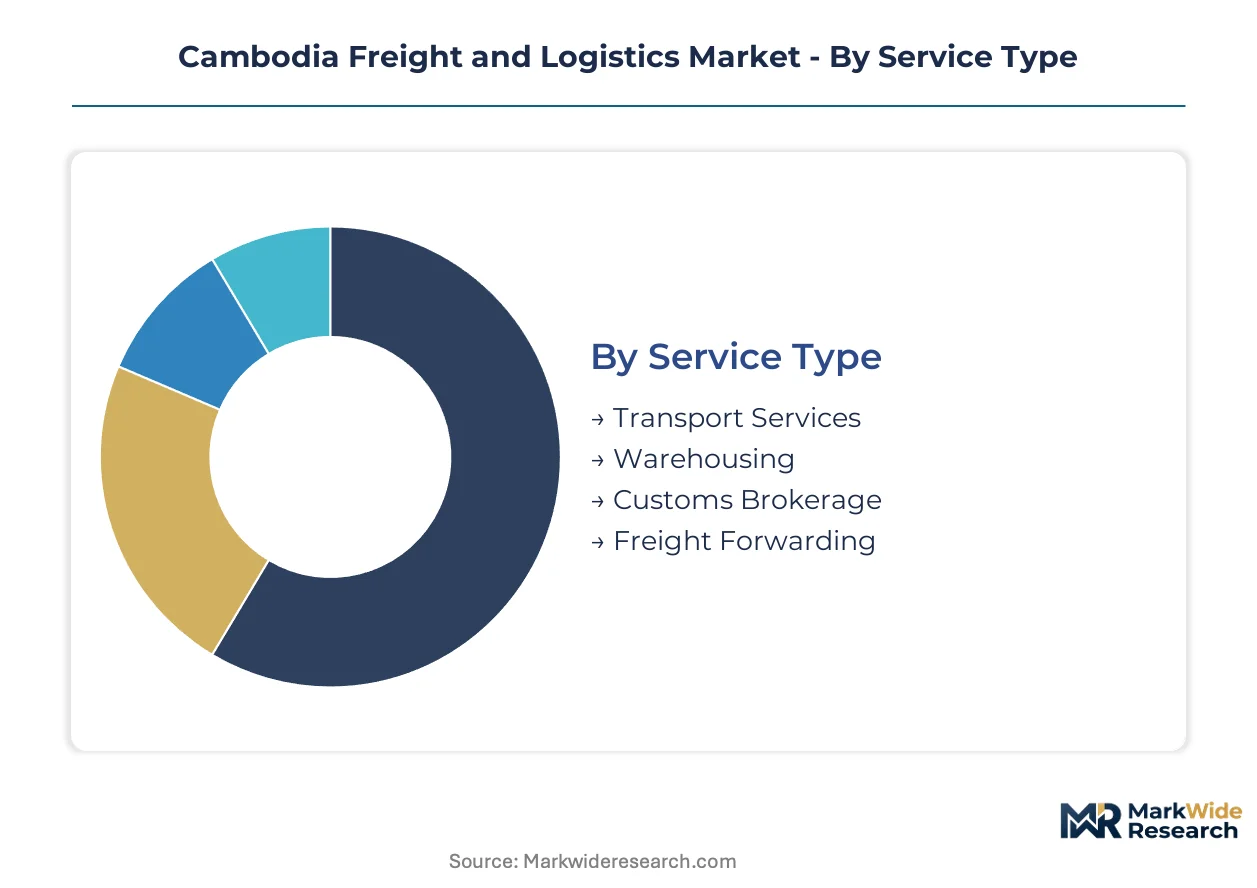
Segmentation in Cambodia freight and logistics reveals how service economics, customer urgency, and infrastructure access split margin pools across distinct operational models. Understanding these divisions exposes where bonded warehousing investments and cross-border digitization deliver competitive advantage.
Service Type:
Cycle times compress from hours in express forwarding to weeks in long-term warehousing contracts, reshaping capital intensity and customer lock-in across each segment.
- Transport Services:Road and rail haulage contracts bundle fuel-adjusted rates with axle-load compliance under Ministry of Public Works and Transport regulations. Garment exporters in Phnom Penh special economic zones dominate contract volumes, demanding 72-hour factory-to-port cycles that pull fleet investment toward express corridors.
- Freight Forwarding:Multimodal coordination merges customs brokerage, carrier booking, and documentation management into single-contract offerings. Phnom Penh-based forwarders capture margin from ASEAN Single Window digitization by collapsing clearance windows from days to hours.
- Warehousing:Bonded facilities near Sihanoukville and Phnom Penh industrial zones serve e-commerce fulfillment and manufacturing buffer stock. Temperature-controlled specifications for agricultural exports command premium rates against ambient garment storage.
- Customs Brokerage:Declaration preparation and duty optimization services face margin compression as ASEAN Single Window protocols automate document flows. Smaller operators struggle with telematics integration complexity during peak export windows.
Transport services dominate installed base. Warehousing is where expansion concentrates.
Industry Vertical:
Customer procurement sophistication spans reverse auctions in consolidated garment buying offices to fragmented spot-market booking among rice cooperatives.
- Manufacturing:Garment and electronics producers in special economic zones contract integrated logistics packages spanning inbound raw materials to outbound finished goods. Fast-fashion lead-time compression demands synchronized bonded warehousing and express forwarding.
- E-Commerce:Cross-border parcel volumes from Chinese platforms pull demand for last-mile sorting hubs in Phnom Penh peripheral districts. Fulfillment integration requires real-time inventory visibility that legacy warehouse management systems struggle to deliver.
- Agriculture:Rice and cassava exporters install temperature-controlled container fleets to access premium ASEAN fresh-produce retail channels. Phytosanitary documentation through ASEAN Single Window portals lags among smaller cooperatives.
- Retail:Traditional distributors serving provincial markets rely on third-party logistics for irregular shipment consolidation. Direct sales channels bypass forwarders for high-value electronics imports.
Manufacturing anchors contract value. E-commerce is climbing the fastest.
Distribution Channel:
Channel selection determines price transparency and service bundling depth, with direct relationships preserving margin against platform commoditization.
- Third-Party Logistics:Asset-light operators lease container fleets and cold-chain equipment to serve garment and agricultural exporters without capital-intensive fleet ownership. Phnom Penh depot networks enable rapid response to demand spikes.
- Direct Sales:Large manufacturers negotiate annual or quarterly rate reviews directly with forwarders, displacing relationship-based contract renewal with procurement rationalization.
- Online Platforms:Digital freight marketplaces expose spot rates for container slots, compressing margins on standardized lane offerings between Sihanoukville and Vietnam border crossings.
- Wholesale:Consolidators aggregate shipments from smaller exporters to achieve volume discounts on sea-air connectivity through regional transshipment hubs.
Third-party logistics controls relationship density. Online platforms are gaining share fastest.
Transportation Mode:
Mode selection balances speed against unit cost, with multimodal combinations dominating complex supply chains.
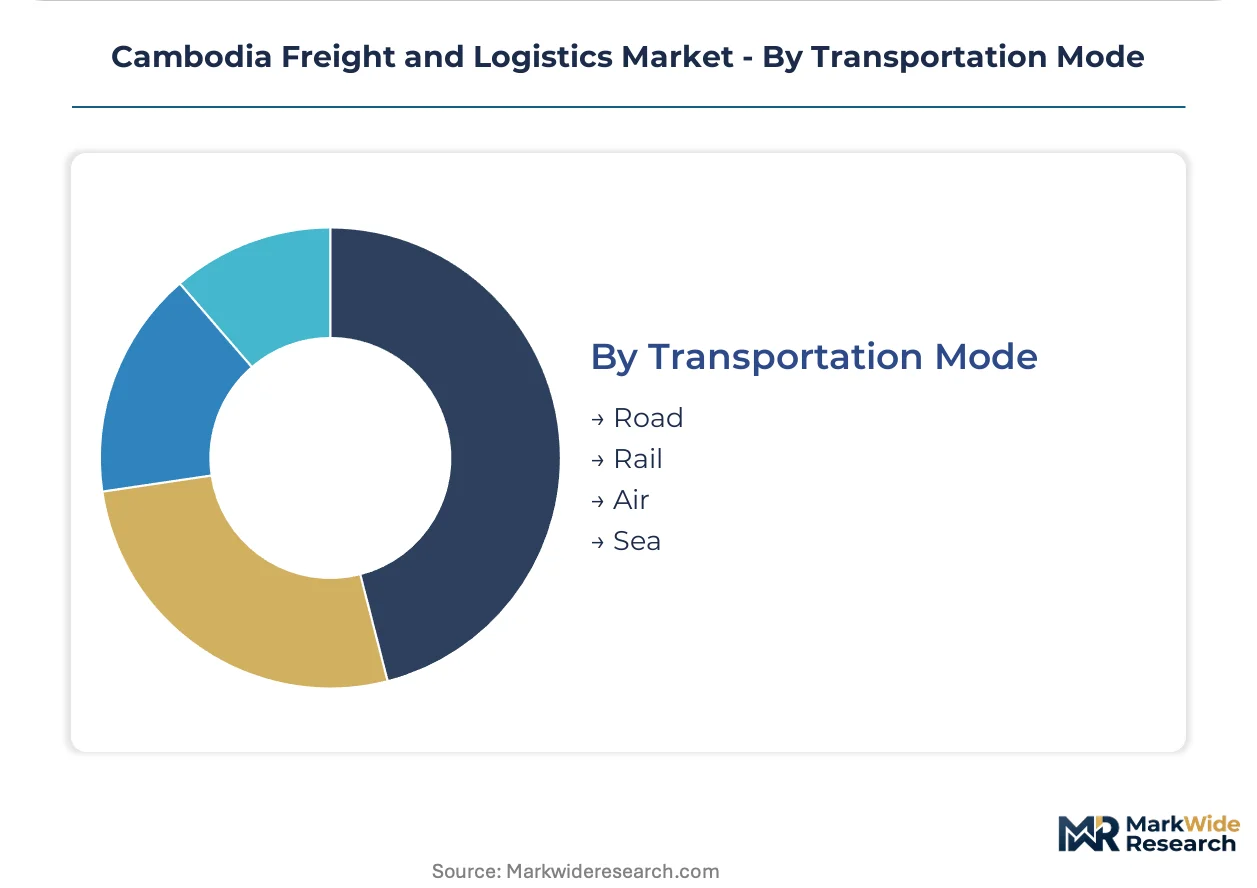
- Road:Diesel-powered trucking handles 70% of containerized trade last-mile distribution, with fuel cost volatility driving 60-70% of operating expenses. Cross-border weight standards limit fleet utilization below regional peers.
- Sea:Sihanoukville Autonomous Port anchors regional sea-air connectivity, handling the dominant share of garment export volumes. Single-point-of-failure risk concentrates just-in-time supply chain exposure.
- Air:Phnom Penh International Airport serves time-critical electronics and pharmaceutical shipments, with limited cargo capacity constraining volume growth.
- Rail:Underdeveloped network connects limited industrial zones, with potential corridor expansion toward Thai border crossings remaining speculative.
Road commands modal share. Sea is where infrastructure investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Garment buyers with 72-hour lead-time requirements cluster around Phnom Penh's special economic zones, pulling bonded warehousing investment toward Vietnam and Thailand border corridors. Agricultural exporters in Battambang and Siem Reap provinces drive cold-chain infrastructure westward. E-commerce fulfillment demand concentrates in peripheral Phnom Penh districts serving cross-border parcel flows.
Phnom Penh Capital Region
Manufacturing logistics dominates through special economic zones supplying fast-fashion brands with factory-to-port cycles measured in hours. The General Department of Customs and Excise operates ASEAN Single Window digitization hubs here, collapsing declaration processing from days to hours. Sen Sok and Meanchey districts host expanding bonded warehouse clusters serving garment-industry buffer stock requirements.
Sihanoukville Coastal Corridor
Sea-air connectivity anchors regional transshipment through the autonomous port handling the dominant share of containerized trade. The Ministry of Public Works and Transport enforces axle-load regulations on approach highways, shaping fleet investment patterns for port drayage operators. Special economic zones surrounding the port attract garment manufacturers seeking direct ocean freight access.
Bavet Border Zone
Cross-border manufacturing clearance concentrates at this Vietnam frontier crossing, where electronic component imports feed Phnom Penh assembly operations. Customs modernization under ASEAN Single Window protocols eliminates redundant paper documentation at this checkpoint. Industrial parks here specialize in just-in-time supply chain synchronization with Ho Chi Minh City manufacturing networks.
Poipet Border Crossing
Thailand-facing freight corridors handle agricultural machinery imports and rice export backhauls through this northwestern gateway. The Ministry of Public Works and Transport coordinates cross-border weight standards with Thai authorities, limiting fleet utilization rates below regional benchmarks. Warehousing investment remains sparse compared to Vietnam-facing corridors, reflecting lower manufacturing density.
Battambang Agricultural Belt
Rice and cassava exporters drive temperature-controlled container fleet installation to access premium ASEAN fresh-produce retail channels. Phytosanitary documentation through ASEAN Single Window portals lags among smaller cooperatives here compared to integrated trading houses. Cold-chain infrastructure gaps persist despite growing demand from regional supermarket procurement networks.
Cambodia Freight and Logistics Market Competitive Environment
Channel-controlling players compete with product-specialist players across bonded warehousing, cross-border clearance, and multimodal coordination segments. Market structure fragments between asset-light leasing operators and port-anchored integrated providers, with concentration visible in Phnom Penh depot networks and Sihanoukville sea-air connectivity. Three archetypes dominate: garment-industry forwarders with SEZ-integrated warehousing, e-commerce parcel specialists with last-mile sorting capacity, and agricultural cold-chain operators with temperature-controlled fleets. Competitive moves center on bonded facility expansion near industrial corridors and telematics integration with ASEAN Single Window data standards.
Within the integrated forwarding tier, Twin Logistics (Cambodia) and Bolloré Logistics (Cambodia) represent contrasting geographic anchoring strategies—Phnom Penh depot networks versus port-centric sea-air operations. SEKO Logistics Cambodia occupies a position among cross-border clearance specialists leveraging bonded warehouse partnerships for e-commerce capacity. These three exemplify how regulatory digitization and lead-time compression are reshaping service bundling across the market.
| Leading Market Players |
|---|
| Twin Logistics (Cambodia) |
| SEKO Logistics Cambodia |
| Heng Heng Import Export |
| CHLL Global Logistics |
| Master Delivery Import Export |
| BEST Express Cambodia |
| Bolloré Logistics (Cambodia) |
| Macle Logistics (Cambodia) |
| J&T Express |
| Others |
Value Chain & Pricing Dynamics
Diesel supply concentration in Thailand and Vietnam refineries directly determines where margin pools accumulate across Cambodian road-freight tiers. Fuel cost pass-through mechanisms favor integrated operators with bonded warehousing assets that can buffer rate volatility for garment exporters.
Pricing Analysis
Certification level under ASEAN Single Window protocols creates the primary spread between premium customs brokers and commodity forwarders. Three-tier pricing structure across bonded-warehouse-integrated, clearance-only, and spot-market operators reflects digitization readiness. Pricing pressure stems from reverse auctions run by consolidated garment buying offices in Phnom Penh special economic zones. Small rice cooperatives in Battambang exhibit highest price sensitivity due to fragmented volumes and lagging phytosanitary system integration.
Supply Chain Analysis
Upstream feedstock for containerized trade flows through Singapore transshipment hubs and Thai Gulf feeder networks before reaching Sihanoukville Autonomous Port. Diesel fuel, refrigerated container units, and chassis equipment draw from Thailand, China, and Vietnam manufacturing bases. Single-point-of-failure risk concentrates at Sihanoukville port handling the dominant share of garment export volumes. Distribution runs through Phnom Penh depot networks for last-mile industrial zone connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN Single Window digitization is compressing customs clearance windows from days to hours, creating high-growth disruption for logistics operators that can integrate telematics with bonded warehousing networks.
For Market Incumbents: Insulate margin pools by deepening backward integration into cold-chain equipment leasing and securing exclusive bonded warehouse partnerships near Phnom Penh special economic zones. Threat from asset-light digital freight marketplaces demands accelerated API compatibility with ASEAN Single Window data standards. Certification investment in temperature-controlled handling protocols preserves premium positioning against commodity forwarders.
For New Entrants and Emerging Players: Kampot and Koh Kong corridor development represents the most penetrable entry point for greenfield logistics park sites with direct Thai Gulf access bypassing Sihanoukville congestion. E-commerce fulfillment integration in Phnom Penh peripheral districts offers second white-space target for cross-border parcel sorting capacity. Go-to-market angle should emphasize real-time inventory visibility that legacy warehouse management systems struggle to deliver.
For Investors and Strategic Acquirers: Capital is best deployed toward asset-light operators with established Phnom Penh depot networks and ASEAN Single Window integration capabilities. Long-term viability over a multi-year horizon favors bonded warehousing specialists serving garment-industry lead-time compression requirements. Signal to watch is Cambodia's pending WTO Trade Facilitation Agreement accession accelerating customs automation and exposing domestic forwarders to ASEAN-wide competitive benchmarking.
| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Network Expansion | Captures margin from 72-hour garment factory-to-port cycle compression in Phnom Penh special economic zones. |
| Telematics-Customs Integration | Enables API compatibility with ASEAN Single Window protocols during peak export windows. |
| Cold-Chain Fleet Leasing | Addresses refrigeration technician scarcity while serving rice and cassava premium channel access. |
| Cross-Border Corridor Development | Bypasses Sihanoukville single-point-of-failure risk through Kampot and Koh Kong greenfield sites. |
| E-Commerce Fulfillment Partnership | Secures last-mile sorting capacity for Chinese platform parcel volumes in peripheral Phnom Penh districts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with logistics operations directors, customs brokerage managers, garment procurement leads at special economic zones, and cold-chain fleet operators; and secondary validation through Cambodia's General Department of Customs and Excise trade statistics, ASEAN Single Window implementation reports, Ministry of Public Works and Transport axle-load regulation filings, and Sihanoukville Autonomous Port throughput disclosures. Bottom-up triangulation across service type, industry vertical, and transportation mode segmentation was cross-checked against top-down market sizing.
Forecast inputs span transport services, freight forwarding, warehousing, and customs brokerage segments across road, sea, air, and rail modalities. Manufacturing, e-commerce, agriculture, and retail verticals were modeled with bonded facility capacity and digitization readiness as industry-specific dimensions. CAGRs were derived from historical trajectory analysis adjusted for ASEAN Single Window protocol implementation pace and garment export lead-time compression trends.
Practitioners should monitor fuel cost volatility, driver certification bottleneck resolution, and WTO Trade Facilitation Agreement accession progress for early signals of forecast revision. Cross-checking against Vietnam and Thailand logistics market benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
On-Demand Logistics Market
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Courier, Express and Parcel Services Market