
 Cargo Hold Coatings Market | 2026-2036
Cargo Hold Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Hold Coatings Market Analysis
Waterborne epoxy technology is narrowing the performance gap with solvent-based systems in cargo hold applications. PPG Industries leverages captive resin production to control formulation costs across major shipyard contracts. Jotun anchors its position through specialized anti-corrosive primers designed for iron ore and coal transport cycles. Hempel competes on global service networks that reduce vessel downtime during scheduled dry-docking.
Cargo hold coatings are high-build protective systems, typically 300–500 μm dry film thickness, formulated from bisphenol-A epoxies or novolac phenolics to resist mechanical abrasion from bulk cargoes and chemical attack from hold-cleaning agents. Their primary purpose is extending steel substrate life while reducing cargo contamination and facilitating faster hold washing between voyages. Epoxy formulations dominate newbuild specifications due to established certification from classification societies, while polyurethane topcoats capture premium retrofit demand where extended gloss retention justifies higher material costs. Spray coating technology leads application methods in automated shipyard environments, though brush and roll techniques persist in emergency repairs and smaller vessel segments.
IMO marine environmental regulations, REACH chemical restrictions in Europe, and China's MEE volatile organic compound controls collectively elevate barrier-to-entry for uncertified coating suppliers. Classification society rules from DNV, ABS, and Lloyd's Register mandate specific performance testing that shapes product development priorities. Stakeholders must monitor bio-based epoxy hardener commercialization and its potential to disrupt incumbent petrochemical supply chains.
Market Dynamics
Dry bulk carrier fleet operators face mounting pressure to extend vessel service life while IMO 2023 marine coating standards mandate lower-VOC formulations. This tension between capital preservation and regulatory compliance is forcing coating specification changes across newbuild and retrofit schedules simultaneously.
Growth Catalysts
- IMO 2023 marine coating standards:Tightened volatile organic compound limits in maritime applications accelerate replacement cycles for legacy solvent-based systems.
- Iron ore transport cycles:Specialized anti-corrosive primer demand rises as bulk carriers handle abrasive mineral cargoes on Asia-Australia routes.
- China shipyard output:Concentrated newbuild activity in Dalian, Shanghai, and Guangzhou clusters sustains specification-grade epoxy consumption.
Market Restraints
- Bisphenol-A epoxy resin price volatility:Petrochemical feedstock fluctuations compress formulation margins for high-build protective systems.
- Classification society certification timelines:DNV, ABS, and Lloyd's Register testing protocols create 12-18 month product validation bottlenecks.
- Waterborne epoxy performance gap:Mechanical abrasion resistance in iron ore holds remains inferior to solvent-based novolac phenolics.
Strategic Opportunities
- India ship repair hubs:Alang-Sosiya and Mumbai clusters lack certified coating applicator density, creating service network expansion potential.
- Bio-based epoxy hardener commercialization:Lignin-derived curing agents from Nordic biorefineries promise petrochemical supply chain disruption.
- Automated spray application:Robotic coating systems in South Korean shipyards reduce labor dependency and film thickness variability.
Industry Challenges
- Certified applicator scarcity:Classification society-qualified spray technicians concentrate in China and South Korea, constraining global service expansion.
- Hold-cleaning chemical compatibility:Aggressive alkaline wash protocols degrade coating interfaces, accelerating premature failure investigations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Hold Coatings Market |
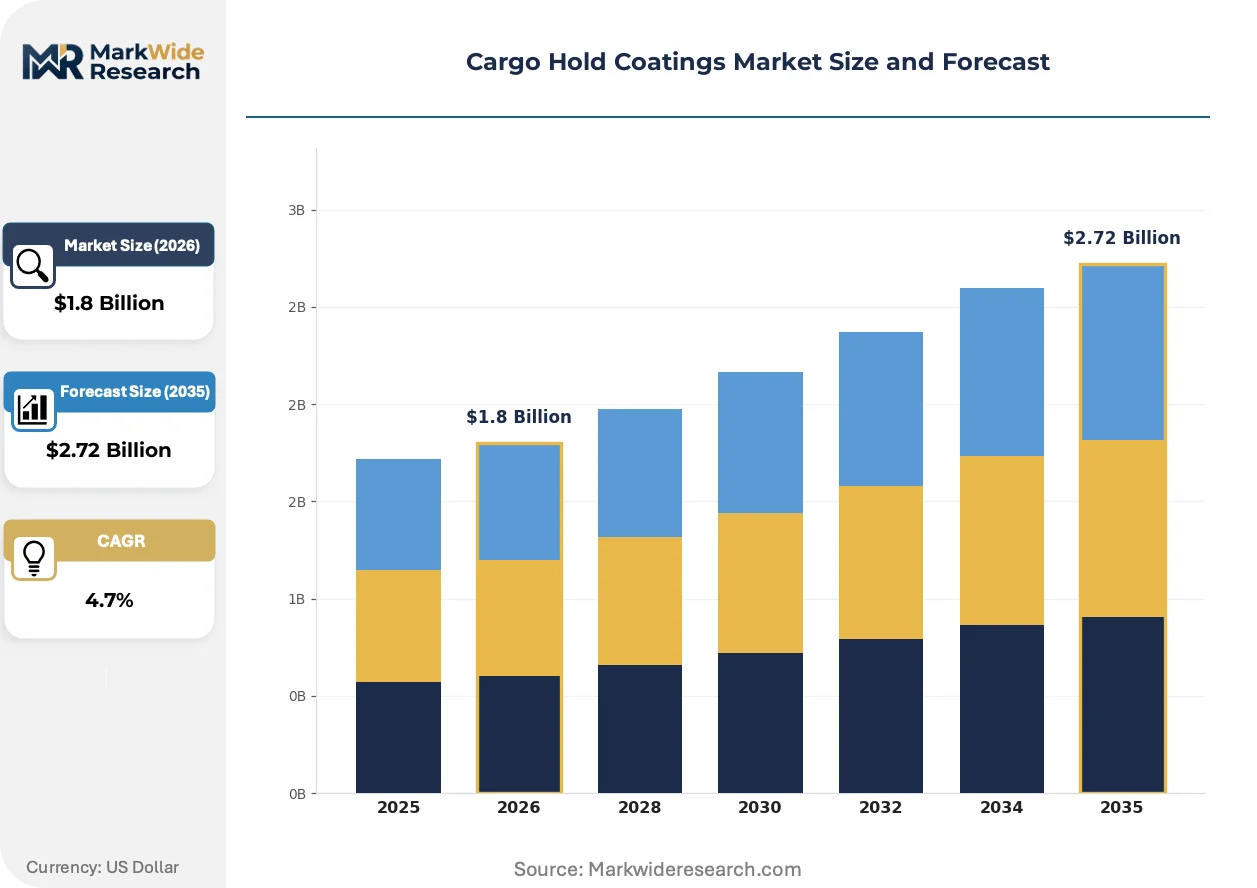
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Phenolic Application: Dry Bulk Carriers, Tankers, Container Ships, Fishing Boast End User: Shipping Companies, Vessel Owners, Freight Operators, Charter Services Technology: Spray Coating, Brush Application, Roll Application, Electrostatic Coating |
| Companies Covered | Jotun, Nippon Paint, PPG Industries, RPM International, Chugoku Marine Paints, Sherwin-Williams, Hempel, Henkel, Akzo Nobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Hold Coatings Market Emerging Trajectories
Digital coating specification tools and predictive maintenance analytics are compressing traditional procurement cycles. Fleet operators now demand real-time film thickness verification and performance tracking across dry-docking intervals.
High-solids epoxy formulations are virtualizing the trade-off between application efficiency and environmental compliance. Korean and Japanese shipyards specify these systems for 80% of newbuild contracts. The technology is virtualizing regulatory compliance costs while maintaining mechanical performance in coal and grain holds.
REACH chemical restrictions in Europe and China's MEE volatile organic compound controls are synchronizing formulation requirements across previously divergent regulatory zones. Coatings suppliers must now design single product lines satisfying multiple jurisdiction limits. This harmonization pressures smaller regional formulators lacking centralized R&D infrastructure.
Buyer consolidation among dry bulk fleet operators concentrates procurement leverage with top-ten shipping lines. Long-term supply agreements now bundle coating application with performance warranties, displacing spot-market material purchases. This pattern is most visible in Singapore and Hamburg, where ship management clusters coordinate fleet-wide specification standardization.
Cargo Hold Coatings Market Segmentation
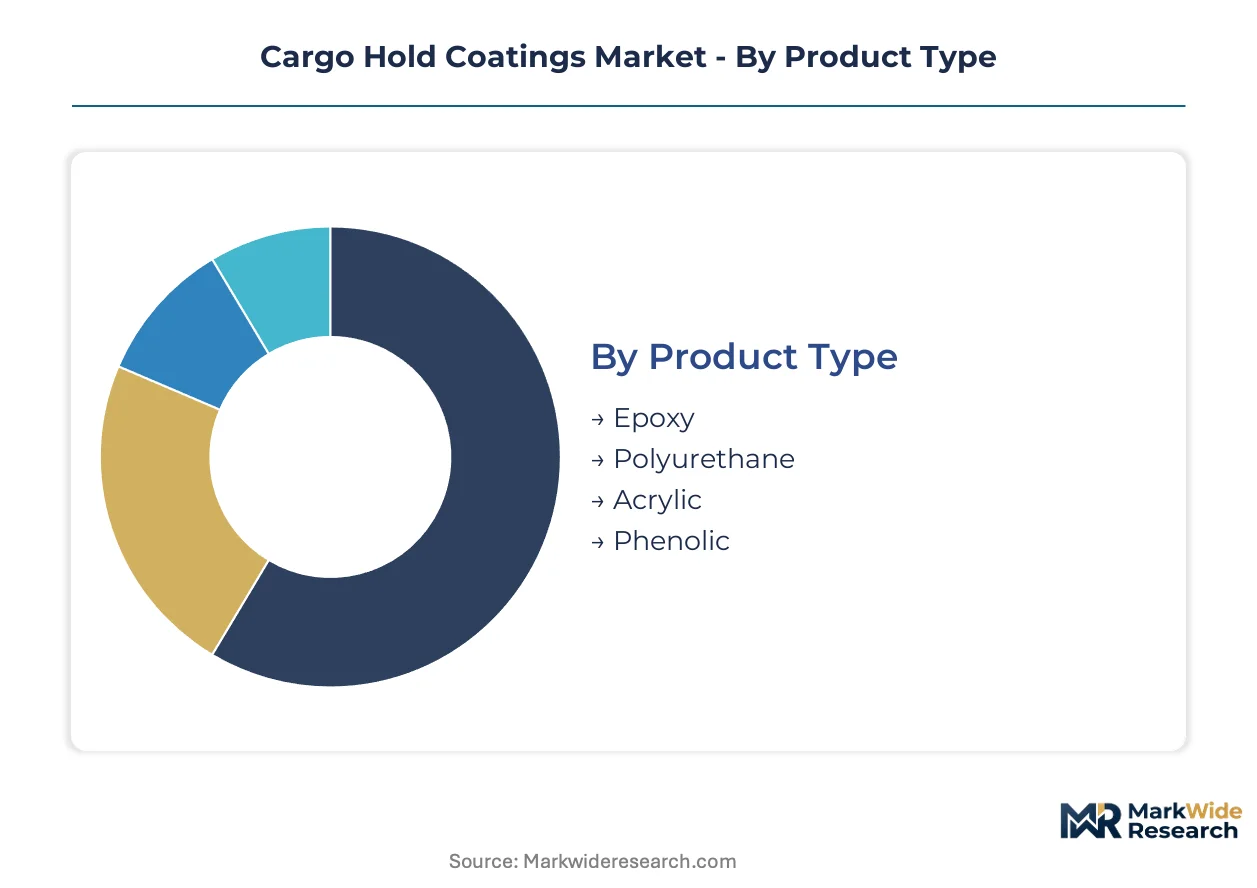
Cargo hold coating procurement varies sharply by vessel type and operational intensity. Application method and resin chemistry together determine warranty terms, dry-docking frequency, and total cost of ownership across fleet portfolios.
Product Type:
After-sales service intensity runs highest for systems requiring certified reapplication at scheduled intervals, particularly where classification society inspections mandate film thickness verification.
- Epoxy:Bisphenol-A and novolac formulations deliver 300–500 μm high-build protection against mechanical abrasion from iron ore and coal cargoes. Specification-grade epoxies dominate newbuild contracts at Dalian, Shanghai, and Guangzhou shipyards where IMO 2023 low-VOC compliance is mandatory.
- Polyurethane:Premium topcoats provide extended gloss retention and UV stability for retrofit applications where aesthetic performance justifies material cost premiums. Demand concentrates with European fleet operators seeking extended service intervals between dry-dockings.
- Acrylic:Waterborne systems serve coastal and short-sea vessels with moderate abrasion exposure and stricter local VOC limits.
- Phenolic:Novolac variants resist aggressive chemical cleaning protocols in specialized mineral ore holds.
By volume, Epoxy leads. By growth pace, Polyurethane is ahead.
Application:
Cost tier stratification separates specification-grade newbuild demand from maintenance-driven retrofit purchasing.
- Dry Bulk Carriers:Capesize and Panamax fleets require high-build systems engineered for iron ore, coal, and grain abrasion cycles. Retrofit demand accelerates as aging vessels extend service life beyond original design specifications.
- Tankers:Chemical and product tankers need specialized coatings compatible with aggressive cargo-cleaning chemicals and thermal cycling. Regulatory scrutiny from MEE and REACH elevates certified system requirements.
- Container Ships:Box hold configurations prioritize rapid turnaround and wash-down efficiency over extreme abrasion resistance.
- Fishing Boats:Smaller vessel segments rely on brush and roll application with shorter warranty periods and localized supply chains.
By volume, Dry Bulk Carriers lead. By growth pace, Tankers are climbing the fastest.
End User:
Customer type determines procurement leverage, with consolidated shipping lines commanding bundled application-and-warranty contracts.
- Shipping Companies:Top-ten operators standardize specifications across multi-vessel fleets, displacing spot-market purchasing through long-term supply agreements.
- Vessel Owners:Independent owners prioritize capital preservation and extended steel substrate life over premium coating tiers.
- Freight Operators:Charter-focused demand emphasizes rapid hold cleaning and cargo contamination prevention to minimize port turnaround times.
- Charter Services:Short-term operators defer coating investment, creating price-sensitive demand for economy-grade systems.
By volume, Shipping Companies lead. By growth pace, Charter Services are gaining share fastest.
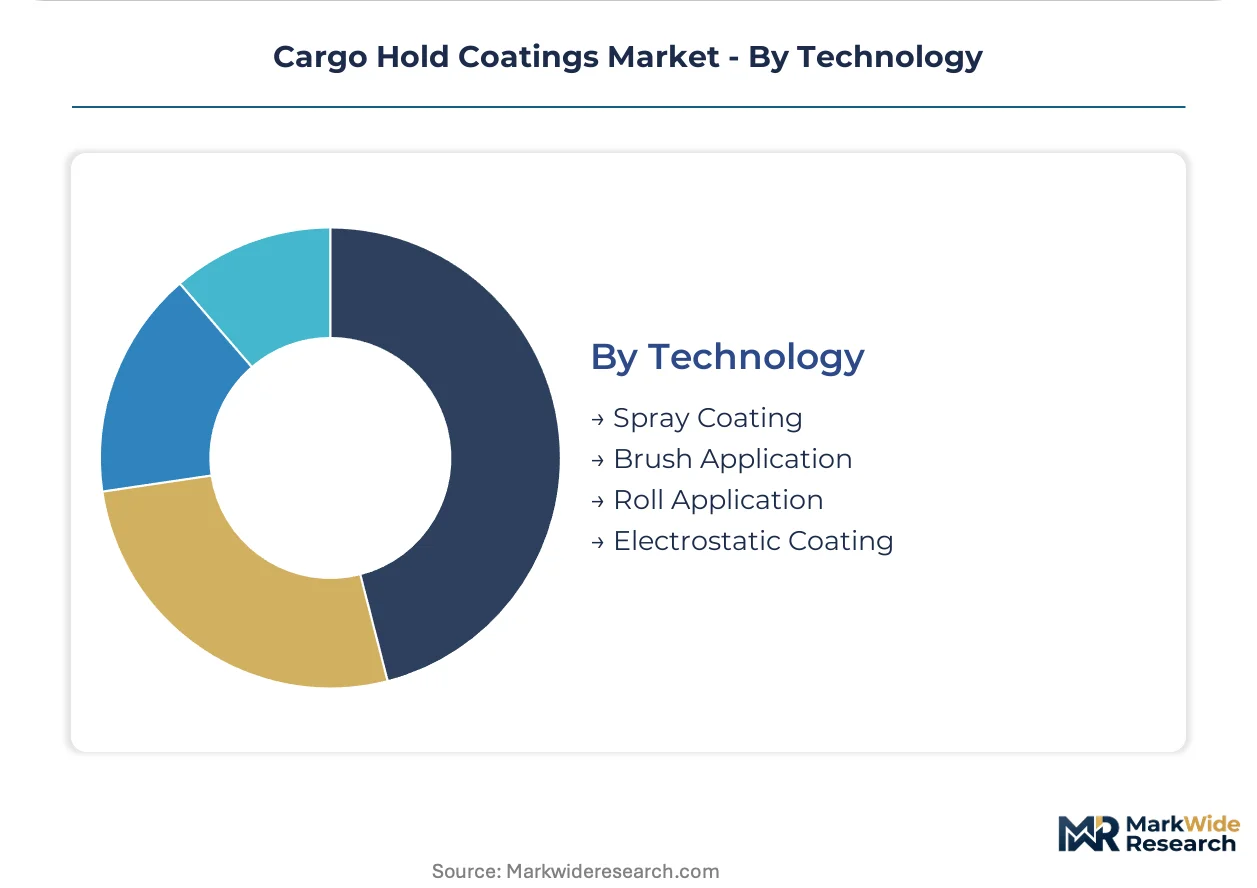
Technology:
Application method shapes labor dependency, film thickness consistency, and classification society certification requirements.
- Spray Coating:Automated robotic systems dominate South Korean and Chinese newbuild yards, reducing technician variability and enabling 80% high-solids epoxy adoption.
- Brush Application:Manual techniques persist in emergency repairs and smaller vessel segments where equipment mobilization costs are prohibitive.
- Roll Application:Intermediate method serves regional ship repair hubs with moderate throughput and certified applicator scarcity.
- Electrostatic Coating:Emerging precision application for complex hold geometries and edge retention in premium specifications.
By volume, Spray Coating leads. By growth pace, Electrostatic Coating shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry bulk fleet operators concentrate procurement leverage in Singapore and Hamburg ship management clusters, while newbuild specification-grade demand flows through Dalian, Shanghai, and Guangzhou shipyards. Regulatory divergence between IMO marine standards and national VOC controls creates formulation complexity across major maritime jurisdictions.
China
Dalian, Shanghai, and Guangzhou shipyards dominate global newbuild schedules for Capesize and Panamax vessels. MEE volatile organic compound controls tighten formulation requirements for domestic coating consumption. High-solids epoxy systems capture 80% of newbuild specifications as shipyards automate spray application lines.
South Korea
Ulsan and Geoje shipbuilding complexes drive premium coating demand for LNG carriers and specialized bulk vessels. Korean shipyards specify robotic spray systems that reduce film thickness variability below 5%. Domestic coating applicators hold classification society certifications that constrain regional service expansion.
Japan
Imabari and Oshima shipyards focus on energy-efficient vessel designs requiring extended coating service intervals. METI industrial standards influence marine coating performance benchmarks for domestic fleet operators. Nagoya-based technical societies coordinate classification society testing protocols with DNV and Lloyd's Register.
Germany
Hamburg ship management clusters standardize specifications across consolidated dry bulk fleets serving Asia-Australia iron ore routes. REACH chemical restrictions eliminate bisphenol-A epoxy variants from European retrofit schedules. Lloyd's Register certification requirements extend product validation timelines for suppliers targeting North Sea operators.
Singapore
Ship management companies coordinate fleet-wide procurement for top-ten shipping lines operating across Southeast Asian hub ports. MPA maritime regulations align with IMO 2023 standards for VOC emissions in port waters. Tuas shipyard expansion projects attract automated coating application investments from Korean and Japanese equipment suppliers.
Cargo Hold Coatings Market Vendor Landscape
Channel-controlling players compete with product-specialist players across specification-grade and retrofit market tiers. The vendor base organizes around three strategic archetypes: integrated resin-coating formulators with captive raw material supply, regional service-network operators with classification society-certified applicator pools, and technology licensors with specialized primer formulations for abrasive mineral cargoes. Competitive moves concentrate on backward integration into epoxy resin production and geographic expansion of certified service networks into undersupplied ship repair hubs.
Among integrated formulators, PPG Industries and Hempel occupy positions defined by scale and service infrastructure breadth. Jotun represents the specialized primer archetype with focused positioning in iron ore and coal transport cycles. These three companies exemplify how coating suppliers align organizational capabilities with either newbuild specification capture or retrofit warranty bundling.
| Leading Market Players |
|---|
| Jotun |
| Nippon Paint |
| PPG Industries |
| RPM International |
| Chugoku Marine Paints |
| Sherwin-Williams |
| Hempel |
| Henkel |
| Akzo Nobel |
| Others |
Supply Flow & Price Mechanics
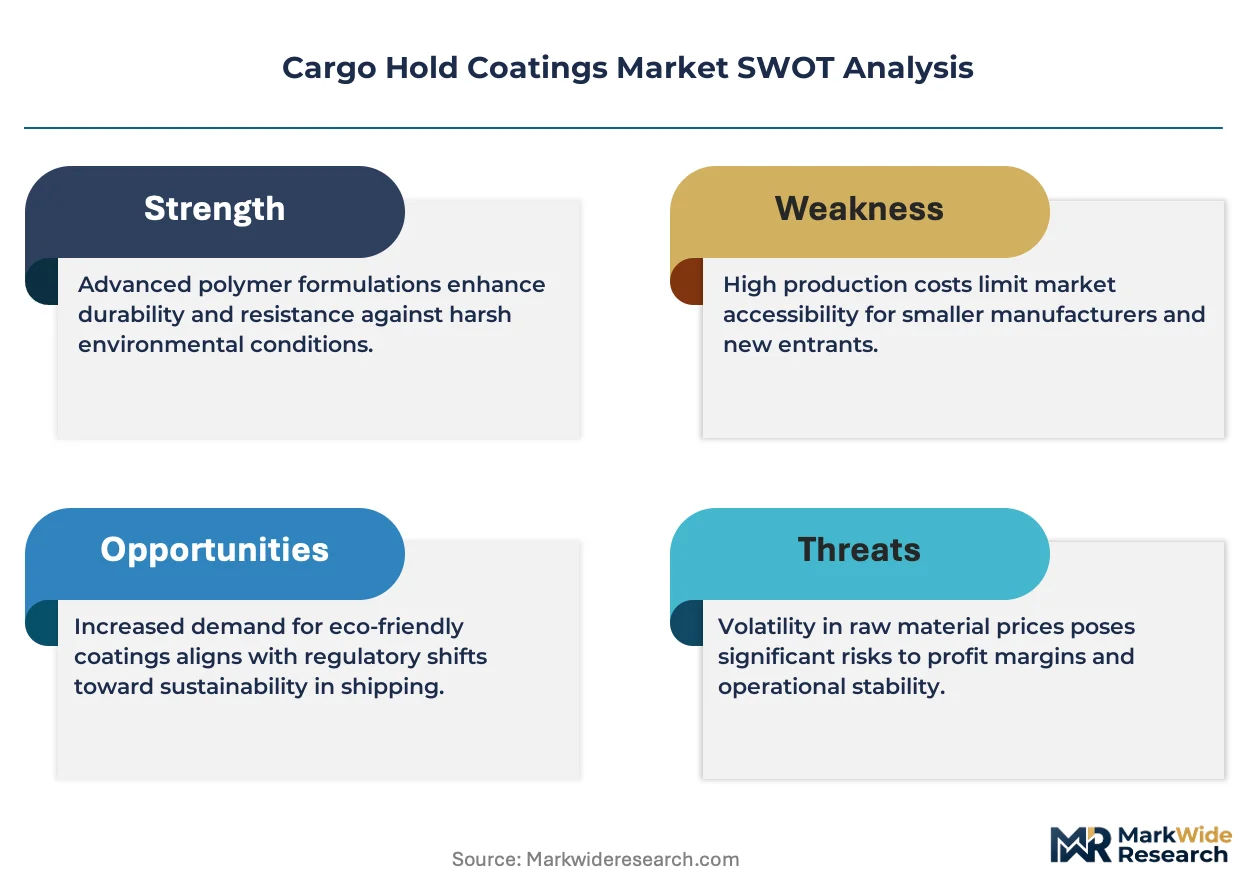
Bisphenol-A epoxy resin price volatility determines both pricing tier spreads and supply chain shape across cargo hold coating procurement. Petrochemical feedstock fluctuations compress formulation margins for high-build protective systems while forcing tiered pricing structures that separate specification-grade newbuild contracts from economy-grade retrofit materials.
Pricing Analysis
Cost-plus contracts with bisphenol-A indexation dominate procurement between integrated formulators and major shipyard clusters in Dalian and Shanghai. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's Register-certified systems from uncertified regional alternatives. Cost compression in standard-tier epoxies is intensifying because waterborne formulations narrow performance gaps with solvent-based novolac phenolics. Charter services exhibit highest price sensitivity due to short-term operational horizons, while top-ten shipping lines absorb premium tiers through bundled application-and-warranty agreements.
Supply Chain Analysis
Export-control scrutiny over advanced epoxy hardener technologies limits flows from Nordic biorefineries to Asian formulators, constraining bio-based supply chain development. Raw material concentration centers on China, South Korea, and Germany for bisphenol-A resin production, amine curing agents, and specialty anti-corrosive pigments. Single-source vulnerability runs through Chinese petrochemical complexes supplying 80% of specification-grade epoxy feedstocks. Distribution runs through ship management clusters in Singapore and Hamburg that coordinate fleet-wide specification standardization across consolidated dry bulk operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cargo hold coatings sit at an early-cycle expansion story driven by IMO 2023 compliance deadlines forcing replacement cycles across aging solvent-based fleets. Waterborne epoxy maturation and automated spray adoption create dual tailwinds for specification-grade volume growth.
For Market Incumbents: Insulate formulation margins through captive resin production and backward integration into bisphenol-A supply chains. PPG Industries demonstrates this model across major shipyard contracts. Certification investment with DNV and Lloyd's Register creates switching costs against emerging waterborne specialists threatening solvent-based incumbency. For New Entrants and Emerging Players: Establish a beachhead in India's Alang-Sosiya and Mumbai ship repair hubs where certified applicator scarcity constrains incumbent service networks. Bio-based epoxy hardener commercialization from Nordic biorefineries offers a go-to-market angle targeting European fleet operators facing REACH chemical restrictions. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors integrated formulators with captive raw material supply and classification society-certified service networks. Acquisition targets should demonstrate Lloyd's Register or DNV testing protocols already completed. The signal to watch is bio-based hardener cost parity with petrochemical alternatives as inflection indicator for supply chain disruption potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | PPG Industries leverages captive supply to control formulation costs across Dalian and Shanghai shipyard contracts. |
| Classification Society Certification Investment | Jotun anchors market position through DNV-validated anti-corrosive primers for iron ore transport cycles. |
| Automated Spray Application Deployment | South Korean shipyards specify robotic systems reducing film thickness variability below 5% for high-solids epoxies. |
| Service Network Expansion into Undersupplied Hubs | Hempel competes through global certified applicator pools reducing vessel downtime during scheduled dry-docking. |
| Bio-Based Hardener Commercialization Partnership | Nordic biorefineries develop lignin-derived curing agents threatening petrochemical supply chain incumbency. |
Methodological Framework
Operator-level perspectives from fleet technical managers, shipyard procurement directors, classification society surveyors, and coating applicator supervisors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through IMO regulatory filings, Lloyd's Register certification databases, MEE volatile organic compound enforcement records, and customs trade data for epoxy resin flows. Bottom-up vessel fleet modeling and top-down chemical consumption estimates were triangulated against shipyard output statistics from Dalian, Shanghai, and Guangzhou clusters.
Scenario-bracketing around waterborne epoxy penetration rates, bio-based hardener cost curves, and automated spray adoption timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, vessel type, application method, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and newbuild specification trends. Forecast inputs incorporated dry bulk carrier fleet age profiles and IMO compliance deadline enforcement intensity.
Stress conditions across bisphenol-A price volatility bands, MEE enforcement escalation scenarios, and waterborne performance gap closure timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about classification society certification timelines and shipyard automation adoption curves. Material shifts in REACH chemical restriction scope or IMO marine coating standard amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Marine Engine Monitoring System Market