
 Europe Inland Water Freight Transport Market | 2026-2036
Europe Inland Water Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Inland Water Freight Transport Market Foresight
Aftermarket service revenue from vessel retrofitting and engine upgrades is rewriting profit distribution across the Europe inland water freight transport value chain. Rhenus Group leverages its integrated terminal network to control cargo consolidation points along the Rhine. HGK Shipping GmbH anchors its position through specialized liquid cargo operations serving chemical producers. Royal Wagenborg competes across northern European waterways with ice-class capabilities that extend operating seasons.
Europe inland water freight transport encompasses the movement of goods via navigable rivers, canals, and lakes using motorized vessels with draft capacities typically ranging from 1.2 to 3.5 meters, where barge convoys can haul 1,500 to 12,000 tonnes per movement depending on waterway classification. The primary purpose remains bulk commodity and container repositioning at substantially lower fuel intensity per tonne-kilometer than road alternatives. Bulk cargo movements dominate volume throughput along the Danube and Rhine corridors, reflecting sustained agricultural and construction material flows. Containerized cargo represents the fastest-expanding segment as shippers convert maritime boxes to inland waterway legs for hinterland distribution. Liquid cargo operations sustain premium margin pools due to specialized tanker requirements and hazardous material handling certifications.
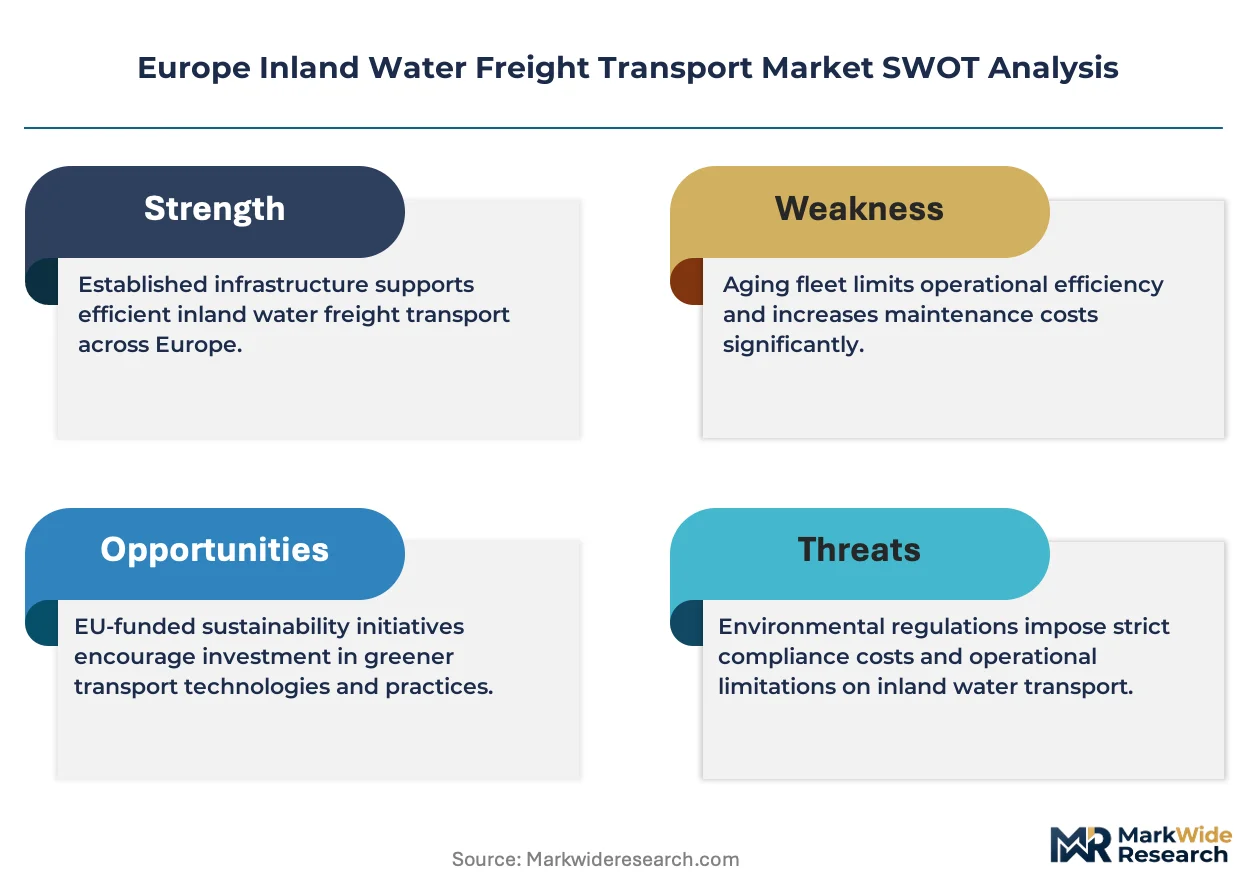
The EU Green Deal and its accompanying F-Gas Regulation for refrigerant systems aboard vessels, alongside CE marking requirements for onboard equipment, are mandating fleet emission reductions and propulsion technology transitions that reshape capital deployment decisions. The European Maritime Safety Agency coordinates with national river authorities to harmonize technical standards across transboundary waterways. Stakeholders must monitor how EU AI Act provisions for autonomous navigation systems will alter crewing requirements and operational cost structures before committing to newbuild programs.
Market Dynamics
EU Green Deal emission mandates are compressing fleet renewal timelines while chemical manufacturers accelerate modal shift commitments, forcing capital reallocation toward low-carbon propulsion systems and terminal electrification infrastructure.
Growth Catalysts
- Rhine corridor infrastructure modernization:Lock capacity expansions at Kaub and Iffezheim enable larger convoy formations. Belgian and Dutch port authorities coordinate dredging programs that deepen draft allowances for 12,000-tonne vessels.
- F-Gas Regulation compliance deadlines:Vessel retrofitting demand for refrigerant system upgrades generates aftermarket service revenue streams. Specialized workshops across Germany and the Netherlands expand capacity to handle simultaneous fleet conversions.
- Containerized cargo modal conversion:Maritime shippers reposition boxes onto barge legs for hinterland distribution. Rotterdam and Antwerp terminal operators invest in intermodal crane systems that compress box transfer times.
Market Restraints
- Steel price volatility:Hull construction and engine fabrication costs fluctuate with scrap metal and alloy input markets. Shipyards pass through material cost swings via extended delivery timelines rather than fixed pricing.
- Danube waterway fragmentation:Romanian and Bulgarian lock infrastructure lags Rhine standards, creating bottlenecks that limit convoy economies. Navigation interruptions during low-water seasons constrain reliable capacity planning.
- Battery energy density limitations:Current lithium-ion configurations cannot support multi-day Rhine operations without mid-route charging infrastructure that remains underdeveloped.
Strategic Opportunities
- Polish waterway network expansion:Oder and Vistula river modernization programs open east-west corridors connecting Baltic ports to industrial hinterlands. Terminal development at Szczecin and Gdansk attracts logistics investment.
- EU AI Act autonomous navigation frameworks:Regulatory clarity on reduced-crewing operations enables remote monitoring center investments. River authorities in Belgium and France pilot corridor-specific exemption protocols.
- Ammonia and methanol bunkering infrastructure:Port authorities along the Rotterdam-Duisburg axis develop fuel supply chains for dual-fuel newbuilds. Chemical producers seek offtake agreements that anchor zero-emission logistics commitments.
Industry Challenges
- Marine engineer certification bottlenecks:Specialized training for hybrid-electric propulsion systems outpaces institutional capacity. German and Dutch maritime academies struggle to scale enrollment for dual-credential programs.
- Legacy fleet depreciation schedules:Asset owners face compressed residual values as emission zones expand. Financing institutions tighten collateral requirements for conventional diesel vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Inland Water Freight Transport Market |
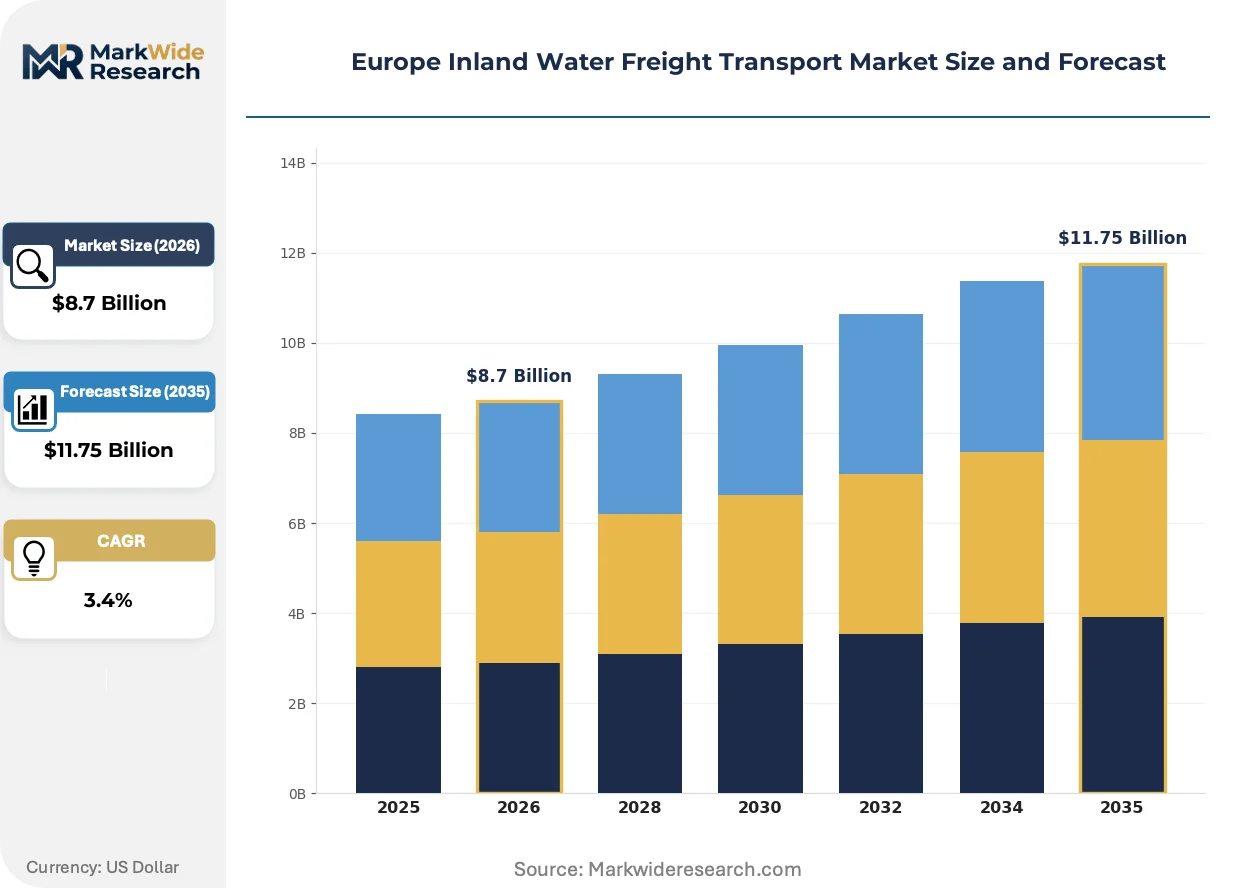
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Barge, Tugboat, Container Vessel, Self-Propelled Vessel Cargo Type: Bulk Cargo, Liquid Cargo, Containerized Cargo, General Cargo Operation Type: Scheduled Service, Charter Service, Dedicated Transport, On-Demand Transport Client Type: Manufacturers, Retailers, Logistics Providers, Government Agencies |
| Companies Covered | Rhenus Group, Royal Wagenborg, Rhenus PartnerShip GmbH & Co. KG, Wagenborg Nedlloyd, Compagnie Maritime Belge, HGK Shipping GmbH, EURO-RIJN B.V., Port-Liner, Gefo Gesellschaft für Oeltransporte mbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Inland Water Freight Transport Market Shifts & Advancements
Propulsion technology transitions and digital navigation systems are compressing operational cost structures while regulatory compliance requirements reshape capital deployment priorities across European waterways.
Hybrid-electric propulsion architectures with shore-power connectivity are rendering obsolete conventional diesel-mechanical drive trains for Rhine corridor operations. Chemical transport operators and container lines specify hybrid configurations for newbuild orders to secure EU Green Deal compliance trajectories. Shipyards in the Netherlands and Germany reconfigure production lines around modular battery-electric packages that reduce engine room footprint and crew maintenance burden.
CE marking requirements for onboard equipment under the EU Green Deal framework are tightening component traceability and emissions verification protocols. Vessel operators must document refrigerant system compliance under F-Gas Regulation standards that phase down hydrofluorocarbon use. Tanker fleets serving hazardous cargo routes face accelerated inspection cycles as national river authorities harmonize enforcement across transboundary waterways.
Shippers are consolidating procurement decisions through dedicated barge service contracts that displace spot-market chartering for core volume lanes. Container lines and chemical manufacturers negotiate multi-year agreements that embed emission reporting obligations and capacity reservation terms. This contractual shift concentrates purchasing power among large cargo owners along the Netherlands-Germany-Belgium corridor where terminal density supports reliable schedule integrity.
Europe Inland Water Freight Transport Market Segmentation
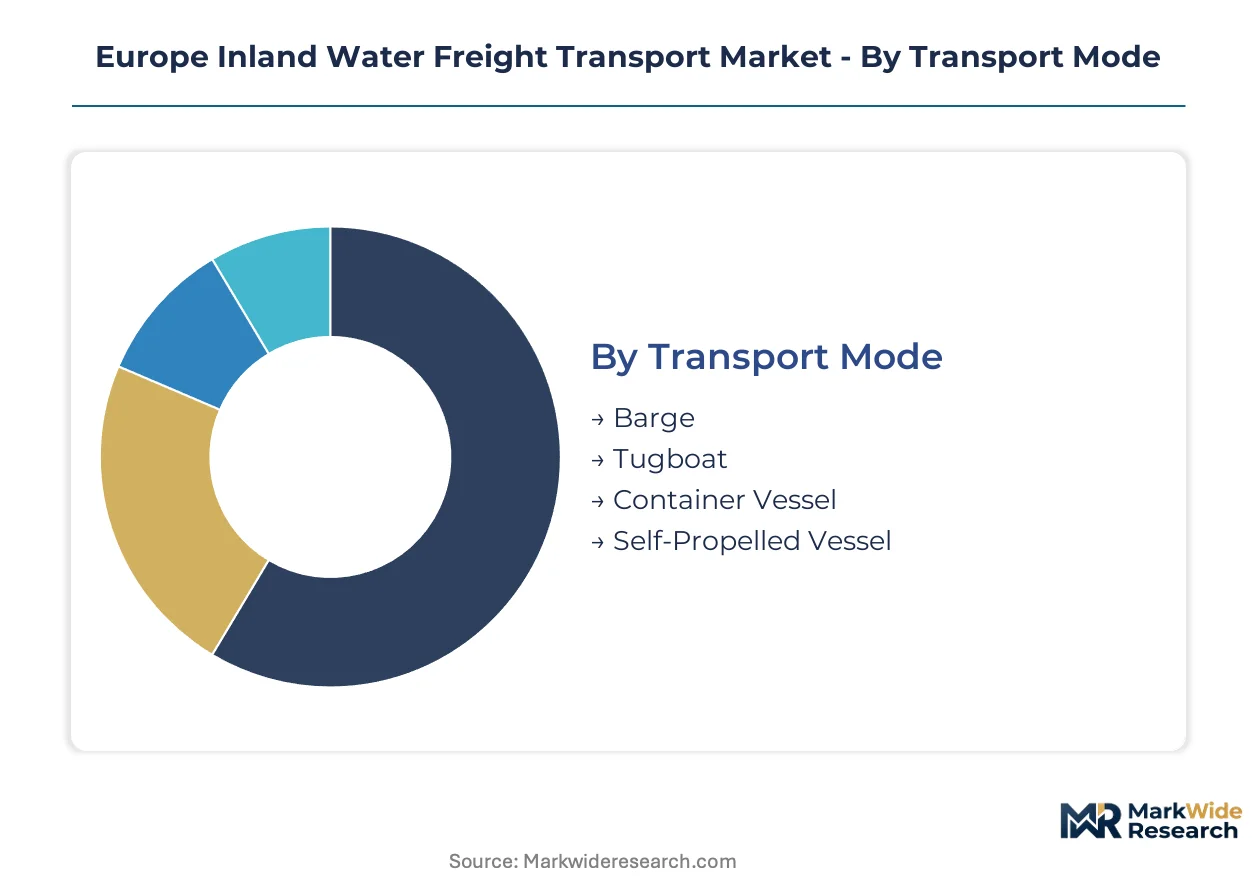
Segmentation reveals how cargo characteristics, vessel configurations, and contractual arrangements reshape capital deployment and margin structures across European waterways. Each dimension exposes distinct operational constraints and regulatory exposure profiles that determine competitive positioning.
Transport Mode:
Cost tier differentiation across vessel categories determines fleet renewal priorities and propulsion technology migration paths.
- Barge:Non-propelled cargo platforms with 1,200-12,000 tonne capacity towed by push boats along Rhine and Danube corridors. Chemical manufacturers and construction material suppliers along the Netherlands-Germany corridor concentrate demand here as EU Green Deal emission zones expand.
- Container Vessel:Purpose-built box carriers with cellular holds and crane-compatible deck structures for intermodal transfers. Rotterdam and Antwerp terminal operators drive specification requirements as maritime shippers convert hinterland legs from road to water.
- Tugboat:Propulsion units providing motive power for barge convoys through lock systems and shallow-draft sections.
- Self-Propelled Vessel:Integrated cargo and propulsion systems suited to fragmented waterway networks with limited towboat availability.
Barge configurations hold installed capacity. Container Vessel is rotating up the share rankings.
Cargo Type:
Application-specific handling requirements create divergent certification burdens and terminal infrastructure needs across the value chain.
- Liquid Cargo:Petroleum products, chemicals, and edible oils transported in double-hull tankers with hazardous material certifications. BASF and Dow operations along the Rhine corridor sustain premium pricing as F-Gas Regulation compliance tightens vessel specifications.
- Containerized Cargo:Maritime boxes repositioned onto barge legs for hinterland distribution with intermodal documentation. Belgian and Dutch port authorities invest in crane systems that compress transfer times as modal shift accelerates.
- Bulk Cargo:Agricultural commodities, ores, and construction aggregates moved in open-hold vessels with grab unloading systems.
- General Cargo:Breakbulk manufactured goods requiring project-specific stowage and lashing configurations.
Liquid Cargo commands margin premiums. Containerized Cargo is climbing the fastest expansion trajectory.
Operation Type:
Volume predictability and asset utilization rates vary sharply across contractual arrangements, reshaping fleet sizing decisions.
- Scheduled Service:Fixed-route, fixed-departure operations with published timetables and capacity reservations. Container lines and chemical manufacturers along the Rotterdam-Duisburg axis negotiate multi-year agreements embedding emission reporting obligations.
- Dedicated Transport:Exclusive vessel allocation for single cargo owners with continuous volume flows. Steel producers and power utilities with stable raw material needs anchor this segment.
- Charter Service:Spot-market vessel procurement for project cargo and seasonal volume spikes.
- On-Demand Transport:Ad-hoc dispatch responding to unplanned logistics requirements with premium pricing.
Scheduled Service anchors revenue stability. Dedicated Transport is gaining share fastest among large industrial cargo owners.
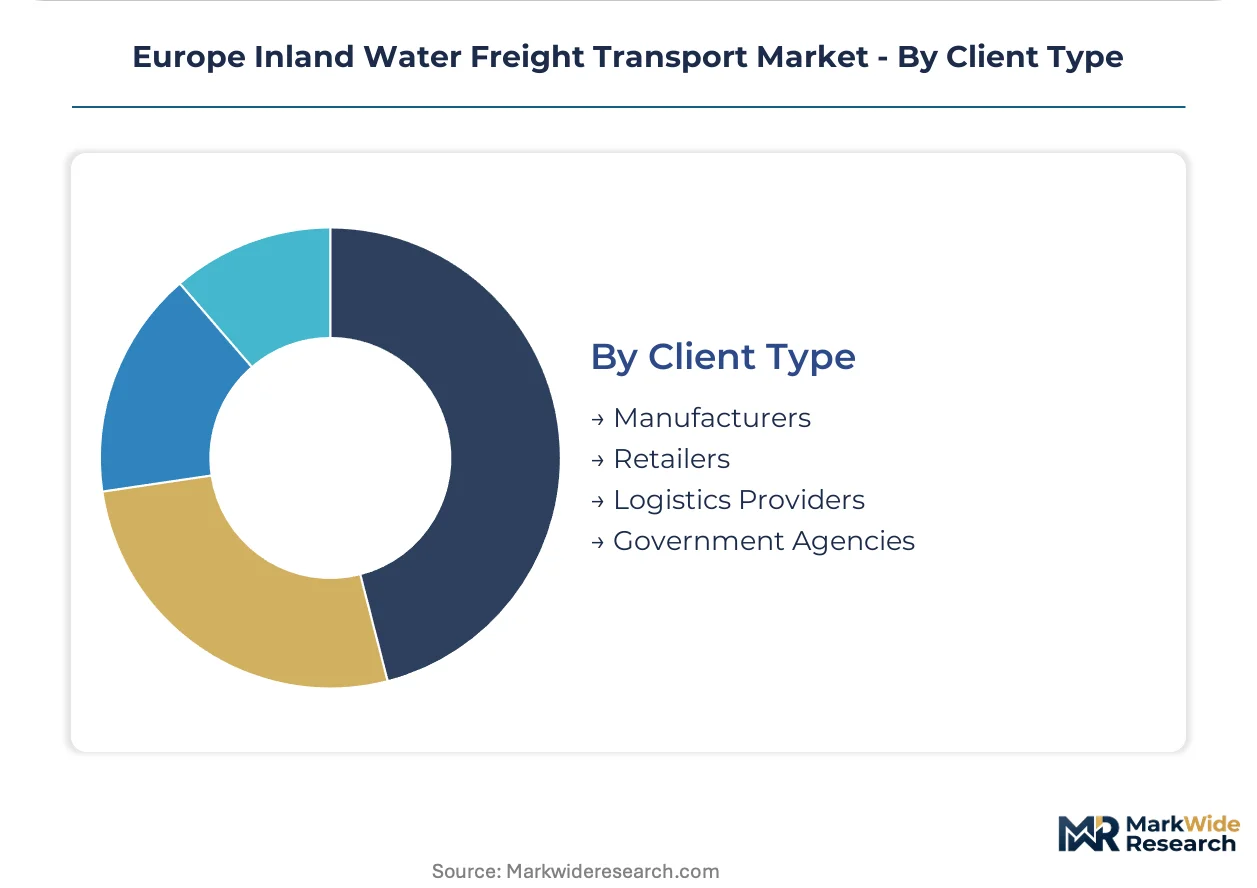
Client Type:
Customer concentration and procurement sophistication determine pricing power distribution and contract structure complexity.
- Manufacturers:Chemical producers, steel mills, and food processors with continuous inbound raw material and outbound finished goods flows. German and Dutch industrial clusters consolidate purchasing through dedicated barge service contracts displacing spot-market chartering.
- Logistics Providers:Third-party operators managing multi-modal supply chains with asset-light or asset-heavy positioning. Rhenus Group and similar integrated networks control cargo consolidation points through terminal ownership.
- Retailers:Consumer goods distributors with seasonal volume volatility and containerized cargo preferences.
- Government Agencies:Public sector entities managing strategic reserve movements and infrastructure construction materials.
Manufacturers hold contract volume concentration. Logistics Providers are rotating up the share rankings as outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhine corridor economies deploy containerized and liquid cargo fleets at higher intensity than Danube markets, where bulk agricultural movements still dominate waterway economics. This consumption-mix differential shapes infrastructure investment priorities and fleet specification patterns across European river systems.
Netherlands
Rotterdam and Antwerp maritime terminals drive containerized cargo conversion onto barge legs for German hinterland distribution. The Dutch Ministry of Infrastructure and Water Management coordinates lock modernization at the Volkerak and Haringvliet sluices to accommodate 12,000-tonne convoy formations. Terminal operators at Moerdijk and Venlo invest in electrified crane systems that compress intermodal transfer times.
Germany
Chemical manufacturers along the Rhine-Main corridor anchor demand for specialized tanker fleets with hazardous material certifications. The Federal Waterways and Shipping Administration enforces F-Gas Regulation compliance timelines for refrigerant system retrofits across inland vessel fleets. Duisburg and Cologne industrial clusters concentrate liquid cargo operations serving BASF and Dow production facilities.
Belgium
Port of Antwerp-Bruges operators expand barge feeder connections to capture maritime container flows for Benelux distribution. The Flemish Environment Agency implements EU Green Deal emission zone protocols that accelerate diesel vessel phase-out schedules. Ghent and Liège terminals develop ammonia bunkering infrastructure for dual-fuel newbuilds.
France
Seine-Nord canal construction and lock upgrades aim to reconnect Paris basin industries to Belgian and Dutch port networks. The French Navigation Authority pilots reduced-crewing exemption protocols under pending EU AI Act autonomous navigation frameworks. Strasbourg and Mulhouse chemical producers evaluate dedicated barge service contracts to displace road freight.
Poland
Oder and Vistula river modernization programs open east-west corridors linking Baltic ports to Silesian industrial hinterlands. The National Water Management Authority allocates EU cohesion funds to deepen draft allowances for 3,000-tonne vessel classes. Szczecin and Gdansk terminal development attracts logistics investment from German and Dutch operators seeking corridor diversification.
Europe Inland Water Freight Transport Market Competitive Landscape
Capability concentration sits with integrated terminal-network operators; scale advantage sits with diversified cargo handlers with multi-waterway presence. The vendor base organizes around three strategic archetypes: Rhine-corridor terminal owners controlling cargo consolidation points, specialized liquid cargo operators serving chemical clusters, and northern European operators with ice-class season extension capabilities. Dominant competitive moves include terminal asset acquisitions that lock in origin-destination volume flows, and fleet renewal programs embedding hybrid-electric propulsion to secure EU Green Deal compliance trajectories.
Within the integrated-network tier, Rhenus Group and Rhenus PartnerShip GmbH & Co. KG represent the terminal-control archetype through their coordinated Rhine corridor positioning. Royal Wagenborg occupies a position exemplifying the ice-class specialization vector for northern European waterway access. HGK Shipping GmbH anchors the liquid cargo premium segment through its chemical transport focus. These three company structures illustrate how geographic coverage breadth and cargo-type depth determine competitive positioning in fleet renewal capital allocation decisions.
| Leading Market Players |
|---|
| Rhenus Group |
| Royal Wagenborg |
| Rhenus PartnerShip GmbH & Co. KG |
| Wagenborg Nedlloyd |
| Compagnie Maritime Belge |
| HGK Shipping GmbH |
| EURO-RIJN B.V. |
| Port-Liner |
| Gefo Gesellschaft für Oeltransporte mbH |
| Others |
Supply & Pricing Matrix
The Rotterdam-Duisburg corridor anchors freight cost structures across European inland waterways, where terminal concentration at Dutch and German consolidation points enables differential pricing power between contract-holding incumbents and spot-market operators. EU Green Deal compliance costs feed downstream into rate negotiations, with emission-certified vessel operators commanding premiums over legacy diesel fleets while chemical manufacturers absorb pass-through charges for specialized tanker handling.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing structures along the Rhine corridor, with scheduled service contracts embedding multi-year capacity reservations and emission reporting obligations. Price differentiation rests on certification grade (EU Green Deal compliance tier) and volume scale (convoy size commitments), while cost compression in the spot-charter tier intensifies because of excess barge availability during low-water seasons. Chemical manufacturers show least price sensitivity due to hazardous cargo handling requirements; construction material suppliers exhibit highest sensitivity, driving procurement consolidation toward dedicated transport arrangements.
Supply Chain Analysis
Export-control regimes for marine propulsion technology limit flows of dual-use battery-electric systems from China, constraining fleet renewal timelines for European operators. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for hull construction and engine fabrication; raw material dependencies draw from Norwegian steel, Polish electrical components, and South Korean battery cells. Single-source vulnerability in lithium-ion supply chains poses structural risk as waterway operators accelerate hybrid-electric procurement. Distribution runs through integrated terminal networks controlled by Rhenus Group and similar operators, with cargo consolidation points determining access to hinterland volume flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe inland water freight transport sits in a cyclical recovery phase, with Rhine water levels and chemical production cycles driving volume volatility across the analysis window.
For Market Incumbents: Pre-empt margin erosion by accelerating terminal electrification investments at Rotterdam and Antwerp hubs before EU Green Deal emission zones expand. Lock in backward integration into shore-power infrastructure to capture aftermarket service revenue from vessel retrofitting demand, while defending against specialized liquid cargo entrants through hazardous material certification deepening at Duisburg and Cologne chemical clusters.
For New Entrants and Emerging Players: Polish waterway network expansion offers the most penetrable geographic entry point, with Oder and Vistula modernization programs opening east-west corridors underserved by incumbent terminal networks. Target containerized cargo modal conversion at Szczecin and Gdansk as the fastest-climbing segment; secure go-to-market positioning through intermodal crane system partnerships with Baltic port authorities rather than asset-heavy fleet deployment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive inland water logistics divisions lacking standalone scale. Long-term viability over a multi-year horizon rests on EU Green Deal compliance trajectory execution; prioritize operators with hybrid-electric newbuild pipelines and terminal network density. Watch ammonia bunkering infrastructure commitments at Rotterdam-Duisburg terminals as the inflection signal for zero-emission logistics anchor demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Electrification Investment | Moerdijk and Venlo electrified crane systems compress intermodal transfer times for Rotterdam-Antwerp container flows. |
| Hybrid-Electric Fleet Renewal | Modular battery-electric packages from Dutch and German shipyards reduce engine room footprint and crew maintenance burden. |
| Ammonia Bunkering Infrastructure | Ghent and Liège terminal development anchors zero-emission logistics commitments from chemical producers. |
| Autonomous Navigation Pilot Programs | French Navigation Authority reduced-crewing exemptions under EU AI Act enable remote monitoring center investments. |
| Polish Waterway Corridor Development | Szczecin and Gdansk terminal investment attracts German and Dutch operators seeking Danube fragmentation bypass. |
Research Methodology
Operator-level perspectives from fleet managers, terminal operators, chemical procurement leads, and maritime shippers anchored the qualitative base for this study. Primary interviews with vessel chartering executives, lock authority engineers, and EU regulatory affairs specialists combined with secondary validation from customs trade data, SEC filings of listed logistics operators, Rhine navigation authority statistics, and EU Green Deal implementation reports. Bottom-up vessel capacity and cargo flow estimates triangulated against top-down macroeconomic freight demand projections.
Scenario-bracketing framed the analytical approach across the projection horizon, with low-growth cases incorporating Danube waterway fragmentation persistence and high-growth cases assuming accelerated Polish corridor development. Segmentation dimensions modeled encompassed transport mode, cargo type, operation type, and client type alongside vessel propulsion technology migration paths. CAGRs derived from historical throughput trends, fleet renewal timelines, and modal shift elasticity assumptions; forecast inputs incorporated EU AI Act autonomous navigation regulatory clarity and F-Gas Regulation refrigerant system compliance deadlines.
Macroeconomic conditions sit as an overlay; deviation in Rhine water levels, chemical production cycles, or steel price volatility would shift the trajectory. Forecasts reflect documented assumptions regarding EU Green Deal enforcement intensity and battery energy density improvement rates. Material shifts in ammonia bunkering infrastructure deployment or EU AI Act reduced-crewing exemption protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market