
 Ship Anchor Market | 2026-2036
Ship Anchor Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Anchor Market Outlook
Aftermarket chain inspection and recertification revenue is reconfiguring profit pools away from pure equipment sales across the ship anchor supply base. VICINAY Group leverages its Spanish manufacturing heritage to dominate Mediterranean naval procurement. Jiangsu Asian Star Anchor Chain Co Ltd anchors its position through captive steel forging capacity in East China. Lister Chain and Forge Inc specializes in North American inland waterway stockless designs.
A ship anchor is a maritime holding device comprising a shank, arms, and flukes or stock, typically forged from high-tensile carbon steel or cast iron, designed to grip seabed substrates through mechanical penetration and suction to prevent vessel drift. Stockless anchors dominate commercial shipping due to rapid hawsepipe stowage, while composite-material experimental designs are gaining traction in recreational boating for weight reduction. Application demand concentrates in commercial vessels where IMO-mandated redundant anchor systems drive replacement cycles, whereas military vessels sustain premium pricing through specialized high-holding-power specifications.
ISO 4565 and IACS unified requirements govern anchor design validation, while national regulators including China's CCS and South Korea's KR enforce type-approval for domestic fleet registration. The EU's MRV framework indirectly shapes anchor demand by optimizing vessel station-keeping to reduce auxiliary engine emissions during port waiting. Stakeholders must monitor classification society harmonization talks on deep-water anchor performance standards as offshore wind installation vessels expand operational envelopes.

Market Dynamics
Classification societies are tightening holding-power certification standards for deep-water anchors, forcing manufacturers to redesign shank geometries and fluke angles while expanding testing protocols for offshore deployment scenarios.
Growth Catalysts
- Offshore wind installation vessel expansion:Europe's offshore wind buildout requires specialized high-holding-power anchors for jack-up rigs operating in North Sea seabed conditions.
- IMO redundant anchor mandates:Commercial shipping fleets must maintain dual anchor systems, compressing replacement cycles for stockless designs across container and bulk carrier segments.
- China's state-owned shipyard dominance:Concentrated newbuild orders in Jiangsu and Zhejiang provinces are concentrating procurement volumes through domestic supply chains.
Market Restraints
- High-tensile steel price volatility:Carbon steel forging inputs face fluctuating scrap metal and energy costs, squeezing margin structures for anchor chain manufacturers.
- Supply concentration in East China:Captive steel forging capacity clusters around Nantong and Taizhou, creating geographic single-source vulnerability for international buyers.
- Deep-water testing infrastructure scarcity:Limited coastal basins capable of validating 3,000+ meter holding power restrict product development timelines for ultra-deepwater anchors.
Strategic Opportunities
- Composite material recreational penetration:Carbon fiber and glass-reinforced polymer anchors are opening weight-sensitive segments in yacht and superyacht refit markets.
- Aftermarket inspection services:Chain recertification and magnetic particle testing contracts offer recurring revenue streams detached from cyclical newbuild demand.
- EU MRV auxiliary emission optimization:Vessel operators are investing in superior holding systems to minimize engine runtime during port waiting periods.
Industry Challenges
- Certification timeline compression:IACS unified requirement harmonization talks are extending type-approval durations while standards remain in flux.
- Welding technician scarcity:Qualified underwater welders for anchor chain repair and hot work certification are in short supply across Mediterranean and Southeast Asian repair hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Anchor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Stockless, Fluke, Mushroom, Grapnel Material: Steel, Aluminum, Plastic, Composite Application: Commercial Vessels, Recreational Boats, Fishing Boats, Military Vessels Size: Lightweight, Medium, Heavyweight, Extra Heavy |
| Companies Covered | China Shipping Anchor Chain Jiangsu Co. Ltd, Chongqing Hi Sea Marine Equipment Import and Export Co Ltd, Qingdao Anchor Chain Co. Ltd, Powerful Machinery, Lister Chain and Forge Inc, VICINAY Group, Jiangsu Asian Star Anchor Chain Co Ltd, Lewmar, Damen Anchor & Chain Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Anchor Market Strategic Shifts
Digital twin modeling and advanced seabed interaction simulation are compressing design validation cycles while enabling performance predictions across variable substrate compositions.
Finite element analysis coupled with real-time seabed sensor feedback is rendering obsolete traditional empirical design tables that relied on uniform soil assumptions. Offshore wind contractors in the North Sea are adopting these physics-based models for jack-up rig positioning. The shift is compressing insurance premiums and operational downtime for anchor drag incidents.
EU MRV monitoring and reporting requirements are forcing vessel operators to document auxiliary fuel consumption during anchorage periods. This transparency mandate is accelerating investment in high-holding-power systems that reduce engine-dependent station-keeping. Container lines calling at Rotterdam and Hamburg are prioritizing anchor upgrades in their decarbonization roadmaps.
Charterers are bundling anchor condition surveys into pre-fixture vessel inspections, unbundling these services from traditional classification society annual audits. Third-party inspection firms in Singapore and Dubai are capturing this disintermediated demand. The practice is most pronounced in tanker and LNG carrier segments where port state control detention risk carries severe commercial penalties.
Ship Anchor Market Segmentation

Ship anchor procurement cycles vary dramatically across vessel types and operational profiles. Replacement intervals compress under redundant anchor mandates for commercial fleets while military specifications extend product lifecycles through premium material requirements.
Type:
Stockless designs turn over fastest due to commercial fleet replacement mandates, while specialized offshore configurations operate on decade-plus cycles tied to rig mobilization schedules.
- Stockless:The shank-arm-fluke assembly lacks a fixed stock, enabling rapid hawsepipe stowage essential for container ships and bulk carriers. Jiangsu and Zhejiang shipyards concentrate procurement for newbuild Panamax and Capesize vessels under China's state-owned order book expansion.
- Fluke:Broad triangular plates maximize holding power in sand and mud substrates through deep penetration. North Sea offshore wind jack-up rigs drive specification tightening as classification societies validate 3,000-meter performance envelopes.
- Mushroom:Hemispherical head design relies on suction and burial for permanent moorings in soft seabed conditions. Permanent buoy installations and aquaculture cage systems sustain steady demand.
- Grapnel:Multiple hooked arms snag rocky or coral substrates where penetration anchors fail. Salvage operations and small craft emergency kits represent primary end-uses.
Stockless anchors anchor the volume base while fluke designs gain share at the steepest rate on offshore wind installation demand.
Material:
Cost tiers separate forged steel commodity supply from lightweight premium alternatives where fuel savings justify unit price premiums.
- Steel:High-tensile carbon steel forgings dominate commercial shipping through IACS-compliant shank and fluke castings. Nantong and Taizhou captive forging clusters supply international classification society type-approved chains and anchors.
- Aluminum:Corrosion-resistant alloys reduce topside handling weight for manual deployment on smaller vessels. Recreational sailing yacht manufacturers specify aluminum for windlass compatibility.
- Plastic:Molded polymer constructions serve temporary mooring and marker buoy applications where holding loads remain minimal.
- Composite:Carbon fiber and glass-reinforced polymer matrices cut deployed weight by 60-70 percent versus steel equivalents. Superyacht refit markets in Mediterranean and Caribbean marinas absorb premium pricing for performance sailing vessels.
Steel retains the installed base while composite materials climb the fastest on weight-reduction specifications in recreational segments.
Application:
Customer procurement authority concentrates with fleet technical managers in commercial shipping, while military buyers operate through defense procurement agencies with multi-year tender cycles.
- Commercial Vessels:Container lines, bulk carriers, and tankers operate under IMO-mandated dual anchor redundancy. Rotterdam and Hamburg port waiting optimization under EU MRV drives holding-power upgrade investments.
- Recreational Boats:Yacht and superyacht owners prioritize weight reduction and aesthetic finish over absolute holding capacity. Mediterranean and Caribbean charter fleets sustain seasonal replacement demand.
- Fishing Boats:Small-scale coastal operations and industrial trawlers require rapid deployment reliability in varying substrates. Southeast Asian and West African fleet modernization programs concentrate procurement.
- Military Vessels:Naval specifications demand specialized high-holding-power designs with mine-avoidance and stealth-compatible signatures. NATO and Pacific Rim naval procurement operates through national defense agencies.
Commercial vessels anchor the volume base while military vessels gain share at the steepest rate on specialized specification premiums.
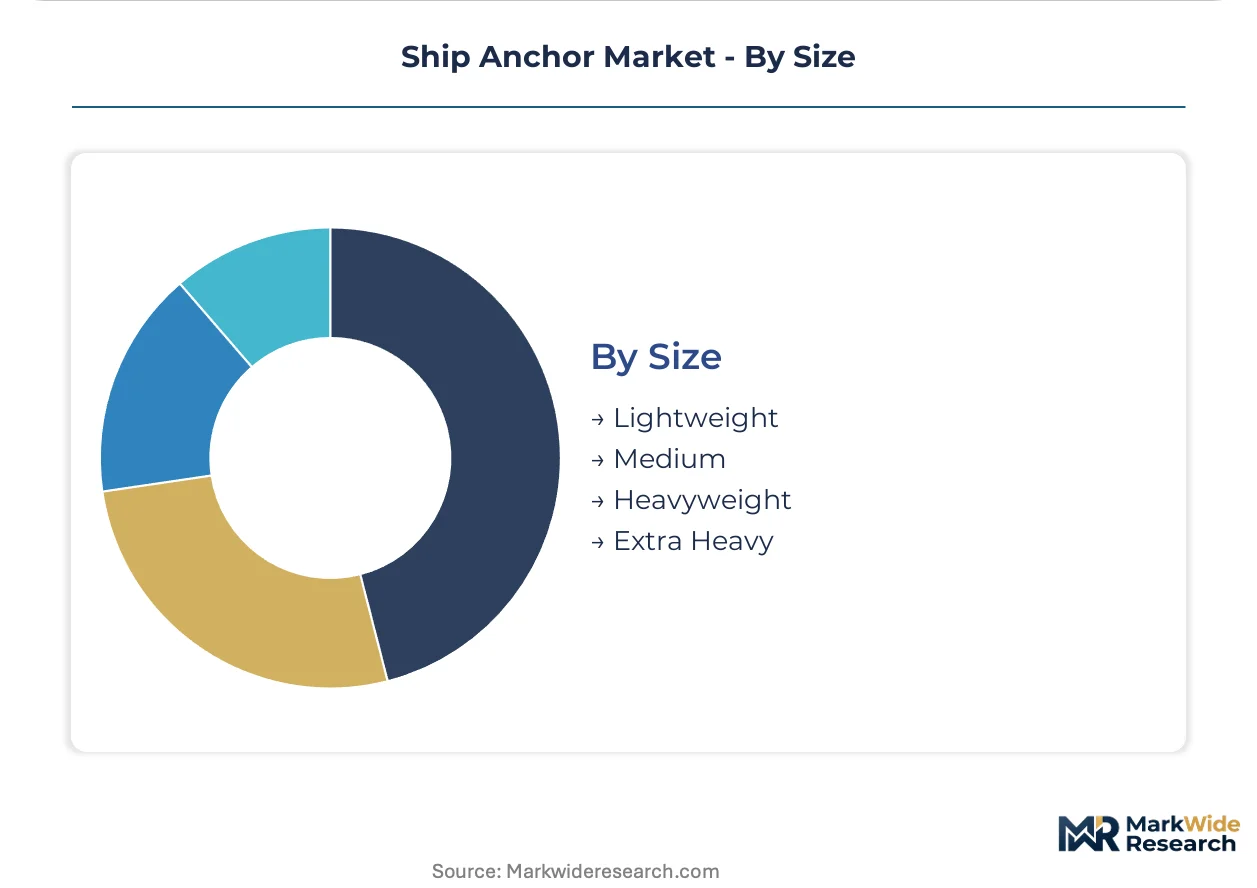
Size:
Volume distribution inverts from fleet composition: lightweight units outnumber heavy units but heavyweight anchors concentrate revenue through material intensity and certification complexity.
- Lightweight:Manual deployment designs under 50 kilograms serve dinghies, personal watercraft, and emergency kits. Recreational retail channels and marine chandleries distribute high volumes at thin margins.
- Medium:Windlass-compatible specifications from 50-500 kilograms dominate coastal and short-sea shipping. European and North American inland waterway fleets sustain steady replacement.
- Heavyweight:500-2,000 kilogram forged assemblies anchor deep-sea commercial vessels and offshore support craft. Classification society witnessing and proof loading extend lead times.
- Extra Heavy:Specialized units exceeding 2,000 kilograms moor floating production platforms and drilling rigs. Ultra-deepwater testing infrastructure scarcity limits supplier participation.
Medium sizes anchor the volume base while extra heavy units gain share at the steepest rate on offshore oil and gas platform deployment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: commercial fleets in East Asia prioritize high-volume stockless procurement under redundant anchor mandates, while European operators optimize for emissions-compliant station-keeping under environmental reporting frameworks.
China
State-owned shipyards in Jiangsu and Zhejiang provinces concentrate newbuild orders for Panamax and Capesize vessels. MIIT and CCS enforce domestic type-approval requirements that favor captive steel forging supply chains. Nantong and Taizhou anchor manufacturing clusters supply international classification society-certified chains through integrated forging capacity.
South Korea
KR certification standards drive specialized high-holding-power demand for LNG carriers and container vessels. The national shipbuilding support program channels procurement toward domestic anchor chain fabricators. Busan-Ulsan industrial corridor houses testing infrastructure for deep-water performance validation.
Germany
EU MRV monitoring requirements accelerate holding-power upgrades among container lines calling at Hamburg and Bremerhaven. ECHA chemical regulations and REACH compliance shape coating and material specifications for anchor chains. North Rhine-Westphalia steel fabrication centers supply windlass-compatible assemblies for European inland waterway fleets.
United States
Coast Guard regulations and ABS classification requirements govern commercial fleet anchor redundancy compliance. EPA emissions standards indirectly shape auxiliary engine runtime optimization during port waiting. Gulf Coast offshore support vessel operators in Texas and Louisiana drive demand for ultra-heavyweight platform mooring systems.
Spain
Naval procurement through the Ministry of Defense sustains premium pricing for specialized high-holding-power designs. CE marking and EU procurement directives standardize technical specifications for NATO-compatible vessels. Basque Country manufacturing heritage supports Mediterranean fleet aftermarket service networks.
Ship Anchor Market Competitive Environment
Capability concentration sits with specialized forging operations possessing captive heat-treatment and proof-loading infrastructure; scale advantage sits with integrated steel producers leveraging backward integration into raw material supply. The market structures around three tiers: naval-specialist premium fabricators, commercial fleet volume suppliers, and recreational segment lightweight specialists. Consolidation pressure concentrates among East Asian forging clusters where capacity expansion and certification harmonization represent dominant competitive vectors.
Among Spanish and Chinese maritime equipment groups, VICINAY Group and Jiangsu Asian Star Anchor Chain Co Ltd exemplify contrasting geographic anchoring strategies for Mediterranean naval and East Asian commercial procurement respectively. Lister Chain and Forge Inc occupies a position within North American inland waterway specialization. These three entities represent distinct archetypes: European naval heritage fabrication, integrated East Asian steel-forging scale, and regional stockless design adaptation.
| Leading Market Players |
|---|
| China Shipping Anchor Chain Jiangsu Co. Ltd |
| Chongqing Hi Sea Marine Equipment Import and Export Co Ltd |
| Qingdao Anchor Chain Co. Ltd |
| Powerful Machinery |
| Lister Chain and Forge Inc |
| VICINAY Group |
| Jiangsu Asian Star Anchor Chain Co Ltd |
| Lewmar |
| Damen Anchor & Chain Factory |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on East China forging clusters determines both pricing tier spreads and supply chain shape, compressing margins for international buyers while amplifying regional procurement advantages for domestic fleet operators.
Pricing Analysis
Long-term offtake contracts dominate anchor procurement for state-owned shipyards in Jiangsu and Zhejiang provinces, while spot purchasing persists for aftermarket replacement orders. Price differentiation rests on IACS certification grade and captive steel forging integration, with fully integrated producers commanding premium positioning over merchant buyers. Cost compression in standard stockless designs is intensifying because scrap metal and energy input volatility squeeze forging margins. Container lines and bulk carriers exhibit highest price sensitivity due to fleet-scale procurement volumes, whereas naval defense agencies remain least sensitive given mission-critical performance specifications.
Supply Chain Analysis
Scrap metal and high-tensile carbon steel feedstock availability centers on Nantong and Taizhou integrated forging complexes, with secondary processing clusters in South Korea and Spain. Raw material dependencies include marine-grade steel billets, heat-treatment alloys, and classification society witnessing services. Single-source vulnerability concentrates in 3,000-meter proof-loading infrastructure scarcity, limiting ultra-deepwater anchor development participation. Distribution runs through shipyard direct procurement for newbuilds and specialized marine equipment distributors for aftermarket refit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified underwater welders for anchor chain repair and hot work certification represent the critical skill gap constraining aftermarket service expansion, creating asymmetric returns for operators who solve this bottleneck.
For Market Incumbents: Build certification moats through accelerated IACS unified requirement compliance investment before harmonization talks conclude. Defensive moves should concentrate on backward integration into heat-treatment infrastructure in Taizhou and magnetic particle testing capacity expansion in Singapore. Composite material substitution in recreational segments poses the primary substitute technology threat requiring monitoring. For New Entrants and Emerging Players: Establish a beachhead in Mediterranean superyacht refit markets where carbon fiber anchor demand outstrips specialized supply. White-space targets include third-party inspection services disintermediated from classification society annual audits, and EU MRV-driven holding-power upgrade programs at Rotterdam and Hamburg. Go-to-market positioning should emphasize rapid magnetic particle testing turnaround versus incumbent scheduling backlogs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated forging operations with captive proof-loading infrastructure. Long-term viability favors asset-heavy specialists over merchant assemblers given certification timeline extension trends. Acquisition target archetypes include East Asian forging clusters with KR or CCS type-approval breadth. The signal to watch is offshore wind jack-up rig mobilization schedules as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forging Capacity Expansion | Nantong and Taizhou clusters strengthen supply security for state-owned shipyard order books. |
| Composite Material R&D Partnership | Carbon fiber development opens Mediterranean and Caribbean superyacht refit market access. |
| Third-Party Inspection Service Launch | Singapore and Dubai-based firms capture disintermediated charterer survey demand from classification societies. |
| Deep-Water Testing Infrastructure Investment | Busan-Ulsan corridor facilities enable 3,000-meter performance validation for offshore wind contractors. |
| EU MRV Compliance Service Bundling | Rotterdam and Hamburg port operators integrate anchor upgrades into vessel decarbonization roadmaps. |
Study Parameters
The analysis maps stockless anchor procurement, fluke design specification, and composite material penetration segments, each validated through fleet technical managers, classification society surveyors, and shipyard procurement officers. Primary interviews with anchor chain manufacturers, heat-treatment facility operators, and underwater welding contractors combined with secondary validation from IACS unified requirement documentation, CCS type-approval registries, and EU MRV monitoring reports. Bottom-up vessel fleet composition analysis and top-down steel forging capacity assessment enabled triangulation across independent estimation approaches.
Assumptions held fixed include IMO redundant anchor mandate enforcement intensity and classification society harmonization timeline trajectories, while offshore wind installation vessel deployment schedules and high-tensile steel price volatility were varied across sensitivity scenarios. Segmentation dimensions modeled encompass anchor type, material grade, vessel application, and weight class across the projection horizon. CAGRs derived from vessel newbuild order book analysis and replacement cycle compression factors, with offshore platform mooring specifications and naval procurement tender cycles as industry-specific forecast inputs.
Sensitivities concentrate around scrap metal price volatility, IACS harmonization timeline delays, and deep-water testing infrastructure development pace. Forecasts reflect assumptions regarding state-owned shipyard order concentration and EU emissions framework enforcement intensity. Cross-checking against Lloyd's List vessel order book data and KR certification issuance statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Drill Ships Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Europe Inland Water Freight Transport Market